
 Whole Grain Drinks Market | 2026-2036
Whole Grain Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Whole Grain Drinks Market Analytics
Supermarket shelf allocation for plant-based beverages is tilting toward whole grain formats as retailers expand dedicated alternative-dairy sections. Nestle leverages its dairy-alternative infrastructure to secure refrigerated placement in mass-market chains. General Mills, Inc. competes through in-house milling operations that anchor its supply of oat-based inputs. Danone S.A. differentiates with fermentation expertise adapted from its traditional yogurt business.
Whole grain drinks comprise beverages manufactured from intact or minimally processed cereal grains, typically containing beta-glucan fiber at concentrations of one to three grams per serving, produced through enzymatic hydrolysis or aqueous extraction to achieve suspension stability and palatable viscosity. These formulations serve commercial purposes ranging from lactose-intolerance accommodation to cardiovascular health positioning in functional nutrition portfolios. Oat milk dominates volume within product type segments due to its barista-compatible foaming properties and neutral flavor profile, while quinoa drink occupies the fastest-growing niche as Andean sourcing narratives attract premium positioning. Health food stores and specialty shops capture margin concentration among distribution channels, though online retail extends reach into rural and subscription-based consumption patterns.
The FDA governs whole grain health claims through its qualified claim framework for beta-glucan and coronary heart disease risk, while the USDA Organic seal shapes premium tier access and pricing power. EFSA evaluates novel food applications for emerging grain sources such as quinoa drink formulations entering European markets. Stakeholders must monitor evolving fiber fortification thresholds as regulators recalibrate permitted health messaging across jurisdictions.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal and F-Gas Regulation are compressing processing margins while forcing capital redeployment toward enzymatic hydrolysis equipment. These regulatory pressures intersect with retailer shelf-space reallocation to reshape competitive positioning across the value chain.
Growth Catalysts
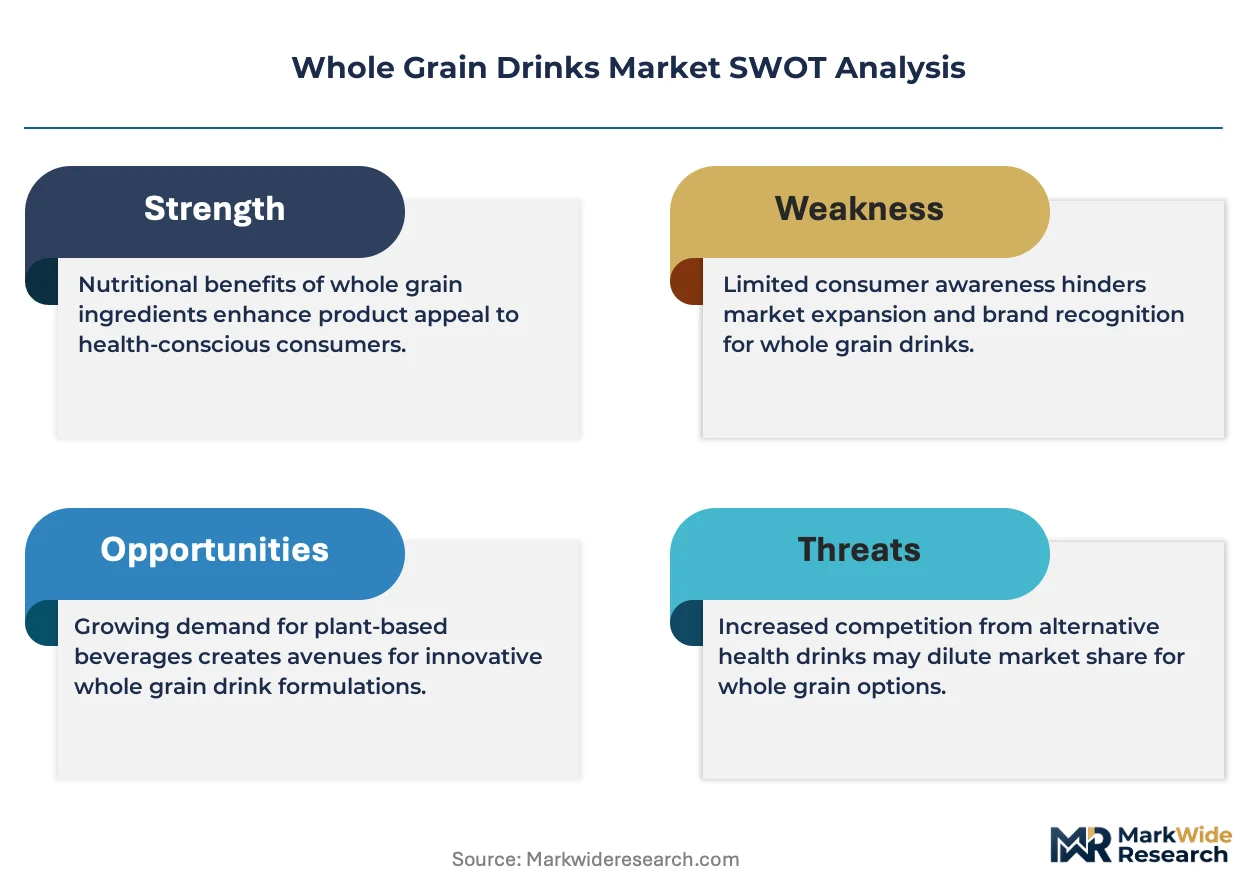
- Beta-glucan health claims:The FDA's qualified claim framework for coronary heart disease risk reduction drives cardiovascular positioning in functional nutrition portfolios. Beverage manufacturers leverage this regulatory pathway to capture health-conscious consumers in retail channels.
- Barista-grade foaming:Oat milk's neutral flavor profile and steam-compatible viscosity properties accelerate adoption in specialty coffee shops. Coffee chains expand dedicated alternative-dairy sections to accommodate this demand.
- EU Green Deal processing standards:The regulation's emissions thresholds push manufacturers toward aqueous extraction methods. European facilities retrofit enzymatic hydrolysis lines to maintain market access.
Market Restraints
- Grain input volatility:Oat and quinoa commodity prices fluctuate with climate-induced harvest variability. Nordic and Andean sourcing regions experience weather-driven supply disruptions.
- Enzyme supply concentration:Industrial enzyme production for hydrolysis concentrates among Danish and Dutch specialty chemical suppliers. This geographic concentration creates procurement bottlenecks during demand surges.
- Shelf-stability limitations:Minimal processing requirements compromise ambient distribution reach. Refrigerated cold-chain dependency restricts rural market penetration.
Strategic Opportunities
- Quinoa drink premiumization:Andean sourcing narratives attract functional beverage positioning in German health food stores. Indigenous grain provenance commands price premiums over commodity oat formulations.
- Online subscription channels:Direct-to-consumer models bypass refrigerated retail shelf constraints. Rural consumers access whole grain drinks through temperature-controlled logistics networks.
- EFSA novel food approvals:Emerging grain sources await regulatory clearance for European market entry. Quinoa drink formulations currently under evaluation will unlock formulation diversification.
Industry Challenges
- Clean-label formulation expertise:Food scientists with enzymatic hydrolysis specialization remain scarce. Manufacturers compete for talent capable of optimizing suspension stability without synthetic additives.
- USDA Organic certification timelines:Multi-year conversion requirements for grain suppliers delay premium tier launches. Supply chain partners struggle to synchronize organic acreage expansion with brand pipeline schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole Grain Drinks Market |
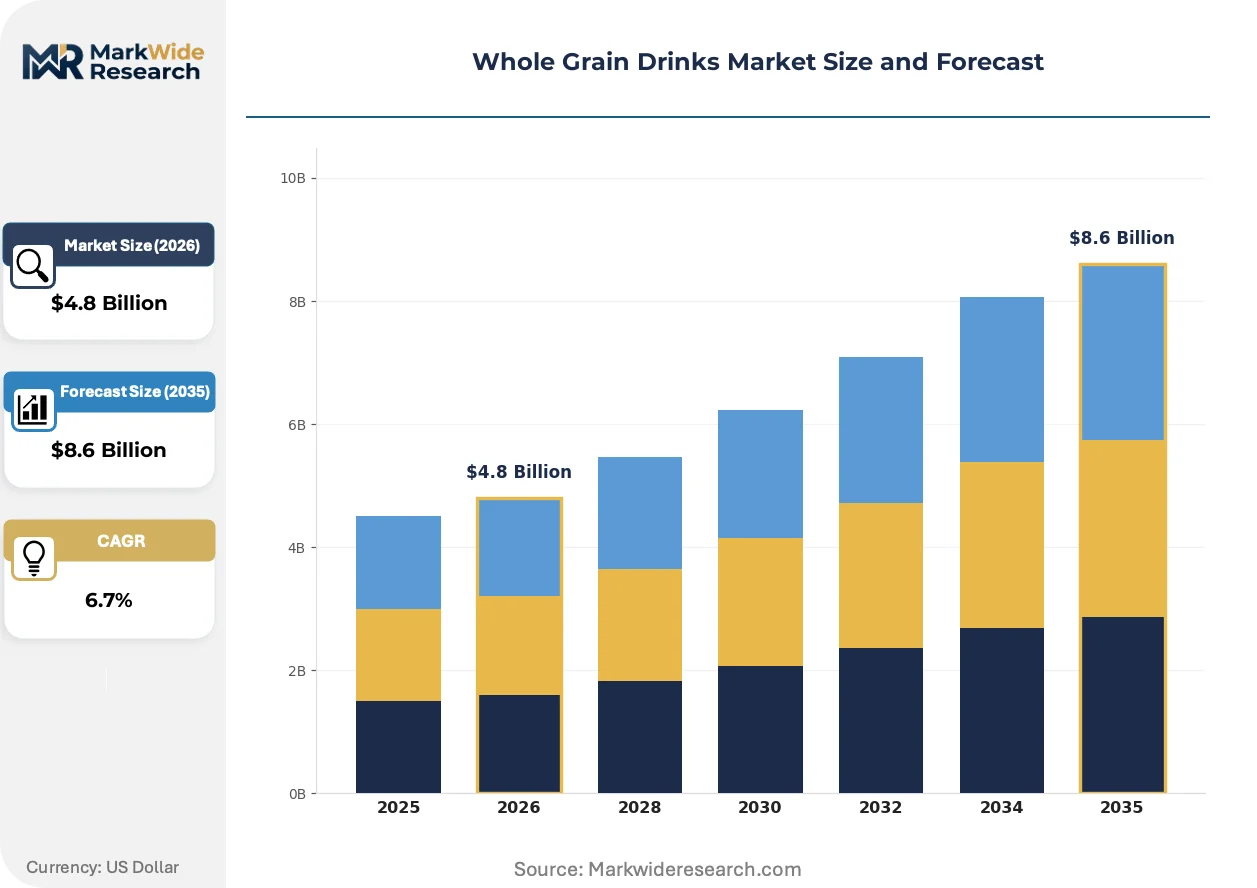
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oat Milk, Barley Water, Rice Milk, Quinoa Drink End User: Health-Conscious Consumers, Athletes, Families, Vegans Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops Packing Type: Cartons, Bottles, Pouches, Cans |
| Companies Covered | Nestle, Campbell Soup, Weiwei Group, Odwalla, Juiceology, NOW Foods, PepsiCo, Inc., Danone S.A., General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole Grain Drinks Market Evolving Landscape
Enzymatic processing advances and regulatory recalibration of fiber fortification thresholds are compressing traditional formulation approaches. These forces converge with shifting procurement behaviors to redefine competitive advantage.
High-pressure homogenization combined with targeted enzyme blends is rendering obsolete conventional heat-treatment methods for achieving oat milk viscosity. Specialty coffee roasters in Berlin and Copenhagen adopt these systems to reduce thermal degradation of beta-glucan content. The technology is rendering obsolete capital-intensive UHT infrastructure that previously dominated shelf-stable production.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants forces cold-chain reconfiguration across European distribution networks. Manufacturers face retrofit costs for transport refrigeration units or risk service interruptions to supermarket clients. German retailers lead compliance timing, pressuring suppliers to accelerate equipment replacement schedules ahead of mandated deadlines.
Subscription-based replenishment models displace traditional supermarket stocking for urban households with predictable consumption patterns. Direct distribution captures margin otherwise surrendered to retail slotting fees. This channel shift concentrates in Scandinavian metropolitan markets where logistics density supports economically viable cold-chain delivery frequencies.
Whole Grain Drinks Market Segmentation
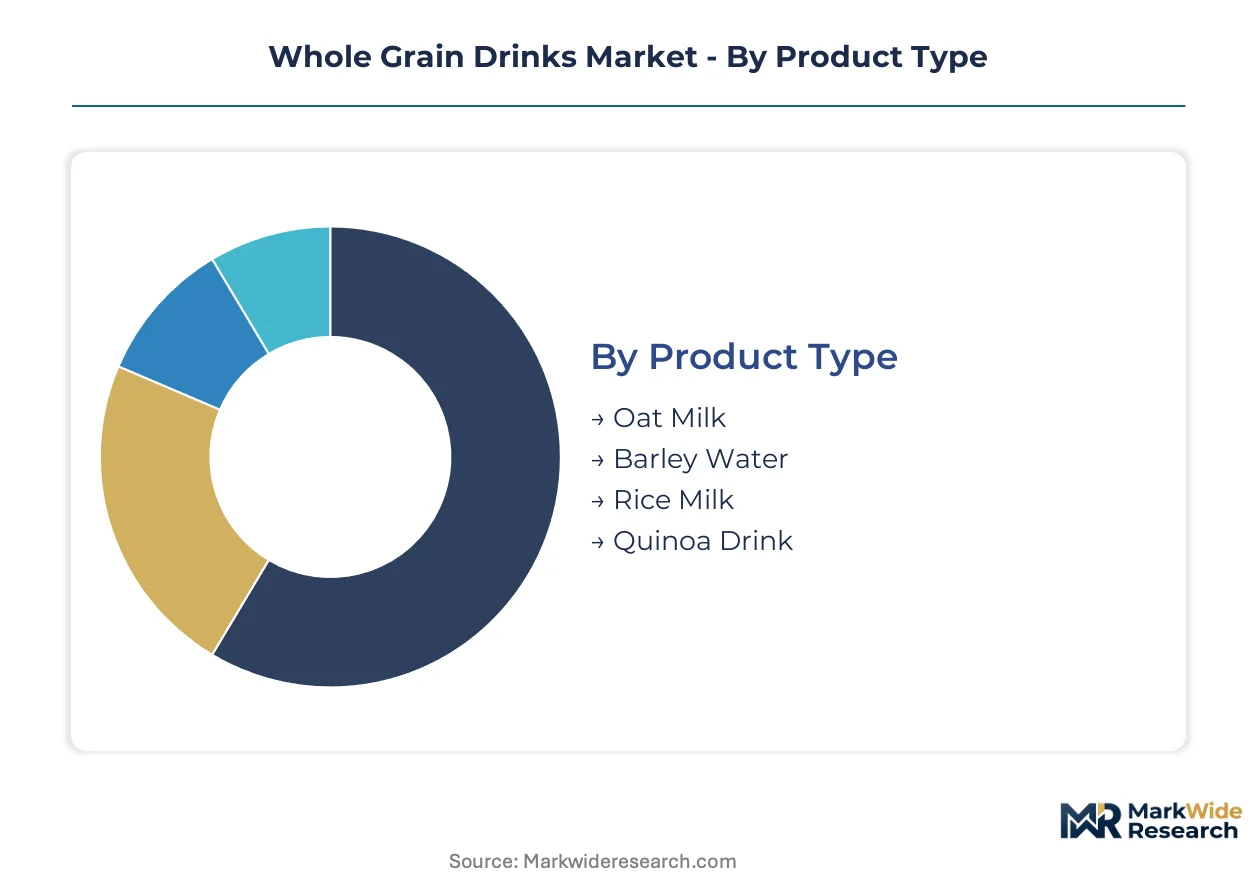
Whole grain drinks manufacturers calibrate formulation, packaging, and channel strategy to distinct consumption occasions and buyer profiles. Segment boundaries blur as barista-grade specifications migrate from specialty shops into mass retail, forcing portfolio architecture decisions.
Product Type:
Mature oat formulations anchor volume while emerging grain sources command premium positioning through provenance narratives.
- Oat Milk:Enzymatic hydrolysis of beta-glucan-rich groats yields barista-compatible viscosity and neutral flavor. German coffee chains drive category volume through dedicated alternative-dairy menu sections and steam-compatible foaming requirements.
- Quinoa Drink:Andean-sourced protein and mineral content supports functional nutrition claims. Health food stores in German metropolitan markets absorb premium pricing for indigenous grain provenance and novel food status under EFSA evaluation.
- Barley Water:Traditional British formulation with lower beta-glucan concentration serves heritage-positioned refreshment segments.
- Rice Milk:Hypoallergenic profile captures allergen-sensitive households seeking dairy and nut-free alternatives.
Oat milk retains volume leadership; quinoa drink holds the steepest expansion curve.
End User:
Application intensity varies from daily nutritional replacement to performance-oriented consumption, reshaping formulation priorities.
- Health-Conscious Consumers:Beta-glucan cardiovascular claims under FDA qualified framework drive repeat purchase in retail channels. Clean-label priorities compress acceptable ingredient lists to grain, water, and enzymatic processing aids.
- Athletes:Post-workout carbohydrate replenishment and plant protein integration guide formulation density. Sports nutrition brands specify higher solids content for satiety and recovery positioning.
- Families:Multi-serve packaging formats and child-friendly flavor masking determine household penetration rates.
- Vegans:Ethical sourcing certifications and B12 fortification requirements shape supplier qualification criteria.
Health-conscious consumers dominate purchase frequency; athletes generate the highest per-unit margin contribution.
Distribution Channel:
Margin capture concentrates in controlled environments while reach extension depends on cold-chain infrastructure investment.
- Supermarkets:Refrigerated shelf reallocation toward dedicated plant-based sections accelerates impulse substitution. German mass-market chains demand slotting fee structures that compress supplier margins in exchange for volume velocity.
- Health Food Stores:Staff-assisted selling environments support premium pricing and emerging grain education. Scandinavian independent retailers maintain curated oat and quinoa assortments with higher service attachment.
- Online Retail:Subscription models bypass refrigerated shelf constraints through temperature-controlled logistics. Direct distribution captures margin surrendered to retail slotting fees in urban consumption clusters.
- Specialty Shops:Coffee roaster partnerships and barista training programs lock in ingredient specification loyalty.
Supermarkets move the highest absolute volume; online retail is climbing the fastest as logistics density improves.
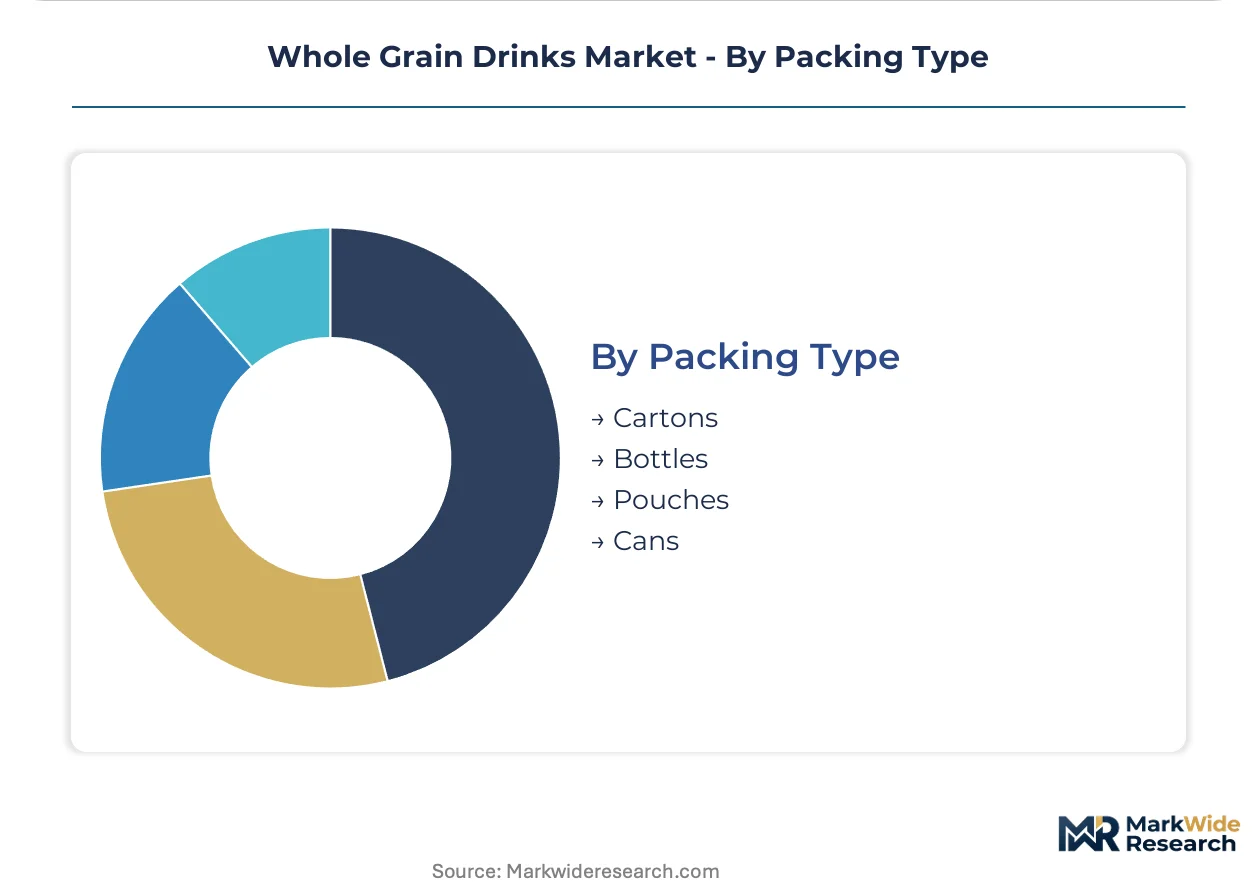
Packing Type:
Supply concentration in aseptic carton manufacturing shapes procurement timelines and sustainability positioning.
- Cartons:Multi-layer aseptic barriers enable ambient distribution with twelve-month shelf stability. Swedish and Finnish packaging equipment suppliers dominate installed base for oat milk producers.
- Bottles:Refrigerated PET and HDPE formats support premium visual differentiation and resealability. German dairy-alternative brands favor bottle formats for on-the-go consumption positioning.
- Pouches:Flexible formats reduce transport cube and material intensity for e-commerce fulfillment.
- Cans:Aluminum formats serve single-serve refreshment occasions and outdoor consumption contexts.
Cartons retain volume leadership; pouches are gaining share fastest through e-commerce channel alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's refrigerated container terminal underwrites Germany's dominance in European whole grain drink distribution, handling enzymatic hydrolysis equipment imports and temperature-sensitive exports across Nordic markets.
Germany
Barista-grade oat milk specifications from Berlin coffee chains drive formulation standards across the continent. The EU F-Gas Regulation forces cold-chain equipment retrofits in Bavarian distribution centers. Hamburg's port infrastructure anchors enzymatic hydrolysis equipment imports serving domestic manufacturers.
United States
FDA qualified health claims for beta-glucan cardiovascular positioning accelerate retail adoption in health-conscious consumer segments. USDA Organic certification requirements shape premium tier supply chain timelines. California's Central Valley oat cultivation clusters support West Coast manufacturing concentration.
France
EFSA novel food evaluation pathways determine quinoa drink market entry timelines for Andean-sourced formulations. The EU Green Deal emissions thresholds push Paris-region facilities toward aqueous extraction retrofits. Lyon-based food technology institutes supply enzymatic processing expertise to domestic brands.
China
Dual carbon goals under MEE guidance reshape processing energy intensity standards for grain beverage manufacturers. SAMR food safety regulations govern beta-glucan content labeling claims. Shanghai's Yangtze River Delta logistics corridor enables cold-chain distribution into premium urban retail.
United Kingdom
Post-Brexit divergence from EU novel food approvals creates separate regulatory pathways for emerging grain sources. Health Canada-aligned cardiovascular health claim frameworks influence domestic positioning strategies. London's specialty coffee density drives barista-grade oat milk specification adoption.
Whole Grain Drinks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in enzymatic supply and organic grain procurement. The vendor base organizes around three strategic archetypes: diversified food conglomerates leveraging dairy-alternative infrastructure, in-house milling operators controlling upstream grain inputs, and fermentation specialists adapting biological processing expertise. Dominant competitive moves include backward integration into captive oat milling capacity and geographic expansion through refrigerated distribution partnerships.
Within the diversified conglomerate tier, Nestle and General Mills, Inc. exemplify platform-scale players, while Danone S.A. occupies a position reflecting fermentation heritage adapted to plant-based categories. Nestle leverages existing dairy-alternative infrastructure for mass-market refrigerated placement. General Mills, Inc. anchors its competitive position through in-house milling operations supplying oat-based inputs. Danone S.A. represents the biological processing specialist archetype, with yogurt-derived fermentation expertise informing whole grain drink formulation approaches.
| Leading Market Players |
|---|
| Nestle |
| Campbell Soup |
| Weiwei Group |
| Odwalla |
| Juiceology |
| NOW Foods |
| PepsiCo, Inc. |
| Danone S.A. |
| General Mills, Inc. |
| Others |
Value Network & Pricing Analysis
Danish and Dutch enzyme suppliers anchor cost structures for hydrolysis-dependent manufacturers, concentrating margin capture in the specialty chemical tier while beverage brands absorb equipment retrofit expenses from EU F-Gas Regulation compliance. This upstream concentration funnels pricing power toward enzymatic input providers and away from finished goods producers competing on refrigerated shelf placement.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between oat milk manufacturers and German supermarket chains, with slotting fee obligations compressing supplier margins in exchange for refrigerated section access. Pricing stratifies across premium, standard, and economy tiers based on USDA Organic certification status and barista-grade viscosity specifications. Cost compression in the standard tier is intensifying as private-label entrants replicate enzymatic processing techniques. Health-conscious consumers in specialty channels exhibit lowest price sensitivity; mass-market families drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between Andean sourcing regions and European processing hubs dominates supply chain risk calculus for quinoa drink formulations awaiting EFSA novel food clearance. Raw material flows draw from Nordic oat cultivation zones, Andean quinoa highlands, and North American organic grain conversion acreage. Industrial enzyme production hinges on Danish and Dutch specialty chemical infrastructure. Single-source vulnerability concentrates in refrigerated transport equipment subject to F-Gas Regulation phasedown timelines. Distribution runs through Hamburg's refrigerated container terminal serving Nordic and German metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision-fermented dairy proteins that replicate mouthfeel without grain-based viscosity requirements. Defense of market position requires structural moves that deepen captive supply control and accelerate certification timelines.
For Market Incumbents: Insulate margin pools through backward integration into captive oat milling capacity in Nordic sourcing regions, eliminating commodity price exposure from climate-driven harvest variability. Accelerate USDA Organic certification pipelines by underwriting multi-year supplier acreage conversion contracts. The precision-fermentation threat from synthetic dairy alternatives demands formulation differentiation through beta-glucan concentration claims that lab-grown proteins cannot replicate.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure in Scandinavian metropolitan clusters where logistics density supports economically viable cold-chain delivery frequencies. Target the quinoa drink segment under EFSA novel food evaluation, where regulatory clearance delays have suppressed incumbent investment. Staff-assisted health food stores in German cities offer the most penetrable channel for premium positioning without slotting fee burdens.
For Investors and Strategic Acquirers: Capital is best deployed toward biological processing specialists with enzymatic hydrolysis expertise and established fermentation infrastructure adaptable to whole grain applications. Long-term viability over the next decade rests on regulatory moats from novel food approvals and organic certification pipelines rather than brand equity alone. The signal to watch is EFSA clearance velocity for Andean-sourced quinoa formulations, which will unlock formulation diversification and premium pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Captive supply from Nordic cultivation zones insulates margin from climate-driven commodity volatility. |
| EFSA Novel Food Approval Pursuit | Regulatory clearance for quinoa drink formulations unlocks premium positioning in German health food channels. |
| Cold-Chain Subscription Infrastructure | Direct distribution in Scandinavian metros captures margin surrendered to supermarket slotting structures. |
| USDA Organic Certification Acceleration | Multi-year supplier underwriting secures premium tier access before competitor pipeline synchronization. |
| Enzymatic Hydrolysis Equipment Retrofit | Aqueous extraction compliance with EU Green Deal emissions thresholds preserves European market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA qualified health claim filings, EFSA novel food application databases, and EU F-Gas Regulation implementation timelines. Input gathered from enzymatic processing specialists, refrigerated logistics operators, health food store category buyers, and supermarket procurement managers in German and Scandinavian markets. Trade data from Hamburg port customs records and Nordic grain cultivation statistics provided supply-side validation. Bottom-up volume modeling triangulated against top-down category expenditure estimates from retail audit sources.
Forecast inputs include grain commodity price trajectories, regulatory approval velocity for novel food categories, cold-chain infrastructure investment cycles, and enzymatic equipment replacement schedules across European manufacturing facilities. Segmentation dimensions span product type, end-user application intensity, distribution channel control level, and packaging format sustainability positioning. CAGRs derived from curve-fitting approaches calibrated to historical substitution rates between dairy and plant-based alternatives. Beta-glucan fortification threshold evolution and organic acreage expansion timelines shaped projection boundaries.
Stress conditions across Andean harvest variability, enzyme supplier concentration disruption, and F-Gas Regulation compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EFSA evaluation timelines and EU Green Deal enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Aloe Vera Drinks Market
Beverages
Pineapple Juice Market
Beverages
Hydrogen Water Bottle Market
Beverages
Hot Cocoa Mix Market
Beverages
Blackstrap Molasses Market
Beverages
Europe Probiotic Drinks Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Carbonate Drink Maker Market
Beverages
Commercial Drink Mixers Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Fruit Water Market
Beverages
Indonesia Bottled Water Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Semillon Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Packaged Coconut Water Market