

Custom Supplement Formulation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Supplement Formulation Service Market Insights
Capital-intensity divergence between in-house analytical laboratories and third-party testing dependencies is redrawing competitive tiers among formulation service providers. Natural Alternatives International leverages vertically integrated manufacturing campuses in California to control batch consistency from raw material qualification through finished goods release. Supplement Factory anchors its position through dedicated softgel and gummy production lines that serve European private label brands seeking novel delivery formats. Vitaquest competes by sustaining dual-site US operations that reduce geographic risk for clients with coast-to-coast distribution requirements.
Custom supplement formulation service encompasses the contract development and manufacturing of bespoke dietary supplement compositions, encompassing active ingredient sourcing, excipient selection, stability testing, and finished dosage form production according to client-specified therapeutic or nutritional targets. The process typically involves dissolution profiling, heavy metal screening, and microbial validation to ensure batch-to-batch reproducibility for commercial sale. Protein blends and amino acids command premium formulation fees due to complex flavor masking requirements and hygroscopic handling challenges during tableting operations. Softgel and gummy delivery formats attract disproportionate development pipeline investment as consumer preference shifts away from traditional capsule regimens toward palatable, portable dosing experiences.
FDA cGMP regulations under 21 CFR Part 111 mandate master manufacturing records and supplier qualification protocols that shape service provider infrastructure investments. NSF International certification and USP verification programs function as de facto market access requirements for brands targeting practitioner and retail pharmacy channels. Stakeholders must monitor evolving FDA enforcement discretion on new dietary ingredient notifications and structure-function claim substantiation as these determinations directly affect formulation feasibility and commercialization timelines for novel botanical and synthetic compounds.
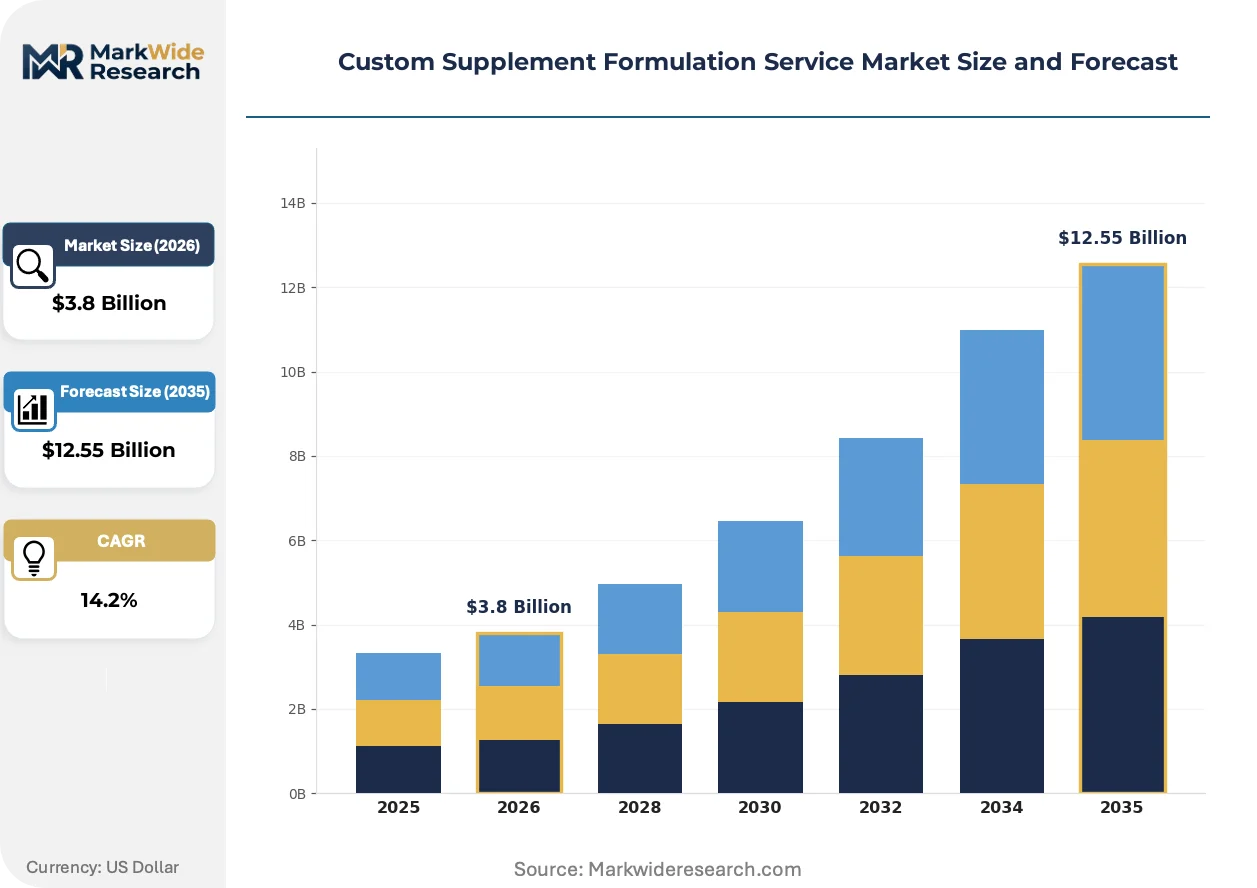
Market Dynamics
Personalized nutrition protocols are fragmenting batch economics as sports nutrition brands demand smaller production runs with rapid reformulation cycles. Formulation service providers must reconfigure fixed-cost manufacturing assets to serve lot sizes that previously fell below minimum efficient scale.
Growth Catalysts
- Practitioner channel expansion:Functional medicine clinics and registered dietitians now prescribe condition-specific supplement stacks. NSF certification requirements filter qualified suppliers into these high-margin distribution channels.
- 21 CFR Part 111 enforcement:FDA cGMP compliance mandates drive brand owners toward contract manufacturers with validated quality systems rather than building captive facilities.
- Softgel format preference:Consumer rejection of capsule regimens accelerates gummy and liquid-filled softgel development pipelines. European private label brands commission novel delivery formats to differentiate shelf presence.
Market Restraints
- Specialized excipient supply:Hydroxypropyl methylcellulose and modified starch suppliers concentrate in Germany and the Netherlands. Regional supply disruptions cascade into formulation delays for vegetarian capsule alternatives.
- NDI notification burden:FDA new dietary ingredient pre-market notifications extend commercialization timelines for novel botanical extracts. Brand owners abandon innovative compounds in favor of grandfathered ingredients with established safety profiles.
- Analytical equipment capex:In-house inductively coupled plasma mass spectrometry and high-performance liquid chromatography systems require seven-figure capital commitments. Smaller contract manufacturers remain dependent on third-party testing laboratories with extended turnaround times.
Strategic Opportunities
- India export manufacturing:CDSCO manufacturing license harmonization with WHO GMP standards positions Indian contract manufacturers for North American and European brand outsourcing. Labor arbitrage in analytical chemistry and quality assurance functions compresses per-batch costs.
- Biometric-integrated protocols:Continuous glucose monitors and microbiome testing kits enable real-time supplement adjustment algorithms. Formulation services that integrate with wearable data platforms capture recurring reformulation revenue streams.
- Clean label certification stacking:Non-GMO Project verification, NSF Certified for Sport, and USP verification function as de facto market access requirements. Service providers offering bundled certification management reduce client administrative burden.
Industry Challenges
- Flavor masking chemistry:Protein and amino acid formulations require sophisticated bitter blocker and sweetness modulation expertise. Formulation chemists with sensory science cross-training command compensation premiums that compress service margins.
- Master batch record reconciliation:Client-specified ingredient substitutions trigger FDA cGMP documentation updates across manufacturing, quality, and regulatory departments. Revision control systems strain under frequent custom formulation iterations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Supplement Formulation Service Market Trends and Innovations
Digital formulation platforms are compressing development cycles as algorithmic ingredient compatibility screening replaces empirical bench testing. Service providers that integrate artificial intelligence into excipient selection and stability prediction capture premium development fees.
Artificial intelligence-powered formulation software is displacing traditional trial-and-error bench development. Mid-sized contract manufacturers deploy machine learning models trained on historical stability datasets to predict shelf-life outcomes. Sports nutrition brands adopting these platforms compress six-month development timelines into eight-week cycles.
REACH regulation amendments on novel chemical substance registration are tightening excipient sourcing protocols for European-bound formulations. ECHA compliance requirements cascade into supplier qualification audits and documentation burdens. Softgel and gummy manufacturers reformulating with natural colorants face substitution pressures as synthetic dye approvals narrow.
Direct-to-consumer subscription models are reshaping procurement patterns as brands demand just-in-time manufacturing rather than inventory-heavy batch production. Formulation service providers reconfigure production scheduling around weekly replenishment cycles rather than quarterly stock builds. United States-based contract manufacturers with flexible line changeover capabilities capture volume from brands abandoning Asian manufacturing partners with longer lead times.
Custom Supplement Formulation Service Market Segmentation
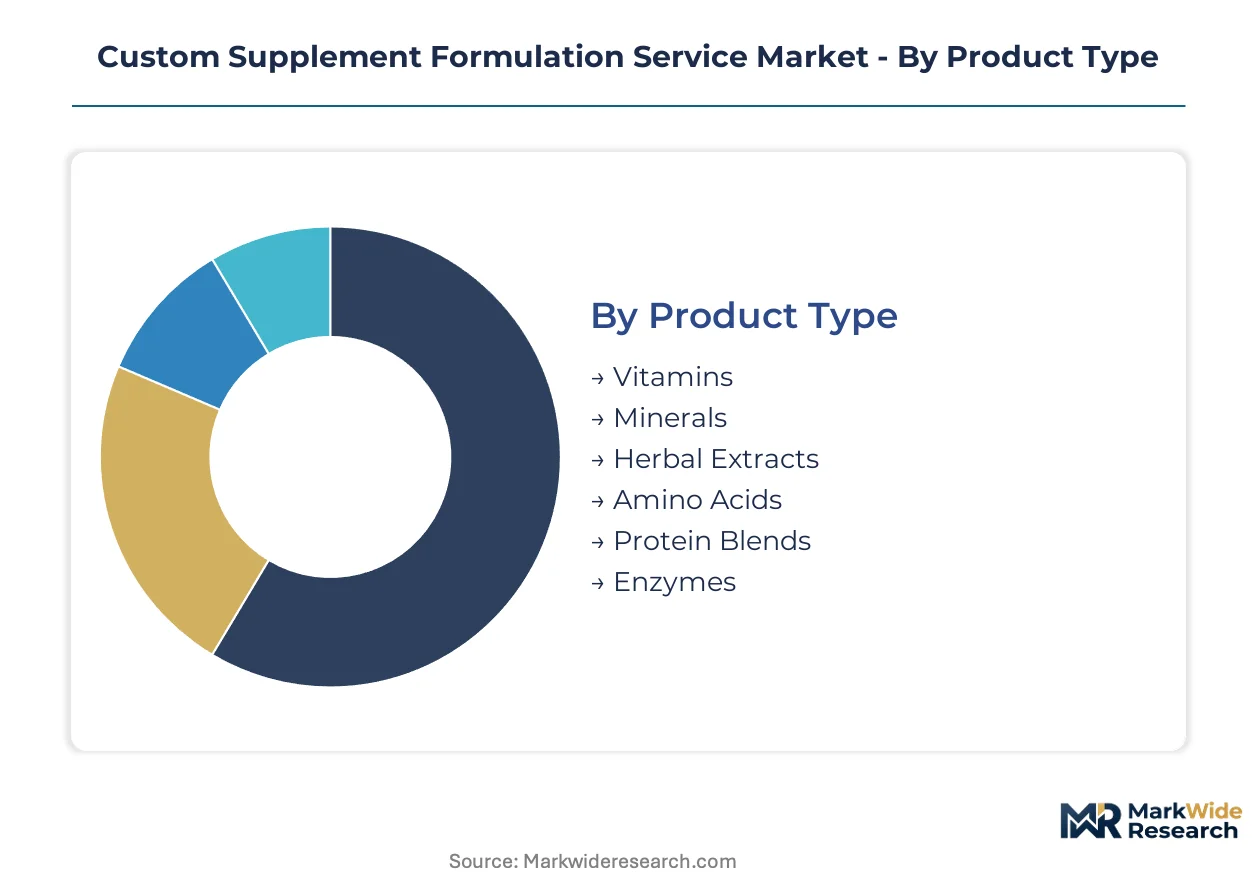
Segmentation in custom supplement formulation services determines which service providers capture volume versus margin. Product chemistry complexity and delivery format capital requirements create divergent competitive moats across category boundaries.
Product Type:
Substitution pressure intensifies around commodity ingredient categories where standardized specifications erode formulation service differentiation.
- Vitamins:Fat-soluble and water-soluble vitamin premixes require stability testing for oxidation and photodegradation. Demand concentrates among private label brands in the United States seeking USP-verified potency claims for retail pharmacy placement.
- Minerals:Chelated and inorganic mineral forms necessitate dissolution profiling and bioavailability validation. Sports nutrition brands in the United States commission mineral stacks for electrolyte replacement protocols, driving chelated magnesium and zinc formulation volumes.
- Herbal Extracts:Standardized botanical compounds face FDA new dietary ingredient notification requirements that extend development timelines.
- Amino Acids:Branched-chain and essential amino acid blends command premium formulation fees due to hygroscopic handling and bitter taste masking complexity.
- Protein Blends:Whey, casein, and plant-based protein formulations require sophisticated flavor systems and texture optimization for palatability.
- Enzymes:Protease, lipase, and amylase blends need activity unit standardization and enteric coating for gastric survival.
Vitamins anchor the volume base while protein blends gain share at the steepest rate.
Application:
Margin tiering follows clinical validation depth, with practitioner-prescribed stacks commanding premium pricing over discretionary wellness categories.
- Sports Nutrition:Pre-workout, intra-workout, and recovery formulations require rapid dissolution and gastric tolerance for high-frequency dosing. Professional athlete demand in the United States drives NSF Certified for Sport requirements that filter qualified suppliers.
- Cognitive Enhancement:Nootropic stacks combining racetams, choline sources, and adaptogens face regulatory scrutiny under FDA structure-function claim guidelines. Wellness clinics in the United States prescribe condition-specific cognitive protocols, creating recurring formulation revenue.
- Immune Support:Elderberry, echinacea, and zinc combinations experience seasonal demand volatility that strains production scheduling.
- Weight Management:Thermogenic and appetite suppressant formulations confront shifting FDA enforcement discretion on ingredient safety.
- Digestive Health:Probiotic and prebiotic synbiotics require strain-specific viability testing and refrigerated supply chain validation.
- Anti-Aging:NAD+ precursors and collagen peptides attract development pipeline investment from direct-to-consumer brands targeting affluent demographics.
Sports Nutrition anchors the volume base while Cognitive Enhancement climbs the fastest as practitioner channel penetration deepens.
Delivery Format:
Capital intensity stratifies competitive tiers, with softgel and gummy lines requiring seven-figure equipment commitments that exclude smaller contract manufacturers.
- Capsules:Hard-shell gelatin and vegetarian capsules remain the default format for clinical trial materials and practitioner protocols. Health practitioners in the United States prefer capsule dosing for precise titration and ingredient isolation.
- Tablets:Direct compression and wet granulation tablet presses handle high-volume mineral and vitamin production. Nutraceutical companies in the United States commission coated tablets for shelf stability and swallowability in mass retail channels.
- Powders:Bulk protein and pre-workout blends require flavor masking and instantization technology for mixability.
- Liquids:Liposomal and emulsion delivery systems enhance bioavailability for fat-soluble nutrients.
- Gummies:Pectin and gelatin-based gummy deposition demands specialized starch molding equipment and moisture control.
- Softgels:Rotary die encapsulation enables liquid-filled and suspension formulations for oil-soluble actives.
Capsules anchor the volume base while Gummies expand most quickly as consumer preference shifts away from pill fatigue.
End User:
Customer type determines certification requirements and batch size economics, fragmenting service provider specialization across channel boundaries.
- Health Practitioners:Functional medicine physicians and naturopaths prescribe condition-specific stacks with ingredient transparency requirements. Wellness clinics in the United States demand master batch records with lot-level Certificates of Analysis for liability protection.
- Dietitians:Registered dietitians recommend targeted micronutrient protocols based on laboratory testing integration. Fitness centers in the United States partner with dietitians for member retention through personalized supplementation.
- Fitness Centers:Gym-branded supplement lines require rapid turnaround on flavor iterations and seasonal limited editions.
- Wellness Clinics:Integrative health facilities combine supplement dispensing with diagnostic services for recurring revenue.
- Private Label Brands:Direct-to-consumer startups demand low minimum order quantities and rapid formulation pivots.
- Nutraceutical Companies:Established brands leverage contract manufacturing for capacity expansion and geographic redundancy.
Private Label Brands anchor the volume base while Health Practitioners gain share fastest as functional medicine adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while contract manufacturing arbitrage draws European brands toward Indian production campuses. Formulation service margins diverge sharply between FDA-cGMP-certified domestic facilities and emerging WHO-GMP-aligned export hubs.
United States
Direct-to-consumer supplement brands and functional medicine clinics drive formulation volumes across California and New York clusters. FDA 21 CFR Part 111 enforcement tightens quality system requirements, filtering qualified contract manufacturers into practitioner and retail pharmacy channels. Southern California hosts vertically integrated manufacturing campuses where batch consistency controls extend from raw material qualification through finished goods release.
Germany
Specialized excipient suppliers in Germany and the Netherlands anchor European vegetarian capsule production for clean-label brands. ECHA REACH compliance requirements cascade into supplier qualification audits and documentation burdens for botanical extract formulations. Bavaria-based softgel manufacturers reformulate with natural colorants as synthetic dye approvals narrow under amended chemical substance regulations.
India
CDSCO manufacturing license harmonization with WHO GMP standards positions Indian contract manufacturers for North American and European brand outsourcing. Labor arbitrage in analytical chemistry and quality assurance functions compresses per-batch costs for protein blend and amino acid formulations. Hyderabad and Mumbai clusters attract formulation development contracts from sports nutrition brands seeking geographic redundancy.
United Kingdom
Private label brands and wellness clinics in Greater London commission novel delivery formats including gummy and liquid-filled softgel alternatives. MHRA guidance on novel food and supplement classifications shapes formulation feasibility assessments for botanical and synthetic compounds. Southeast England manufacturing facilities serve European distribution requirements while navigating post-Brexit regulatory divergence.
China
NMPA dietary supplement registration requirements and GB standards compliance shape formulation service capabilities for domestic and export markets. Yangtze River Delta manufacturing clusters specialize in tablet and capsule production for mineral and vitamin premixes. SAMR enforcement on health food claims and dual carbon goals influence excipient sourcing and packaging material selections.
Custom Supplement Formulation Service Market Competitive Landscape
Concentration sits with vertically integrated specialists controlling analytical laboratories and certified manufacturing campuses. The vendor base stratifies across three tiers: full-service providers with dual-site operations, format specialists concentrating on softgel or gummy production, and regional contract manufacturers dependent on third-party testing. Dominant competitive moves include certification stacking for market access and capacity expansion into flexible line configurations serving smaller batch sizes.
Within the full-service tier, Natural Alternatives International and Vitaquest exemplify vertically integrated operations with multi-site geographic coverage. Supplement Factory occupies a position among format specialists leveraging dedicated softgel and gummy production lines. These three entities anchor the competitive structure by representing distinct strategic archetypes: integrated quality control, delivery format specialization, and coast-to-coast distribution redundancy.
| Leading Market Players |
|---|
| Natural Alternatives International |
| Supplement Factory |
| Vitaquest |
| Uckele |
| Activ'Inside |
| Superior Supplement Manufacturing |
| Nutra Coast |
| LifeLab |
| Canyonside Lab |
| Others |
Pricing and Supply Chain Analysis
Vegetarian capsule excipient substitution from hydroxypropyl methylcellulose to modified starch variants simultaneously redraws supply geography toward German and Dutch chemical clusters and compresses per-unit formulation economics for clean-label brands. This input shift forces contract manufacturers to absorb qualification costs while passing through regional supply premiums to end customers.
Pricing Analysis
The customization-premium spread separates configured-to-order formulation services from standard catalog offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification stacking depth and batch size scale. Pricing pressure stems from direct-to-consumer brands demanding smaller lot sizes below traditional minimum efficient scale. Private label startups exhibit highest price sensitivity while practitioner-prescribed stacks tolerate premium positioning for liability protection.
Supply Chain Analysis
Germany and the Netherlands anchor specialized excipient production for vegetarian capsule alternatives and modified starch derivatives. Raw material dependencies center on hydroxypropyl methylcellulose, gelatin variants, and natural colorant feedstocks. Single-source vulnerability concentrates around pectin suppliers for gummy matrices. Distribution runs through direct-to-consumer fulfillment centers and practitioner dispensing channels rather than traditional retail warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against in-house analytical laboratory buildouts by brand owners seeking captive quality control. The substitution threat from vertically integrated sports nutrition brands with dedicated manufacturing campuses compresses available contract volume.
For Market Incumbents: Compound certification depth through NSF Certified for Sport and USP verification stacking to filter competitors from practitioner channels. Expand dual-site geographic coverage to capture coast-to-coast distribution requirements from direct-to-consumer brands. The threat of AI-powered formulation platforms displacing traditional bench development demands accelerated digital platform integration. For New Entrants and Emerging Players: NSF certification fast-track through established quality consulting partnerships opens practitioner channel access previously blocked to unqualified suppliers. Target biometric-integrated protocol services as the most penetrable white-space segment. The go-to-market angle centers on wearable data platform partnerships for recurring reformulation revenue capture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive analytical laboratories. Long-term viability over the extended investment window hinges on regulatory compliance infrastructure rather than pure manufacturing scale. The acquisition target archetype combines dual-site operations with softgel or gummy format specialization. The signal to watch as inflection indicator is FDA enforcement discretion shifts on new dietary ingredient notifications.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Stacking Program | NSF and USP verification bundling reduces client administrative burden for practitioner channel access. |
| AI Platform Integration | Machine learning formulation software compresses development timelines from empirical bench testing cycles. |
| Dual-Site Geographic Expansion | Coast-to-coast manufacturing redundancy captures direct-to-consumer brands with rapid replenishment requirements. |
| Biometric Data Partnership | Wearable platform integration enables recurring reformulation revenue from continuous glucose monitor protocols. |
| India Export Manufacturing Scale-Up | CDSCO-WHO GMP harmonization positions contract manufacturers for North American brand outsourcing arbitrage. |
Research Methodology
Cross-validation between primary interviews with contract manufacturing executives and secondary FDA filing analysis anchors the qualitative findings. Stakeholder consultations encompass formulation chemists, quality assurance directors at NSF-certified facilities, procurement leads at direct-to-consumer supplement brands, and regulatory affairs specialists navigating 21 CFR Part 111 compliance. Secondary sources include FDA cGMP inspection databases, NSF certification registries, CDSCO manufacturing license records, and ECHA REACH substance registrations. Bottom-up batch economics modeling triangulates against top-down market sizing from disclosed contract manufacturing revenues.
Sensitivity analysis on excipient cost volatility and certification timeline assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions span product chemistry complexity, delivery format capital requirements, end-user channel type, and regional regulatory cluster. CAGRs derive from historical batch volume trajectories and penetration rate modeling for personalized nutrition protocols. Industry-specific forecast inputs incorporate FDA enforcement discretion patterns and CDSCO harmonization progress with WHO GMP standards.
The analysis sits within stated boundaries; outcomes outside sustained practitioner channel expansion or abrupt regulatory enforcement shifts would require recalibration. Forecasts reflect assumptions on certification adoption rates and excipient supply stability. Recalibration cycles align with material shifts in FDA new dietary ingredient notification processing timelines and ECHA REACH amendment implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.