
 Phytoestrogen Supplements Market | 2026-2036
Phytoestrogen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Phytoestrogen Supplements Market Analysis
USP Verified certification is redrawing competitive boundaries in phytoestrogen supplements, forcing smaller brands toward costly third-party testing or private-label partnerships. NOW Foods leverages its in-house analytical laboratories to sustain USP compliance across multiple source types without external dependencies. Nature's Way anchors shelf presence in natural retail through decades-long relationships with regional health store cooperatives. Jarrow Formulas differentiates through clinician-directed education programs that build prescriber familiarity with isoflavone dosing protocols.
Phytoestrogen supplements deliver biologically active plant-derived compounds—primarily isoflavones, lignans, and coumestans—that bind to mammalian estrogen receptors with partial agonist activity, typically standardized to genistein, daidzein, or secoisolariciresinol diglucoside content. Manufacturers employ solvent extraction, supercritical CO2 processing, or fermented whole-food matrices to concentrate these actives for standardized dosing in clinical and consumer applications. Capsule formats dominate volume due to stability advantages and consumer familiarity, though liquid extracts command margin premiums through bioavailability claims and functional beverage integration. Soy-derived isoflavones occupy the largest source-type position, while red clover extracts gain traction among practitioners seeking standardized formononetin levels for menopausal symptom protocols.
FDA's Current Good Manufacturing Practice regulations and NDI notification requirements govern manufacturing quality and new ingredient market entry, while EFSA health claim assessments in Europe restrict promotional language around cardiovascular and bone-density benefits. The Federal Trade Commission monitors substantiation for hormone-balancing advertising claims, creating compliance costs that favor established players with legal infrastructure. Stakeholders must track evolving state-level hemp and cannabis regulations, as emerging cannabinoid-phytoestrogen combination products test classification boundaries and create parallel compliance obligations.
Market Dynamics
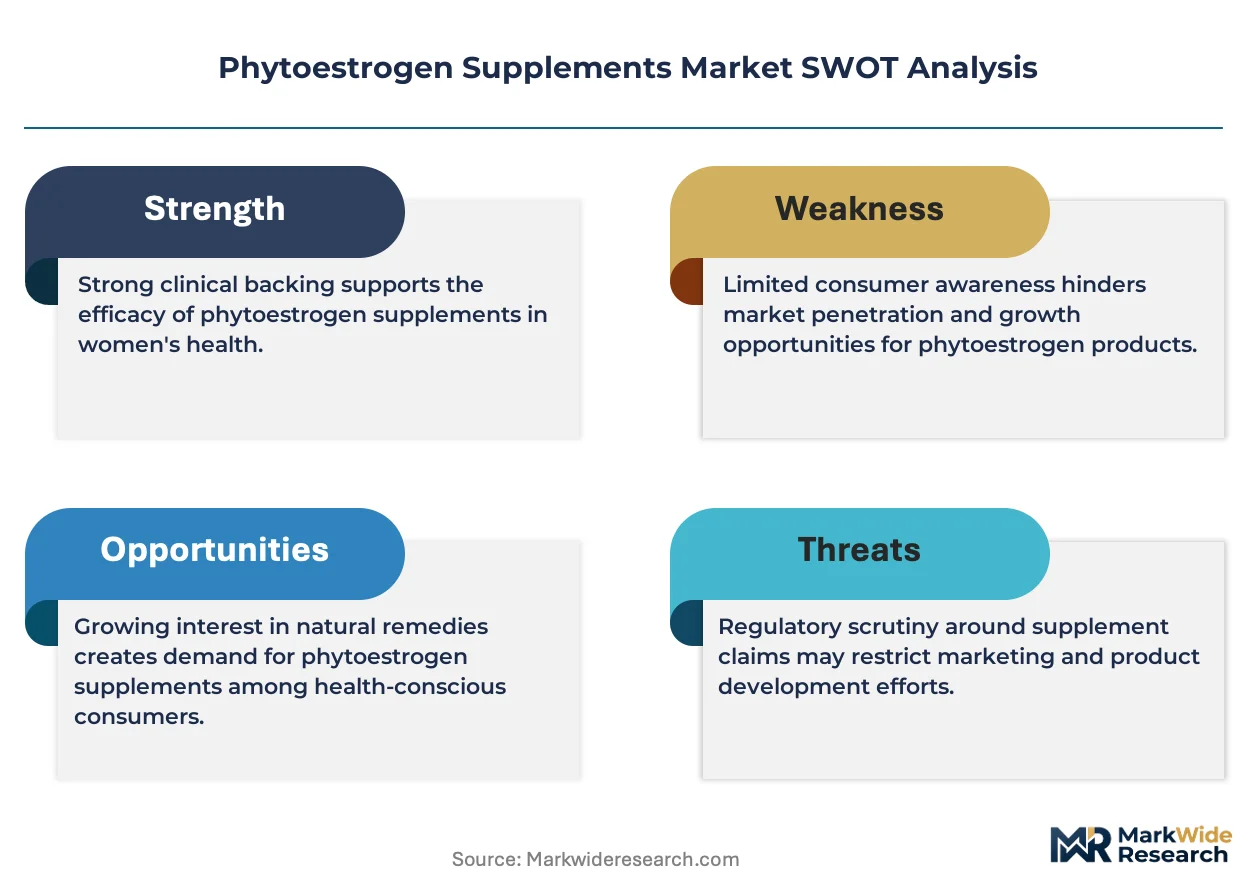
Postmenopausal women seeking alternatives to hormone replacement therapy are compressing demand cycles and forcing manufacturers to prove bioequivalence through clinical validation rather than traditional botanical marketing.
Growth Catalysts
- FDA NDI notification requirements:The notification framework is filtering out speculative entrants and concentrating shelf access among laboratories with documented safety dossiers.
- Functional medicine practitioners:This prescriber channel is writing specific isoflavone protocols that convert consumer curiosity into repeat purchase behavior.
- Soy isoflavone extraction advances:Supercritical CO2 processing is yielding higher genistein purity at lower solvent residue levels, satisfying practitioner-grade specifications.
Market Restraints
- Input cost volatility:Organic non-GMO soybean premiums fluctuate with Midwestern US crop yields and Chinese import demand swings.
- Supply concentration risk:Red clover extract production clusters in limited Eastern European agricultural zones, creating single-source vulnerability.
- EFSA health claim restrictions:The European regulator's negative opinions on cardiovascular and bone-density claims block promotional pathways in member states.
Strategic Opportunities
- Underpenetrated practitioner channels in Germany:Heilpraktiker regulatory recognition creates prescriber access unavailable in neighboring France or UK markets.
- Fermented whole-food matrices:This processing convergence with microbiome science opens positioning against synthetic isolates in premium positioning.
- Direct-to-consumer subscription platforms:US wellness platforms are capturing cohort data that enables personalized dosing algorithms and retention pricing.
Industry Challenges
- USP Verified certification timelines:The 12-18 month validation process strains working capital for mid-tier manufacturers without captive analytical capacity.
- Analytical chemist scarcity:Compound-specific quantification of formononetin and biochanin A requires specialized phytochemical expertise concentrated in academic rather than commercial laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytoestrogen Supplements Market |
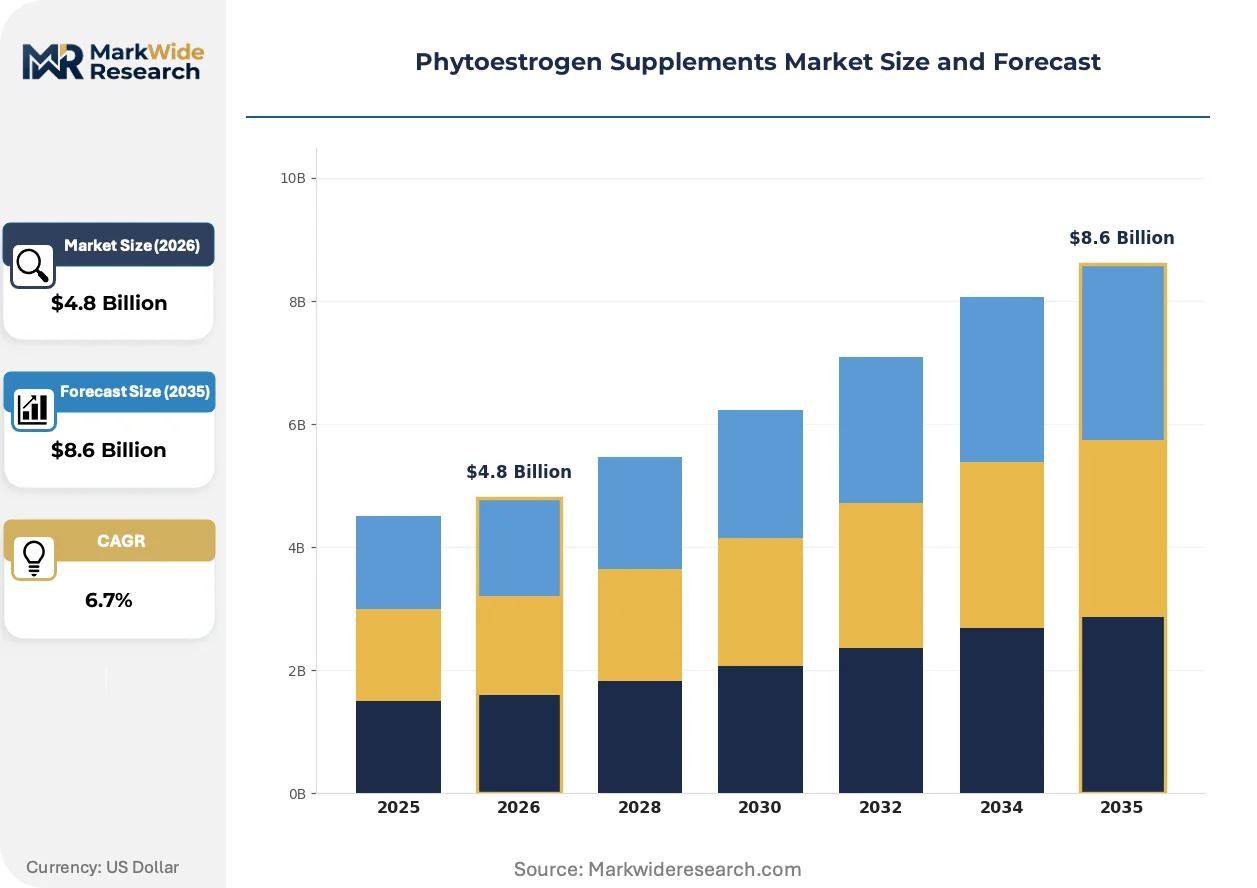
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powders, Liquids Source Type: Flaxseed, Soy, Red Clover, Alfalfa Target Audience: Women, Postmenopausal Women, Health Enthusiasts, Natural Remedy Seekers Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Nature's Way, Solaray, NOW Foods, Swanson Health Products, Solgar, GNC Holdings, Inc., Blackmores Limited, Jarrow Formulas, dōTERRA International, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytoestrogen Supplements Market Emerging Trajectories
Fermentation-based processing and practitioner-channel validation are displacing conventional extraction marketing, while regulatory documentation requirements separate investable operations from catalog sellers.
Microbial fermentation of soy substrates is decomposing the cost advantage of solvent-extracted isolates by delivering standardized isoflavone profiles with co-occurring metabolites that support bioavailability claims. Functional medicine clinics in California and Texas are adopting these fermented formats for patient protocols requiring documented batch consistency. The technology is decomposing the premium pricing power of pharmaceutical-grade synthetic alternatives in menopausal symptom management.
EFSA's 2023 updated guidance on botanical health claim substantiation is requiring human intervention trials for bone-density and cardiovascular benefit language that previously relied on observational epidemiology. German and Dutch manufacturers are reformulating toward vaginal health and skin elasticity endpoints where the evidentiary threshold remains lower. Practitioner-directed brands are responding by shifting promotional emphasis toward symptom severity reduction rather than disease risk modification.
Subscription-based replenishment models are capturing menopausal cohorts through telehealth platforms that bundle diagnostic testing with personalized isoflavone dosing. This channel is displacing natural retail shelf browsing in US metropolitan markets where convenience and privacy concerns dominate purchase decisions. The shift is most visible in coastal states where direct-to-consumer advertising restrictions on hormone-related claims are less stringent than for broadcast media.
Phytoestrogen Supplements Market Segmentation
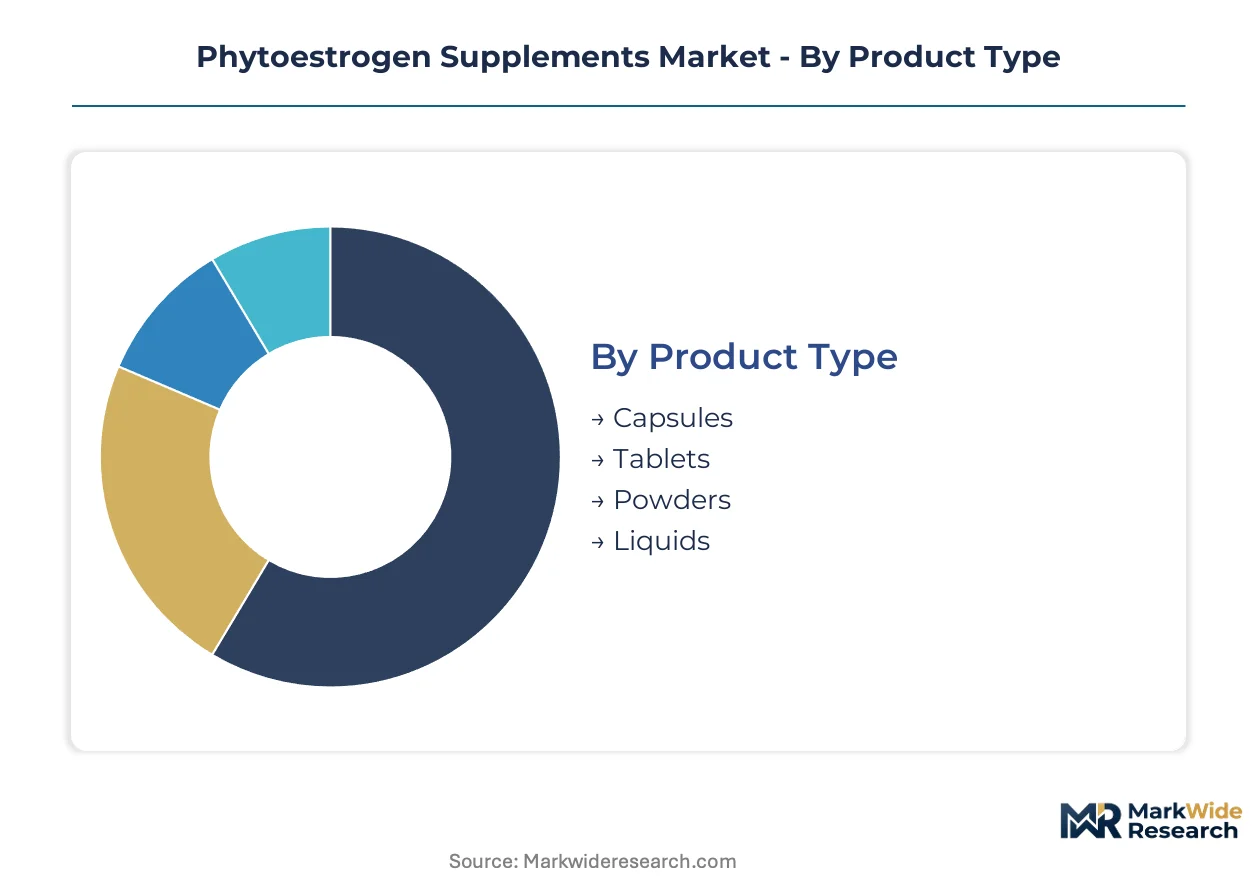
Phytoestrogen supplement manufacturers face divergent substitution threats across product formats and sourcing strategies. Capsule producers defend against functional beverage encroachment while soy-derived formulations compete with emerging fermented alternatives.
Product Type:
Capsule formats face the strongest substitute pressure from liquid extracts and functional beverages targeting bioavailability-conscious consumers.
- Capsules:Hard gelatin and vegetable cellulose shells deliver standardized isoflavone doses with 24-month stability profiles. Postmenopausal women in the United States drive volume through practitioner-directed protocols requiring precise genistein quantification.
- Liquids:Glycerin-based tinctures and liposomal suspensions command margin premiums through sublingual absorption claims. California functional medicine clinics favor these formats for patients with compromised digestive enzyme production.
- Tablets:Compressed formulations with binders and coatings sacrifice dissolution speed for manufacturing throughput. These occupy economy positioning in mass retail channels where price sensitivity dominates.
- Powders:Bulk isoflavone concentrates serve smoothie additive applications and compounding pharmacies. The format struggles with dosing precision compared to unit-dose alternatives.
Capsules anchor the volume base while liquids gain share at the steepest rate.
Source Type:
Cost tier stratification separates commodity soy isolates from premium red clover extracts with standardized formononetin certificates.
- Soy:Solvent-extracted and supercritical CO2-processed isoflavones yield genistein and daidzein standardized to 40% aggregate content. Midwestern US organic crop premiums fluctuate with Chinese import demand cycles.
- Red Clover:Eastern European agricultural zones supply formononetin and biochanin A concentrates for menopausal symptom protocols. German Heilpraktiker prescribe these for hot flash severity reduction.
- Flaxseed:Lignan-rich secoisolariciresinol diglucoside extracts target cardiovascular positioning despite EFSA health claim restrictions. The source competes on sustainability narratives rather than clinical validation.
- Alfalfa:Coumestan-containing sprout and leaf extracts occupy niche positioning for lactation support applications. Limited clinical dossiers constrain practitioner adoption.
Soy dominates manufacturing scale while red clover climbs the fastest on prescriber channel expansion.
Target Audience:
Application intensity varies from daily wellness maintenance to acute symptom management requiring protocol compliance.
- Postmenopausal Women:This cohort drives clinical validation investments and USP Verified certification requirements. Texas and California functional medicine clinics write specific isoflavone protocols converting curiosity into repeat purchases.
- Women:Premenopausal consumers seek cycle regulation and skin elasticity benefits with lower evidentiary thresholds than bone-density claims.
- Health Enthusiasts:Biohacking communities experiment with phytoestrogen stacking for athletic recovery and hormonal optimization. The segment tolerates higher price points for fermented whole-food matrices.
- Natural Remedy Seekers:Skepticism toward synthetic hormones drives trial of botanical alternatives with weaker standardization requirements.
Postmenopausal women anchor the volume base while health enthusiasts gain share at the steepest rate.
Distribution Channel:
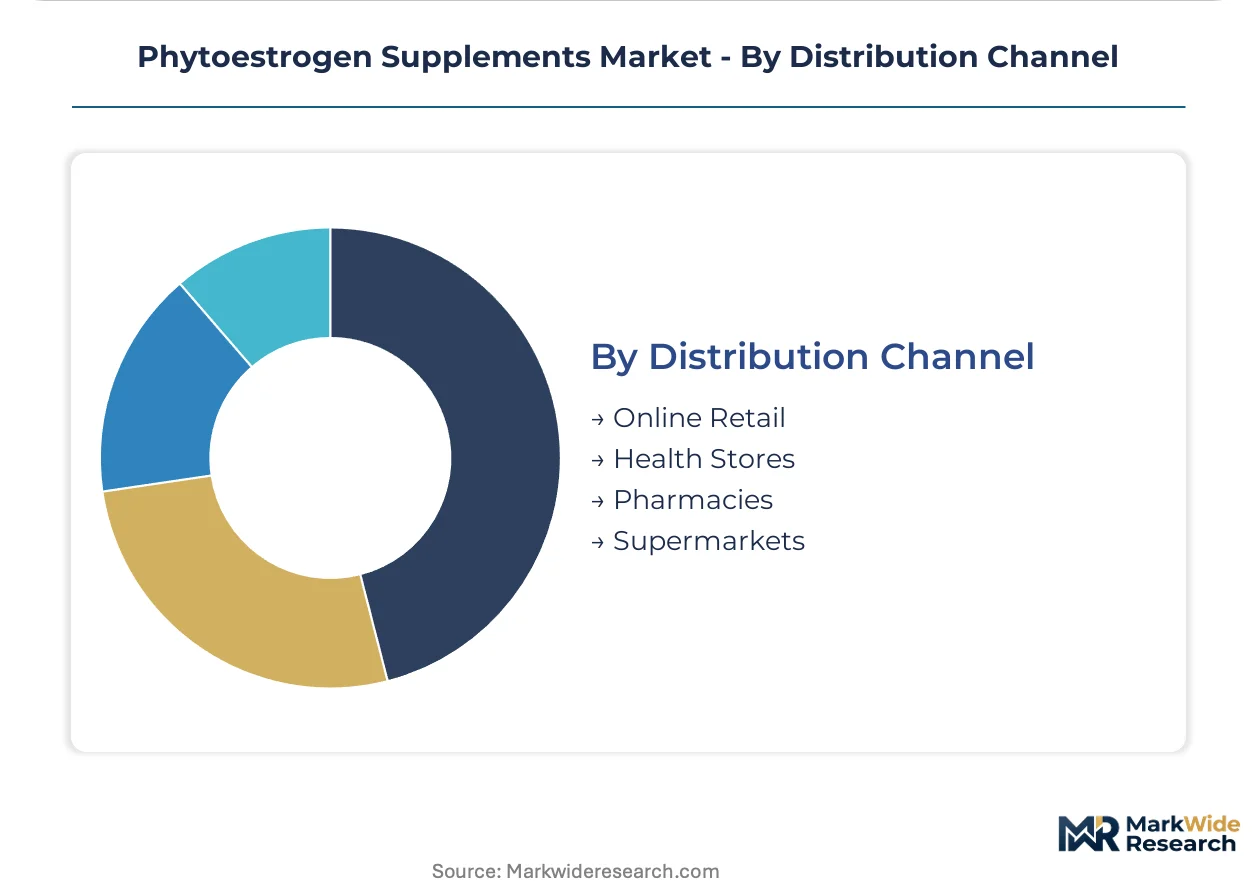
Customer type concentration determines margin structure and regulatory exposure across channel archetypes.
- Online Retail:Direct-to-consumer wellness platforms capture cohort data enabling personalized dosing algorithms. Coastal US states show highest subscription conversion where privacy concerns dominate purchase decisions.
- Health Stores:Regional cooperatives and natural retail chains maintain decades-long supplier relationships. These channels prioritize USP Verified and non-GMO certifications for shelf placement.
- Pharmacies:Chain and independent drugstores stock practitioner-recommended brands with documented safety dossiers. FDA NDI notification requirements filter speculative entrants from this channel.
- Supermarkets:Mass retail placement demands economy pricing and broad demographic appeal. The channel sacrifices margin for volume throughput.
Health stores anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA NDI notification requirements and EFSA health claim assessments are reshaping competitive access across major jurisdictions, with regulatory documentation costs concentrating shelf presence among established laboratories.
United States
Postmenopausal women in Texas and California drive practitioner-directed protocol adoption through functional medicine clinics. FDA Current Good Manufacturing Practice regulations filter speculative entrants from pharmacy channels. Direct-to-consumer wellness platforms in coastal metropolitan areas capture subscription cohorts through personalized isoflavone dosing algorithms.
Germany
Heilpraktiker regulatory recognition creates prescriber access unavailable in neighboring France or UK markets. EFSA negative opinions on cardiovascular and bone-density claims block promotional pathways, forcing reformulation toward vaginal health endpoints. Bavarian and North Rhine-Westphalian manufacturing clusters specialize in fermented whole-food matrix processing for practitioner-grade specifications.
China
Domestic demand for soy-derived isoflavones fluctuates with organic non-GMO crop premiums and import demand cycles. The national pharmaceutical regulator enforces dual carbon goals that favor supercritical CO2 extraction over solvent-based methods. Yangtze River Delta processing facilities concentrate genistein purification capacity for export markets.
Australia
Health enthusiast segments experiment with phytoestrogen stacking for athletic recovery applications. The Therapeutic Goods Administration monitors substantiation for hormone-balancing advertising claims, creating compliance costs that favor established players. Sydney and Melbourne functional medicine clinics adopt fermented formats for patient protocols requiring documented batch consistency.
United Kingdom
Premenopausal consumers seek cycle regulation and skin elasticity benefits with lower evidentiary thresholds than bone-density claims. The national pharmaceutical regulator restricts promotional language around menopausal symptom management. London-based subscription platforms capture metropolitan cohorts where privacy concerns dominate purchase decisions.
Phytoestrogen Supplements Market Vendor Landscape
Player mix skews toward vertically integrated laboratories and specialist botanical houses with captive analytical capacity. NOW Foods leverages in-house analytical laboratories to sustain USP compliance across multiple source types without external dependencies. Three strategic archetypes dominate: certification-heavy incumbents with USP Verified dossiers, practitioner-channel specialists with clinician education programs, and direct-to-consumer platforms with subscription retention models. Competitive moves concentrate on third-party testing partnerships and private-label manufacturing agreements that bypass 12-18 month USP validation timelines.
Within the certification-heavy tier, NOW Foods and Nature's Way exemplify divergent approaches to regulatory compliance. NOW Foods anchors its position through captive laboratory infrastructure that eliminates external testing dependencies. Nature's Way occupies shelf presence in natural retail through decades-long relationships with regional health store cooperatives. Jarrow Formulas sits within the practitioner-channel specialist archetype, building prescriber familiarity with isoflavone dosing protocols through clinician-directed education programs. These three entities collectively represent the competitive fault lines separating investable operations from catalog sellers in an environment where FDA NDI notification requirements and USP Verified certification timelines strain working capital for mid-tier manufacturers.
| Leading Market Players |
|---|
| Nature's Way |
| Solaray |
| NOW Foods |
| Swanson Health Products |
| Solgar |
| GNC Holdings, Inc. |
| Blackmores Limited |
| Jarrow Formulas |
| dōTERRA International, LLC |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction capacity utilization in Midwestern US facilities shapes both minimum viable scale for new entrants and floor pricing for organic non-GMO soy isoflavones. Scale advantages concentrate among laboratories with captive analytical infrastructure, forcing mid-tier manufacturers toward private-label arrangements or extended USP validation timelines that compress working capital.
Pricing Analysis
Certification level creates the primary spread between USP Verified practitioner-grade products and unverified catalog offerings. Three-tier pricing structure across premium, standard, and economy levels separates fermented whole-food matrices from solvent-extracted isolates and bulk powder concentrates. Cost compression in the economy tier is intensifying because organic soybean premiums fluctuate with Chinese import demand cycles. Postmenopausal women in practitioner-directed protocols show lowest price sensitivity, while mass retail consumers in supermarket channels drive volume at margin-thin price points.
Supply Chain Analysis
Eastern European red clover harvests anchor formononetin supply for German Heilpraktiker protocols, creating single-source vulnerability during adverse weather cycles. Raw material dependencies center on Midwestern US organic soybeans, Chinese non-GMO crop premiums, and Black Sea region agricultural output. Tariff exposure runs through US-China trade friction affecting isoflavone concentrate imports. Distribution runs through direct-to-consumer wellness platforms in coastal US states, regional health store cooperatives, and pharmacy chains with FDA NDI compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward functional medicine practitioners who consolidate protocol authority and convert patient curiosity into repeat purchase behavior. This prescriber-channel consolidation fragments traditional retail influence and rewards manufacturers with clinician education infrastructure.
For Market Incumbents: Consolidate analytical laboratory capacity to eliminate external USP testing dependencies and compress certification timelines. Deepen backward integration into organic soybean sourcing to buffer Midwestern crop yield volatility. Defend against fermented whole-food matrix substitutes by documenting batch consistency for practitioner protocols.
For New Entrants and Emerging Players: Personalized dosing algorithm services represent the most penetrable white-space where incumbent laboratories under-serve direct-to-consumer platforms. Target subscription-based wellness platforms in Texas and California metropolitan markets where privacy concerns dominate purchase decisions. Pursue Heilpraktiker channel access in Germany through bilingual clinician education programs that bypass EFSA health claim restrictions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with diagnostic testing bundling and retention pricing algorithms. Long-term viability over the projection horizon favors laboratories with captive analytical infrastructure and documented safety dossiers. Watch FDA NDI notification backlogs as an inflection indicator for competitive access tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Investment | Captive laboratory infrastructure eliminates external testing dependencies and compresses 12-18 month validation timelines. |
| Practitioner Education Program | Clinician-directed protocols in Texas and California functional medicine clinics convert consumer curiosity into repeat purchases. |
| Fermented Whole-Food Matrix Development | Microbial fermentation processing aligns with microbiome science positioning against synthetic isolates in premium segments. |
| Direct-to-Consumer Platform Launch | Subscription models in coastal US states capture cohort data enabling personalized isoflavone dosing algorithms. |
| Heilpraktiker Channel Expansion | German regulatory recognition creates prescriber access unavailable in neighboring France or UK markets. |
Methodological Framework
Operator-level perspectives from functional medicine practitioners, dietary supplement formulators, USP analytical laboratory directors, and health store cooperative buyers anchored the qualitative base. Primary interviews triangulated with FDA NDI notification filings, EFSA health claim assessment records, organic crop premium data from Midwestern agricultural exchanges, and customs documentation of isoflavone concentrate imports. Secondary validation drew from SEC 10-K filings of publicly traded supplement manufacturers, trade association production surveys, and practitioner protocol databases. Bottom-up demand modeling across postmenopausal cohorts, health enthusiast segments, and natural remedy seekers converged with top-down value chain analysis.
Sensitivity analysis tested input cost volatility in organic soybean markets, USP certification timeline variations, and Heilpraktiker prescription volume assumptions across the analysis window. The analytical framework modeled segmentation dimensions including product format, source type, target audience intensity, and distribution channel regulatory exposure. CAGRs derived from cohort-level adoption curves and practitioner protocol penetration rates. Forecast inputs incorporated supercritical CO2 processing yield improvements and EFSA guidance evolution on botanical health claim substantiation.
Forecasts assume regulatory continuity in FDA NDI notification requirements and EFSA health claim assessments; material policy shifts would require re-modeling competitive access assumptions. Specific risk factors include US-China trade friction affecting organic soybean supply, Eastern European agricultural disruption impacting red clover harvests, and state-level hemp-cannabis regulatory divergence affecting combination product classification. Practitioners should keep alternative scenarios live as Heilpraktiker regulatory recognition and fermented processing technology adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Vegan Protein Market