
 Spain Whey Protein Market | 2026-2036
Spain Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Whey Protein Market Analytics
The capability gap between integrated dairy processors and commodity traders is collapsing. Glanbia plc leverages its Irish whey sourcing network to dominate isolate production for Spanish sports nutrition brands. Lactalis Ingredients anchors its position through captive cheese-making operations that secure raw whey streams. Estrel Ingredients, S.L. competes on proximity, operating blending and flavoring facilities near Barcelona's distribution hubs.
Whey protein comprises the soluble protein fraction separated during cheese manufacture, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 34% to 90% depending on processing intensity; spray drying and membrane filtration transform liquid whey into shelf-stable powders for human consumption. Isolate commands the highest margin pool due to its 90%+ protein content and superior amino acid density for athletic recovery applications. Hydrolysate represents the fastest-growing product type as pre-digested peptides gain traction among consumers with lactose sensitivity. Online retail channels are displacing traditional health food stores for repeat purchases, though supermarkets still capture trial-driven volume from health-conscious consumers entering the category.
EFSA novel food and health claim assessments govern whey protein labeling across Spain, while the country's national food safety agency enforces maximum residue limits for heavy metals and microbiological contaminants. REACH compliance for processing aids and cleaning chemicals adds cost layers for imported whey concentrates. Spanish packaging regulations under the EU Single-Use Plastics Directive are forcing transitions from conventional tubs to recyclable or biodegradable alternatives. Stakeholders must monitor evolving EFSA opinions on protein-specific health claims and the pace of Madrid's implementation of extended producer responsibility schemes for supplement packaging.
Market Dynamics
EFSA health claim assessments are compressing formulation flexibility while Madrid and Barcelona gym chains consolidate private-label procurement, forcing ingredient suppliers to recertify products for narrower label claims.
Growth Catalysts
- Metropolitan fitness penetration:Premium gym chains in Madrid and Barcelona are expanding captive supplement lines, creating anchored demand for whey isolate and hydrolysate variants.
- EFSA protein claim frameworks:Approved health claims for muscle maintenance are enabling sports nutrition brands to differentiate finished products through substantiated labeling.
- Membrane filtration advances:Cold-processed microfiltration is preserving bioactive fractions in whey isolate, appealing to performance-oriented consumers seeking native protein structures.
Market Restraints
- Raw whey supply concentration:Spanish cheese-making capacity limits domestic raw material availability, forcing dependence on Irish and French whey streams subject to dairy commodity cycles.
- REACH compliance burdens:Processing aids and cleaning chemicals used in whey fractionation face ECHA registration requirements that add fixed cost layers for imported concentrates.
- Plant protein substitution:Pea and fava protein isolates are capturing trial purchases among consumers with lactose sensitivity or sustainability preferences.
Strategic Opportunities
- Andalusian and Valencian expansion:Underpenetrated secondary cities offer whitespace for sports nutrition distribution as fitness club penetration lags Madrid and Barcelona.
- EU Single-Use Plastics Directive compliance:Biodegradable tub and pouch formats create first-mover positioning for brands willing to absorb packaging transition costs ahead of Madrid's extended producer responsibility enforcement.
- Medical nutrition convergence:Sarcopenia-focused clinical applications for whey protein are opening hospital and pharmacy channels beyond traditional sports nutrition retail.
Industry Challenges
- Flavor masking formulation expertise:Hydrolysate bitterness requires specialized protein chemists and sensory scientists in short supply within Spanish ingredient development teams.
- EFSA novel food assessment timelines:New whey-derived bioactive submissions face multi-year evaluation periods that delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Whey Protein Market |
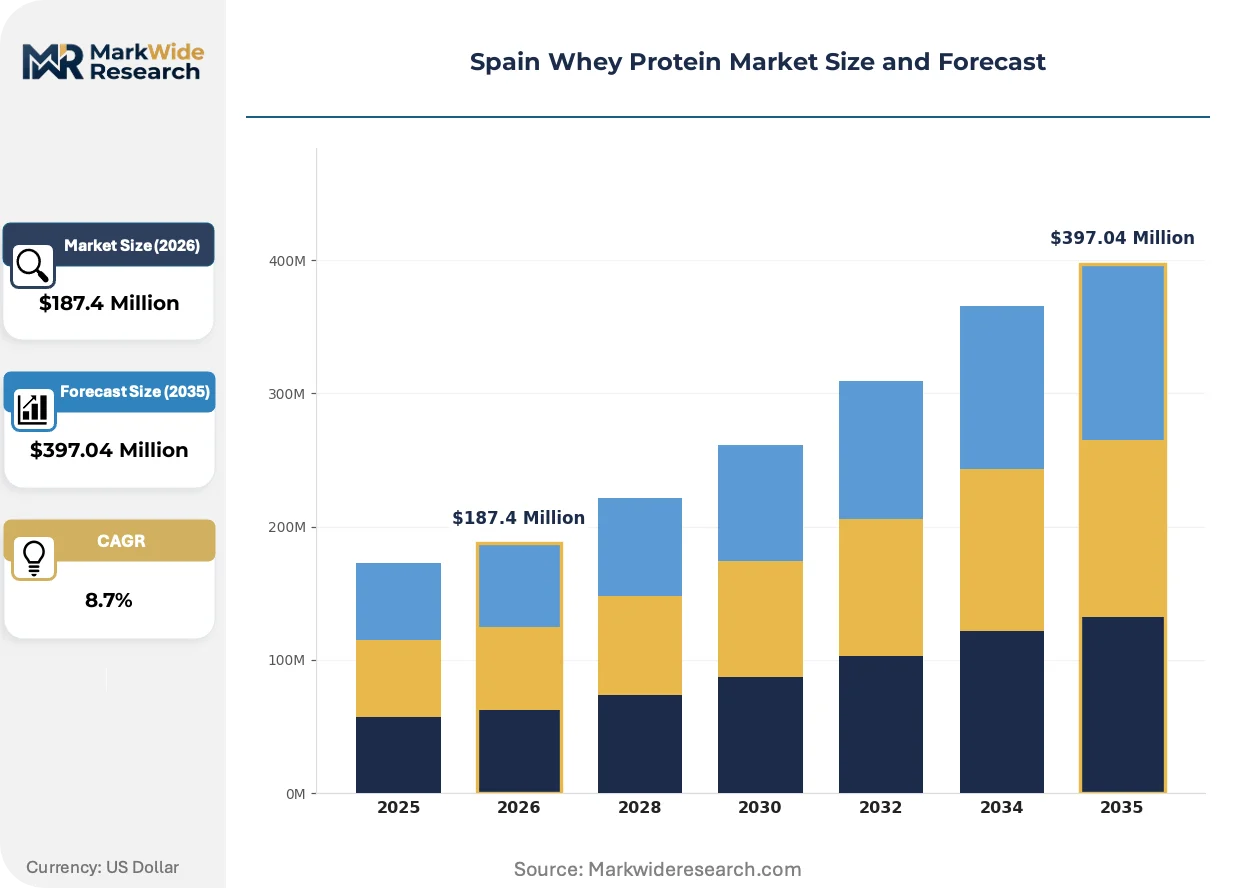
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blend End User: Athletes, Fitness Enthusiasts, Health-conscious Consumers, Dietary Supplement Users Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Gyms Packaging Type: Bags, Tubs, Sachets, Cans |
| Companies Covered | Carbery Group, Glanbia plc, Lactalis Ingredients, Hilmar Ingredients, Arla Foods amba, Estrel Ingredients, S.L., United Quality Foods, Agropur Cooperative, Fonterra Co-operative Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Whey Protein Market Evolving Landscape
Processing intensities and distribution architectures are diverging as brands split between premium isolate positioning and mass-market concentrate accessibility, with regulatory packaging mandates forcing simultaneous format innovation.
Cross-flow microfiltration combined with ceramic membrane cascades is miniaturizing the equipment footprint required for 90%+ protein isolation. Regional Spanish dairy processors are adopting these systems to enter sports nutrition ingredient supply. The technology is compressing capital barriers that previously reserved isolate production to large integrated operators.
EFSA novel food and health claim assessments are tightening evidentiary requirements for whey protein product positioning. Sports nutrition brands must now commission human intervention studies to support muscle recovery claims. Spanish formulations targeting athletic populations face the steepest compliance costs as Madrid's food safety agency enforces residue testing protocols.
Subscription-based replenishment models are displacing single-purchase behavior among established whey protein consumers. Online direct-to-consumer channels capture recurring revenue while supermarkets retain category entry trial volume. Barcelona and Madrid metropolitan zones show the highest subscription penetration as fitness enthusiasts automate supplement resupply.
Spain Whey Protein Market Segmentation
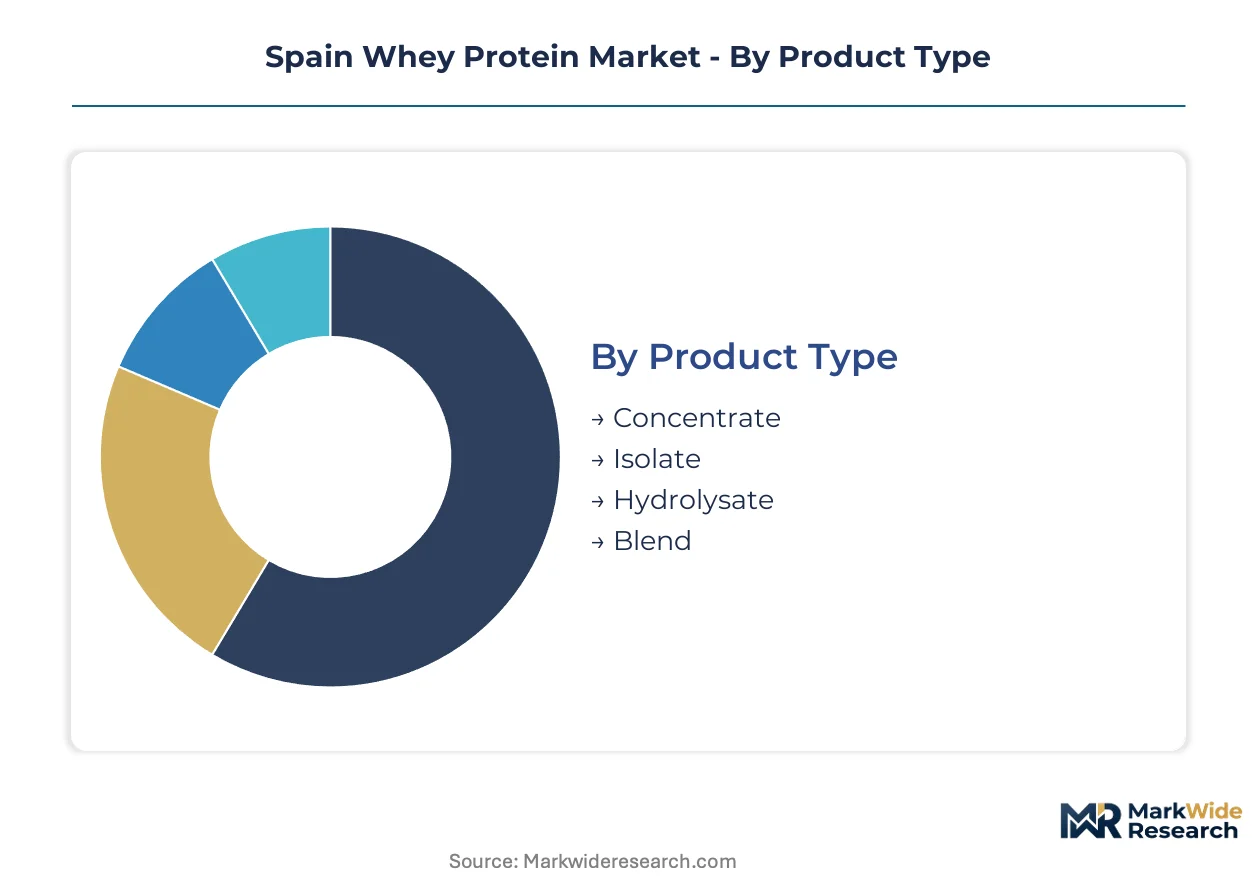
Segmentation in the Spain whey protein market reveals how regulatory frameworks and supply chain configurations create distinct competitive battlegrounds. EFSA health claim approvals and Madrid's packaging enforcement reshape profitability across product tiers and channel strategies.
Product Type:
EFSA protein content thresholds differentiate labeling permissions and health claim eligibility across processing intensities.
- Isolate:Contains 90%+ protein content with minimal lactose and fat through ion exchange or cross-flow microfiltration. Demand concentrates in Madrid and Barcelona premium gym chains where EFSA-approved muscle maintenance claims command shelf space. Cold-processed variants preserving native protein structures capture the steepest expansion trajectory among performance-oriented consumers.
- Hydrolysate:Pre-digested peptides broken by enzymatic hydrolysis reduce allergenicity and accelerate gastric emptying. Barcelona-based sports nutrition brands source hydrolysate for consumers with lactose sensitivity, though flavor masking complexity limits formulation proliferation. EFSA novel food timelines delay bioactive peptide launches.
- Concentrate:Standard 34-80% protein fractions retain more lactose and bioactive compounds for cost-sensitive applications.
- Blend:Custom ratios of concentrate, isolate, and hydrolysate target specific price-performance positioning.
Established volume favors concentrate; emerging adoption favors isolate.
End User:
Customer sophistication and purchase frequency split the market between institutional procurement and discretionary trial.
- Athletes:Competitive and professional sports populations require batch-tested products meeting anti-doping protocols. Madrid Olympic training facilities and Catalan professional football academies drive certified isolate demand. EFSA contamination limits and national residue testing enforce supply chain documentation burdens.
- Fitness Enthusiasts:Regular gym attendees in metropolitan Spain automate replenishment through subscription models. Barcelona and Madrid show highest subscription penetration as premium chains expand private-label lines. Protein timing research influences pre-workout and recovery formulation preferences.
- Health-conscious Consumers:General wellness seekers entering the category through supermarket trial purchases.
- Dietary Supplement Users:Medical nutrition and clinical sarcopenia applications opening pharmacy and hospital channels.
Volume concentrates with fitness enthusiasts; margin expansion sits with athletes.
Distribution Channel:
Channel economics reflect customer lifetime value divergence between acquisition and retention phases.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through subscription automation. Madrid and Barcelona metropolitan zones show highest digital penetration as fitness enthusiasts eliminate purchase friction. E-commerce logistics face REACH compliance documentation for imported concentrates.
- Supermarkets:Mass-market retail retains category entry function for health-conscious consumers testing the segment. Carrefour and Mercadona shelf placement determines trial volume concentration. EFSA front-of-pack labeling requirements constrain claim presentation.
- Health Food Stores:Specialist retailers retain educated consumer segments seeking personalized guidance.
- Gyms:Captive distribution through premium chain private-label lines anchors metropolitan demand.
Acquisition economics favor supermarkets; lifetime value maximization favors online retail.
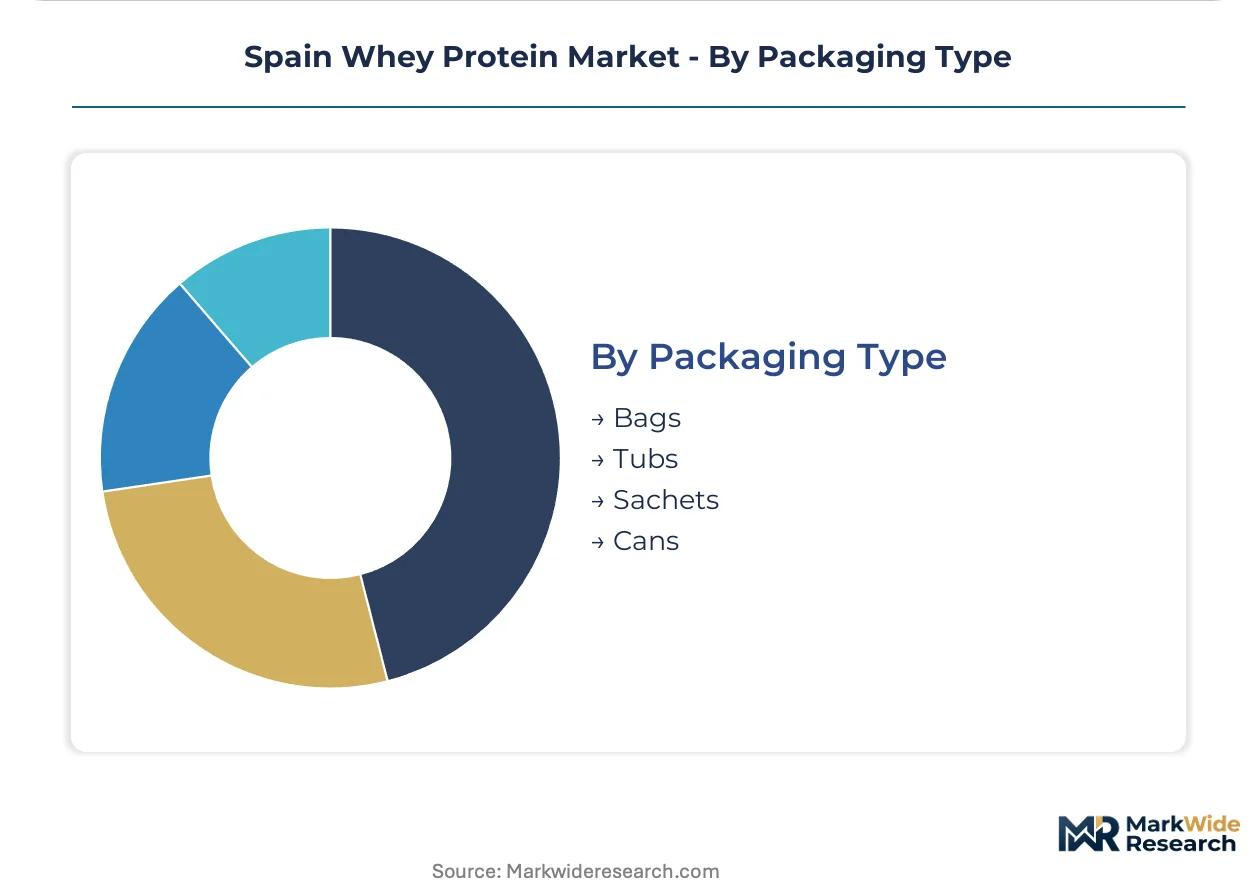
Packaging Type:
EU Single-Use Plastics Directive compliance timelines force format transition investments ahead of Madrid's extended producer responsibility enforcement.
- Tubs:Rigid plastic containers dominate bulk isolate and concentrate formats for home consumption. Conventional polypropylene faces mandatory replacement under Spanish packaging regulations. Biodegradable alternatives command 15-25% cost premiums absorbed by premium positioning.
- Bags:Flexible pouches reduce shipping cube and material intensity for high-volume concentrate sales. Valencia and Andalusian secondary market expansion favors bag economics for distribution efficiency. Recyclable mono-material structures attract sustainability-positioned brands.
- Sachets:Single-serve formats target trial and travel occasions with higher unit economics.
- Cans:Metal packaging retains niche positioning for ready-to-drink whey protein beverages.
Transition risk concentrates in tubs; format innovation opportunity sits with bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's whey protein trade flows reflect a structural deficit in domestic cheese-making capacity, with raw material dependence on Irish and French dairy streams shaping import patterns. Metropolitan fitness penetration in Madrid and Barcelona concentrates finished product demand, while secondary regions offer whitespace expansion corridors.
Madrid
Premium gym chains anchor isolate demand through private-label supplement lines. EFSA health claim regulations constrain formulation flexibility for products targeting competitive athletes. The capital's Olympic training facilities drive certified batch requirements for anti-doping compliance.
Catalonia
Barcelona's distribution hubs attract blending and flavoring operations seeking proximity to Mediterranean export routes. REACH compliance documentation burdens concentrate here for imported whey concentrates. The region's sports nutrition brands source hydrolysate variants for lactose-sensitive consumer segments.
Basque Country
Specialized dairy processing infrastructure supports whey fractionation for medical nutrition applications. Spain's national food safety agency enforces residue testing protocols for products entering hospital channels. Bilbao's port facilities handle membrane filtration equipment imports for regional processors.
Andalusia
Underpenetrated fitness club density creates whitespace for sports nutrition distribution expansion. EU Single-Use Plastics Directive compliance timelines force packaging transition investments ahead of Madrid's extended producer responsibility enforcement. Seville and Málaga metropolitan zones show emerging subscription model adoption.
Valencia
Flexible pouch formats gain traction for cost-efficient distribution to secondary markets. Recyclable mono-material structures attract sustainability-positioned brands seeking differentiation. The region's logistics infrastructure supports bag economics for high-volume concentrate sales.
Spain Whey Protein Market Competitive Landscape
Concentration sits with integrated dairy processors possessing captive whey streams from cheese-making operations. Irish and French operators leverage raw material proximity to dominate isolate supply for Spanish sports nutrition brands. Three archetypes define competitive positioning: multinational dairy cooperatives with backward integration into milk supply, specialized whey fractionators with membrane filtration expertise, and regional blenders competing on flavor development and distribution proximity. Capacity expansion and EFSA recertification for narrower health claims represent the dominant competitive moves reshaping supplier relationships.
Within the integrated dairy tier, Glanbia plc and Lactalis Ingredients exemplify archetypes built on captive raw material access and fractionation scale. Carbery Group occupies a position representing Irish cooperative structures with whey sourcing networks. Estrel Ingredients, S.L. anchors the regional blender segment through Barcelona-proximate operations. These three patterns—multinational integration, cooperative sourcing, and geographic specialization—structure competitive dynamics for Spanish market access.
| Leading Market Players |
|---|
| Carbery Group |
| Glanbia plc |
| Lactalis Ingredients |
| Hilmar Ingredients |
| Arla Foods amba |
| Estrel Ingredients, S.L. |
| United Quality Foods |
| Agropur Cooperative |
| Fonterra Co-operative Group |
| Others |
Value Network & Pricing Analysis
Membrane filtration scale economies at Irish and French dairy cooperatives compress unit economics for whey isolate, concentrating supply power among integrated processors while anchoring Spanish price floors to cross-channel raw material costs. Madrid's premium gym chains absorb these input premiums through private-label markups, whereas mass-market concentrate distributors face margin compression from commodity whey volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Spanish whey protein procurement. Cold-processed isolate commands premium positioning against commodity concentrate, with EFSA certification tiers and volume scale driving price differentiation between sports nutrition brands. Pricing pressure stems from plant protein substitution as pea and fava isolates capture trial purchases among sustainability-conscious consumers. Health-conscious supermarket entrants exhibit highest price sensitivity, while certified athletic batch buyers demonstrate lowest elasticity due to anti-doping compliance requirements.
Supply Chain Analysis
Container availability fluctuations on Irish Sea and English Channel routes directly impact inbound whey concentrate landed costs for Spanish blenders. Raw material sourcing draws from Ireland, France, and the Netherlands as domestic Spanish cheese-making capacity limits captive whey streams. Membrane filtration equipment, enzymatic hydrolysis inputs, and flavor masking compounds constitute critical dependencies. Single-source vulnerability concentrates in Irish whey isolate supply given Glanbia's dominant fractionation share. Distribution runs through Barcelona's Mediterranean hub for southern European reach, with Madrid's metropolitan logistics serving central Iberian penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription automation platforms are reconfiguring buyer-supplier relationships in Spanish sports nutrition, with direct-to-consumer interoperability collapsing traditional retail gatekeeper economics.
For Market Incumbents: Fortify backward integration into Irish and French whey streams through long-term offtake agreements with Carbery Group and Lactalis Ingredients. Expand cold-processed microfiltration capacity in Catalonia to defend margin position against commodity concentrate erosion. EFSA recertification timelines for narrowed health claims represent the priority defensive investment. For New Entrants and Emerging Players: Flavor masking formulation expertise gaps among Spanish ingredient development teams create service-layer white space for specialized protein chemists. Target Andalusian and Valencian secondary cities where fitness club penetration lags Madrid and Barcelona. Enter through biodegradable packaging compliance services ahead of extended producer responsibility enforcement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane filtration equipment suppliers with ceramic cascade miniaturization capabilities. Five-to-ten year viability hinges on clinical sarcopenia application expansion beyond sports nutrition. Acquisition targets should demonstrate hospital channel penetration and EFSA novel food submission track records. Watch EFSA opinions on protein-specific health claims as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Streams | Long-term offtake agreements with Irish cooperatives secure raw material cost predictability against dairy commodity cycles. |
| Cold-Processed Microfiltration Capacity Expansion | Catalonia-based native protein preservation captures performance-oriented consumer premium positioning. |
| Biodegradable Packaging Transition | EU Single-Use Plastics Directive compliance creates first-mover differentiation ahead of Madrid enforcement. |
| Medical Nutrition Channel Development | Hospital and pharmacy sarcopenia applications diversify revenue beyond saturated sports nutrition retail. |
| EFSA Health Claim Recertification Investment | Substantiated muscle maintenance labeling defends shelf space against plant protein substitutes. |
Research Methodology
Cross-validation between primary interviews with dairy processors and secondary trade data anchors the qualitative findings in this study. Sports nutrition brand managers, gym chain procurement officers, EFSA regulatory consultants, and membrane filtration equipment suppliers constituted the stakeholder interview base. Secondary sources included EFSA novel food assessment databases, Spanish customs whey import records, EU dairy cooperative financial disclosures, and REACH compliance documentation repositories. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Sensitivity analysis across protein content tiers, end-user sophistication levels, and distribution channel economics shaped the analytical framework over the projection horizon. Segmentation dimensions encompassed product type, customer archetype, channel structure, and packaging format compliance status. CAGRs derived from volume trajectory modeling against population fitness penetration curves and subscription automation adoption rates. EFSA regulatory timeline assumptions and Irish dairy output volatility informed scenario boundaries.
Underlying assumptions cover EFSA health claim approval continuity, Irish-French whey supply stability, and Madrid packaging enforcement schedules, with deviation risk concentrated in novel food assessment delays and plant protein substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Australia Protein Market
Nutritional Supplements
Flax Protein Powder Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Europe Omega-3 Products Market