
 Nicotine Gum Market | 2026-2036
Nicotine Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Nicotine Gum Market Intelligence
Corporate wellness programs is pivoting toward nicotine cessation benefits, expanding employer-sponsored access to over-the-counter cessation aids. Johnson & Johnson sustains brand recognition through pharmacy shelf presence and clinician recommendation networks. Pfizer Inc. competes via prescription-to-OTC transition expertise and regulatory navigation capabilities. British American Tobacco plc leverages its combustible-to-reduced-risk portfolio pivot to secure pharmacy distribution partnerships for nicotine replacement products.
Nicotine gum consists of a chewing gum base infused with nicotine polacrilex, designed for buccal absorption through the oral mucosa at controlled release rates typically spanning 20 to 30 minutes per piece, serving as a pharmacological aid to reduce withdrawal symptoms during tobacco cessation protocols. Mint flavored and fruit flavored variants dominate consumer preference matrices due to palatability masking of nicotine bitterness, while 2 mg and 4 mg dosage strengths anchor volume sales by aligning with stepped-down dependence protocols. E-Commerce channels are capturing incremental share as direct-to-consumer subscription models bypass traditional pharmacy intermediaries.
FDA classification of nicotine gum as a drug-device combination product mandates New Drug Application compliance for manufacturers accessing the United States market, while EMA oversight through centralized marketing authorization procedures governs European commercialization pathways. Japan's PMDA maintains distinct pharmacovigilance reporting thresholds that influence regional product labeling and post-market surveillance obligations. Stakeholders must monitor evolving prescription-status reclassifications and excise tax treatments that could reshape channel economics across major jurisdictions.
Market Dynamics
Corporate wellness mandates are redrawing access pathways for nicotine cessation products, as employers embed pharmacological aids into insurance-covered benefit tiers. This structural shift compresses traditional pharmacy intermediation while elevating clinician recommendation networks as primary demand gatekeepers.
Growth Catalysts
- Workplace wellness integration:Employer-sponsored health plans in the United States now routinely cover over-the-counter cessation aids, bypassing prior prescription barriers and expanding addressable user bases through payroll-deducted benefit structures.
- FDA labeling clarity:The agency's tightened purity benchmarks for nicotine replacement therapies have reduced consumer safety concerns, accelerating pharmacist confidence in front-of-counter placement recommendations.
- Japan's smoking cessation infrastructure:PMDA-sanctioned reimbursement protocols and municipal cessation counseling programs concentrate demand in Tokyo, Osaka, and Yokohama metropolitan clusters.
Market Restraints
- Active pharmaceutical ingredient concentration:Three contract manufacturers in India control the majority of nicotine polacrilex supply, creating input vulnerability for finished gum producers.
- EMA centralized authorization timelines:Marketing authorization procedures for nicotine replacement therapies extend 18-24 months, delaying product launches and freezing working capital.
- Heat-not-burn tobacco devices:Reduced-risk alternatives from combustible manufacturers capture switching smokers who might otherwise adopt pharmaceutical cessation protocols.
Strategic Opportunities
- Direct-to-consumer subscription channels:E-commerce platforms bypass pharmacy intermediation, capturing recurring revenue through automated replenishment algorithms and personalized dosing protocols.
- Germany's statutory health insurance expansion:The G-BA assessment framework is evaluating full reimbursement for nicotine replacement therapies, which would eliminate out-of-pocket friction.
- Flavor masking technology convergence:Microencapsulation processes combined with sustained-release polymer matrices enable palatability improvements for pediatric and geriatric off-label applications.
Industry Challenges
- Post-market surveillance staffing:Pharmacovigilance reporting thresholds in Japan and Europe require dedicated adverse event teams, straining mid-tier manufacturers without captive regulatory affairs capacity.
- Drug-device combination documentation:FDA New Drug Application compliance demands clinical bioequivalence studies that extend development timelines and compress R&D budget flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicotine Gum Market |
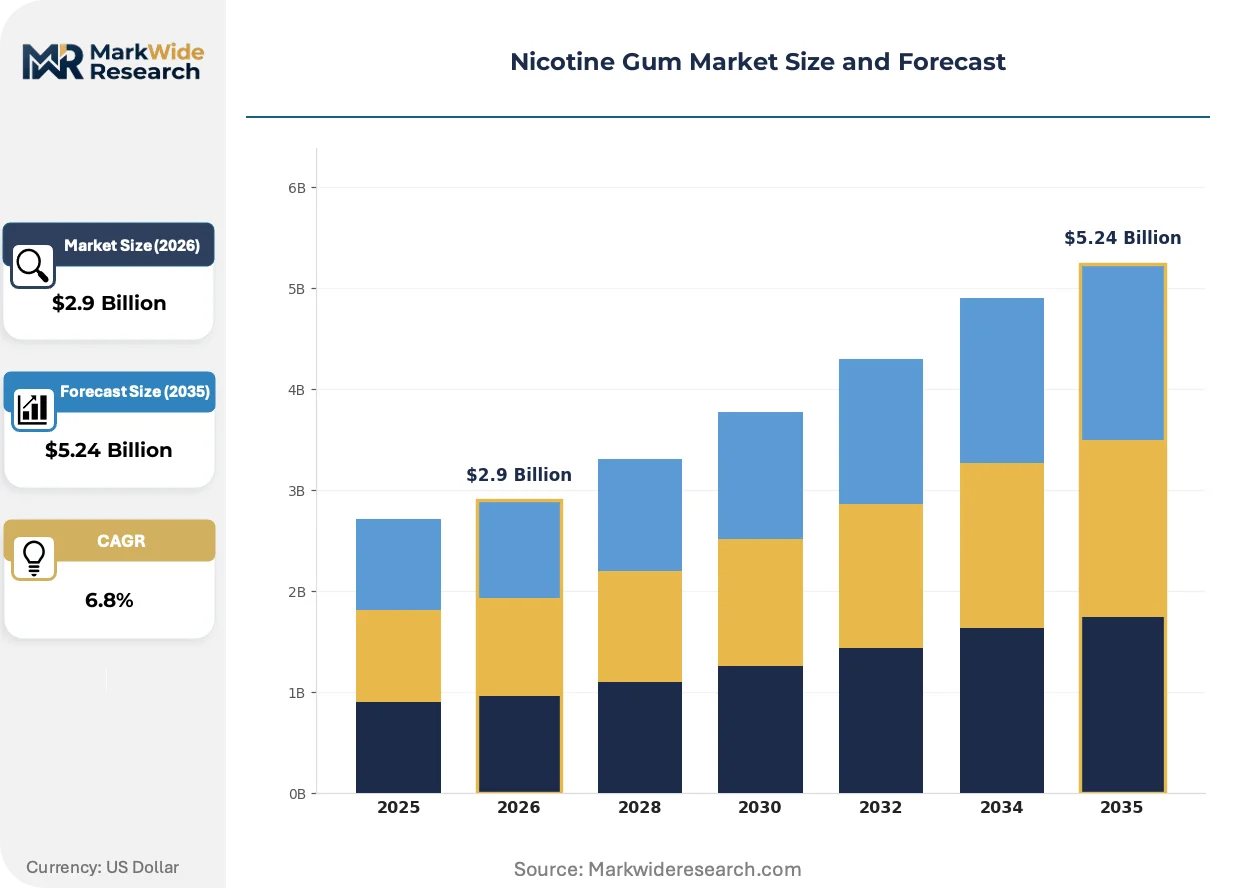
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Gum, Mint Flavored, Fruit Flavored, Cinnamon, Herbal End User: Smoking Cessation Clinics, Pharmacies, Online Consumers, Wellness Centers Distribution Channel: Retail Pharmacies, E-Commerce, Supermarkets, Specialty Stores Dosage Strength: 2 mg, 4 mg, 6 mg, 8 mg |
| Companies Covered | Novartis AG, British American Tobacco plc, Johnson & Johnson, ITC Limited, Cipla Limited, Pfizer Inc., Perrigo Company plc, Haleon plc, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicotine Gum Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reshape how nicotine replacement products reach dependent users. These developments compress legacy channel economics while opening new addressable segments.
Microencapsulated nicotine polacrilex is rewriting release kinetics in next-generation gum formulations. The technology embeds active compounds in lipid-shell matrices that extend buccal absorption windows beyond 45 minutes. Specialty pharmacy chains in Germany and the United States are prioritizing shelf placement for these extended-duration variants. This compression of dosing frequency is eroding volume-based revenue models that relied on higher piece consumption.
EMA's Medical Devices Regulation recalibration is reclassifying certain nicotine delivery formats as combination products requiring notified body oversight. Manufacturers must now submit technical documentation demonstrating quality management system alignment with Annex IX pathways. The 4 mg strength category faces the steepest compliance burden, as higher-dose formats trigger enhanced clinical evidence requirements.
Subscription-based procurement is displacing episodic pharmacy purchases among heavy users. Direct-to-consumer platforms offer algorithm-driven tapering protocols that adjust shipment frequency based on self-reported craving intensity. This behavioral shift concentrates lifetime value capture with platform operators rather than retail intermediaries. The United States exhibits the fastest channel migration, where employer benefit administrators increasingly steer covered employees toward preferred digital dispensaries.
Nicotine Gum Market Segmentation
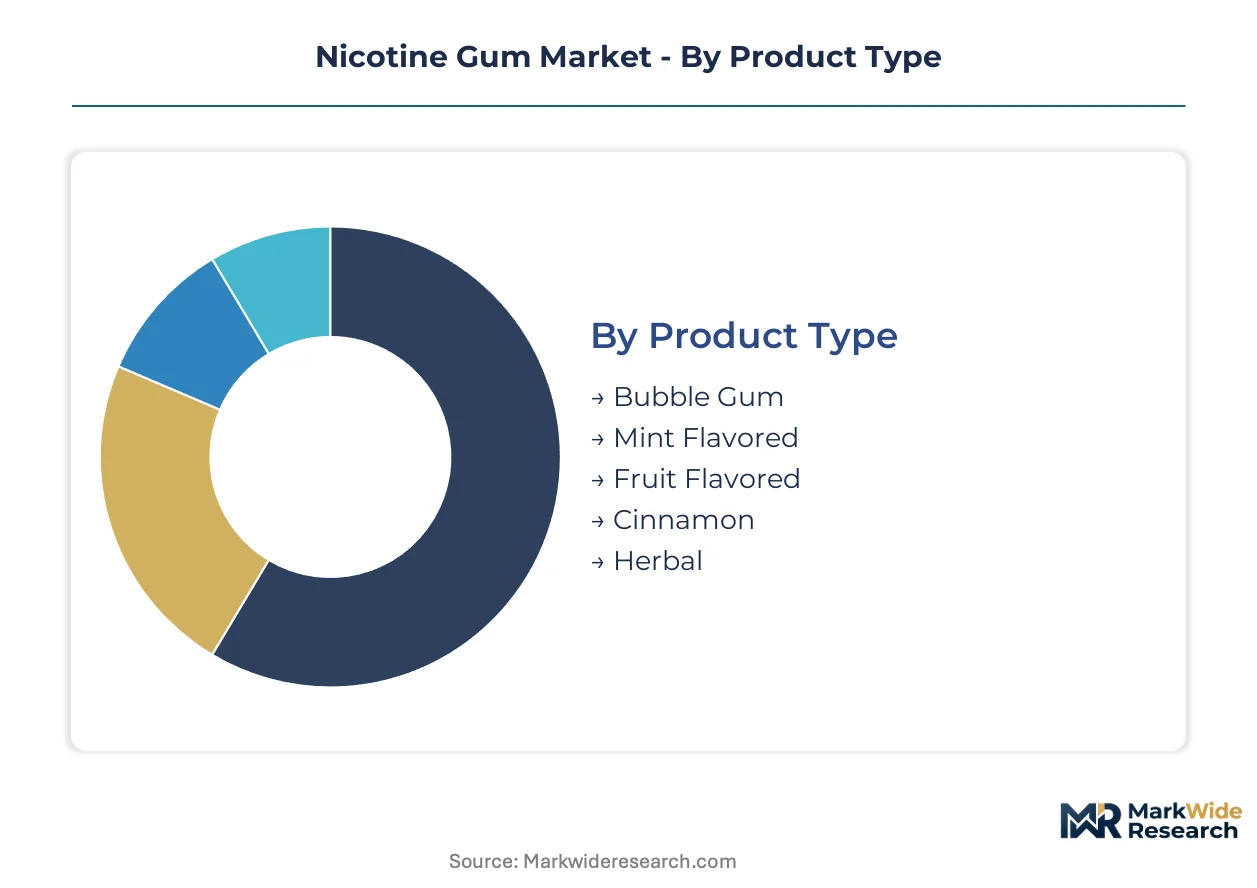
Segmentation in nicotine gum reveals how formulation science, channel economics, and user dependence profiles intersect to create distinct commercial battlegrounds. Each dimension carries implications for regulatory compliance, margin structure, and customer lifetime value capture.
Product Type:
Upgrade cycles in nicotine gum track flavor innovation and bitterness-masking technology rather than hardware obsolescence, with palatability improvements driving repeat purchase loyalty.
- Mint Flavored:Peppermint and spearmint oil formulations dominate pharmacy shelf placement due to familiar sensory association with oral hygiene products. Demand concentrates in the United States and Germany where clinician recommendations prioritize tolerability during stepped cessation protocols.
- Fruit Flavored:Berry and citrus variants embed microencapsulated citric acid buffers that neutralize nicotine alkalinity for extended chewing duration. Japanese consumers in Tokyo and Osaka metropolitan clusters exhibit strongest preference, linked to PMDA-sanctioned reimbursement protocols that emphasize adherence optimization.
- Bubble Gum:Saccharin-sweetened formulations with elastic gum bases target younger adult demographics transitioning from combustible tobacco.
- Cinnamon:Cinnamaldehyde-infused variants leverage thermal sensation to mask withdrawal-related oral paresthesia.
- Herbal:Eucalyptus and licorice root extracts position as natural-positioned alternatives in European specialty pharmacy channels.
Volume placements concentrate in Mint Flavored; the faster expansion belongs to Fruit Flavored.
End User:
Cost tier stratification separates institutional procurement with negotiated formulary access from out-of-pocket retail purchases.
- Pharmacies:Brick-and-mortar dispensaries maintain front-of-counter placement leverage through pharmacist counseling relationships and insurance adjudication infrastructure. United States retail chains capture the majority of employer-sponsored benefit redemptions.
- Online Consumers:Direct-to-user platforms deploy algorithm-driven tapering protocols with automated replenishment scheduling. German statutory health insurance pilot programs are steering covered users toward preferred digital dispensaries.
- Smoking Cessation Clinics:Hospital-affiliated programs in Japan bundle nicotine replacement therapies with municipal counseling services.
- Wellness Centers:Corporate on-site facilities integrate gum distribution into biometric screening workflows.
Revenue concentration sits with Pharmacies; Online Consumers are climbing the fastest.
Distribution Channel:
Application-specific logistics requirements separate cold-chain-agnostic gum products from temperature-sensitive biologics, enabling broader channel penetration.
- Retail Pharmacies:Community and chain dispensaries exploit prescription-to-OTC transition expertise to capture clinician referral flows. FDA labeling clarity has accelerated front-of-counter placement confidence among United States pharmacists.
- E-Commerce:Subscription platforms bypass intermediary margin stacking through direct manufacturer relationships. The United States exhibits steepest channel migration as employer benefit administrators consolidate vendor relationships.
- Supermarkets:Mass merchandisers compete on price transparency for unassisted quit attempts.
- Specialty Stores:Health-focused retailers curate premium-positioned flavor variants with organic positioning.
Transaction volume aggregates at Retail Pharmacies; E-Commerce is gaining share fastest.
Dosage Strength:
Customer type stratification aligns with dependence severity assessed through Fagerström Test protocols, creating stepped-care reimbursement tiers.
- 4 mg:Higher-dose polacrilex complexes serve heavy smokers exceeding one pack daily. EMA Medical Devices Regulation recalibration imposes enhanced clinical evidence requirements on this tier, extending authorization timelines.
- 2 mg:Standard-dose formats anchor maintenance-phase protocols and light-smoker induction. German G-BA assessment frameworks are evaluating full reimbursement elimination of out-of-pocket friction.
- 6 mg:Extended-release matrix formulations target users with prior NRT failure.
- 8 mg:Maximum-strength variants address poly-tobacco users with dual combustible and smokeless habits.
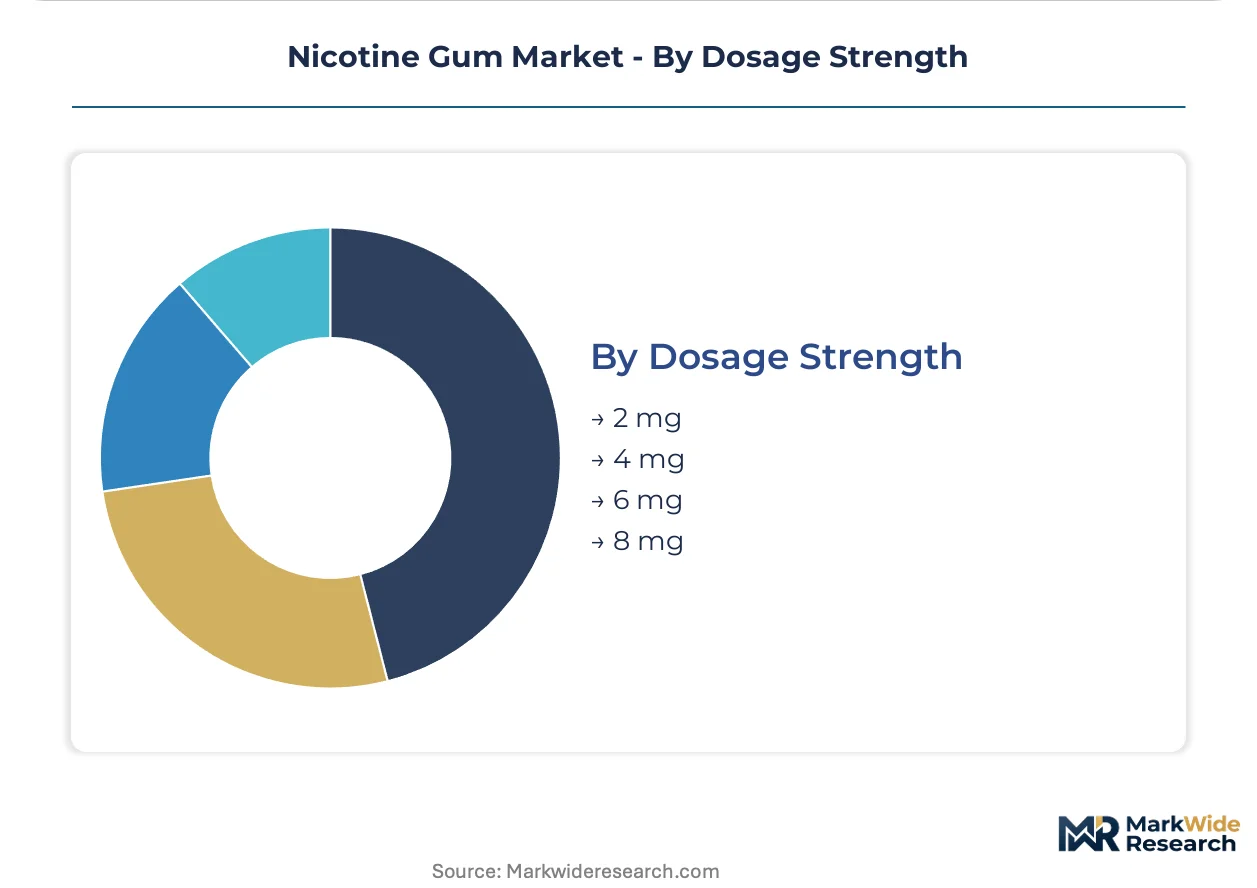
Unit economics favor 4 mg; 2 mg shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates and Singapore concentrate regional distribution hubs for nicotine replacement therapies. Tax-advantaged logistics corridors enable manufacturers to stage inventory for Middle East and Southeast Asian markets. Special economic zone status reduces customs friction for pharmaceutical imports.
United States
Employer-sponsored wellness programs and pharmacy benefit managers drive volume through payroll-deducted access structures. FDA tightened purity benchmarks for nicotine replacement therapies, accelerating pharmacist confidence in front-of-counter placement. Demand clusters in metropolitan corridors including New York, Chicago, and Los Angeles where smoking cessation infrastructure has matured.
Germany
Statutory health insurance evaluation frameworks and pharmacy counseling networks shape procurement patterns. The G-BA assessment protocol is reviewing full reimbursement status for nicotine replacement therapies. Industrial concentration sits in North Rhine-Westphalia and Bavaria, with distribution hubs in Düsseldorf and Munich serving Central European markets.
Japan
Municipal cessation counseling programs and PMDA-sanctioned reimbursement protocols concentrate demand in metropolitan clusters. Japan's pharmaceutical regulator maintains distinct pharmacovigilance reporting thresholds that influence regional labeling obligations. Tokyo, Osaka, and Yokohama anchor volume consumption through integrated hospital-affiliated cessation programs.
India
Contract manufacturing concentration for nicotine polacrilex active pharmaceutical ingredients creates supply-side leverage. CDSCO oversight of drug-device combination products governs import and domestic manufacturing compliance. Production gravity centers on Hyderabad and Ahmedabad, where specialty chemical producers serve finished gum manufacturers in Europe and North America.
United Kingdom
Pharmacy-led smoking cessation services and National Health Service procurement frameworks structure demand access. The Medicines and Healthcare products Regulatory Agency aligns with EMA centralized authorization procedures for market entry. London and the Southeast corridor dominate prescription-to-OTC transition volumes through chain pharmacy networks.
Nicotine Gum Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical incumbents commanding pharmacy shelf placement while generic producers capture institutional procurement. The vendor base organizes around three strategic archetypes: diversified healthcare conglomerates with clinician recommendation networks, tobacco industry pivot players leveraging combustible-to-reduced-risk transitions, and pure-play nicotine replacement specialists. Consolidation pressure operates through vertical integration into active pharmaceutical ingredient supply and direct-to-consumer platform acquisitions.
Among diversified healthcare conglomerates, Johnson & Johnson and Pfizer Inc. exemplify the prescription-to-OTC transition expertise archetype, anchoring clinician-facing distribution channels. British American Tobacco plc occupies a distinct position as a combustible manufacturer pivoting toward reduced-risk product portfolios, securing pharmacy partnerships through existing retail relationships. These three entities represent divergent strategic postures toward nicotine cessation market development.
| Leading Market Players |
|---|
| Novartis AG |
| British American Tobacco plc |
| Johnson & Johnson |
| ITC Limited |
| Cipla Limited |
| Pfizer Inc. |
| Perrigo Company plc |
| Haleon plc |
| GlaxoSmithKline plc |
| Others |
Cost & Logistics Intelligence
Employer-sponsored wellness program consolidation is compressing intermediary margins and forcing manufacturers toward direct procurement relationships that reward volume scale over brand premium. This buyer-side concentration is reshaping how nicotine polacrilex suppliers structure contract terms and allocate capacity across finished gum producers.
Pricing Analysis
Short lead-time premiums command pricing power for contract manufacturers holding buffer inventory of nicotine polacrilex active pharmaceutical ingredient. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated batches from standard GMP-compliant lots and spot-market generic sourcing. Cost compression in economy tiers is intensifying because Indian contract manufacturers are expanding polacrilex fermentation capacity. Employer benefit administrators exhibit lowest price sensitivity due to payroll-deducted structures, while unassisted retail purchasers show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Indian specialty chemical producers in Hyderabad and Ahmedabad who control the majority of nicotine polacrilex supply. Finished gum manufacturing draws from Indian active pharmaceutical ingredient supply, German flavor masking technology, and Malaysian gum base production. Tariff exposure on cross-border pharmaceutical inputs represents the dominant structural risk. Distribution runs through pharmacy benefit manager networks in the United States, statutory insurance procurement in Germany, and hospital-affiliated dispensing in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
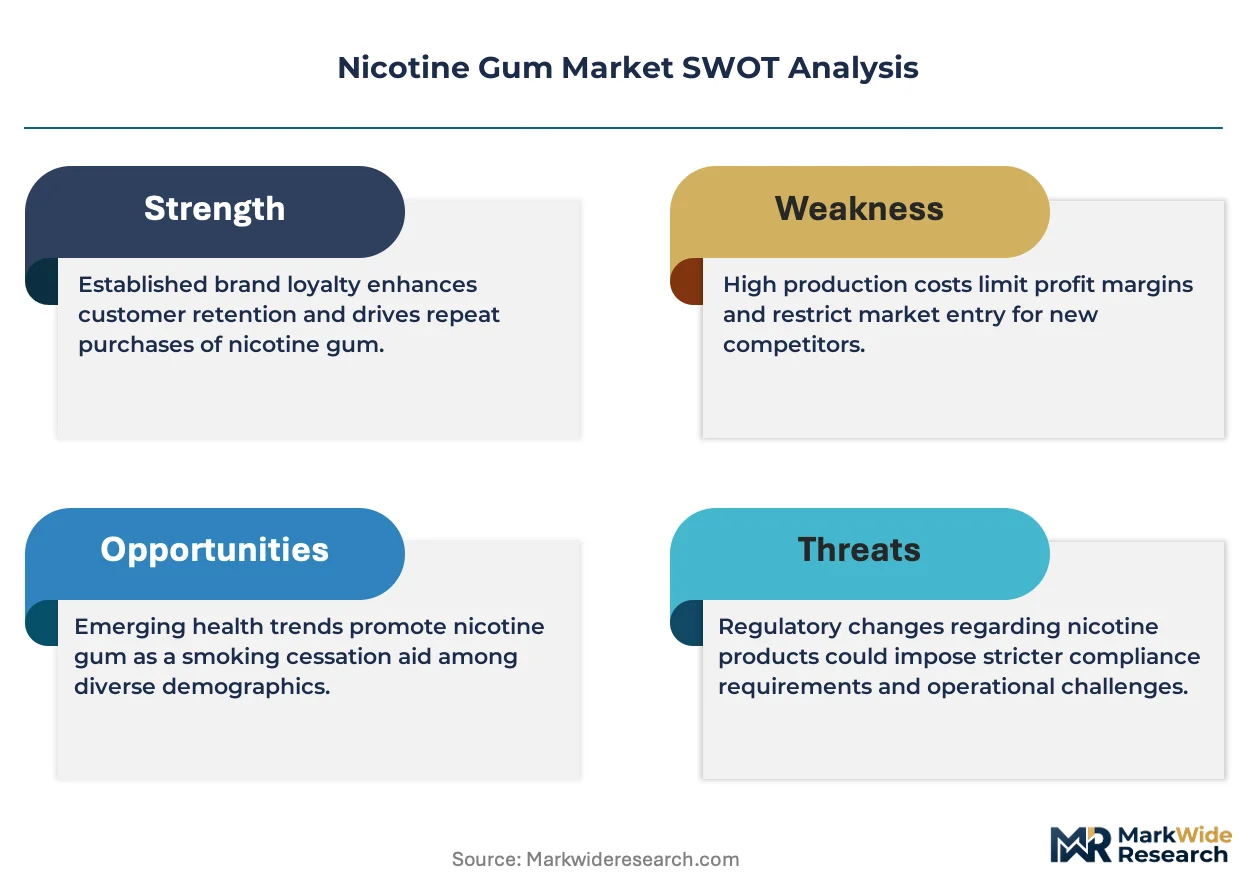
This market operates as a cost-of-compliance story where FDA New Drug Application requirements and EMA centralized authorization procedures erect barrier-to-entry moats that protect validated incumbents from commodity competition.
For Market Incumbents: Anticipate heat-not-burn tobacco device manufacturers capturing switching smokers by securing pharmacy distribution partnerships that mirror your own clinician recommendation networks. Defend position by deepening backward integration into nicotine polacrilex supply and accelerating microencapsulation R&D to extend absorption duration beyond generic competition. Prioritize certification investment for 4 mg extended-release formats ahead of EMA Medical Devices Regulation recalibration. For New Entrants and Emerging Players: The price-point gap between premium microencapsulated formulations and economy generic gum creates white-space opportunity for mid-tier entrants with differentiated flavor technology. Target Germany's statutory health insurance pilot programs as the most penetrable procurement channel, where reimbursement expansion is eliminating out-of-pocket friction. Pursue direct-to-consumer subscription models with algorithm-driven tapering protocols as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with captive regulatory affairs capacity and established pharmacovigilance infrastructure. Long-term viability hinges on vertical integration into active pharmaceutical ingredient supply and platform control over recurring revenue relationships. Watch for FDA prescription-to-OTC reclassification decisions as the signal indicating margin compression or expansion for pharmacy-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Captive nicotine polacrilex production insulates against Indian contract manufacturer concentration risk. |
| Direct-to-Consumer Platform Launch | Subscription algorithms bypass pharmacy intermediation and capture lifetime value from employer benefit steers. |
| Microencapsulation R&D Investment | Extended-release matrices beyond 45 minutes create differentiation against generic 20-30 minute formats. |
| EMA Combination Product Certification | Notified body alignment with Annex IX pathways secures 4 mg tier placement ahead of regulatory recalibration. |
| Corporate Wellness Partnership Expansion | Pharmacy benefit manager consolidation steers covered employees toward preferred vendor relationships. |
Research Approach
Document review covered FDA New Drug Application filings, EMA centralized marketing authorization procedures, and PMDA pharmacovigilance reporting thresholds, complemented by interviews with regulatory affairs leads at nicotine replacement therapy manufacturers, pharmacy benefit managers, and employer wellness program administrators. Secondary validation drew from hospital procurement databases, statutory health insurance reimbursement schedules, and customs records tracking nicotine polacrilex trade flows. Bottom-up demand modeling and top-down market sizing were triangulated against manufacturer capacity disclosures.
Segmented outputs across the projection horizon reflect dosage strength tiers, distribution channel migration patterns, and flavor formulation categories. CAGRs were derived from employer benefit expansion trajectories, prescription-to-OTC transition velocities, and heat-not-burn tobacco device substitution rates. The analytical framework incorporated PMDA-sanctioned reimbursement protocol adoption curves and G-BA assessment framework evaluation timelines as industry-specific forecast inputs.
Inputs from FDA advisory committee minutes and EMA rapporteur assessment reports were available through the study window; gaps in real-time employer benefit administrator enrollment data introduce uncertainty bands around workplace wellness integration assumptions. Forecasts reflect documented regulatory timelines and reimbursement evaluation schedules. Product reclassification decisions, excise tax treatments, and contract manufacturer supply disruptions represent revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Bone Supplements Market