
 Adaptogenic Beverages Market | 2026-2036
Adaptogenic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptogenic Beverages Market Outlook
North American production capacity is tilting toward dedicated adaptogenic beverage facilities as contract manufacturers expand clean-room brewing capabilities. Four Sigmatic leverages its mushroom supply chain relationships to sustain ingredient traceability across its product lines. Rasa specializes in caffeine-free adaptogenic formulations, occupying a distinct niche among consumers seeking alternatives to traditional energy drinks. Moon Juice controls premium positioning through its retail presence and formulation expertise in botanical adaptogens.
Adaptogenic beverages are functional drinks containing standardized extracts of herbs and fungi that modulate cortisol response and support homeostatic balance, typically processed through low-temperature extraction to preserve bioactive compounds. Ready-to-drink formats now dominate shelf space in mainstream retail as convenience overrides the ritual of preparation, while tea-based adaptogenic products retain stronger margins through premium positioning and subscription loyalty. Ashwagandha-containing formulations lead volume among key ingredient segments, though reishi-infused products command higher per-unit pricing in specialty channels where functional mushroom credibility concentrates.
The FDA's dietary supplement enforcement discretion shapes how adaptogenic brands structure their marketing claims, while the USDA organic certification program influences ingredient sourcing premiums and consumer trust thresholds. EFSA's novel food assessments in Europe create divergent approval pathways for emerging adaptogenic ingredients, fragmenting international product portfolios. Stakeholders must monitor evolving caffeine-adjacent regulatory classifications as jurisdictions reassess where adaptogenic stimulants fall relative to conventional energy drink frameworks.
Market Dynamics
The Adaptogenic Beverages Market is being restructured by the FDA's evolving enforcement discretion on dietary supplement labeling, which is forcing brands to recalibrate how they communicate cortisol-modulation claims without triggering drug classification.
Growth Catalysts
- Clean-room brewing capabilities:Contract manufacturers in the United States are expanding dedicated adaptogenic production lines to meet pharmaceutical-grade extraction standards.
- USDA Organic certification:Premium ingredient sourcing premiums are accelerating as consumers demand traceability from soil to shelf.
- Direct-to-consumer channels:Subscription loyalty programs in the United States are capturing recurring revenue from stress-conscious professionals.
Market Restraints
- Reishi supply concentration:Functional mushroom sourcing clusters in specific cultivation regions create input volatility for premium-positioned products.
- EFSA novel food assessments:European approval pathways fragment international portfolios and delay ingredient launches across EU member states.
- Low-temperature extraction capex:Bioactive compound preservation requires specialized equipment that raises barrier to entry for new entrants.
Strategic Opportunities
- Caffeine-free formulation white space:Rasa's niche success demonstrates unmet demand among consumers seeking alternatives to traditional energy drinks.
- IRA wellness incentives:United States policy frameworks may expand tax-advantaged health spending to include functional beverages.
- Ready-to-drink mainstream retail:Convenience formats are displacing preparation rituals in conventional grocery channels.
Industry Challenges
- Botanical standardization expertise:Formulation teams with homeostatic balance measurement capabilities remain scarce.
- Multi-jurisdiction claim alignment:Brands must reconcile FDA, EFSA, and Health Canada positioning without portfolio fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptogenic Beverages Market |
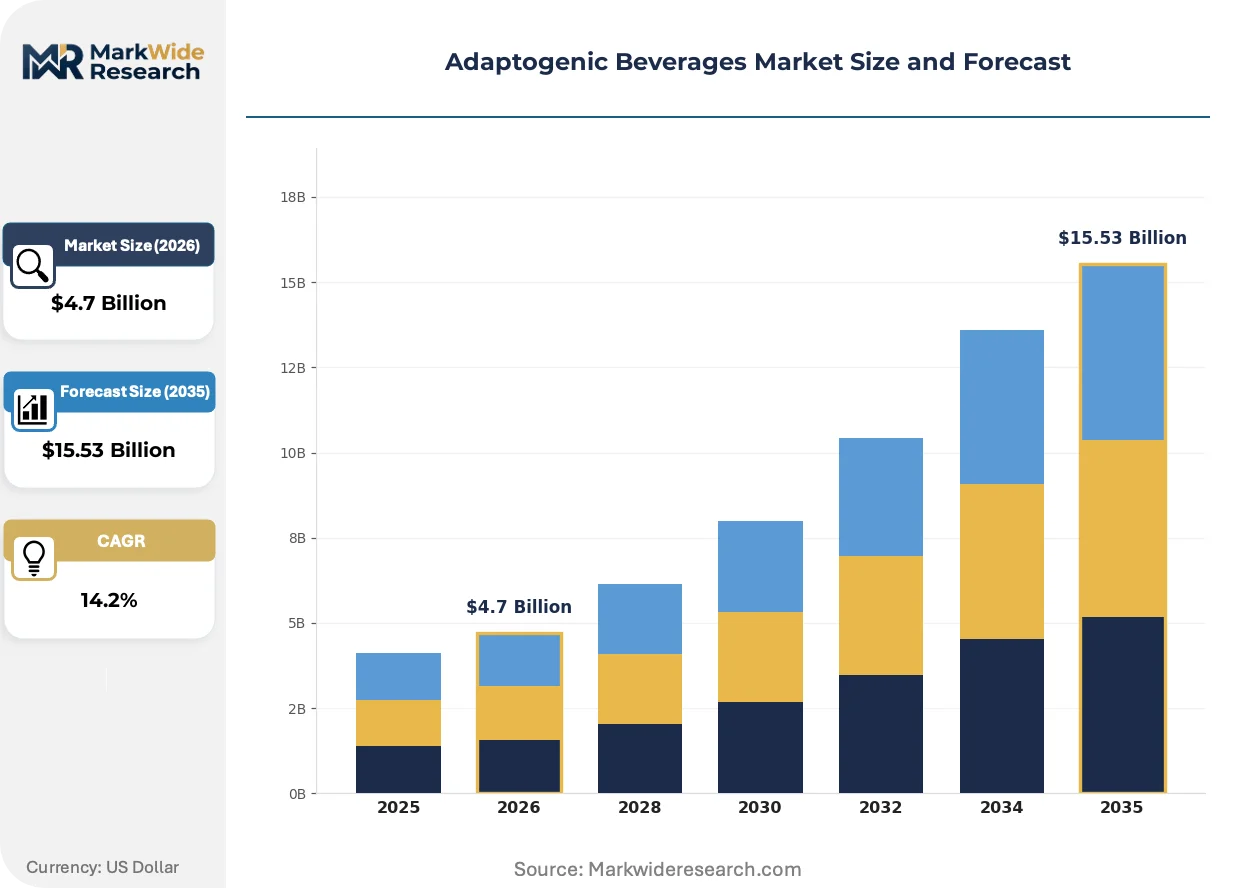
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Teas, Tonics, Powders, Ready-to-Drink Key Ingredient: Ashwagandha, Rhodiola, Holy Basil, Reishi End User: Health-Conscious Consumers, Athletes, Busy Professionals, Wellness Enthusiasts Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Shops |
| Companies Covered | Sunwink, Moon Juice, Four Sigmatic, Rasa, Adapt Drinks, REBBL, Om Mushroom, Peak and Valley, Kin Euphorics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptogenic Beverages Market Strategic Shifts
Formulation science and regulatory navigation are converging to reshape how adaptogenic benefits reach consumers. Three developments are compressing competitive timelines and redefining value capture.
Low-temperature extraction technology is virtualizing the economics of bioactive preservation. Premium brands are adopting vacuum-concentration systems to maintain standardized ashwagandha withanolide content. This equipment shift is virtualizing quality differentiation that previously required artisanal production scales.
EFSA's novel food framework is fragmenting European launch strategies for emerging adaptogenic ingredients. Brands must maintain parallel dossiers for ingredients like lion's mane and cordyceps across divergent member state interpretations. Specialty mushroom products face the steepest compliance burden as mycelium versus fruiting body distinctions lack harmonized classification.
Subscription-driven replenishment is displacing impulse purchase patterns among core consumers. Direct channels are capturing lifetime value through personalized dosing protocols and home delivery. This behavioral pivot concentrates most visibly in United States metropolitan wellness corridors where convenience overrides retail discovery.
Adaptogenic Beverages Market Segmentation
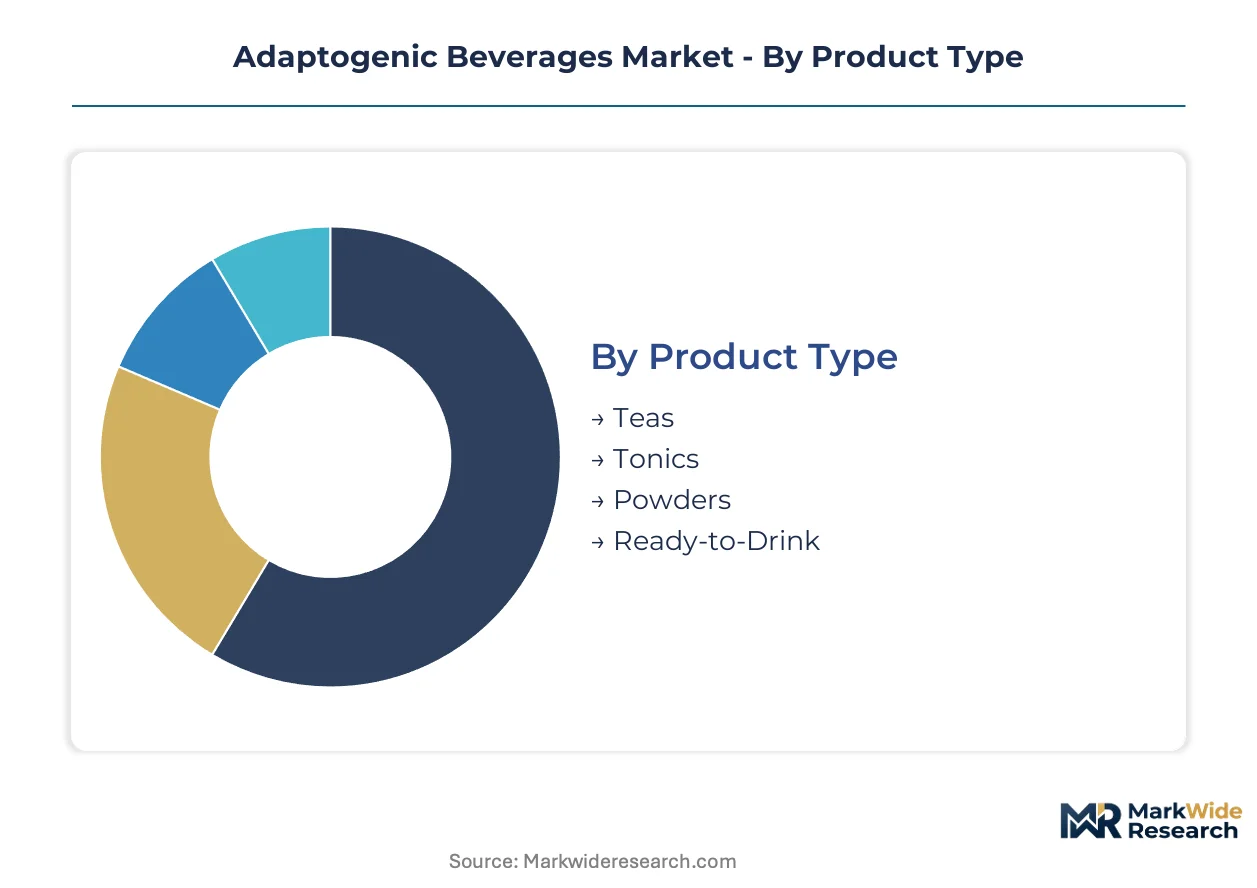
Adaptogenic beverage segmentation reveals how formulation formats, ingredient sourcing, and channel strategies align with distinct consumer stress-management rituals. Each dimension carries implications for shelf stability, bioactive standardization, and recurring purchase patterns.
Product Type:
After-sales intensity varies sharply across formats, with subscription-dependent powders requiring customer success infrastructure that ready-to-drink products bypass entirely.
- Ready-to-Drink:Single-serve cans and bottles dominate conventional grocery velocity. Convenience-seeking professionals in United States metropolitan corridors drive repeat purchase through grab-and-go placement.
- Teas:Loose-leaf and sachet formats retain premium positioning through ritual preparation and higher per-ounce margins. Wellness enthusiasts sustain subscription loyalty where brewing ceremony reinforces habit formation.
- Tonics:Concentrated liquid extracts requiring dilution occupy specialty retail with pharmacist-grade dosing guidance.
- Powders:Bulk canisters and stick packs minimize shipping cost per serving while demanding consumer education on mixing protocols.
By volume, Ready-to-Drink leads. By growth pace, Powders are expanding most quickly.
Key Ingredient:
Cost tier stratification separates commodity botanicals from mycelium-cultivated fungi with multi-month lead times.
- Ashwagandha:Standardized root extracts with measured withanolide content anchor mass-market formulations. Indian cultivation clusters supply cost-competitive raw material to United States contract manufacturers.
- Reishi:Fruiting body extracts command ingredient premiums through dual-extraction protocols. Japanese and Chinese mycology specialists control quality-tier supply for clinical-positioned brands.
- Rhodiola:Arctic-region sourcing constraints limit volume scalability despite documented cortisol-modulation efficacy.
- Holy Basil:Ayurvedic supply chains from Indian subcontinent regions serve niche adaptogenic positioning with religious-ceremony crossover appeal.
By volume, Ashwagandha leads. By margin capture, Reishi shows the steepest expansion trajectory.
End User:
Application context determines dosing frequency and permissible price points across consumption occasions.
- Busy Professionals:Cortisol-conscious knowledge workers prioritize portable formats with caffeine-adjacent positioning. United States corporate wellness programs subsidize subscription trials.
- Athletes:Recovery-focused formulations emphasize anti-inflammatory claims and NSF Certified for Sport verification. Training facilities become sampling nodes.
- Health-Conscious Consumers:Broad wellness seekers respond to USDA Organic and Non-GMO Project verification at mainstream retail.
- Wellness Enthusiasts:Early adopters drive ingredient innovation through direct-to-community feedback loops and biohacking forum influence.
By volume, Health-Conscious Consumers lead. By lifetime value, Busy Professionals are gaining share fastest.
Distribution Channel:
Geographic concentration of wellness infrastructure shapes channel viability beyond simple foot traffic metrics.
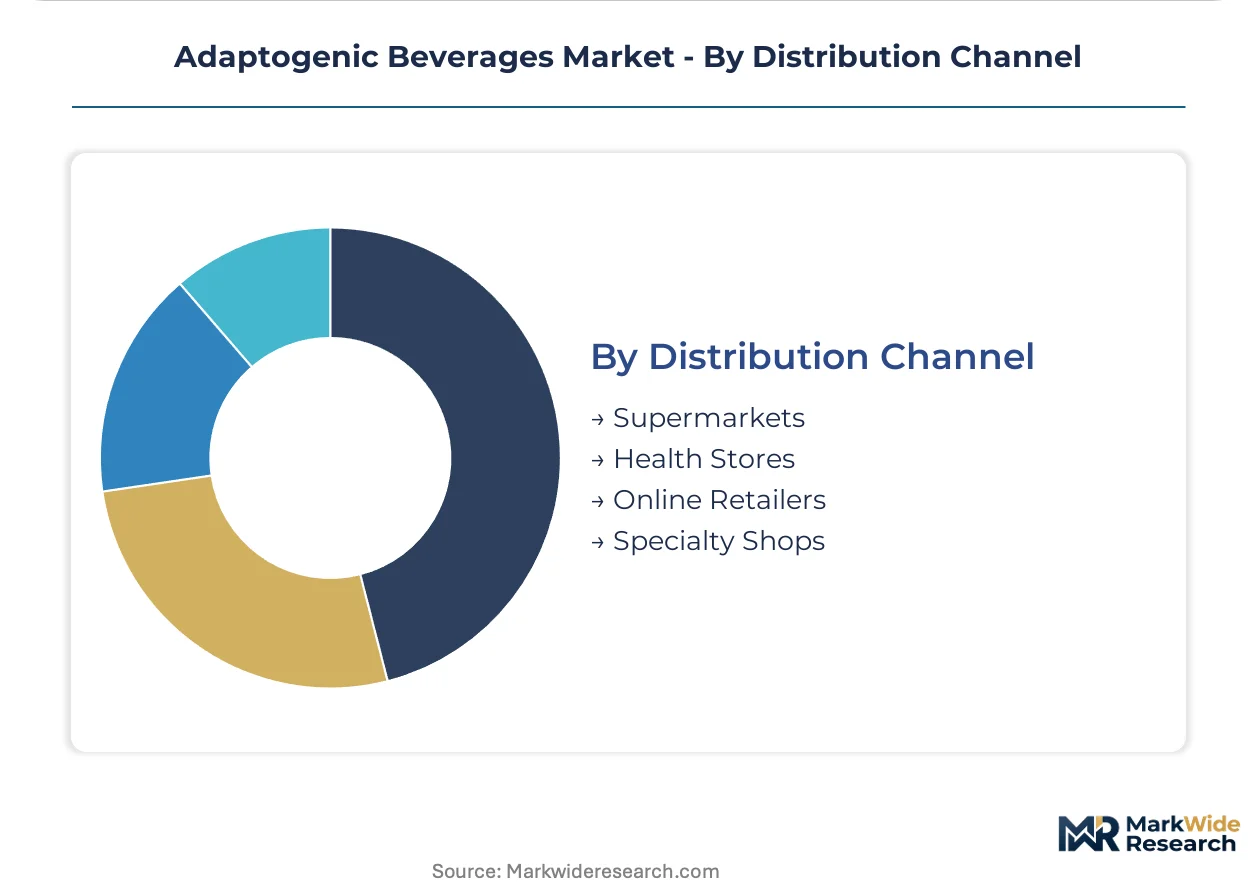
- Online Retailers:Subscription platforms capture recurring revenue through personalized protocol algorithms. United States direct-to-consumer specialists bypass slotting fee barriers.
- Health Stores:Staff-trained environments support complex ingredient storytelling and trial-size conversion. Regional chains in California and New York anchor premium placement.
- Supermarkets:Mass-market velocity requires velocity guarantees and promotional calendar alignment.
- Specialty Shops:Yoga studios and apothecary formats sustain cult brand discovery with minimal competitive shelf density.
By volume, Supermarkets lead. By growth pace, Online Retailers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States consumers prioritize grab-and-go convenience and subscription replenishment, while European buyers emphasize ritual preparation and certified organic sourcing, and Asian markets blend traditional herbal medicine familiarity with modern functional positioning.
United States
Corporate wellness programs and direct-to-consumer subscription platforms drive volume concentration among cortisol-conscious professionals in metropolitan corridors. FDA dietary supplement enforcement discretion shapes how brands structure cortisol-modulation claims without triggering drug classification. Brooklyn and Los Angeles anchor contract manufacturing expansion as clean-room brewing capabilities multiply across dedicated adaptogenic production facilities.
Germany
Pharmacy-channel credibility and biocyclical certification standards elevate consumer trust thresholds for functional mushroom positioning. BfArM novel food consultations create procedural friction for emerging ingredients like lion's mane mycelium. Bavaria hosts specialized extraction equipment manufacturers serving pharmaceutical-grade botanical processing demands.
United Kingdom
Holland & Barrett retail penetration and wellness influencer culture accelerate trial-to-adoption conversion among urban millennials. FSA novel food assessments delay ingredient launches for emerging adaptogens not on the Union list. London concentrates venture-backed brand headquarters and subscription platform engineering talent.
Japan
Traditional kampo medicine familiarity reduces consumer education burdens for reishi and ashwagandha positioning. PMDA functional food notification requirements create distinct compliance pathways separate from supplement frameworks. Tokyo and Osaka anchor premium retail placement where ritual consumption occasions sustain higher per-unit pricing.
Australia
Health practitioner endorsement channels and TGA-listed medicine pathways support clinical credibility claims for stress-modulation formulations. FSANZ novel food determinations govern ingredient approval timelines for emerging botanicals. Sydney and Melbourne concentrate naturopathic practitioner networks that drive professional-channel distribution.
Adaptogenic Beverages Market Competitive Environment
Capability concentration sits with formulation specialists possessing botanical standardization expertise; scale advantage sits with beverage conglomerates leveraging existing distribution infrastructure. The vendor base stratifies across three tiers: venture-backed direct-to-consumer specialists, established functional food platforms, and contract-manufactured private label programs. Dominant competitive moves include strategic partnerships with mycology cultivation operations and portfolio diversification into caffeine-free formulations.
Within the venture-backed specialist tier, Four Sigmatic, Moon Juice, and Rasa occupy distinct positioning vectors. Four Sigmatic exemplifies mushroom supply chain integration and ingredient traceability architecture. Moon Juice anchors premium retail presence and botanical formulation credibility. Rasa represents caffeine-free niche specialization and subscription-driven customer success infrastructure. These three entities collectively demonstrate how divergent capability investments—supply chain control, retail environment design, and formulation differentiation—support sustainable competitive separation in a category where consumer education costs remain elevated.
| Leading Market Players |
|---|
| Sunwink |
| Moon Juice |
| Four Sigmatic |
| Rasa |
| Adapt Drinks |
| REBBL |
| Om Mushroom |
| Peak and Valley |
| Kin Euphorics |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors linking Indian botanical cultivation zones to United States contract manufacturers impose cost volatility that amplifies price stratification between premium reishi formulations and commodity ashwagandha products. This logistics architecture concentrates margin pressure on mid-tier brands lacking dedicated extraction facilities or long-term grower partnerships.
Pricing Analysis
Long-term offtake contracts between mycology cultivators and functional beverage brands anchor pricing stability for reishi and lion's mane inputs, while spot-market procurement dominates commodity botanical transactions. Price differentiation hinges on USDA Organic certification tier and dual-extraction processing depth, with pharmaceutical-grade standardization commanding substantial premiums over conventional extracts. Cost compression in the ashwagandha segment intensifies as Indian cultivation capacity expands and contract manufacturers achieve economies of scale. Wellness enthusiasts demonstrate lowest price sensitivity, accepting per-serving premiums for traceability documentation, while mainstream grocery buyers gravitate toward promotional pricing in ready-to-drink formats.
Supply Chain Analysis
Upstream feedstock for functional mushroom extracts concentrates in Japanese and Chinese mycology cultivation clusters, with fruiting body quality grading determining downstream formulation tier eligibility. Indian subcontinent regions supply standardized ashwagandha root extracts, while Arctic-region rhodiola sourcing remains constrained by climatic cultivation limits. Single-source vulnerability pervades reishi dual-extraction inputs, where specialized Japanese processors control pharmaceutical-grade supply. Distribution runs through direct-to-consumer subscription platforms for premium-positioned brands, while mass-market velocity depends on conventional grocery and pharmacy channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature extraction technology diffusion is disrupting incumbent cost structures, compressing the quality-premium window that previously protected artisanal producers. FDA enforcement discretion on cortisol-modulation claims adds regulatory uncertainty that favors formulation-science investment over marketing-heavy positioning.
For Market Incumbents: Harden supply chain control through captive cultivation partnerships or equity stakes in Japanese mycology operations, insulating against reishi input volatility. Deepen FDA pre-submission engagement on structure-function claim language to preempt enforcement actions that could reclassify adaptogenic beverages as drug products. Prioritize clean-room brewing capacity expansion in Brooklyn and Los Angeles manufacturing clusters to meet pharmaceutical-grade extraction demand. For New Entrants and Emerging Players: Caffeine-free formulation white space among cortisol-conscious professionals represents the most penetrable entry point, with Rasa's subscription infrastructure demonstrating viable unit economics. Direct-to-consumer algorithmic dosing protocols offer differentiation against retail-dependent incumbents, capturing lifetime value through personalized replenishment. Target corporate wellness program procurement channels in United States metropolitan corridors for bulk trial conversions. For Investors and Strategic Acquirers: Formulation teams with homeostatic balance measurement capabilities and established FDA regulatory dossiers represent the highest-conviction acquisition archetype, commanding scarcity premiums as enforcement discretion tightens. Long-term viability rests on navigating multi-jurisdiction claim alignment without portfolio fragmentation. Monitor EFSA novel food determination timelines for lion's mane and cordyceps as inflection indicators for European market expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mycology Cultivation | Captive reishi supply from Japanese fruiting body specialists secures pharmaceutical-grade input quality tier. |
| Clean-Room Brewing Capacity Expansion | Brooklyn and Los Angeles facilities meet FDA pharmaceutical-grade extraction standards for clinical positioning. |
| Direct-to-Consumer Subscription Launch | Algorithmic dosing protocols capture recurring revenue from cortisol-conscious professionals in metropolitan corridors. |
| USDA Organic Certification Investment | Traceability documentation commands premium pricing from wellness enthusiasts demanding soil-to-shelf verification. |
| Novel Food Dossier Preparation | Parallel EFSA and BfArM submissions enable European market entry for emerging adaptogenic ingredients. |
Study Parameters
A standing panel of contract manufacturing executives, mycology cultivation specialists, FDA regulatory affairs consultants, and direct-to-consumer subscription platform operators provided ongoing calibration across the primary research phase. Secondary validation drew from FDA warning letter databases, EFSA novel food register entries, USDA organic certification records, and customs import data for adaptogenic raw materials. Bottom-up volume triangulation across product format segments reconciled with top-down expenditure analysis from corporate wellness program disclosures.
Scenario-bracketing around low-temperature extraction technology adoption rates and FDA enforcement discretion severity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, key ingredient sourcing tier, end-user stress-management context, and distribution channel concentration. CAGRs derived from fitted growth curves incorporating subscription retention benchmarks and retail velocity coefficients. Forecast inputs encompassed mycelium versus fruiting body price differentials and clean-room brewing capacity expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in trans-Pacific freight rates, Indian agricultural input costs, or United States discretionary health spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and extraction technology diffusion rates. Cross-checking against Nielsen retail audit data and corporate wellness program procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Drinking Bottled Mineral Water Market
Beverages
Reconstituted Juice Market
Beverages
CBD-Infused Beverages Market
Beverages
United States Recovery Drinks Market
Beverages
North America Dairy Beverages Market
Beverages
Ginger Ale Market
Beverages
North America Cold Pressed Juices Market
Beverages
Aloe Vera Juice Market
Beverages
Peanut Oil Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Extra Virgin Olive Oil Market
Beverages
Global Electrolyte Drinks Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Breakfast Drink Market
Beverages
Global Squash Drinks Market