
 Germany Gelatin Market | 2026-2036
Germany Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Gelatin Market Foresight
Pharmaceutical supply contracts is rewriting how gelatin volumes flow through Germany's market, with direct sales channels capturing larger commitments from drug manufacturers seeking batch traceability. GELITA AG leverages its Swabian production footprint to sustain just-in-time deliveries for domestic capsule makers. PB Gelatins GmbH anchors its position through specialized pharmaceutical-grade output, while Merck KGaA competes by controlling captive gelatin demand across its own drug manufacturing network.
Gelatin is a collagen-derived protein obtained through controlled hydrolysis of animal connective tissues, typically processed via acid or alkaline pretreatment followed by hot-water extraction, with Bloom strength serving as the standard measure of gel firmness. The material functions primarily as a gelling agent, film-former, and encapsulation medium across pharmaceutical, food, and technical applications. Gelatin powder dominates pharmaceutical formulations due to its precise dosing and storage stability, while liquid gelatin captures growth in automated capsule production lines where viscosity control reduces manufacturing cycle times. Granulated gelatin occupies a narrower niche among confectionery makers prioritizing rapid dissolution, with margin pools concentrating in pharmaceutical-grade certifications rather than commodity food variants.
Germany's Federal Institute for Drugs and Medical Devices enforces EU MDR compliance for medical-grade gelatin, while the German Federal Ministry of Food and Agriculture oversees animal-by-product safety under national implementations of EU hygiene regulations. REACH registration requirements from ECHA further constrain imported raw materials, elevating compliance costs for non-European suppliers. Stakeholders must monitor how the EU Green Deal's emerging bioeconomy targets will reshape animal-derived versus fermentation-based gelatin alternatives.
Market Dynamics
Pharmaceutical-grade gelatin procurement is tightening around batch-level traceability requirements, with southern Germany's capsule manufacturers now demanding origin documentation that stretches from slaughterhouse to extraction facility.
Growth Catalysts
- EU MDR compliance deadlines:Medical device manufacturers across Bavaria and Baden-Württemberg are accelerating gelatin qualification to meet stricter biocompatibility documentation requirements.
- Softgel capsule expansion:Nutraceutical brands are driving gelatin volume through omega-3 and probiotic encapsulation formats that require specialized bloom strength specifications.
- Swabian production cluster density:Concentrated gelatin manufacturing around Eberbach creates logistics efficiencies that shorten lead times for domestic pharmaceutical buyers.
Market Restraints
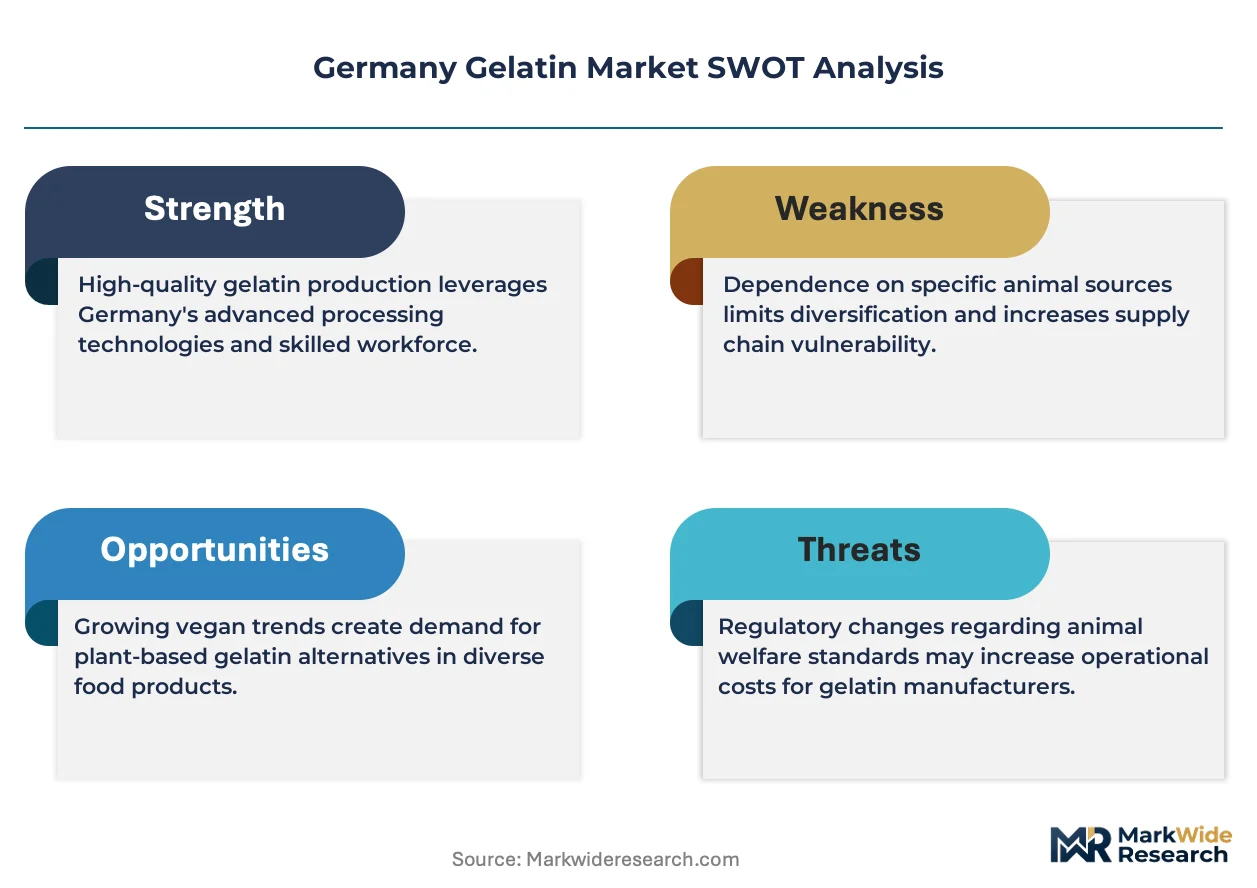
- Porcine raw material concentration:Overreliance on pigskin-derived gelatin exposes processors to African swine fever outbreaks in Eastern European sourcing regions.
- ECHA REACH registration burdens:Imported collagen hydrolysates face escalating compliance documentation costs that disadvantage non-EU suppliers.
- Plant-based capsule substitution:HPMC and pullulan alternatives are capturing vegan-label pharmaceutical contracts from gelatin incumbents.
Strategic Opportunities
- Fermentation-derived collagen platforms:Precision fermentation technologies are opening pathways to animal-free gelatin with identical functional properties.
- EU Green Deal bioeconomy incentives:Circular economy funding streams support gelatin recovery from slaughterhouse waste streams that previously entered rendering.
- Direct-to-manufacturer digital platforms:Blockchain-enabled procurement systems are disintermediating traditional distributor relationships for large-volume pharmaceutical accounts.
Industry Challenges
- Pharmaceutical-grade certification timelines:New production lines require 18-24 month validation periods under German Federal Institute for Drugs and Medical Devices protocols.
- Skilled extraction technician scarcity:Acid and alkaline hydrolysis process expertise is concentrating among aging workforces in traditional gelatin-producing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Gelatin Market |
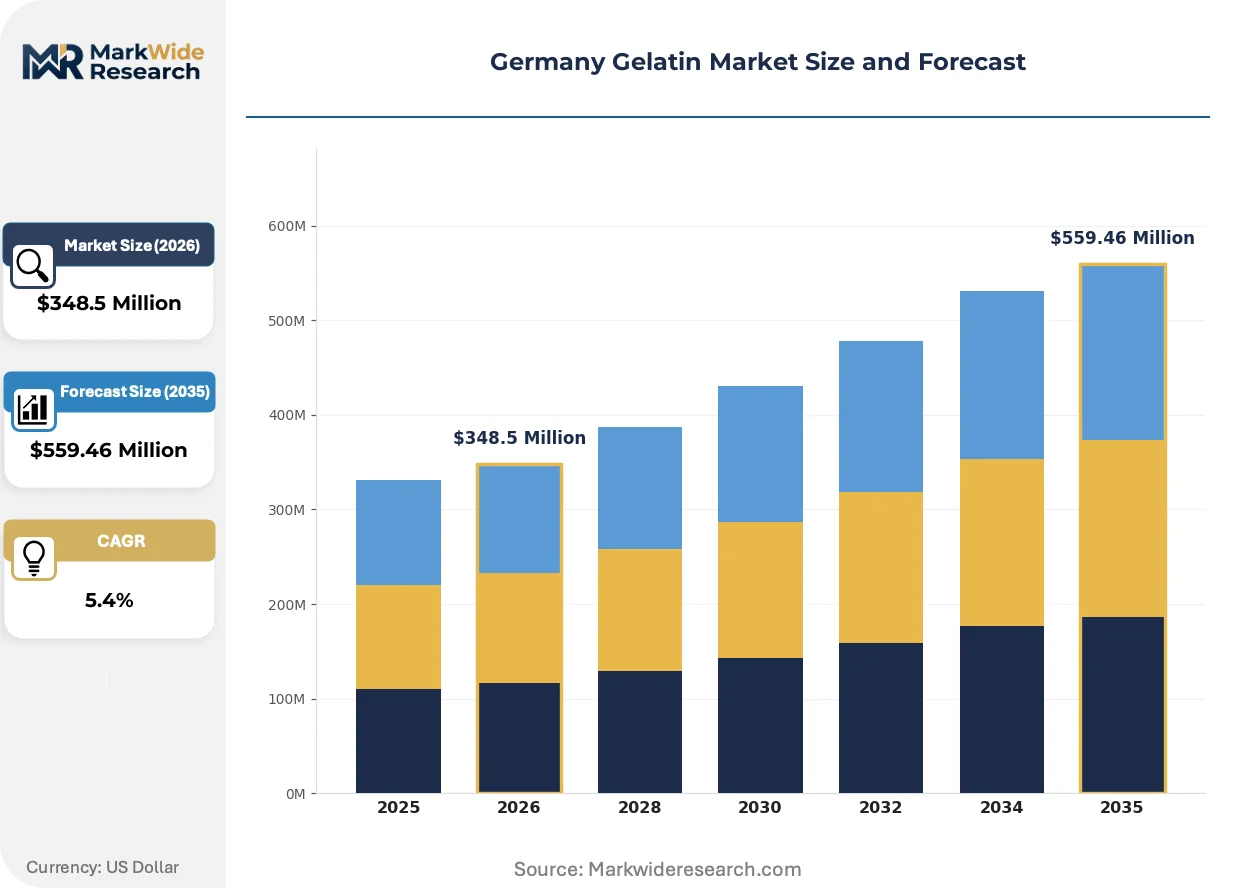
| Market Size in 2026 | $348.5 Million |
| Market Size in 2035 | $559.46 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin Powder, Gelatin Sheets, Granulated Gelatin, Liquid Gelatin Application: Pharmaceuticals, Food & Beverage, Cosmetics, Photography End User Industry: Drug Manufacturing, Confectionery Makers, Personal Care, Film Producers Supply Chain Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | PB Gelatins GmbH, Tessenderlo Group, GELITA AG, Merck KGaA, Weishardt Group, Rousselot, Ewald-Gelatine GmbH, Kraemer GmbH, NITTA GELATIN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Gelatin Market Shifts & Advancements
Functional gelatin specifications are fragmenting as end-users demand performance-tuned variants rather than commodity grades, while sustainability verification becomes a parallel purchasing criterion alongside technical parameters.
Precision fermentation collagen is hybridizing with traditional extraction methods as pharmaceutical manufacturers run parallel qualification studies on recombinant proteins. Mid-sized drug makers in Baden-Württemberg are piloting hybrid sourcing models that blend animal-derived and fermentation-based gelatin within single product portfolios. This dual-track approach is compressing the timeline for full-scale alternative protein adoption while maintaining existing supply relationships.
REACH registration requirements from ECHA are tightening documentation standards for imported raw collagen materials. German gelatin processors now face expanded substance data obligations that increase administrative overhead for non-European supply chains. Pharmaceutical-grade segment participants are responding by regionalizing raw material procurement within EU member states to reduce regulatory friction.
Just-in-time inventory models are displacing bulk stockpiling among southern Germany's capsule manufacturers. Large pharmaceutical buyers are consolidating purchase orders into quarterly contracts with embedded price adjustment clauses rather than spot market transactions. This behavioral shift concentrates most visibly among Merck KGaA's network and affiliated mid-tier drug producers in the Rhine-Neckar metropolitan region.
Germany Gelatin Market Segmentation
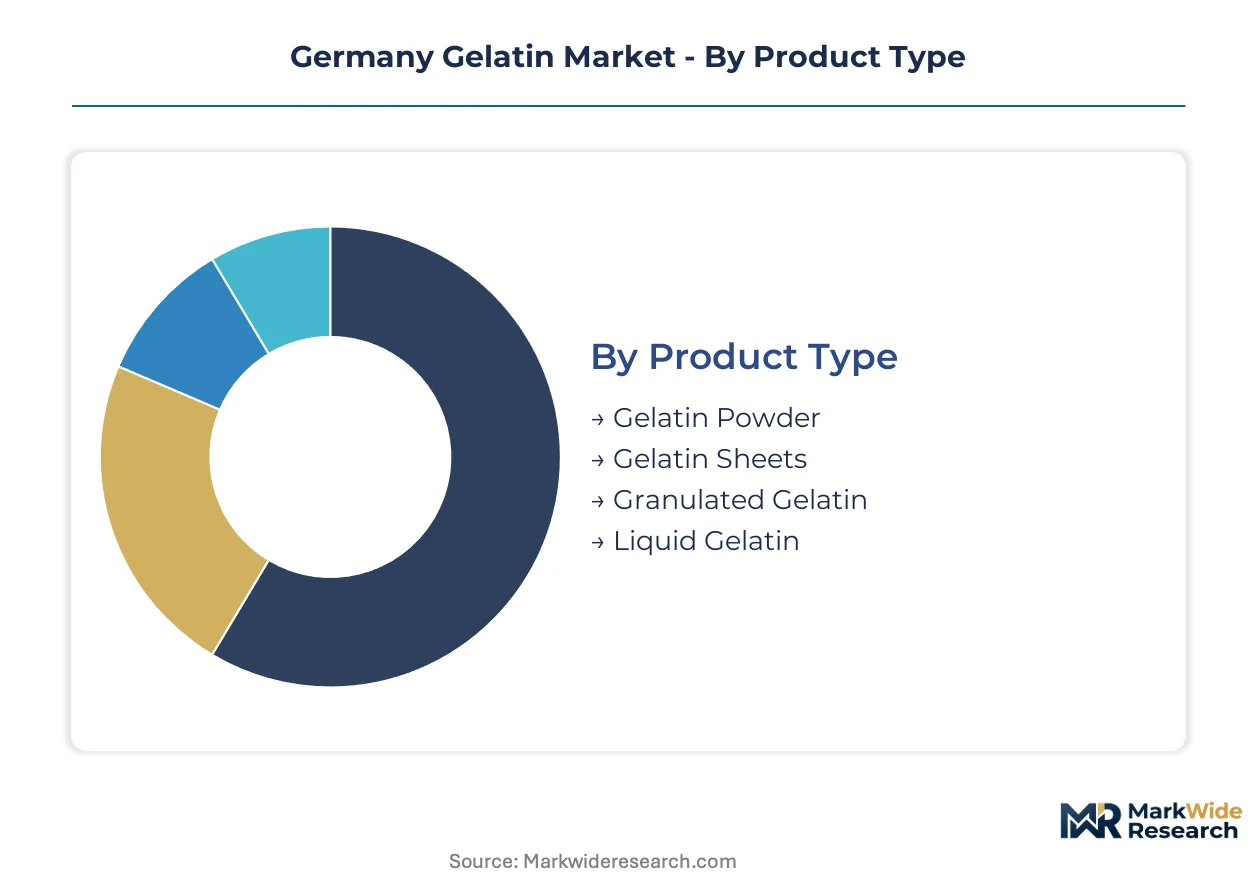
Segmentation in Germany's gelatin market reveals how procurement cycles, certification requirements, and application-specific formulations create divergent margin pools across product categories. Manufacturers optimize production schedules and inventory models differently for pharmaceutical-grade batches versus food-grade commodities.
Product Type:
Gelatin powder turns inventory fastest in Bavarian capsule plants, while liquid gelatin sits longest in storage due to temperature-controlled handling requirements and shorter shelf stability.
- Gelatin Powder:Dried protein extract standardized by Bloom strength enables precise dosing in hard-shell capsule manufacturing. Drug manufacturers in Baden-Württemberg favor this format for its 24-month stability under ambient warehouse conditions, though humidity control remains critical during summer months.
- Liquid Gelatin:Pre-hydrated collagen solution with controlled viscosity for automated softgel encapsulation lines. Confectionery producers in the Rhineland deploy this format for gummy manufacturing where rapid setting reduces mold cycle times, yet refrigerated logistics constrain geographic sourcing radius.
- Gelatin Sheets:Dehydrated film layers used in professional culinary applications and specialized pharmaceutical coatings.
- Granulated Gelatin:Rapid-dissolution particles targeting artisanal confectioners and small-batch food processors.
Gelatin powder anchors the volume base while liquid gelatin gains share at the steepest rate.
Application:
Cost tiers separate pharmaceutical applications demanding EMA-grade certification from commodity food uses where price sensitivity dominates purchasing decisions.
- Pharmaceuticals:Medical-grade gelatin for capsule shells, tablet binders, and vaccine stabilizers requires full EU MDR traceability documentation. Manufacturers in southern Germany pay certification premiums to secure batch-level origin records from slaughterhouse through extraction facility.
- Food & Beverage:Gelling agent for confectionery, dairy, and meat products operates under FSSAI-aligned EU hygiene standards. Bavarian confectioners source lower-Bloom variants for marshmallow and gummy applications where clarity and mouthfeel specifications vary by brand positioning.
- Cosmetics:Collagen hydrolysate for skincare formulations and hair care products.
- Photography:Traditional silver halide emulsion binder serving niche fine-art and archival markets.
Pharmaceutical applications command premium pricing tiers while food and beverage represents the broadest volume foundation.
End User Industry:
Customer concentration patterns show drug manufacturing consolidating purchase orders into quarterly contracts, whereas confectionery makers maintain spot-market flexibility.
- Drug Manufacturing:Large-volume buyers including Merck KGaA and mid-sized Baden-Württemberg producers negotiate direct supply agreements with embedded price adjustment clauses. These stakeholders demand 18-24 month validation documentation for any new gelatin source under German Federal Institute for Drugs and Medical Devices protocols.
- Confectionery Makers:Haribo and regional artisanal producers prioritize rapid-dissolution granulated formats for gummy and marshmallow production. Seasonal demand spikes around holiday periods create inventory management challenges for processors lacking forward-contract coverage.
- Personal Care:Cosmetic formulators sourcing collagen peptides for anti-aging and moisturizing products.
- Film Producers:Archival photography specialists and motion picture laboratories requiring high-clarity emulsion binders.
Drug manufacturing concentrates procurement spend among few suppliers while confectionery makers fragment orders across multiple channels.
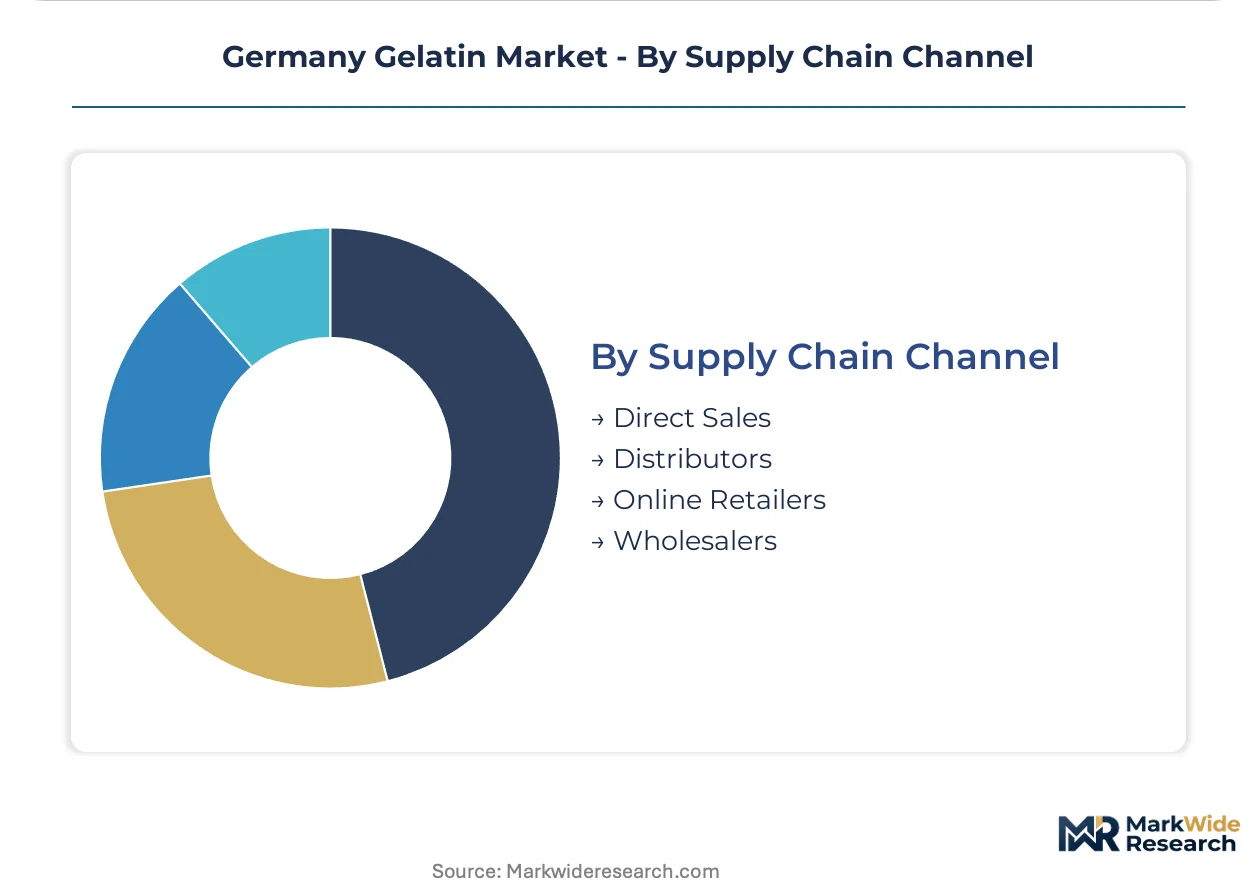
Supply Chain Channel:
Margin structures vary sharply between direct sales with embedded technical service and distributor-mediated transactions carrying 12-18% markups.
- Direct Sales:Large pharmaceutical accounts in the Rhine-Neckar metropolitan region negotiate factory-direct relationships with GELITA AG and PB Gelatins GmbH. These arrangements include just-in-time delivery guarantees and dedicated quality liaison support.
- Distributors:Regional chemical and ingredient distributors serve mid-sized food processors lacking volume thresholds for direct manufacturer engagement.
- Online Retailers:E-commerce platforms capture artisanal and small-batch buyers seeking specialty grades in sub-ton quantities.
- Wholesalers:Traditional bulk handlers moving commodity food-grade gelatin to decentralized processing operations.
Direct sales channels capture the steepest expansion trajectory as pharmaceutical buyers consolidate procurement functions, while distributors retain relevance among fragmented food industry accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in southern Germany's pharmaceutical corridor while northern food-processing clusters operate on thinner margins. Bavaria and Baden-Württemberg command certification premiums that Rhineland confectioners cannot extract. This regional asymmetry shapes procurement patterns across the federal structure.
Bavaria
Pharmaceutical capsule manufacturing and vaccine stabilizer production drive gelatin consumption in the Munich-Ingolstadt corridor. The German Federal Institute for Drugs and Medical Devices enforces EU MDR traceability standards that elevate procurement costs. Merck KGaA's Darmstadt-adjacent operations and mid-sized drug makers in Upper Bavaria anchor regional demand through direct supply agreements.
Baden-Württemberg
Softgel nutraceutical expansion and omega-3 encapsulation formats require specialized bloom strength specifications. REACH registration requirements from ECHA constrain imported collagen hydrolysates, favoring domestic processors. The Swabian production cluster around Eberbach sustains just-in-time delivery networks for regional pharmaceutical buyers.
North Rhine-Westphalia
Confectionery manufacturing and gummy production consume lower-Bloom variants where price sensitivity dominates purchasing decisions. The German Federal Ministry of Food and Agriculture oversees animal-by-product safety under EU hygiene regulations. Cologne-Düsseldorf processors face seasonal demand spikes that strain inventory management without forward-contract coverage.
Lower Saxony
Meat processing waste streams and slaughterhouse rendering operations supply raw collagen materials to regional gelatin producers. EU Green Deal bioeconomy incentives support circular economy funding for waste stream recovery. The Hanover-Brunswick corridor hosts mid-scale processors serving food industry accounts lacking pharmaceutical-grade certification requirements.
Hesse
Personal care collagen peptide formulation and cosmetic hydrolysate demand create niche consumption pockets. ECHA substance data obligations increase administrative overhead for processors sourcing outside EU member states. The Frankfurt-Rhine-Main metropolitan region concentrates cosmetic formulators seeking rapid-dissolution granulated formats.
Germany Gelatin Market Competitive Landscape
Vertically integrated multinationals and specialized regional processors split the market into distinct capability tiers. Consolidation pressure intensifies as pharmaceutical buyers consolidate purchase orders into quarterly contracts with embedded price adjustment clauses. Two strategic archetypes dominate: captive-demand conglomerates controlling internal supply chains, and independent processors competing on certification breadth. Capacity expansion and backward integration into raw material sourcing represent the dominant competitive moves.
Among Germany-based operators, GELITA AG and PB Gelatins GmbH occupy positions exemplifying the specialized processor archetype, while Merck KGaA represents captive-demand integration. GELITA AG leverages its Swabian production footprint for just-in-time pharmaceutical deliveries. PB Gelatins GmbH anchors its market presence through pharmaceutical-grade output specialization. Merck KGaA controls internal gelatin demand across its own drug manufacturing network, reducing external procurement exposure.
| Leading Market Players |
|---|
| PB Gelatins GmbH |
| Tessenderlo Group |
| GELITA AG |
| Merck KGaA |
| Weishardt Group |
| Rousselot |
| Ewald-Gelatine GmbH |
| Kraemer GmbH |
| NITTA GELATIN |
| Others |
Supply & Pricing Matrix
African swine fever exposure in Eastern European pigskin sourcing regions determines both the spread between pharmaceutical-grade premiums and commodity food-grade pricing and the geographic restructuring of collagen procurement networks. German processors now pay certification premiums to secure EU-origin raw materials that bypass REACH documentation burdens while Rhineland confectioners absorb spot-market volatility without contractual protection.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical batches from standard food-grade commodities. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR certification depth, Bloom strength specification, and embedded technical service. Cost compression in the food-grade tier is intensifying because Baltic and Polish slaughterhouse waste streams face veterinary border controls. Drug manufacturers show least price sensitivity due to 18-24 month validation lock-in, while artisanal confectioners fragment orders across spot markets.
Supply Chain Analysis
Contract manufacturing concentration sits with GELITA AG's Eberbach complex and PB Gelatins GmbH's specialized pharmaceutical lines, which together anchor domestic extraction capacity. Geographic supply draws from Germany, Belgium, and France for EU-compliant collagen, with residual dependence on Brazilian bovine hides for specific Bloom grades. Raw material inputs hinge on porcine skins, bovine bones, and acid/alkaline pretreatment chemicals. Single-source vulnerability concentrates in Swabian just-in-time networks serving Merck KGaA's Darmstadt-adjacent operations. Distribution runs through direct sales channels for pharmaceutical accounts and regional chemical distributors for food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German gelatin demand functions as a service-attach opportunity where technical validation support and batch-level traceability documentation expand faster than base commodity tonnage. Recurring revenue from certification maintenance and regulatory liaison services now outpaces volume growth in the pharmaceutical segment.
For Market Incumbents: Entrench position by deepening captive supply of porcine raw materials through slaughterhouse partnerships in Lower Saxony and Baden-Württemberg. Expand pharmaceutical-grade certification breadth to capture nutraceutical softgel expansion before fermentation-based alternatives achieve price parity. Plant-based capsule substitution from HPMC and pullulan suppliers represents the core threat requiring defensive R&D in hybrid animal-fermentation product portfolios. For New Entrants and Emerging Players: Pursue white-space in precision fermentation collagen platforms serving mid-sized Baden-Württemberg drug makers running parallel qualification studies. Target the personal care collagen peptide segment in Hesse's Frankfurt-Rhine-Main corridor where pharmaceutical-grade validation requirements do not apply. Go-to-market angle should emphasize sustainability verification aligned with EU Green Deal bioeconomy incentives rather than price undercutting. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized processors with pharmaceutical-grade certification infrastructure over commodity food-grade operators. Long-term viability over the next decade hinges on successful navigation of animal-free transition pathways while maintaining existing supply relationships. Acquisition target archetype: mid-scale Swabian processors with embedded just-in-time delivery contracts and aging workforce replacement needs. Signal to watch is ECHA expansion of REACH substance data obligations to fermentation-derived collagen alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughterhouse Waste Streams | Secures EU-origin raw materials that bypass REACH documentation burdens for ECHA compliance. |
| Pharmaceutical-Grade Certification Expansion | Captures nutraceutical softgel volume from omega-3 and probiotic brands in Baden-Württemberg. |
| Precision Fermentation Platform Development | Opens animal-free pathways with identical Bloom strength specifications for EU MDR compliance. |
| Blockchain-Enabled Procurement Systems | Disintermediates distributor relationships for large-volume pharmaceutical accounts in Bavaria. |
| EU Green Deal Bioeconomy Funding Capture | Supports circular economy gelatin recovery from rendering waste streams in Lower Saxony. |
Research Methodology
The analysis maps pharmaceutical-grade gelatin, food-grade commodities, and technical applications, each validated through procurement directors at capsule manufacturers, quality assurance leads at drug makers, and regulatory affairs specialists navigating EU MDR and REACH frameworks. Primary interviews with plant managers at Swabian extraction facilities and distribution channel partners in the Rhineland combined with secondary validation from ECHA substance registrations, German Federal Institute for Drugs and Medical Devices guidance documents, and EU trade data. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Assumptions held fixed include current EU MDR compliance timelines and ECHA REACH registration scope, while variables included fermentation technology cost curves and African swine fever geographic spread. Segmentation dimensions spanned product format, application grade, end-user industry concentration, and supply chain channel structure across the projection horizon. CAGRs derived from weighted average of historical volume trends and forward demand elasticity estimates, with specific inputs from pharmaceutical production indices and confectionery seasonal demand patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by fermentation-based collagen entrants or sudden ECHA regulatory expansion would shift outcomes substantially. Quarterly review of ECHA guidance updates, veterinary border control announcements, and pharmaceutical buyer consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Smoked Yeast Market
Ingredients
Caramel Malt Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Oat Grass Powder Market
Ingredients
Citrus Fiber Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Cocoa Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Glucosylglycerol Market