
 Japan Whey Protein Market | 2026-2036
Japan Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Whey Protein Market Foresight
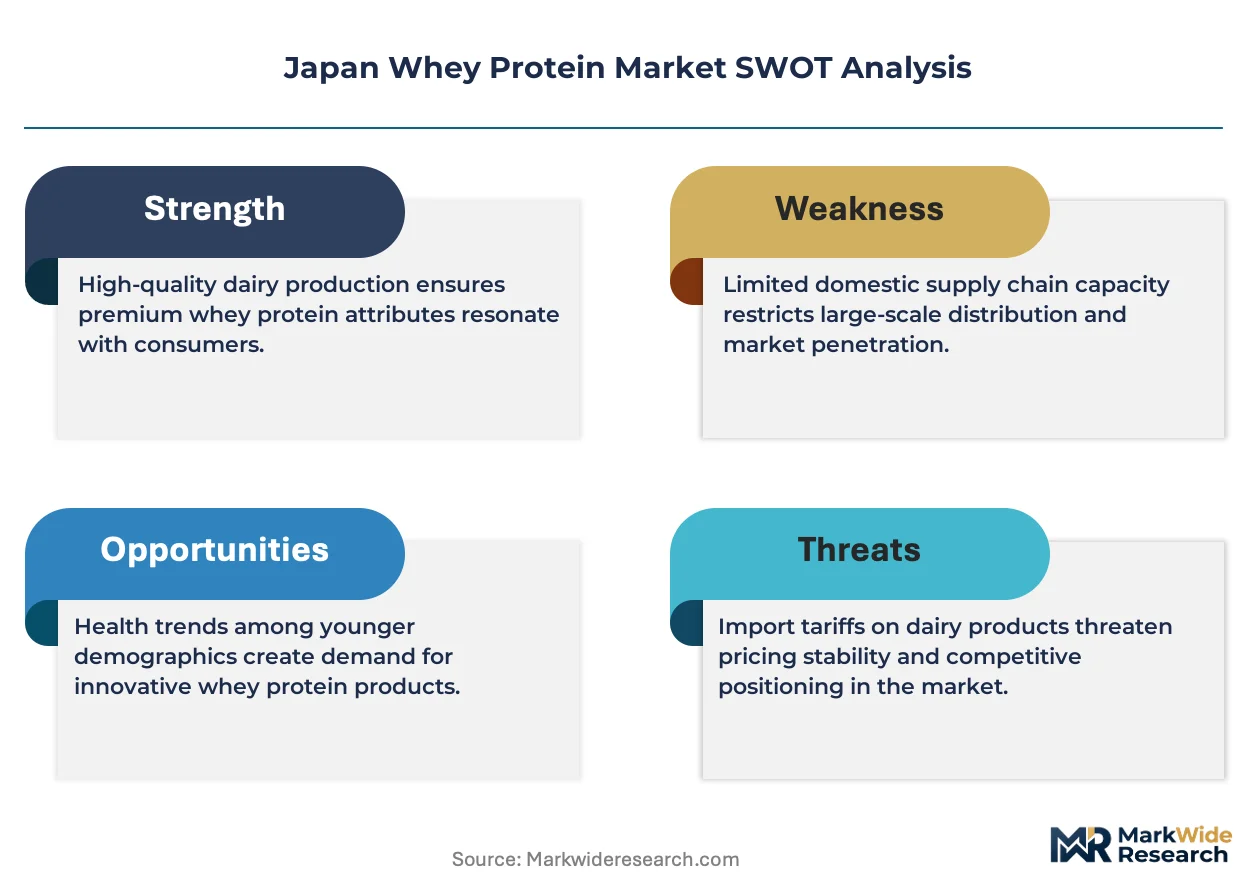
Buyer concentration in Japan's whey protein channel is decoupling as specialty fitness boutiques and direct-to-consumer platforms fragment what supermarkets once dominated. Morinaga Milk Industry Co., Ltd. leverages its domestic dairy heritage to control shelf positioning in conventional retail. Meiji Holdings Co., Ltd. anchors its portfolio through integrated milk-to-protein supply chains. Fonterra Co-operative Group Limited competes on whey isolate purity grades tailored to discerning Japanese buyers.
Whey protein comprises the globular proteins isolated from liquid whey, a cheese-making byproduct, typically processed through membrane filtration or ion exchange to achieve protein concentrations ranging from 35% to 90% depending on grade. Its primary commercial purpose centers on delivering complete amino acid profiles for muscle protein synthesis in sports nutrition and clinical dietary applications. Isolate formats command premium positioning among athletes and bodybuilders seeking minimal lactose content, while hydrolysate variants attract formulation interest from functional food developers targeting rapid absorption claims. General consumers represent the fastest-expanding end-user pool as protein fortification extends beyond traditional sports use into everyday wellness routines.
Japan's Ministry of Health, Labour and Welfare oversees FOSHU and Foods with Function Claims frameworks that determine permissible health statements on whey protein products. Consumer Affairs Agency labeling rules enforce strict protein content declarations and allergen warnings that shape packaging and marketing approaches. METI industrial standards further influence manufacturing quality benchmarks for imported and domestically produced powders. Stakeholders must monitor evolving claims regulations and shifting retail channel power as online platforms and specialty stores reshape how Japanese consumers discover and purchase protein products.
Market Dynamics
Aging demographics and FOSHU certification requirements are restructuring how whey protein manufacturers formulate, label, and distribute products across Japan's fragmented retail landscape.
Growth Catalysts
- FOSHU pathway maturation:Japan's Ministry of Health, Labour and Welfare has streamlined approval timelines for functional protein claims, enabling faster product launches with verified health benefits.
- Senior fitness expansion:Municipal sports centers in Saitama and Chiba prefectures are expanding protein education programs for adults over sixty-five.
- Cross-flow microfiltration:This membrane technology is improving isolate purity while reducing lactose residuals, opening formulation options for lactose-intolerant consumers.
Market Restraints
- Import dependency:Domestic whey production covers under fifteen percent of raw material needs, exposing processors to New Zealand and Australian supply volatility.
- FOSHU compliance costs:Clinical trial requirements for functional claims add twelve to eighteen months to product development cycles.
- Plant protein substitution:Soy and pea protein isolates from domestic Japanese agriculture are capturing shelf space in conventional retail channels.
Strategic Opportunities
- Hokkaido dairy integration:Proximity to Japan's largest milk-producing region offers opportunities for captive whey supply and shorter logistics chains.
- Medical nutrition expansion:Hospital discharge protocols and home-care nutrition plans are creating demand for clinical-grade hydrolysates.
- Subscription direct-to-consumer:Monthly replenishment models bypass conventional retail slotting fees and build consumption habit data.
Industry Challenges
- Foods with Function Claims documentation:The Consumer Affairs Agency requires extensive scientific substantiation that strains smaller manufacturers' regulatory affairs capabilities.
- Cold chain integrity:Summer humidity in the Kanto region degrades powder stability during last-mile delivery, requiring packaging investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Whey Protein Market |
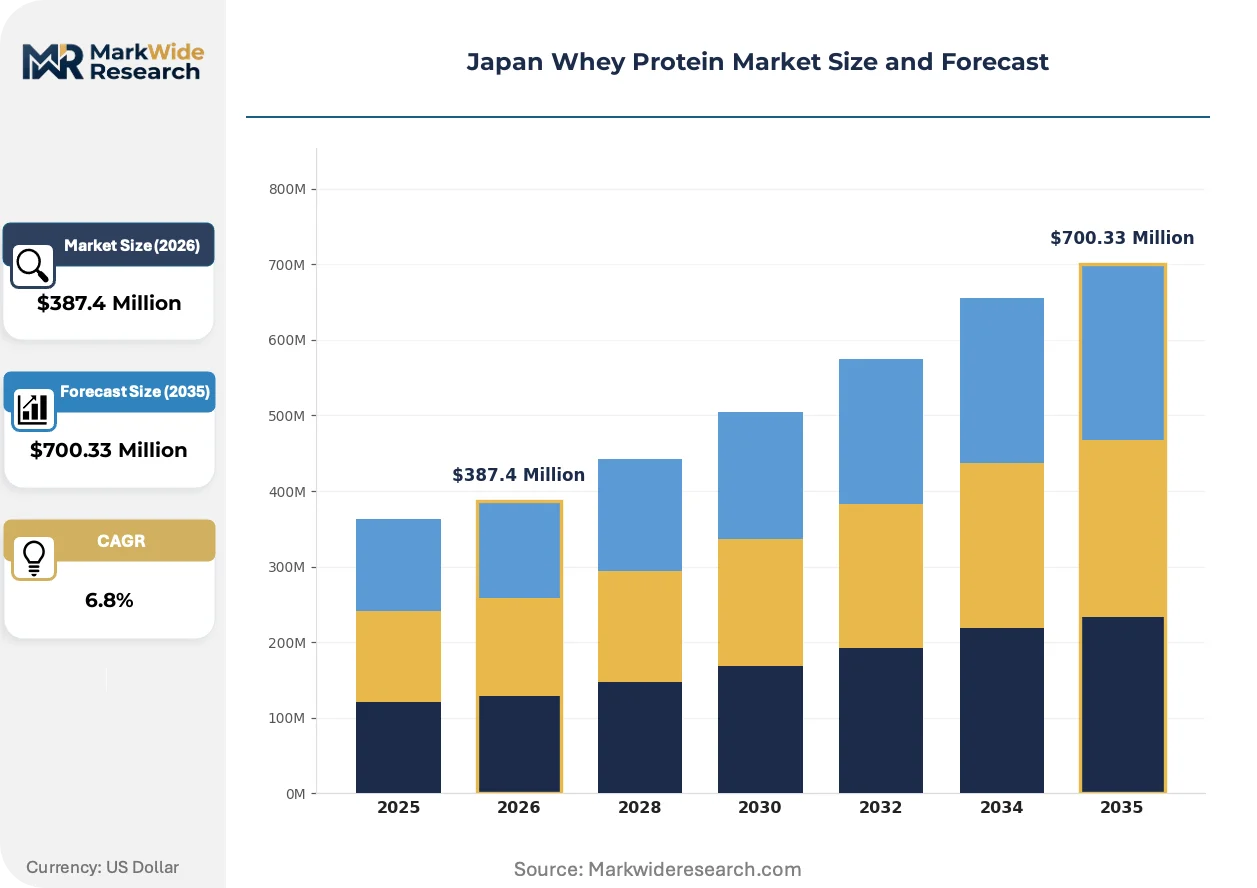
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends Distribution Channel: Online, Supermarkets, Specialty Stores, Health Shops End User: Athletes, Bodybuilders, Fitness Enthusiasts, General Consumers Packaging Type: Bulk, Sachets, Containers, Tubs |
| Companies Covered | Morinaga Milk Industry Co., Ltd., Meiji Holdings Co., Ltd., Fonterra Co-operative Group Limited, Glanbia Plc, Arla Foods amba, Groupe Lactalis, Nestlé Japan Ltd., Ajinomoto Co., Inc., Otsuka Pharmaceutical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Whey Protein Market Shifts & Advancements
Membrane filtration advances and regulatory claim pathways are redrawing competitive boundaries between commodity suppliers and differentiated functional food developers.
Cross-flow microfiltration combined with ceramic membrane technology is decentralizing whey protein production economics. Small-batch processors in Osaka and Nagoya are adopting these systems to produce isolate grades that previously required scale volumes only achievable by import houses. This capability diffusion is compressing minimum efficient scale thresholds and enabling regional specialty brands to compete on purity specifications.
METI's 2023 revision to food manufacturing standards has tightened heavy metal and microbial contamination limits for protein powders. Domestic processors are responding with additional ion-exchange polishing steps that add production cost but create compliance differentiation against lower-grade imports. The clinical nutrition segment has absorbed these costs most readily, passing them through to hospital procurement contracts.
Japanese consumers over fifty are abandoning single-serve sachet purchases in favor of bulk powder subscriptions with flavor rotation options. Specialty fitness boutiques in Tokyo's Shibuya and Shinjuku wards are facilitating this shift through in-store sampling programs that convert trial to recurring direct orders. This channel migration is eroding supermarket category management leverage and reallocating marketing spend toward digital retention mechanics.
Japan Whey Protein Market Segmentation
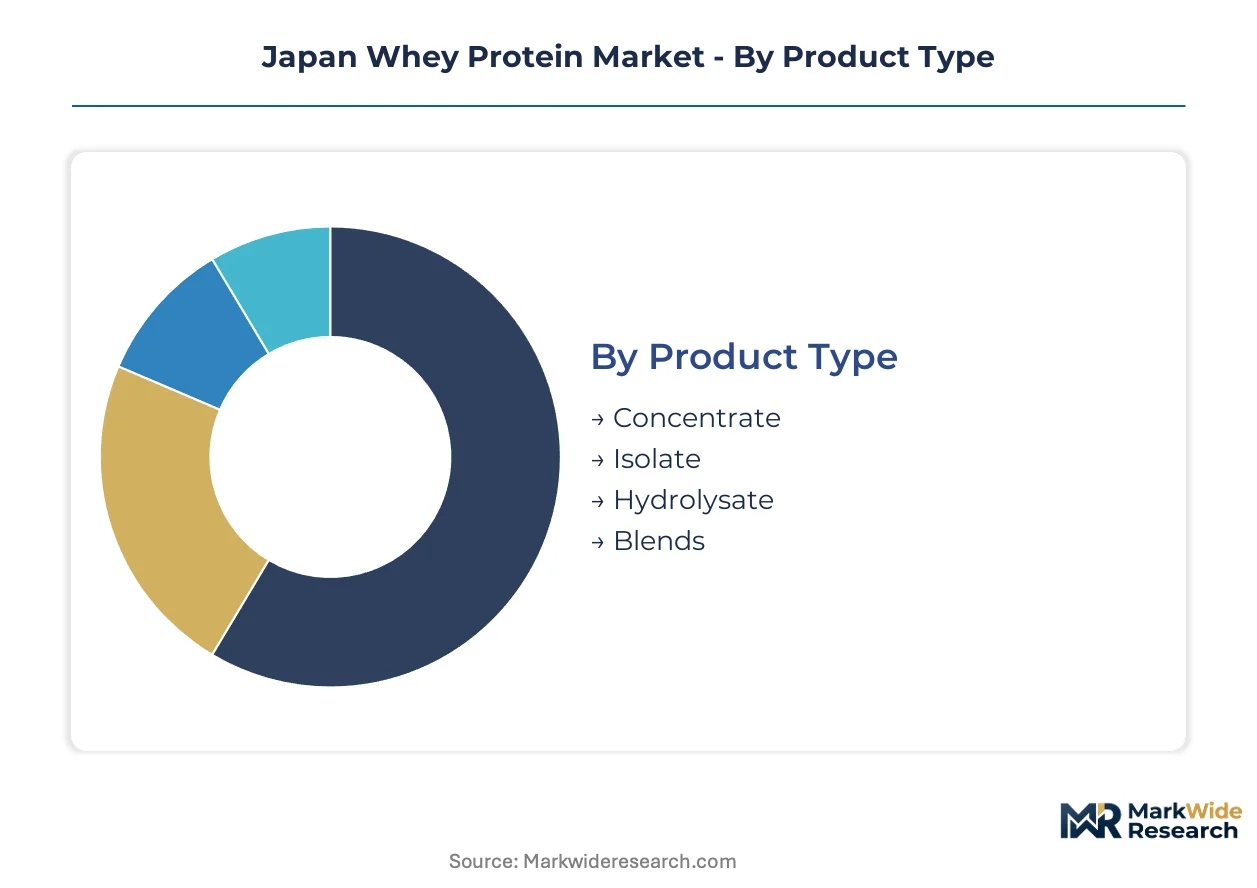
Segmentation in Japan's whey protein market reveals how FOSHU certification requirements and aging demographics reshape product development priorities across formulation grades and channel strategies. Manufacturers must align technical specifications with regulatory pathways while navigating fragmented retail evolution from conventional supermarkets to direct-to-consumer platforms.
Product Type:
Customization intensity varies sharply across this category, with isolate and hydrolysate grades demanding specialized membrane filtration investments while concentrates accommodate standardized commodity production.
- Concentrate:Protein content ranges from 35% to 80% with retained lactose and fat fractions. Municipal sports centers in Saitama and Chiba prefectures distribute concentrate formats through bulk procurement for senior fitness programs. Leading the category by volume: Concentrate. Growing fastest: Isolate.
- Isolate:Cross-flow microfiltration achieves 90%+ protein purity with minimal lactose residuals. Tokyo's specialty fitness boutiques in Shibuya and Shinjuku wards stock isolate grades for lactose-intolerant athletes seeking premium positioning.
- Hydrolysate:Enzymatic pre-digestion creates rapid-absorption peptide fractions for clinical nutrition applications. Hospital discharge protocols in the Kanto region specify hydrolysate grades for post-surgical recovery regimens.
- Blends:Multi-source protein combinations balance cost and absorption kinetics. Functional food developers in Osaka formulate blends to achieve specific amino acid profiles under FOSHU claim requirements.
Isolate commands premium shelf positioning while concentrate dominates procurement volumes for institutional and mass-market channels.
Distribution Channel:
Channel economics shift with customer acquisition costs, where digital platforms bypass slotting fees but demand retention infrastructure that supermarkets never required.
- Online:Direct-to-consumer subscriptions with flavor rotation options capture recurring revenue from consumers over fifty. Monthly replenishment models in the Kanto region build consumption habit data that conventional retail cannot replicate.
- Supermarkets:Category management leverage erodes as protein fortification extends beyond sports use into everyday wellness. Morinaga Milk Industry maintains shelf positioning through domestic dairy heritage relationships with conventional retail buyers.
- Specialty Stores:In-store sampling programs convert trial to recurring direct orders. Tokyo's dense gym infrastructure anchors specialty boutique density in Shibuya and Shinjuku wards.
- Health Shops:FOSHU-certified products receive preferential placement where functional claims carry regulatory verification. Consumer Affairs Agency labeling compliance shapes product mix decisions.
Online channels expand most quickly among aging fitness enthusiasts while supermarkets retain volume concentration in rural prefectures.
End User:
User sophistication determines formulation complexity, with clinical and athletic applications demanding purity specifications that general wellness consumers rarely require.
- Athletes:Competition-grade isolate specifications with batch-tested contaminant screening. Sports nutrition adoption among aging fitness enthusiasts accelerates demand for recovery-optimized formulations.
- Bodybuilders:High-dose consumption patterns favor bulk packaging with cost-per-gram optimization. Protein education programs at municipal sports centers expand this segment beyond traditional youth demographics.
- Fitness Enthusiasts:Mid-tier concentrate and blend consumption for routine training support. This segment shows steepest expansion trajectory as protein fortification enters everyday wellness routines.
- General Consumers:Sachet and convenience formats for occasional use without equipment investment. FOSHU functional claims drive trial among health-conscious households seeking verified benefits.
Fitness enthusiasts represent the broadest addressable expansion while athletes concentrate value capture.
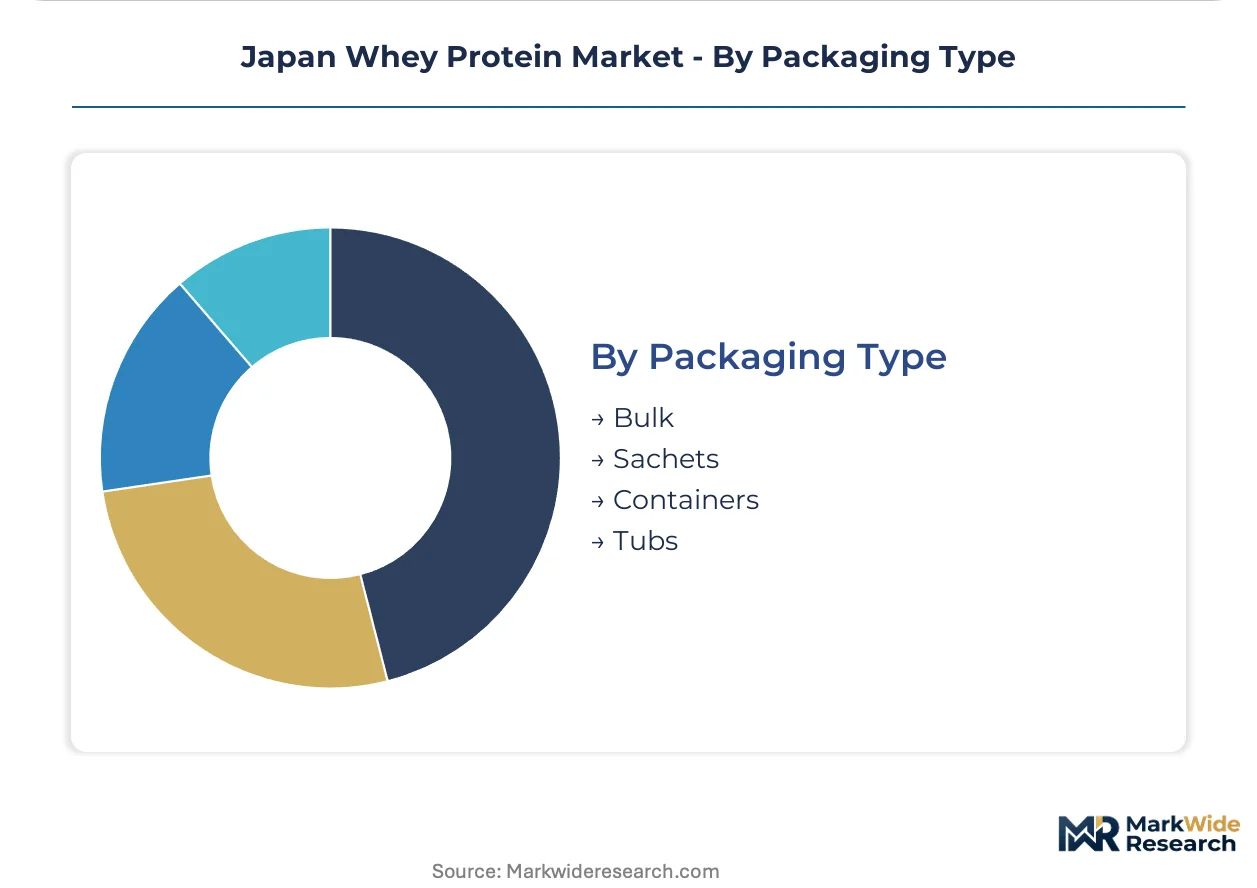
Packaging Type:
Packaging economics reflect consumption frequency and humidity exposure risks, with bulk formats sacrificing portability for unit cost advantages.
- Bulk:Institutional procurement for municipal sports centers and hospital nutrition programs. METI manufacturing standards govern microbial contamination limits for large-format powder stability.
- Sachets:Single-serve convenience for trial and travel use. Consumers over fifty are abandoning sachet purchases in favor of subscription-based bulk alternatives with flavor rotation.
- Containers:Mid-volume formats for regular home consumption. Summer humidity in the Kanto region degrades powder stability, requiring desiccant and barrier packaging investment.
- Tubs:Standard fitness retail format with scoop and reseal functionality. Specialty fitness boutiques facilitate tub format sampling that converts to direct-to-consumer replenishment.
Bulk packaging leads institutional procurement while containers dominate household replenishment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Japan's Kanto region, anchored by Tokyo's dense gym infrastructure and supplement retail networks. Prefectural governments across the archipelago are deploying divergent protein education and senior fitness strategies. METI standards and FOSHU frameworks create uniform regulatory baselines that regional players navigate with varying facility investments.
Kanto
Tokyo's Shibuya and Shinjuku wards host the highest density of specialty fitness boutiques in Japan. Municipal sports centers in Saitama and Chiba prefectures operate protein education programs targeting adults over sixty-five. The Consumer Affairs Agency maintains regional enforcement offices in Tokyo that shape labeling compliance investments by local distributors.
Kansai
Osaka-based small-batch processors deploy cross-flow microfiltration systems to produce isolate grades at reduced scale. The prefecture's functional food developers formulate blends to achieve specific amino acid profiles under FOSHU claim requirements. METI's Kansai bureau monitors manufacturing quality benchmarks for regional powder production facilities.
Chubu
Nagoya anchors central Japan's membrane technology adoption corridor with ceramic filtration equipment installations. Regional dairy cooperatives supply whey streams to local processors seeking shorter logistics chains than import-dependent competitors. The prefecture's industrial standards office coordinates with METI on manufacturing quality certifications.
Hokkaido
Japan's largest milk-producing region offers captive whey supply opportunities for integrated processors. Dairy cooperatives in the prefecture are expanding whey fractionation capacity to serve domestic protein demand. Cold chain infrastructure investments address summer humidity degradation risks during powder storage and distribution.
Kyushu
Fukuoka's health food retail clusters distribute FOSHU-certified products with preferential placement for verified functional claims. Regional hospital networks specify clinical-grade hydrolysates for post-surgical recovery regimens. The prefecture's aging population demographics exceed national averages, accelerating senior fitness program adoption.
Japan Whey Protein Market Competitive Landscape
Domestic Japanese producers anchor one tier; New Zealand and European import houses hold scale-driven positions in isolate and hydrolysate grades. The vendor base organizes around three strategic archetypes: integrated dairy conglomerates with captive whey streams, specialist ingredient importers with purity grading capabilities, and functional food developers with FOSHU certification expertise. Competitive moves concentrate on Hokkaido dairy integration for supply security and direct-to-consumer subscription infrastructure for channel bypass.
Among domestic integrated players, Morinaga Milk Industry Co., Ltd. and Meiji Holdings Co., Ltd. exemplify the dairy heritage archetype with conventional retail shelf positioning. Fonterra Co-operative Group Limited occupies the import specialist tier, competing on whey isolate purity grades tailored to discerning Japanese buyers. These three entities represent the competitive spectrum from domestic supply chain control to offshore scale economies.
| Leading Market Players |
|---|
| Morinaga Milk Industry Co., Ltd. |
| Meiji Holdings Co., Ltd. |
| Fonterra Co-operative Group Limited |
| Glanbia Plc |
| Arla Foods amba |
| Groupe Lactalis |
| Nestlé Japan Ltd. |
| Ajinomoto Co., Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Others |
Supply & Pricing Matrix
New Zealand Global Dairy Trade auction prices cascade through Japanese whey protein supply chains, compressing margins for import-dependent processors while rewarding Hokkaido-integrated domestic players with captive whey streams and insulation from currency volatility.
Pricing Analysis
Volume capture versus margin defense splits the competitive field. Three-tier pricing structure across premium isolate, standard concentrate, and economy blend levels reflects FOSHU certification status and cross-flow microfiltration investment. Pricing pressure stems from plant protein substitution in conventional retail, forcing whey processors to absorb ion-exchange polishing costs without full pass-through. General consumers exhibit highest price sensitivity, while clinical nutrition procurement absorbs premium grades with minimal elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure remains underdeveloped for protein powder returns, with humidity-degraded stock typically written off rather than refurbished. Raw material flows concentrate in New Zealand, Australia, and domestic Hokkaido dairy cooperatives. Membrane filtration equipment, lactose fractionation capacity, and ceramic filter replacements constitute critical input dependencies. Single-source vulnerability to Oceania drought cycles threatens supply continuity. Distribution runs through Tokyo-centered specialty fitness boutiques and direct-to-consumer subscription platforms, bypassing supermarket slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's whey protein sector has become a vertical-integration race where Hokkaido dairy control and captive membrane filtration capacity determine who captures margin from import volatility.
For Market Incumbents: Hedge against Oceania supply disruption by securing Hokkaido whey stream offtake agreements before regional dairy cooperatives expand fractionation capacity. Deepen backward integration into ceramic membrane equipment maintenance to reduce isolate production downtime. Plant protein substitution in conventional retail channels threatens volume concentration; defend through FOSHU certification exclusivity that soy and pea isolates cannot replicate.
For New Entrants and Emerging Players: Begin with clinical-grade hydrolysate production for hospital discharge protocols, where procurement specifications favor purity over brand heritage and create entry tolerance. Municipal sports centers in Chiba and Saitama prefectures represent the most penetrable institutional segment, with bulk concentrate procurement replacing aging vendor relationships. Direct-to-consumer sampling partnerships with Shibuya fitness boutiques convert trial to subscription retention without supermarket slotting investment.
For Investors and Strategic Acquirers: The window for entry favors regional membrane technology adopters in Osaka and Nagoya with FOSHU documentation capabilities but subscale marketing infrastructure. Long-term viability rests on clinical nutrition segment absorption of premium pricing and senior fitness program expansion beyond Tokyo. Watch for Consumer Affairs Agency enforcement actions on Foods with Function Claims substantiation as an inflection signal for regulatory compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hokkaido Dairy Integration | Captive whey supply from Japan's largest milk-producing region reduces import dependency and currency exposure. |
| FOSHU Certification Investment | Verified functional claims from Japan's Ministry of Health, Labour and Welfare create supermarket shelf preference. |
| Cross-Flow Microfiltration Adoption | Regional processors in Osaka deploy ceramic membrane systems to achieve isolate purity at reduced scale. |
| Direct-to-Consumer Subscription Launch | Monthly replenishment models bypass Tokyo supermarket slotting fees and build consumption habit data. |
| Clinical Nutrition Partnership | Hospital discharge protocols in Kanto specify hydrolysate grades for post-surgical recovery regimens. |
Research Methodology
Multi-period observation of FOSHU approval timelines, GDT auction price movements, and municipal sports center procurement patterns anchored the trend analysis, supplemented by interviews with membrane filtration equipment suppliers, Hokkaido dairy cooperative managers, Tokyo specialty fitness boutique operators, and hospital nutrition procurement officers. Secondary validation drew from METI manufacturing standard revisions, Consumer Affairs Agency labeling enforcement records, and customs import data for whey protein concentrates and isolates. Bottom-up volume modeling across prefectural consumption clusters triangulated against top-down dairy production statistics.
Segment-weighting approaches applied differential growth assumptions across product grades, distribution channels, and end-user sophistication levels throughout the forecast period. Protein content tiers, FOSHU certification status, and regional humidity exposure risks shaped the analytical framework. CAGRs emerged from iterative reconciliation of historical procurement volumes, senior fitness program expansion trajectories, and clinical nutrition absorption capacity. Forecast inputs incorporated membrane technology adoption curves and plant protein substitution elasticity in conventional retail.
Regulatory enforcement intensity, Oceania drought frequency, and plant protein isolate quality improvements are the dominant revision risks to projection assumptions. Practitioners should monitor Consumer Affairs Agency Foods with Function Claims documentation requirements and New Zealand milk powder auction volatility for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Folate Market