
 Vegan Protein Powder Market | 2026-2036
Vegan Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Powder Market Intelligence
Expanded pea protein processing capacity in Canada is reconfiguring the raw material supply chain for North American and European producers. Garden of Life leverages its organic certification and broad retail presence to attract health-conscious consumers. MyProtein competes on volume through its direct-to-consumer channel, while Vega specializes in blended plant protein formulas for athletes.
Vegan protein powder is a dietary supplement derived from plant sources, processed to achieve a protein concentration typically exceeding 70%. It serves as an alternative to animal-based proteins for muscle repair, dietary supplementation, and food product fortification. Pea protein sources are displacing soy protein due to allergen concerns and favorable sustainability perceptions. The online retail channel dominates distribution, offering direct access to fitness enthusiasts and health-conscious consumers.
Labeling accuracy and allergen declarations are governed by regulations from bodies like the U.S. FDA and the European Food Safety Authority (EFSA). These rules dictate how terms like 'vegan' and 'plant-based' can be used, influencing consumer trust. Future competitive advantage depends on navigating protein source diversification and clean-label formulation challenges.
Market Dynamics
The reconfiguration of the raw material supply chain, driven by expanded pea protein processing in Canada and shifting perceptions around soy, is the central force shaping the vegan protein powder market. This change affects cost structures, product formulation strategies, and competitive dynamics for producers in North America and Europe.
Growth Catalysts
- Favorable Regulatory Guidance:Clarifications on plant-based food labeling from bodies like the U.S. FDA enhance consumer trust and provide clearer market access pathways for manufacturers, solidifying product positioning.
- Mainstream Food Fortification:Demand from food and beverage manufacturers for plant proteins to fortify products like snacks, cereals, and dairy alternatives is expanding the market beyond core dietary supplement users.
- Supply Chain Development:Significant investment in Canadian pea processing capacity is increasing the availability and stabilizing the cost of a key raw material for North American and European markets.
Market Restraints
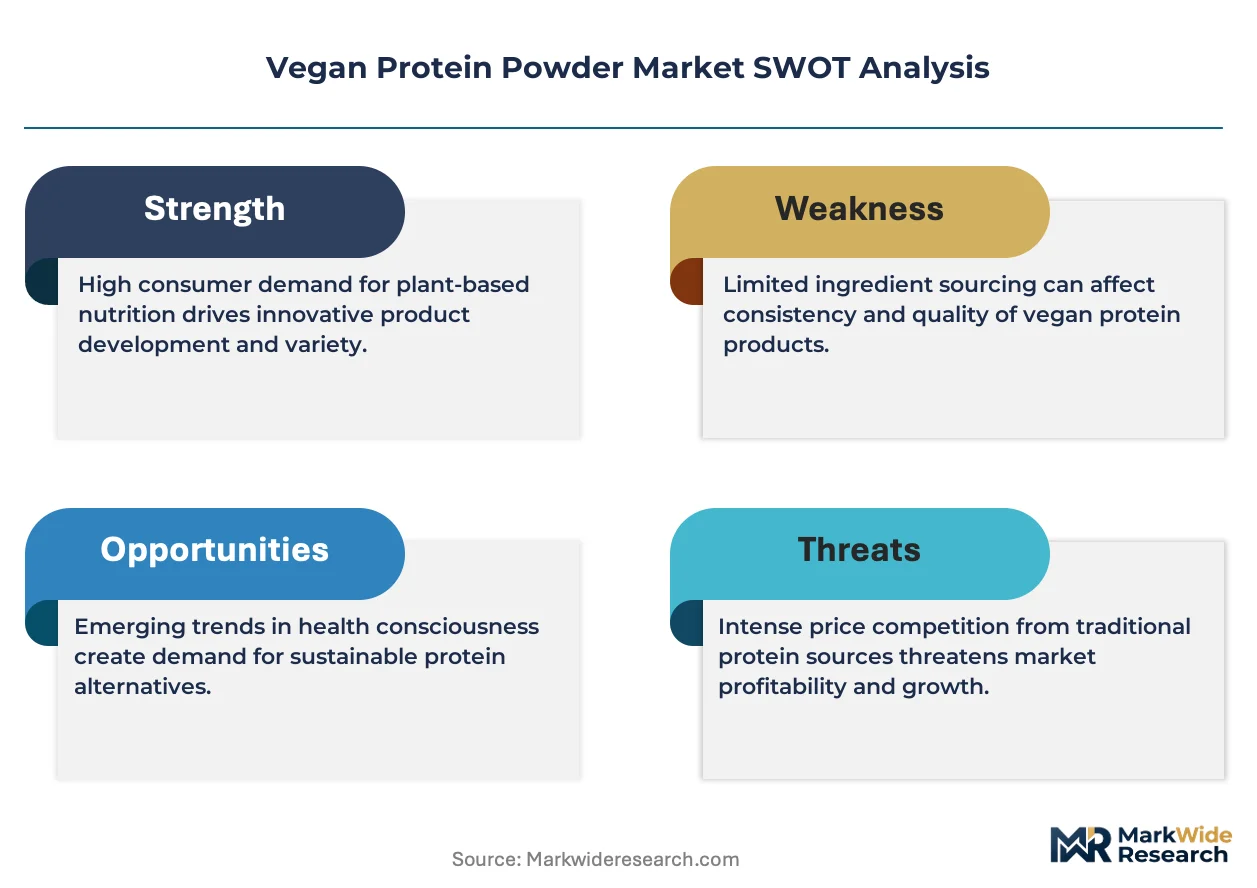
- Input Cost Volatility:Prices for key inputs like non-GMO peas and organic rice are subject to agricultural yield fluctuations, weather events, and competition from the food industry, creating margin pressure.
- Sensory Profile Limitations:Many plant proteins, particularly from emerging sources, possess inherent off-flavors or gritty textures that require extensive masking or processing, which can deter mainstream consumer adoption.
- Substitution from Whole Foods:A segment of health-conscious consumers prefers obtaining protein from whole food sources like lentils, beans, and tofu, viewing processed powders as less natural and thus limiting market penetration.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand in Latin American and Southeast Asian countries, where plant-forward dietary patterns are growing, presents a significant geographic expansion opportunity for established brands.
- Novel Protein Source Commercialization:Developing and scaling proteins from sources like fava beans, chickpeas, and mung beans offers a path to product differentiation and supply chain diversification away from pea and soy.
- Functional Ingredient Blends:Incorporating complementary ingredients like probiotics, adaptogens, or specific micronutrients allows for the creation of targeted, higher-margin products for specific health outcomes like gut health or stress management.
Industry Challenges
- Formulation Expertise Scarcity:A shortage of food scientists skilled in overcoming the technical hurdles of plant protein formulation, such as solubility and taste, creates a bottleneck for new product development.
- Allergen Cross-Contamination Risk:Maintaining stringent production protocols to prevent cross-contamination in facilities that also handle soy, nuts, or dairy is a significant operational and compliance challenge.
- Clean-Label Ingredient Sourcing:Securing a consistent supply of raw materials that meet "clean-label" criteria—non-GMO, organic, and free from chemical processing aids—is increasingly difficult as demand outstrips certified supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Powder Market |
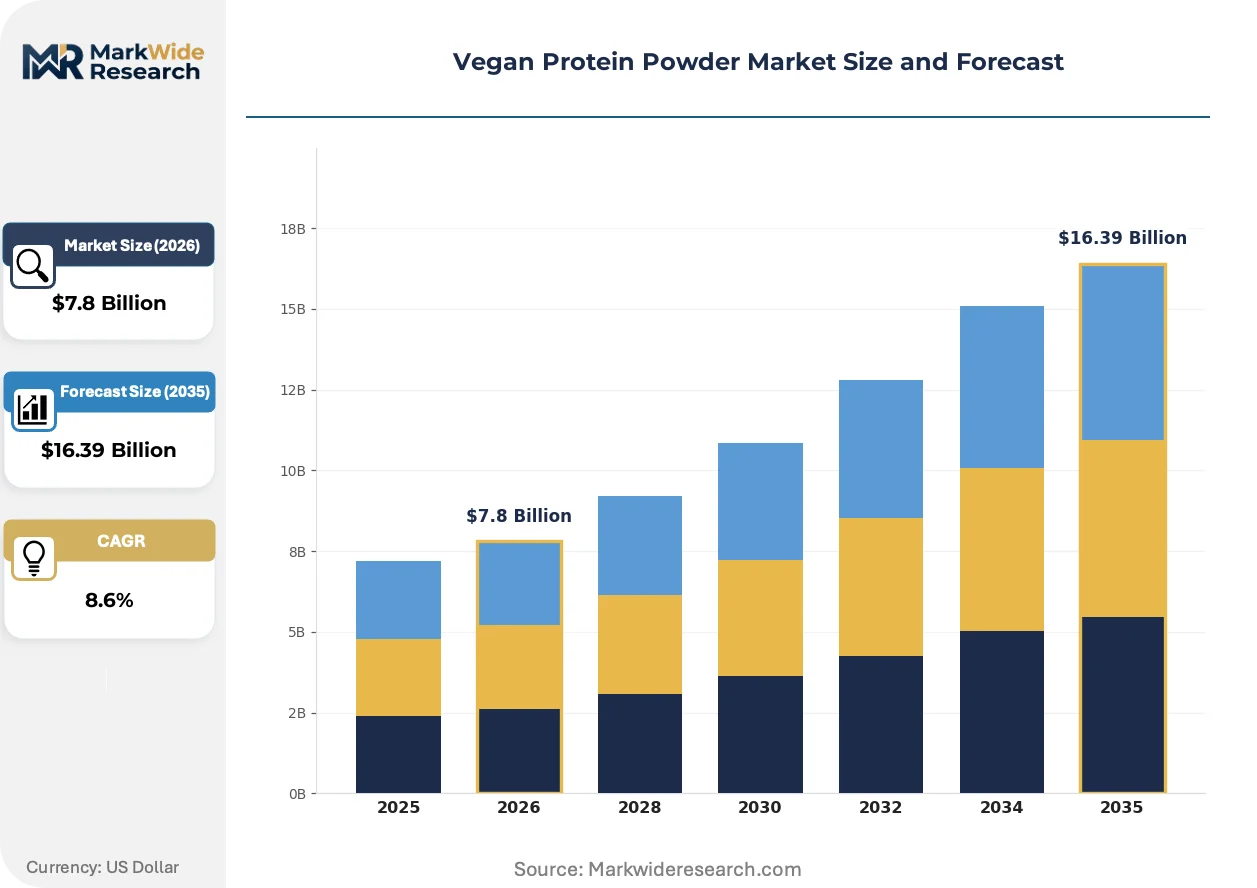
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Rice Protein, Hemp Protein, Soy Protein End User: Fitness Enthusiasts, Athletes, Health-conscious Consumers, Bodybuilders Packaging Type: Bag, Jar, Sachet, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Gyms |
| Companies Covered | Orgain, Swolverine, Naked Nutrition, KOS, Ora Organic, Legion Athletics, Garden of Life, MyProtein, Vega, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Powder Market Strategic Shifts & Innovations
Product development is pivoting from single-ingredient powders toward sophisticated, multi-source blends designed for specific functional outcomes and sensory experiences. This evolution reflects a maturing consumer base that demands not only efficacy but also superior taste, texture, and transparent sourcing across all product categories.
Precision fermentation is a key enabling technology for creating novel protein ingredients with enhanced functional properties. Food technologists and formulators are adopting these processes to improve solubility, emulsification, and mouthfeel in finished products. This advancement is collapsing the sensory and performance gap between plant-based proteins and their traditional animal-based counterparts like whey, opening new application possibilities in beverages and dairy alternatives.
The European Food Safety Authority's (EFSA) rigorous novel food approval process sets a high bar for market entry. This framework requires extensive data on safety and toxicology, creating a significant investment hurdle for companies developing proteins from new sources like duckweed or certain microalgae. This regulatory dynamic most affects innovative startups, often compelling them to seek partnerships with larger corporations to navigate the costly and lengthy path to commercialization in the EU.
A distinct shift in purchasing behavior involves consumers seeking vegan protein powders in mainstream retail environments, moving beyond online-only channels. This trend disrupts the established direct-to-consumer model, compelling brands to build relationships with grocery chains, pharmacies, and mass-market retailers. The expansion of wellness sections in supermarkets across the United States and Germany is where this channel diversification is most apparent, normalizing the product category for a broader audience.
Vegan Protein Powder Market Segmentation
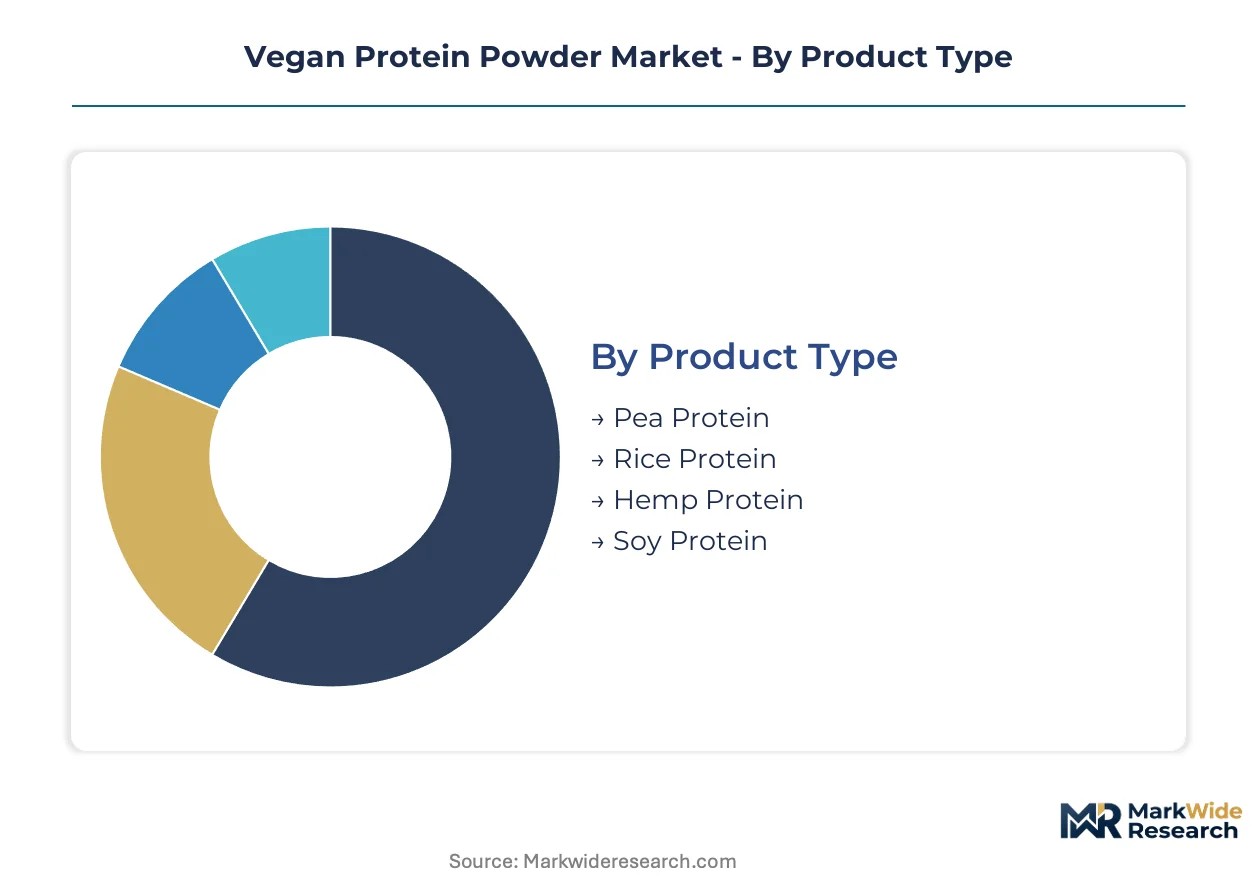
The vegan protein powder market segments across diverse product types and consumer needs, reflecting a dynamic landscape. Understanding these distinctions helps stakeholders identify specific growth vectors and tailor product offerings. This detailed segmentation reveals the varied pathways for market penetration and competitive differentiation.
Product Type:
The spectrum of plant-based protein sources addresses different nutritional profiles and consumer preferences for texture and taste.
- Pea Protein:Derived from yellow peas, this isolate or concentrate offers a neutral flavor profile and high digestibility. Demand is concentrating in North American and European markets due to its versatility in beverages and fortified foods.
- Soy Protein:A complete protein source, available as isolate or concentrate, traditionally favored for its cost-effectiveness and functional properties. Fortification applications in dairy alternatives and meat analogs drive its use, despite allergen concerns in some regions.
- Rice Protein:Often combined with pea protein to create a complete amino acid profile, it appeals to consumers seeking hypoallergenic options.
- Hemp Protein:Valued for its fiber content and omega fatty acids, it is gaining traction among consumers prioritizing whole-food nutrition.
Established volume favors Pea Protein; emerging adoption favors Hemp Protein.
End User:
Segmentation by end user highlights distinct consumption patterns and specific nutritional requirements across various demographics.
- Health-conscious Consumers:This broad group seeks general wellness benefits, digestive health support, and clean-label ingredients. Demand is strong across urban centers in Germany and the United States, driven by holistic lifestyle choices.
- Athletes:Requiring high protein intake for muscle repair and recovery, this segment prioritizes amino acid profiles and rapid absorption. Performance-oriented products targeting endurance athletes and strength trainers are popular in fitness communities globally.
- Fitness Enthusiasts:These individuals use protein powders for general fitness support, muscle maintenance, and meal supplementation.
- Bodybuilders:Focused on maximizing muscle mass and minimizing fat, they seek high-purity protein isolates with minimal additives.
Health-conscious Consumers represent the largest segment, while Athletes are expanding most quickly.
Packaging Type:
Packaging types differentiate products based on volume, convenience for consumption, and preservation requirements.
- Bag:Flexible pouches, often resealable, offer cost-effective and space-efficient packaging for various protein powder sizes. This format is preferred by online retailers and budget-conscious consumers in markets like the United States.
- Jar:Rigid containers, typically plastic, provide durability and a premium aesthetic, often featuring scoops for convenient dosing. Supermarket shelves in Canada and the UK frequently stock jars, appealing to consumers seeking easy storage.
- Sachet:Single-serving packets cater to on-the-go consumption and product sampling, popular for travel and gym use.
- Bulk Packaging:Large-format containers serve industrial clients and food service, providing cost efficiencies for high-volume applications.
Bags dominate individual consumer purchases, with Sachet formats climbing the fastest for convenience.
Distribution Channel:
Distribution channels define product accessibility and market reach, influencing brand visibility and consumer purchasing habits.
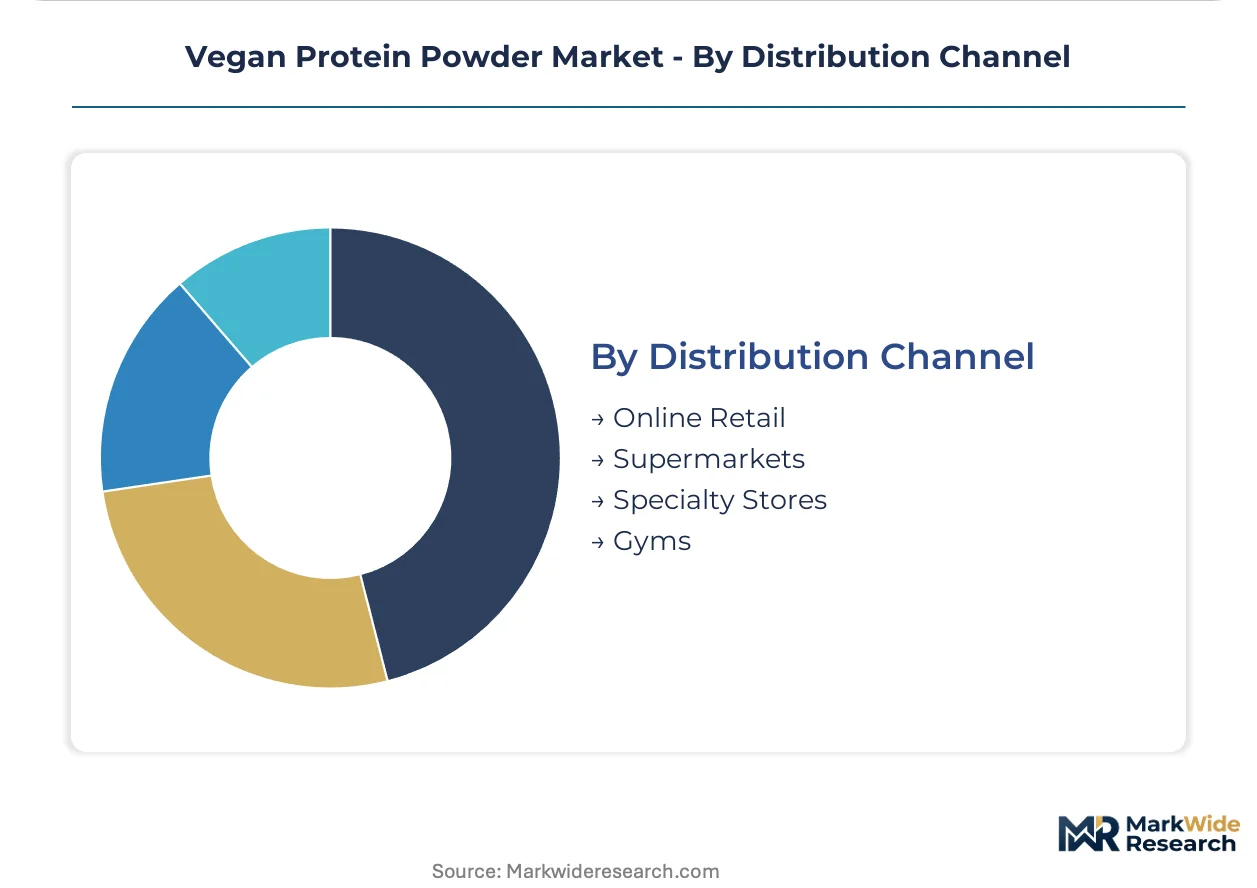
- Online Retail:E-commerce platforms provide extensive product selection, competitive pricing, and direct-to-consumer delivery. This channel dominates sales in North America and Europe, leveraging digital marketing to reach fitness enthusiasts.
- Supermarkets:Mainstream grocery stores offer convenience and immediate availability, normalizing vegan protein powders for a broader audience. Wellness sections in German and U.S. supermarkets are increasingly featuring these products.
- Specialty Stores:Health food stores and organic markets cater to niche segments seeking premium, certified, or unique plant-based protein options.
- Gyms:Fitness centers and athletic facilities offer direct sales to athletes and bodybuilders, often through branded kiosks or pro shops.
Online Retail maintains market leadership, while Supermarkets are on the steepest expansion trajectory for broader consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expanded pea protein processing capacity in Canada underwrites the global vegan protein powder market's supply chain dynamics. This infrastructure development impacts cost structures and product formulation for North American and European producers. Demand drivers vary significantly across key geographic markets.
United States
United States consumers demonstrate strong demand for vegan protein powders, driven by health-conscious choices and dietary supplementation. The FDA's guidance on plant-based food labeling provides market clarity and enhances consumer trust. Wellness sections within supermarkets across major U.S. cities increasingly stock these products, normalizing the category.
Germany
German consumers prioritize plant-based diets, fueling demand for vegan protein powders in various food fortification applications. The European Food Safety Authority (EFSA) framework governs novel food approvals, influencing product development and market entry. Urban centers like Berlin and Munich show high concentration of supermarket wellness sections featuring these supplements.
Canada
Canada plays a pivotal role in raw material supply, with significant investment in pea processing capacity increasing ingredient availability. Health Canada regulations ensure food safety and quality standards for domestically produced plant proteins. Agricultural regions in Saskatchewan and Manitoba host expanded pea protein facilities, serving North American and European markets.
United Kingdom
British consumers show a preference for convenient packaging formats like jars and sachets, driving demand for accessible vegan protein options. The UK's Food Standards Agency (FSA) oversees labeling accuracy and allergen declarations for plant-based products. Major retail chains in London and other metropolitan areas prominently feature vegan protein powders on their shelves.
China
China represents an emerging market for vegan protein powders, with a growing interest in plant-forward dietary patterns among its population. The State Administration for Market Regulation (SAMR) establishes standards for food additives and labeling, impacting product formulation. E-commerce logistics hubs in cities like Shanghai and Guangzhou facilitate broad product distribution.
Vegan Protein Powder Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the vegan protein powder market. The market exhibits a tiered structure, with established brands competing against agile niche players. Strategic archetypes include volume-driven producers, organic-certified specialists, and functional blend innovators. Competitive moves focus on portfolio diversification through novel protein sources and strategic partnerships for raw material access.
Specialists in blended plant protein formulas, such as Vega, exemplify a focus on performance-oriented products tailored for athletes, emphasizing specific functional outcomes like muscle repair and recovery. Garden of Life represents the organic-certified segment, leveraging its stringent quality standards and broad retail presence to attract health-conscious consumers seeking clean-label and transparently sourced options. MyProtein occupies a position as a volume-driven player, effectively reaching a wide consumer base through its direct-to-consumer channel, which enables competitive pricing and extensive product offerings.
| Leading Market Players |
|---|
| Orgain |
| Swolverine |
| Naked Nutrition |
| KOS |
| Ora Organic |
| Legion Athletics |
| Garden of Life |
| MyProtein |
| Vega |
| Others |
Cost & Logistics Intelligence
Commodity volatility for non-GMO peas and organic rice determines both pricing tier spreads and the overall supply chain shape for vegan protein powders. This volatility creates margin pressure for producers and influences strategic sourcing decisions across the market.
Pricing Analysis
Volume-discount tiering characterizes pricing across the vegan protein powder market. Quality grade and organic certification drive premium pricing differentiation, appealing to health-conscious consumers. Pricing softness reflects intense competition from established brands and input cost volatility. Fitness enthusiasts often exhibit higher price sensitivity compared to health-conscious consumers seeking specialized, transparently sourced formulations.
Supply Chain Analysis
Input cost volatility for key raw materials like non-GMO peas and organic rice anchors the vegan protein powder supply chain. Supply concentration centers on Canadian pea protein facilities, while other ingredients draw from diverse agricultural regions. Single-source vulnerability for specific protein types presents a structural risk to producers. Distribution runs through online retail platforms, increasingly complemented by supermarket wellness sections in key markets like the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan protein powder market embodies an early-cycle expansion story, driven by the mainstreaming of plant-forward dietary patterns across urban centers.
For Market Incumbents: Build brand equity moats through consistent clean-label formulation and organic certification. Diversify protein portfolios beyond pea and soy to mitigate raw material price volatility. Invest in R&D to improve sensory profiles, countering potential off-flavors from novel protein sources. Control distribution channels to maintain competitive advantage against agile niche players.
For New Entrants and Emerging Players: Targeted functional blends for specific health outcomes represent the most penetrable entry point for new market players. Focus on emerging markets like Latin America, where plant-forward dietary patterns are growing. Leverage direct-to-consumer online channels for efficient market penetration. Partner with fitness influencers to build credibility within niche athlete communities.
For Investors and Strategic Acquirers: Niche formulators specializing in novel protein sources offer compelling acquisition targets for long-term growth. This market offers long-term viability due to sustained consumer preference for plant-based diets. Look for companies with proprietary processing technologies that overcome sensory limitations. Successful commercialization of proteins from fava beans or mung beans signals an inflection point for scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Incorporating fava bean protein expands product appeal and reduces reliance on single sources. |
| Clean-Label Sourcing Initiatives | Securing organic rice protein builds consumer trust and meets evolving regulatory standards. |
| Direct-to-Consumer Channel Expansion | MyProtein leverages online platforms for market reach and competitive pricing. |
| Functional Blend R&D | Vega develops performance-oriented formulas tailored for specific athlete needs. |
| International Market Entry | Targeting Latin American markets unlocks new demand for plant-based nutrition. |
Research Approach
A standing panel of food scientists, R&D directors, procurement managers, and regulatory affairs specialists provided ongoing calibration for this analysis. This approach combined primary interviews with industry stakeholders and secondary data validation. Secondary sources included FDA guidance documents, EFSA novel food framework, and agricultural commodity reports. Triangulation ensured data integrity.
Scenario-based modeling established a range of plausible market outcomes across the analysis window. The analytical framework integrated segmentation dimensions including product type, end user, packaging type, and distribution channel. Compound annual growth rates derived through regression analysis and expert consensus. Key forecast inputs included plant-based diet adoption rates.
Macroeconomic conditions sit as an overlay; deviation in consumer spending patterns or agricultural policy changes would shift the trajectory. Forecasts reflect assumptions documented throughout this study. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Inflammation Supplements Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Flax Protein Powder Market