
 Caffeinated Beverage Market | 2026-2036
Caffeinated Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Caffeinated Beverage Market Insights
Asset-light contract manufacturing and co-packing arrangements is rewriting competitive entry dynamics for mid-sized brands. The Coca-Cola Company leverages its bottling partner network to sustain manufacturing flexibility across multiple continents. PepsiCo anchors its position through captive concentrate production and direct-store-delivery infrastructure. Red Bull competes via premium brand licensing rather than owning production assets outright.
Caffeinated beverages comprise water-based drinks containing psychoactive methylxanthines—primarily caffeine at concentrations ranging from 30 mg per 100 ml in cola to 80 mg per 250 ml in energy drinks—formulated for mental alertness and physical performance enhancement. Coffee commands the largest value pool within product type segmentation due to ritual consumption frequency and specialty premiumization, while energy drinks represent the fastest-expanding category driven by gaming and fitness subcultures. Ready-to-drink formats within packaging type segmentation are capturing share from traditional brew-at-home coffee as convenience priorities intensify among working professionals.
The FDA governs caffeine content labeling and GRAS status in the United States, while the EU Green Deal and national sugar taxation frameworks in France, the United Kingdom, and Germany are mandating reformulation toward reduced-calorie profiles. EFSA scientific opinions on caffeine daily intake limits directly constrain product concentration ceilings and marketing claims across European markets. Stakeholders must monitor evolving methylxanthine regulatory thresholds and carbon-neutral packaging mandates as dual compliance vectors that will determine market access and margin structure.
Market Dynamics
Sugar taxation frameworks across France, the United Kingdom, and Germany are forcing accelerated reformulation cycles, compressing product development timelines from 18 months to under 9 months as brands race to maintain shelf placement under evolving compliance thresholds.
Growth Catalysts
- EU Green Deal carbon-neutral packaging mandates:Brands investing in biodegradable bottle formats and aluminum can lightweighting secure preferential retail placement in German and French supermarket chains.
- Ready-to-drink convenience prioritization:Urban working professionals in São Paulo and Shanghai are substituting home-brewed coffee with chilled single-serve formats during commute windows.
- Gaming and fitness subculture expansion:Energy drink consumption concentrates around esports venues in Seoul and CrossFit box memberships in Australian metropolitan areas.
Market Restraints
- Arabica coffee price volatility:Brazilian frost events and Colombian drought cycles transmit directly into input cost instability for roasted coffee concentrate suppliers.
- EFSA caffeine daily intake ceilings:The European Food Safety Authority's 400 mg per day adult limit constrains product concentration formulations and marketing claims across EU member states.
- Aluminum can sheet supply concentration:Global primary aluminum smelting capacity clusters in China's Yunnan province and Russia's Siberian hydroelectric corridor, creating geopolitical exposure.
Strategic Opportunities
- Underpenetrated Indonesian archipelago:Java and Sumatra's young demographic profile and low per-capita caffeinated beverage consumption offer first-mover positioning for RTD coffee entrants.
- Nitrogen-infused cold brew technology:Creamy texture profiles without dairy additives attract lactose-intolerant consumers in South Korean and Japanese convenience store channels.
- Extended producer responsibility schemes:France's AGEC law and Germany's VerpackG regulations create competitive advantage for brands with established reverse logistics infrastructure.
Industry Challenges
- Reformulation R&D talent scarcity:Food scientists with dual expertise in flavor chemistry and regulatory compliance command premium compensation in Switzerland and the Netherlands.
- Legacy PET bottling line retrofit costs:Transitioning existing European filling equipment to handle recycled content above 50% requires capital outlays that strain mid-sized brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caffeinated Beverage Market |
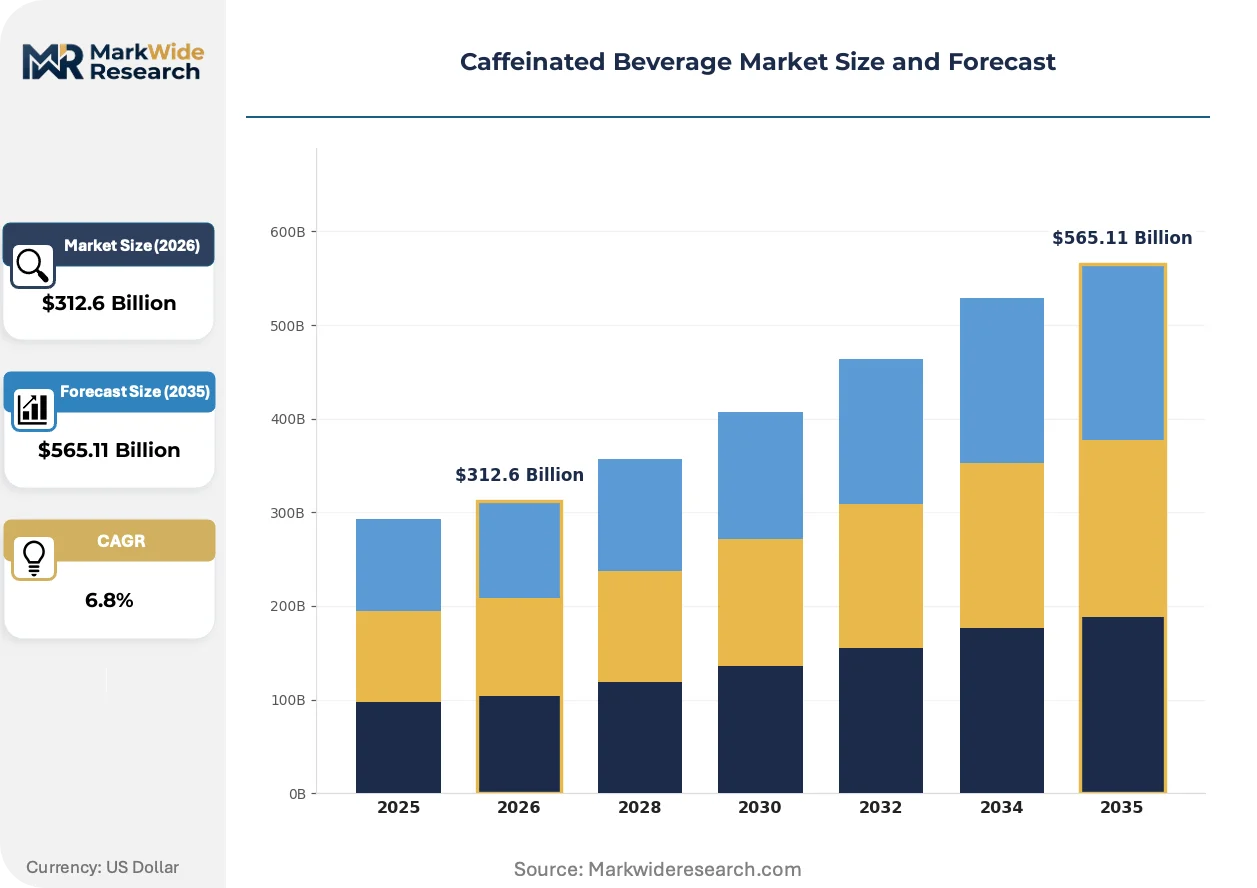
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Coffee, Tea, Soda, Ready-to-Drink Packaging Type: Can, Bottle, Carton, Pouch, K-Cup Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines Consumer Segment: Students, Working Professionals, Athletes, Travelers, Gamers |
| Companies Covered | The Coca-Cola Company, PepsiCo, Red Bull, Monster Beverage Corporation, Nestlé, Keurig Dr Pepper, Starbucks, Taisho Pharmaceutical Holdings, Suntory Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caffeinated Beverage Market Trends and Innovations
Active ingredient diversification and packaging material substitution are compressing traditional category boundaries between coffee, tea, and functional beverage segments. Manufacturers now compete on methylxanthine sourcing transparency and carbon footprint labeling rather than caffeine dosage alone.
Cold extraction and flash brewing technologies are migrating from specialty coffee roasters to mass-market RTD production facilities. Nestlé and JDE Peet's are deploying these methods in Brazilian and Vietnamese contract manufacturing sites. The shift enables cleaner flavor profiles at scale while reducing thermal energy inputs by approximately one-third compared to conventional hot-brew methods.
The EU Green Deal's Packaging and Packaging Waste Regulation is mandating minimum recycled content thresholds for beverage containers sold in member states. French retailers are already rejecting shipments that lack digital product passport traceability. German discounters are prioritizing suppliers with verified carbon-neutral production certifications ahead of the 2030 compliance deadlines.
Subscription-based replenishment models are displacing traditional supermarket stocking-up behaviors among urban professionals in London, New York, and Tokyo. Direct-to-consumer platforms offering personalized caffeine dosing schedules and flavor rotation algorithms capture higher lifetime value than conventional retail channels. The shift concentrates customer data assets with platform operators rather than brand owners.
Caffeinated Beverage Market Segmentation
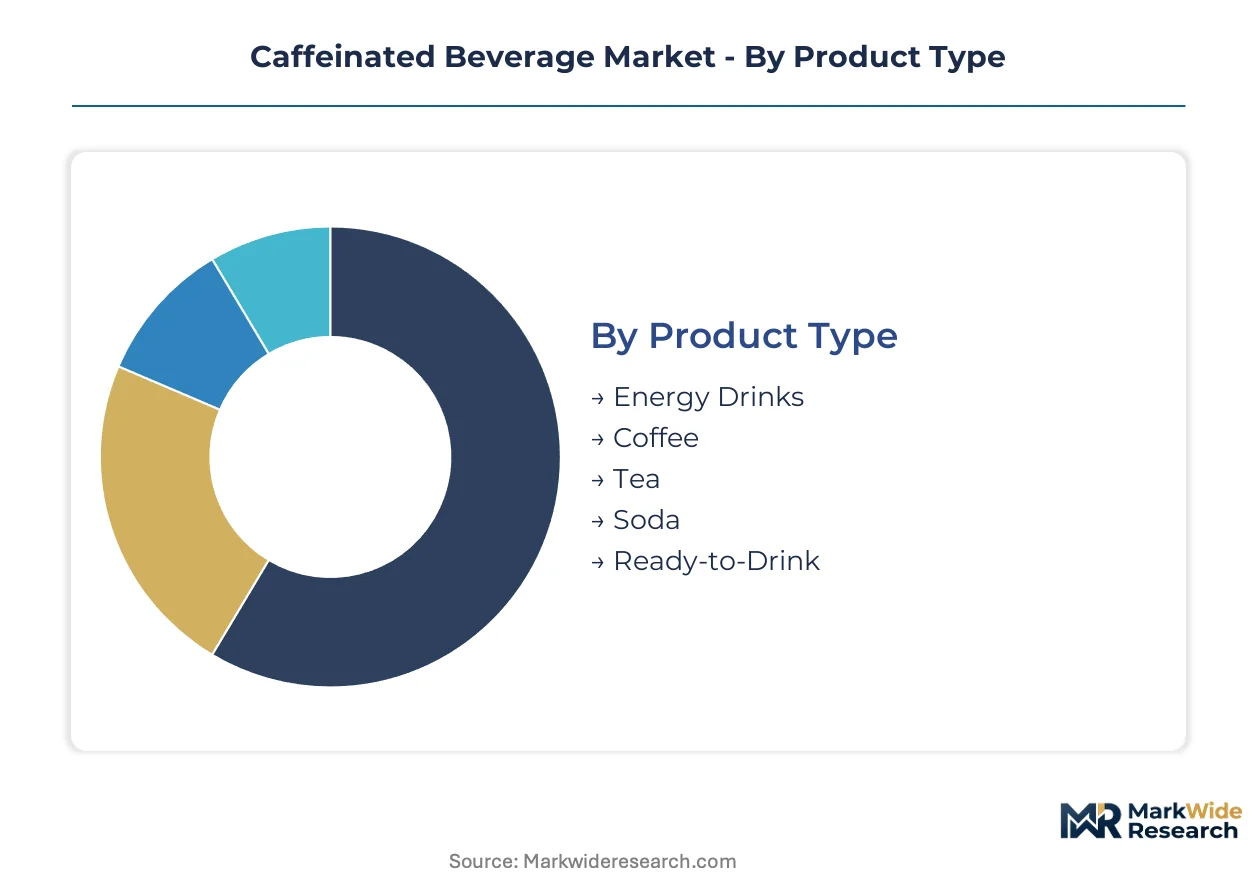
Caffeinated beverage segmentation reveals divergent margin architectures across consumption occasions and delivery formats. Product type and packaging choices determine regulatory exposure, while distribution channel selection shapes customer acquisition economics and brand positioning latitude.
Product Type:
The use-case spectrum spans ritual daily consumption through performance-driven episodic intake, with each segment carrying distinct formulation requirements and pricing power.
- Coffee:Roasted and brewed preparations delivering 80-100 mg caffeine per 240 ml serving anchor habitual morning routines. Specialty arabica concentrates in São Paulo and Shanghai command premium shelf positioning as working professionals abandon home brewing for convenience.
- Energy Drinks:Formulations combining caffeine with taurine and B-vitamins at 80 mg per 250 ml target mental acuity and physical endurance. Esports venues in Seoul and CrossFit affiliates in Australian metros concentrate demand as gaming and fitness subcultures expand consumption frequency.
- Tea:Camellia sinensis-derived beverages with 20-50 mg caffeine per serving appeal to wellness-positioned consumers seeking milder stimulation. Matcha and yerba maté variants gain traction in Japanese and Argentine urban centers respectively.
- Soda:Cola and citrus formulations at 30 mg per 100 ml serve mass-market refreshment occasions with established brand loyalty. EFSA caffeine ceilings and sugar taxation in France, Germany, and the United Kingdom force accelerated reformulation cycles.
- Ready-to-Drink:Pre-packaged chilled formats spanning coffee, tea, and hybrid functional blends capture commute-window consumption. Cold extraction technologies deployed in Brazilian and Vietnamese contract manufacturing sites enable cleaner flavor profiles at scale.
Established volume favors Coffee; emerging adoption favors Energy Drinks.
Packaging Type:
Material selection determines carbon footprint compliance, shelf-life extension, and consumption occasion portability across retail and foodservice channels.
- Can:Aluminum containers with 12-16 oz standard formats dominate energy drink and carbonated segments. German discounters prioritize suppliers with verified carbon-neutral production certifications as EU Green Deal mandates tighten recycled content thresholds.
- Bottle:PET and glass formats accommodate larger volume coffee and tea preparations for extended consumption. France's AGEC law and Germany's VerpackG regulations reward brands with established reverse logistics infrastructure.
- Carton:Aseptic laminated board enables ambient distribution of RTD coffee and tea with 6-12 month shelf stability. Lightweighting reduces transport emissions for ocean freight from Southeast Asian manufacturing clusters.
- Pouch:Flexible film formats target single-serve powder and liquid concentrate segments in Asian convenience channels. Portability suits travel and outdoor consumption occasions with minimal packaging mass.
- K-Cup:Single-serve brewing pods capture office and premium home segments with portion-controlled freshness. Compatibility requirements with Keurig and Nespresso systems constrain supplier qualification.
Aluminum Can commands current volume share; Pouch formats gain fastest in Asian travel retail.
Distribution Channel:
Channel selection determines margin capture, promotional control, and data asset accumulation for replenishment algorithm refinement.
- Supermarkets:Multi-brand shelf space in French and German chains demands compliance with digital product passport traceability. Retailer consolidation concentrates negotiating leverage among Carrefour, Tesco, and REWE buying groups.
- Convenience Stores:24-hour urban formats in Tokyo, Seoul, and São Paulo capture impulse and commute-window purchases. Chilled single-serve RTD coffee rotates fastest in Japanese Lawson and 7-Eleven locations.
- Online Retailers:Direct-to-consumer platforms in London, New York, and Tokyo deploy subscription models with personalized dosing schedules. Customer data concentrates with platform operators rather than brand owners.
- Vending Machines:Automated cold and hot dispensing networks anchor Japanese workplace and transit hub consumption. Cashless payment integration and real-time inventory telemetry enable dynamic pricing.
Supermarkets retain volume dominance; Online Retailers climb fastest in customer lifetime value metrics.
Consumer Segment:
Demographic and psychographic targeting determines product positioning, caffeine concentration, and marketing claim permissibility under regulator frameworks.
- Working Professionals:Urban office workers aged 25-45 prioritize convenience and sustained alertness without sugar crash. Chilled RTD formats displace home brewing during São Paulo and Shanghai commute windows.
- Gamers:Esports participants and spectators seek rapid onset mental acuity for competitive performance. Seoul PC bangs and Twitch streaming culture normalize energy drink consumption as social ritual.
- Students:University populations balance cost sensitivity with examination-period stimulation needs. Private label and promotional pricing dominate purchasing patterns.
- Athletes:Fitness enthusiasts target pre-workout energy and intra-training hydration with electrolyte-caffeine combinations. CrossFit box memberships in Australian metros concentrate functional beverage trials.
- Travelers:Airport, rail, and highway service station consumers prioritize portability and ambient stability. Single-serve formats with extended shelf life suit irregular consumption patterns.
Working Professionals anchor current revenue; Gamers represent the steepest expansion trajectory as esports commercialization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's carbon-neutral packaging mandates and national sugar taxation frameworks are reshaping competitive entry dynamics across major consumption clusters. Brazil's southeastern coffee belt and China's eastern seaboard manufacturing hubs anchor supply-side concentration, while demand fragmentation accelerates in Southeast Asian urban centers.
United States
FDA caffeine content labeling requirements and GRAS status determinations govern product concentration ceilings and marketing claims. Young working professionals in New York and Los Angeles are substituting home-brewed coffee with chilled ready-to-drink formats during commute windows. Subscription-based replenishment models concentrate customer data assets with platform operators in metropolitan coastal corridors.
Germany
The VerpackG extended producer responsibility scheme rewards brands with established reverse logistics infrastructure. National sugar taxation frameworks compress product development timelines as manufacturers race to maintain shelf placement under evolving compliance thresholds. German discounters in the North Rhine-Westphalia retail cluster prioritize suppliers with verified carbon-neutral production certifications.
China
Dual carbon goals and packaging waste regulations mandate minimum recycled content thresholds for beverage containers. Urban working professionals in Shanghai and Shenzhen drive chilled single-serve format adoption during transit commutes. Eastern seaboard manufacturing clusters concentrate contract manufacturing capacity for nitrogen-infused cold brew technologies.
Brazil
Frost events and drought cycles in the southeastern coffee belt transmit directly into input cost instability for roasted coffee concentrate suppliers. São Paulo's working professionals anchor ritual consumption frequency for specialty arabica preparations. Cold extraction technologies deployed in Vietnamese and domestic contract manufacturing sites enable cleaner flavor profiles at reduced thermal energy inputs.
Japan
METI energy efficiency standards and waste reduction targets constrain packaging material selection for convenience store distribution. Tokyo and Osaka's 24-hour urban retail formats capture impulse and commute-window purchases for chilled single-serve products. Vending machine networks with cashless payment integration anchor workplace and transit hub consumption patterns.
Caffeinated Beverage Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base separates into multinational beverage conglomerates with captive distribution infrastructure, regional contract manufacturing specialists, and premium brand licensors without production asset ownership. Three strategic archetypes dominate: asset-light co-packing arrangements, backward-integrated concentrate production, and direct-store-delivery network operators. Competitive moves concentrate on portfolio diversification toward reduced-calorie profiles and strategic partnerships for biodegradable packaging compliance.
Among multinational beverage conglomerates, The Coca-Cola Company leverages its bottling partner network across multiple continents, while PepsiCo anchors positioning through captive concentrate production and direct-store-delivery infrastructure. Red Bull exemplifies the premium brand licensing archetype, competing without owning production assets outright. These three players represent contrasting strategic postures on manufacturing control versus brand equity concentration.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Red Bull |
| Monster Beverage Corporation |
| Nestlé |
| Keurig Dr Pepper |
| Starbucks |
| Taisho Pharmaceutical Holdings |
| Suntory Holdings |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Rotterdam container freight corridors transmit Brazilian arabica cost volatility directly into European retail price tiers, amplifying margin compression for mid-sized brands lacking backward-integrated concentrate supply. This logistics-cost transmission mechanism concentrates pricing power among bottling-network operators while forcing asset-light competitors toward co-packing arrangements that sacrifice margin for flexibility.
Pricing Analysis
Certification level (FDA-grade, EFSA-compliant, carbon-neutral verified) creates the primary spread between premium and economy positioning. Three-tier pricing structure across premium arabica concentrates, standard cola formulations, and private-label energy drinks dominates transactional volume. Cost compression in standard-tier carbonated segments is intensifying because sugar taxation frameworks in France, Germany, and the United Kingdom force accelerated reformulation cycles. Students and young professionals in university corridors exhibit highest price sensitivity, while gaming subculture participants in Seoul and Australian CrossFit affiliates demonstrate lowest sensitivity to per-unit pricing.
Supply Chain Analysis
Export-control scrutiny on aluminum smelting technology limits capacity expansion outside China's Yunnan province and Russia's Siberian corridor, constraining can-sheet supply diversification. Raw material flows draw from Brazilian arabica belts, Vietnamese robusta clusters, and Chinese methylxanthine synthesis facilities. Single-source vulnerability concentrates in aluminum can-sheet supply, with German and French retailers already rejecting shipments lacking carbon-neutral production certifications. Distribution runs through direct-store-delivery networks for multinational conglomerates and contract manufacturing arrangements for emerging brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat. EFSA caffeine ceilings and EU Green Deal packaging mandates create compliance barriers that favor incumbents with established reformulation pipelines and reverse logistics infrastructure.
For Market Incumbents: Harden compliance infrastructure against tightening EFSA methylxanthine thresholds and France's AGEC extended producer responsibility schemes. Secure captive concentrate production in Brazilian and Vietnamese manufacturing clusters to insulate margins from arabica price volatility. Channel control through direct-store-delivery networks remains the priority defensive lever against private-label encroachment in German discounter chains. For New Entrants and Emerging Players: Pursue underpenetrated Indonesian archipelago markets where Java and Sumatra's young demographics and low per-capita consumption offer first-mover positioning for RTD coffee entrants. Nitrogen-infused cold brew technology provides the most penetrable innovation angle for lactose-intolerant consumers in South Korean convenience channels. Launch through subscription-based direct-to-consumer platforms to accumulate customer data assets for personalized dosing algorithms. For Investors and Strategic Acquirers: Asset-light brand licensors with premium positioning but no production ownership represent the most attractive acquisition archetype for portfolio diversification. Long-term viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. Watch EFSA scientific opinion revisions on daily caffeine intake limits as the critical inflection signal for portfolio rebalancing toward reduced-concentration formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Acceleration | Compresses development timelines from 18 months to under 9 months to meet France, UK, and Germany sugar taxation thresholds. |
| Carbon-Neutral Packaging Transition | Biodegradable bottle formats and aluminum can lightweighting secure preferential retail placement in Carrefour and REWE chains. |
| Contract Manufacturing Expansion | Asset-light co-packing arrangements in Vietnamese and Brazilian sites enable mid-sized brands to compete without capital-intensive bottling lines. |
| Direct-to-Consumer Platform Launch | Subscription models with personalized caffeine dosing capture higher lifetime value than conventional supermarket channels in London and Tokyo. |
| Reverse Logistics Infrastructure Buildout | Compliance with Germany's VerpackG and France's AGEC laws creates competitive advantage through established take-back systems. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with beverage industry executives and secondary validation across regulatory filings and trade databases. Conversations engaged brand managers at multinational conglomerates, category buyers at French and German supermarket chains, supply planners at contract manufacturing sites in Brazil and Vietnam, and regulatory affairs leads navigating EFSA and FDA compliance pathways. Secondary sources encompassed FDA GRAS determinations, EFSA scientific opinions on methylxanthine intake, EU Green Deal packaging regulations, customs records for arabica and robusta trade flows, and Nielsen retail audit data for RTD format adoption. Bottom-up volume modeling triangulated against top-down market sizing from macroeconomic consumption indicators.
Forecast inputs incorporated product type segmentation across coffee, energy drinks, tea, soda, and ready-to-drink formats; packaging material selection from aluminum cans to aseptic cartons; distribution channel dynamics spanning supermarkets, convenience stores, and direct-to-consumer platforms; and consumer psychographic clustering around working professionals, gamers, and fitness enthusiasts. CAGRs were derived from trend extrapolation adjusted for regulatory intervention impacts and substitution elasticity between home-brewed and chilled single-serve consumption. Arabica futures price volatility and aluminum can-sheet supply concentration served as industry-specific demand-side and supply-side forecast inputs.
Sensitivities concentrate around EFSA caffeine ceiling revisions, Brazilian frost event frequency, and EU Green Deal packaging compliance deadline acceleration. Forecasts reflect documented assumptions on substitution rates between consumption occasions and channel migration patterns. Material shifts in methylxanthine regulatory thresholds or carbon-neutral certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Water Flavor Market
Beverages
Collagen Drinks Market
Beverages
Milk Tea Powder Market
Beverages
Cold Pressed Juice Market
Beverages
Carbonated Beverages Market
Beverages
Orange Juice Market
Beverages
Collagen-Infused Water Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Europe Smoothies Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Sparkling Soda Market
Beverages
India Cafes & Bars Market
Beverages
Beverage Multipacks Market
Beverages
Hydration Infusers Market
Beverages
Nitro-Infused Cola Market