
 Energy Ingredients Market | 2026-2036
Energy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Ingredients Market Intelligence
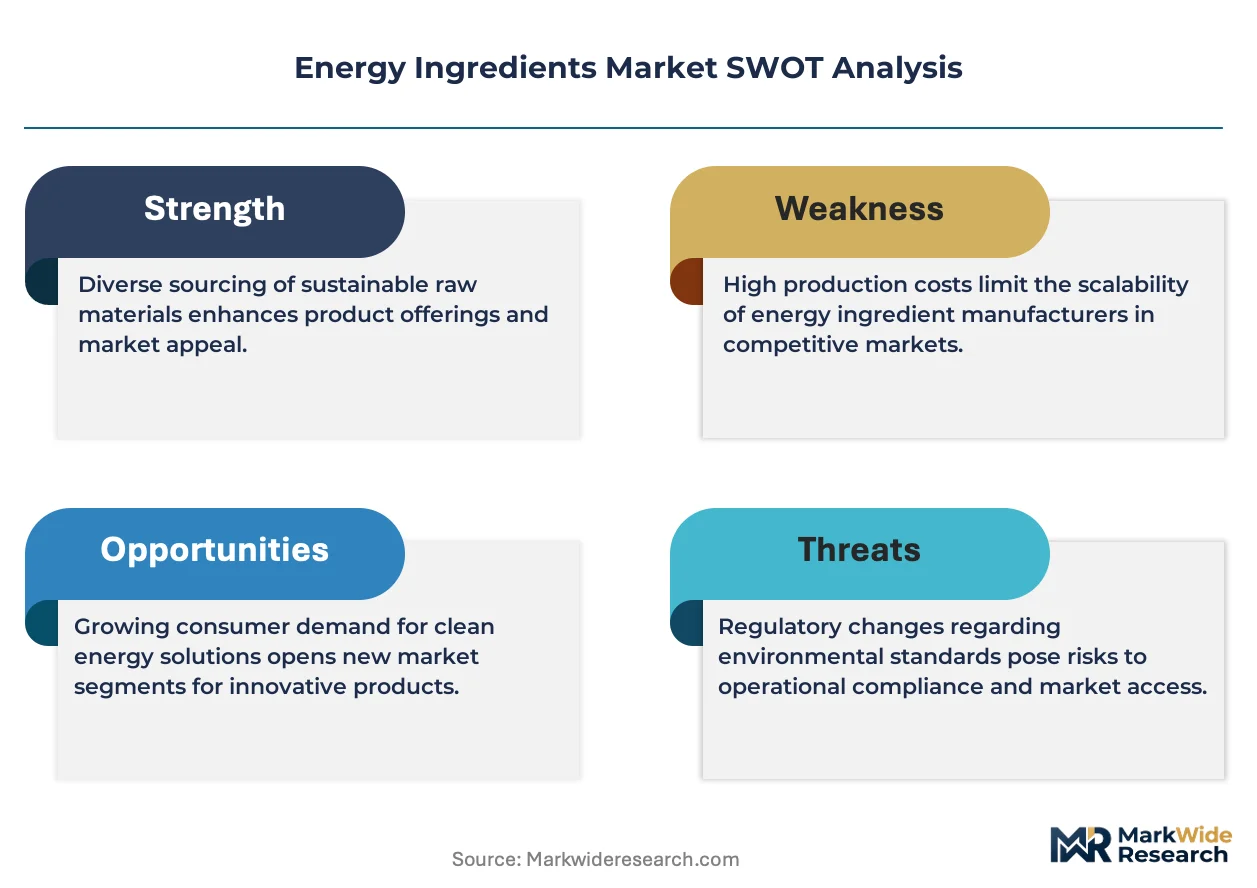
A shift from single-source to multi-source procurement is rebalancing the supply chain for key ingredients like caffeine and taurine. This creates opportunities for suppliers with diverse portfolios. Archer Daniels Midland leverages its extensive agricultural sourcing to provide plant-based proteins and carbohydrates. Meanwhile, BASF SE specializes in high-purity, synthetic vitamins and minerals for the functional beverage sector.
Energy ingredients are compounds formulated to enhance physical stamina, mental alertness, and metabolic efficiency. These substances, including carbohydrates and proteins, act on physiological pathways to delay fatigue. While beverages remain a dominant application, demand for plant-based sources like ginseng and green tea extract is growing faster than for traditional synthetic ingredients. This shift impacts formulation strategies across sports nutrition and dietary supplements.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern health claims and permissible ingredient levels. In China, the State Administration for Market Regulation (SAMR) enforces strict standards on functional food registrations. Navigating these varied international regulations is a critical competency for manufacturers seeking to expand their geographic footprint.
Market Dynamics
The central tension shaping the energy ingredients market is the conflict between rising consumer demand for natural, plant-based sources and the established supply chain's efficiency in producing low-cost synthetic compounds like caffeine and taurine.
Growth Catalysts
- Sports Nutrition Expansion:The mainstreaming of sports nutrition products into general consumer wellness routines is increasing volume demand for ingredients like whey protein, creatine, and branched-chain amino acids (BCAAs) beyond elite athletic circles.
- Plant-Based Preference:A strong consumer pull towards clean-label products is accelerating the adoption of botanical ingredients such as ginseng, guarana, and green tea extract, particularly within the North American beverage market.
- EFSA Health Claim Framework:The European Food Safety Authority's structured process for health claim substantiation, while rigorous, creates a clear pathway for companies to differentiate ingredients with proven efficacy, encouraging targeted R&D investment.
Market Restraints
- Caffeine Price Volatility:Dependence on agricultural outputs from Brazil and Vietnam for natural caffeine and chemical production in China for synthetic versions creates significant price instability, impacting margins for beverage manufacturers.
- FDA Regulatory Hurdles:The US Food and Drug Administration's New Dietary Ingredient (NDI) notification process imposes a lengthy and expensive barrier to entry for novel compounds, slowing innovation in the supplement sector.
- Taurine Supply Concentration:A high concentration of global taurine manufacturing within a few facilities in China exposes the functional food industry to significant supply chain and geopolitical disruption risks.
Strategic Opportunities
- Cognitive Health Formulations:Blending energy with nootropic benefits opens a new frontier for ingredients like L-theanine and citicoline in products designed for gamers, students, and professionals seeking enhanced mental focus.
- Fermentation-Derived Ingredients:Advances in precision fermentation enable the production of bio-identical vitamins and amino acids, offering a sustainable, non-synthetic alternative that aligns with clean-label consumer demands.
- Indian Dietary Supplement Market:Growing disposable incomes and a proactive regulatory environment under the FSSAI make India a high-potential expansion market for vitamins, minerals, and herbal extracts.
Industry Challenges
- Sensory Profile Masking:Formulators face a persistent technical challenge in masking the inherent bitterness and off-notes of potent botanical extracts without compromising the clean-label integrity of the final product.
- Navigating Global Regulatory Divergence:Developing a single product formulation that complies with disparate ingredient limits and health claim rules from the EFSA, FDA, and China's SAMR is a major operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Ingredients Market |
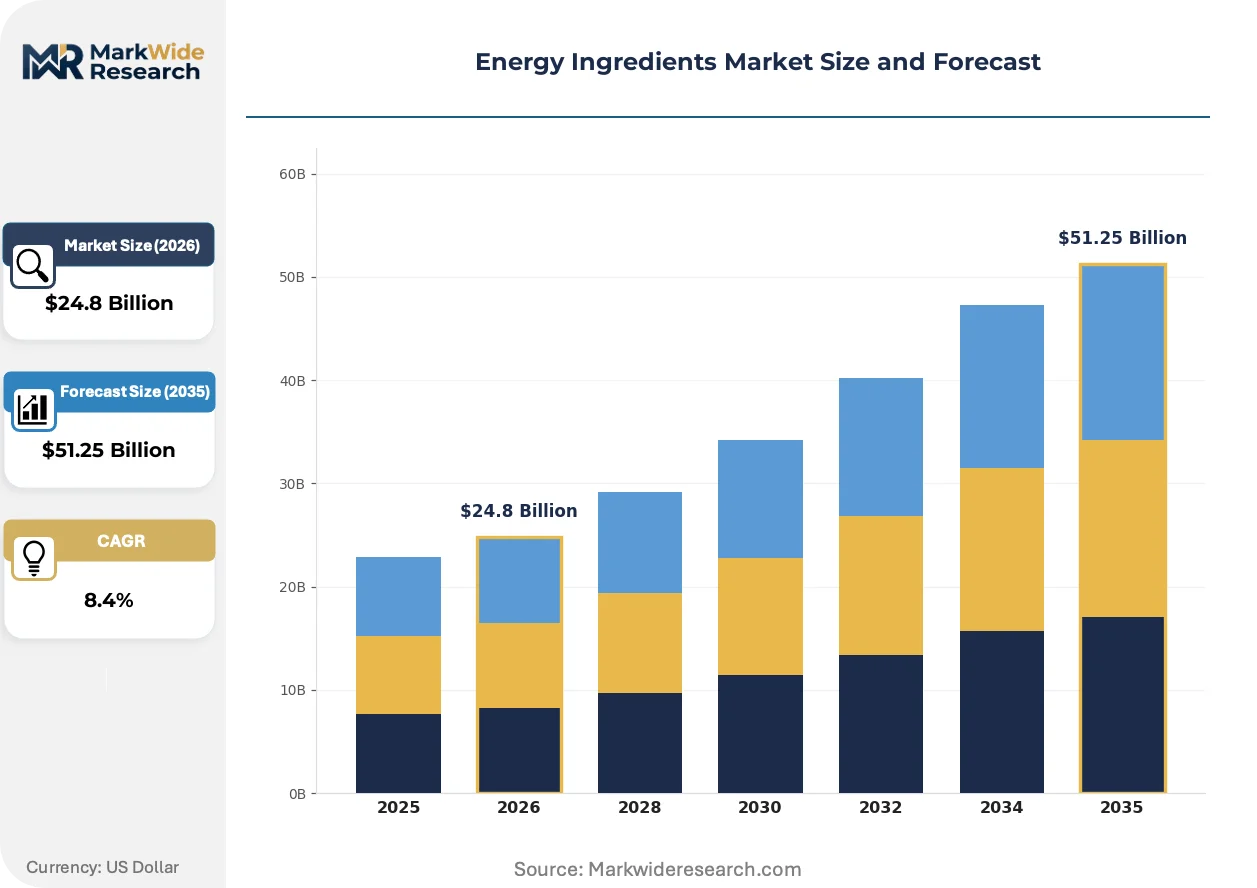
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Carbohydrates, Proteins, Fats, Fiber Application: Sports Nutrition, Functional Foods, Dietary Supplements, Beverages Source: Plant-Based, Animal-Based, Synthetic, Fermented Form: Powders, Liquids, Bars, Capsules |
| Companies Covered | BASF SE, Spectrum Chemical Mfg. Corp., RFI Ingredients, Korea Ginseng Corporation, Orkla, ILHWA CO., LTD., Applied Food Sciences, Inc., Archer Daniels Midland, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Ingredients Market Strategic Shifts & Innovations
Ingredient functionality is expanding beyond simple stimulation to encompass holistic metabolic and cognitive benefits. This evolution is compelling formulators to prioritize multi-functional compounds, fundamentally altering product development strategies in the functional food and beverage sectors.
Microencapsulation technology provides a protective barrier for sensitive compounds like vitamins and caffeine against heat, light, and pH changes. The sports nutrition sector is adopting this to create products with controlled, timed-release profiles for sustained performance. This innovation is decentralizing product efficacy from simple ingredient dosage to the sophistication of its delivery mechanism within the body.
The European Food Safety Authority (EFSA) is tightening its evaluation of health claims related to caffeine and other stimulants. This regulatory scrutiny compels manufacturers to invest in robust clinical trials to substantiate claims about alertness and endurance. The energy drink and pre-workout supplement categories are most affected, prompting a shift toward more scientifically-backed formulation strategies.
A clear behavioral change is visible as brands move from purchasing individual raw materials to sourcing pre-formulated, customized ingredient blends. This disrupts the traditional in-house R&D and procurement model for many CPG companies, outsourcing complexity to specialized ingredient system suppliers. This trend is most apparent among mid-sized beverage brands in the United States seeking to accelerate their speed to market.
Energy Ingredients Market Segmentation
Understanding the intricate segmentation of the energy ingredients market reveals diverse pathways for product innovation and market penetration. Ingredient selection hinges on specific functional requirements, consumer preferences, and regulatory compliance across varied applications. This granular analysis provides manufacturers with a roadmap for targeted product development and strategic sourcing.
Type:
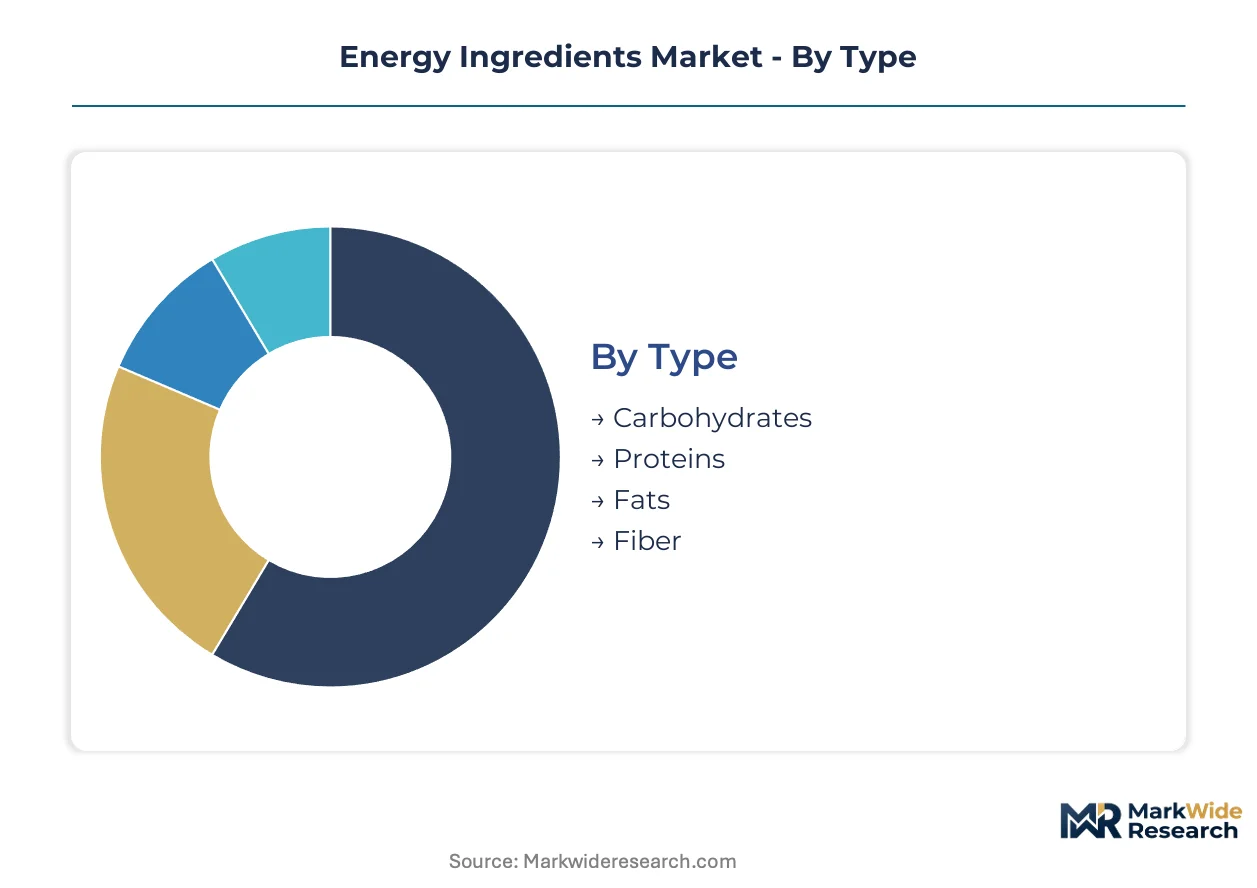
The market for energy ingredients differentiates compounds based on their primary biochemical function and metabolic pathway.
- Carbohydrates:These compounds, including simple sugars and complex starches, provide readily available energy for immediate physical activity and sustained endurance. Demand concentrates in sports beverages and pre-workout formulations due to their rapid absorption and glucose replenishment properties.
- Proteins:Comprising amino acids, proteins support muscle repair, growth, and satiety, contributing to sustained energy release and recovery. The sports nutrition segment drives significant demand for protein isolates and concentrates, particularly whey and casein, for post-exercise recovery.
- Fats:Essential fatty acids and medium-chain triglycerides offer a dense, long-lasting energy source, particularly beneficial for endurance athletes.
- Fiber:Dietary fiber contributes to digestive health and can modulate glucose absorption, indirectly supporting stable energy levels throughout the day.
Mature deployment sits with Carbohydrates. Newer deployment is concentrated in Proteins.
Application:
Demand for energy ingredients varies significantly across diverse end-use applications, each targeting specific consumer needs.
- Sports Nutrition:This segment encompasses products designed to enhance athletic performance, recovery, and muscle development, utilizing ingredients like creatine, BCAAs, and specialized proteins. The mainstreaming of fitness culture beyond elite athletes drives volume demand across North America and Europe.
- Beverages:Energy drinks and functional beverages incorporate stimulants, vitamins, and botanicals to provide mental alertness and physical stamina. Consumer preference for natural extracts like green tea and guarana influences formulation strategies in the US.
- Functional Foods:Foods fortified with energy-boosting ingredients aim to provide sustained vitality and specific health benefits beyond basic nutrition. This category includes energy bars and fortified snacks, appealing to on-the-go consumers.
- Dietary Supplements:Capsules, tablets, and powders contain concentrated doses of energy ingredients, often targeting specific physiological pathways for alertness or metabolic support. The US FDA's New Dietary Ingredient notification process impacts innovation in this sector.
Sports Nutrition represents the fastest-growing trajectory for energy ingredients. Functional Foods also show significant expansion.
Source:
The origin of energy ingredients, whether natural or manufactured, influences consumer perception and supply chain dynamics.
- Plant-Based:Derived from botanical extracts such as ginseng, guarana, and green tea, these sources align with clean-label trends and offer a natural energy boost. Consumer pull for these ingredients is strong in the North American beverage market.
- Synthetic:Chemically manufactured compounds like caffeine anhydrous and taurine offer consistent purity and cost-effectiveness, dominating the traditional energy drink market. China's chemical production facilities are critical for global supply.
- Animal-Based:Ingredients like whey protein, creatine, and collagen are sourced from animal products, primarily serving the sports nutrition and recovery segments.
- Fermented:Produced through microbial fermentation, these ingredients offer sustainable and often bio-identical alternatives to synthetic or animal-derived compounds. Advances in precision fermentation are opening new avenues for vitamins and amino acids.
Plant-Based sources are gaining share fastest among consumers. Traditional Synthetic ingredients maintain a substantial market presence.
Form:
The physical presentation of energy ingredients directly impacts consumer convenience and product integration.
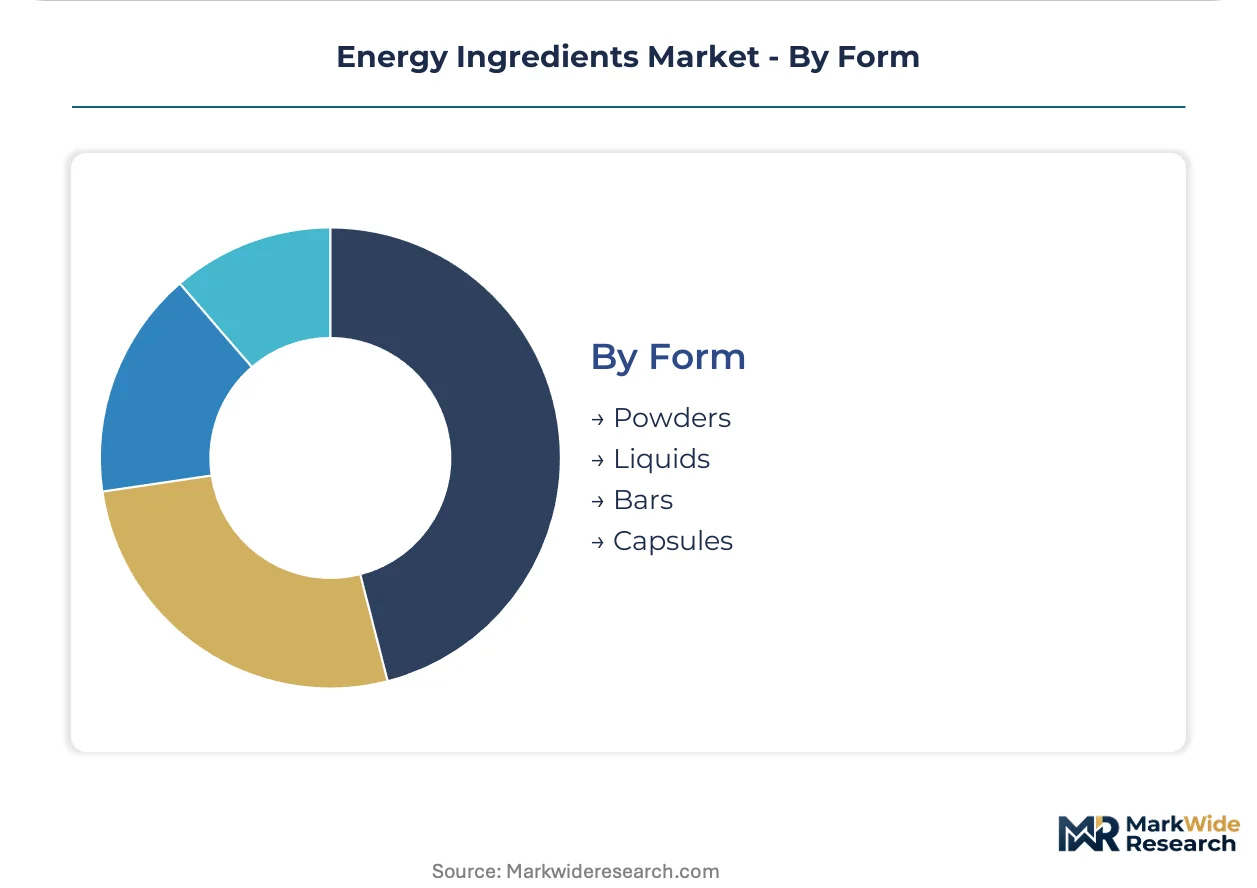
- Powders:Highly versatile, powders allow for customizable dosing and easy integration into shakes, smoothies, and bulk supplement formulations. This form is popular in the sports nutrition and dietary supplement sectors for its flexibility.
- Liquids:Ready-to-drink beverages and liquid shots offer immediate consumption and rapid absorption, catering to consumers seeking instant energy. Formulation challenges include masking off-notes from potent extracts.
- Bars:Energy bars provide a convenient, portable format for sustained energy release, often combining carbohydrates, proteins, and fats. This form appeals to consumers seeking on-the-go nutrition.
- Capsules:Encapsulated ingredients offer precise dosage and mask undesirable tastes, commonly used for concentrated dietary supplements and vitamins.
Liquids offer immediate bioavailability and convenience. Powders provide dosage flexibility for manufacturers and consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chemical manufacturing capabilities anchor the global supply of synthetic energy ingredients. This market experiences varied growth patterns influenced by local consumer preferences and regulatory environments. Demand for energy ingredients is strong in key economies.
United States
United States consumers demonstrate strong demand for sports nutrition products and functional beverages. The US Food and Drug Administration (FDA) New Dietary Ingredient (NDI) notification process shapes innovation in dietary supplements. California's vibrant food and beverage industry drives product development for plant-based and clean-label energy solutions.
China
China's market for energy ingredients is characterized by stringent functional food registration requirements. The State Administration for Market Regulation (SAMR) enforces rigorous standards for ingredient approval. The Yangtze River Delta region, with its robust chemical and pharmaceutical industries, serves as a major hub for synthetic ingredient production.
India
India's dietary supplement market shows substantial growth, propelled by rising disposable incomes and a health-conscious population. The Food Safety and Standards Authority of India (FSSAI) provides a proactive regulatory framework. Maharashtra, a key pharmaceutical manufacturing state, sees increasing production of nutraceuticals and energy ingredient formulations.
Germany
Germany, a significant European market, exhibits strong demand for functional beverages and sports nutrition. The European Food Safety Authority (EFSA) health claim framework influences product formulation across the European Union. Bavaria, a center for food processing and research, fosters innovation in ingredient development for performance and wellness products.
Brazil
Brazil plays a critical role in the global supply of natural caffeine derived from agricultural outputs. The country's National Health Surveillance Agency (ANVISA) regulates food supplements and functional ingredients. Minas Gerais, a prominent agricultural state, contributes substantially to the sourcing and initial processing of botanical extracts.
Energy Ingredients Market Key Industry Players
Global majors compete with regional champions across ingredient sourcing and formulation expertise, navigating diverse regulatory landscapes. The market structure exhibits a tiered consolidation, with large-scale producers holding significant sway in foundational ingredients. Diversified ingredient suppliers, specialized synthetic chemical manufacturers, and botanical extract specialists form the primary strategic archetypes. Portfolio diversification, strategic partnerships, and geographic expansion are dominant competitive moves for market participants.
Within the large-scale ingredient supplier tier, Archer Daniels Midland exemplifies a diversified agricultural powerhouse, providing extensive plant-based proteins and carbohydrates. BASF SE represents a major European chemical company specializing in high-purity synthetic vitamins and minerals crucial for functional beverages. Korea Ginseng Corporation occupies a position as a specialized botanical extract supplier, focusing on natural energy sources like ginseng. These entities highlight the varied approaches to ingredient production, market access, and alignment with consumer preferences for synthetic or natural origins.
| Leading Market Players |
|---|
| BASF SE |
| Spectrum Chemical Mfg. Corp. |
| RFI Ingredients |
| Korea Ginseng Corporation |
| Orkla |
| ILHWA CO., LTD. |
| Applied Food Sciences, Inc. |
| Archer Daniels Midland |
| Cargill |
| Others |
Cost & Logistics Intelligence
Skilled fermentation scientists in European biotech hubs influence pricing tiers for bio-identical amino acids. Their specialized expertise and limited availability create a premium for precision-fermented ingredients, impacting overall market costs.
Pricing Analysis
The inclusion of comprehensive technical support and certification documentation often dictates pricing for energy ingredients. Pricing operates on a contract-based long-term offtake model for bulk commodities, transitioning to per-unit transactional for specialized ingredient blends. Purity grade and volume scale are primary price differentiation drivers. Pricing softness stems from the increasing efficiency of synthetic ingredient production in China. Mid-sized beverage brands exhibit higher price sensitivity compared to large, established CPG manufacturers.
Supply Chain Analysis
Dual-sourcing requirements from major food and beverage manufacturers mitigate risks in the energy ingredients supply chain. Geographic supply concentrates in China for synthetic compounds like taurine, and Brazil and Vietnam for natural caffeine. Raw material dependencies include agricultural outputs for botanical extracts and chemical precursors for synthetic amino acids. Geopolitical disruption in key manufacturing regions presents a structural supply chain risk. Distribution runs through a mix of direct sales from large ingredient manufacturers and specialized ingredient distributors to CPG companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy ingredients market is consolidating, driven by rigorous regulatory scrutiny from bodies like the EFSA. This pressure on health claim substantiation forces smaller, less resourced players to exit or merge.
For Market Incumbents:Lock in long-term supply agreements for critical raw materials like caffeine and taurine to stabilize input costs. Invest in advanced microencapsulation technologies to differentiate product offerings against generic alternatives, mitigating threats from commoditization. Enhance R&D into multi-functional compounds, leveraging existing scientific expertise. Pursue strategic acquisitions of specialized botanical extract suppliers to broaden the natural ingredient portfolio.
For New Entrants and Emerging Players:Mid-sized beverage brands seeking accelerated speed to market represent an underserved buyer archetype. Target the functional beverage sector with customized ingredient blends, emphasizing clean-label botanicals and sustainable fermentation-derived compounds. Focus on niche applications like cognitive health formulations for gamers and students. A strong go-to-market angle involves offering comprehensive regulatory support for novel ingredients, easing market entry for buyers.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized ingredient system suppliers given the trend toward outsourced R&D by CPG companies. Long-term viability depends on firms capable of navigating global regulatory divergence and offering multi-functional, scientifically-backed ingredients. Monitor companies with strong intellectual property in precision fermentation technologies. A signal to watch is the increasing investment in clinical trials for novel plant-based extracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify Raw Material Sourcing | Reduces dependence on single regions, like China for taurine, enhancing supply chain resilience. |
| Invest in Precision Fermentation | Develops sustainable, bio-identical alternatives aligning with clean-label consumer demand in North America. |
| Expand into India's Supplement Market | Captures growth from rising disposable incomes and proactive FSSAI regulatory support for nutraceuticals. |
| Develop Cognitive Health Blends | Addresses demand from gamers and professionals for enhanced mental focus beyond traditional energy benefits. |
| Adopt Advanced Microencapsulation | Creates controlled-release profiles for caffeine and vitamins, improving product efficacy and consumer experience. |
Research Approach
EFSA health claim reports, FDA New Dietary Ingredient filings, and SAMR functional food registrations formed the secondary backbone of this analysis. Primary interviews with CPG procurement managers, ingredient R&D scientists, and regulatory affairs specialists validated market dynamics. This combined approach utilized both bottom-up market sizing and top-down industry trend verification.
Historical trendline analysis established foundational growth patterns across the analysis window. The market was segmented by ingredient type, application, source, and form, alongside regional regulatory differences. Compound annual growth rates were derived from a multi-factor regression model, incorporating consumer preference shifts towards plant-based sources and sports nutrition expansion.
Revisions become necessary when significant shifts in international trade policies or major regulatory amendments materialize. Forecasts reflect current market assumptions, accounting for known supply chain vulnerabilities. Deviation in raw material commodity pricing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Konjac Flour Market
Ingredients
Food Ingredients Market
Ingredients
Dry Malt Products Market
Ingredients
Global Natural Gum Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Lupine Peptides Market
Ingredients
Rose Hips Extract Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
South America Malt Ingredient Market
Ingredients
Seaweed Extracts Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
US Plant-Based Oils Market