
 Rose Hips Extract Market | 2026-2036
Rose Hips Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Rose Hips Extract Market Insights
Single-serve capsule bundling is consolidating buyer choice in the Rose Hips Extract landscape, pushing volume purchasers toward pre-formulated combinations over bulk powder sourcing. Martin Bauer Group leverages its German extraction infrastructure to dominate European pharmaceutical-grade supply. Döhler GmbH sustains beverage-application leadership through integrated flavor-botanical formulation capabilities. Frutarom (IFF) competes on kosher and halal-certified extract lines for North American dietary supplement brands.
Rose hips extract comprises lipophilic and hydrophilic fractions derived from Rosa canina L. fruit, typically standardized to 5-70% vitamin C content and 0.5-5% galactolipids through aqueous ethanol or supercritical CO2 processing, serving primarily as an antioxidant and anti-inflammatory active in nutraceutical and cosmetic matrices. Powder formats anchor the volume base due to stability in blending operations and lower unit logistics cost, while liquid extracts capture faster expansion in functional beverage pipelines where cold-fill compatibility matters. Pharmaceutical applications occupy the premium margin tier, with extractors pursuing USP or EP monograph alignment to access prescription-adjacent channels.
FDA dietary supplement cGMPs, EFSA Novel Food catalog listings, and USDA organic certification collectively determine market access thresholds and label claim permissibility for rose hips extract suppliers across target geographies. The EU F-Gas Regulation indirectly shapes extraction economics by restricting certain solvent recovery systems, nudging capital investment toward supercritical CO2 infrastructure. Stakeholders must monitor evolving pharmacopeial monograph updates and organic equivalency agreements to defend supply chain positioning.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing synthetic additive pipelines, forcing dietary supplement and cosmetic manufacturers toward standardized botanical actives with verified polyphenol and galactolipid profiles.
Growth Catalysts
- EFSA Novel Food substantiation:The EU's tightened health claim assessments are filtering out unverified botanical suppliers, concentrating procurement among extractors with pharmacopeial-grade documentation and clinical trial backing.
- Supercritical CO2 processing:Solvent-free extraction infrastructure is capturing investment as EU F-Gas Regulation restrictions raise operating costs for conventional ethanol recovery systems.
- Functional beverage pipelines:Cold-fill compatible liquid extract formats are displacing powder in ready-to-drink applications where heat-sensitive vitamin C retention determines shelf stability.
Market Restraints
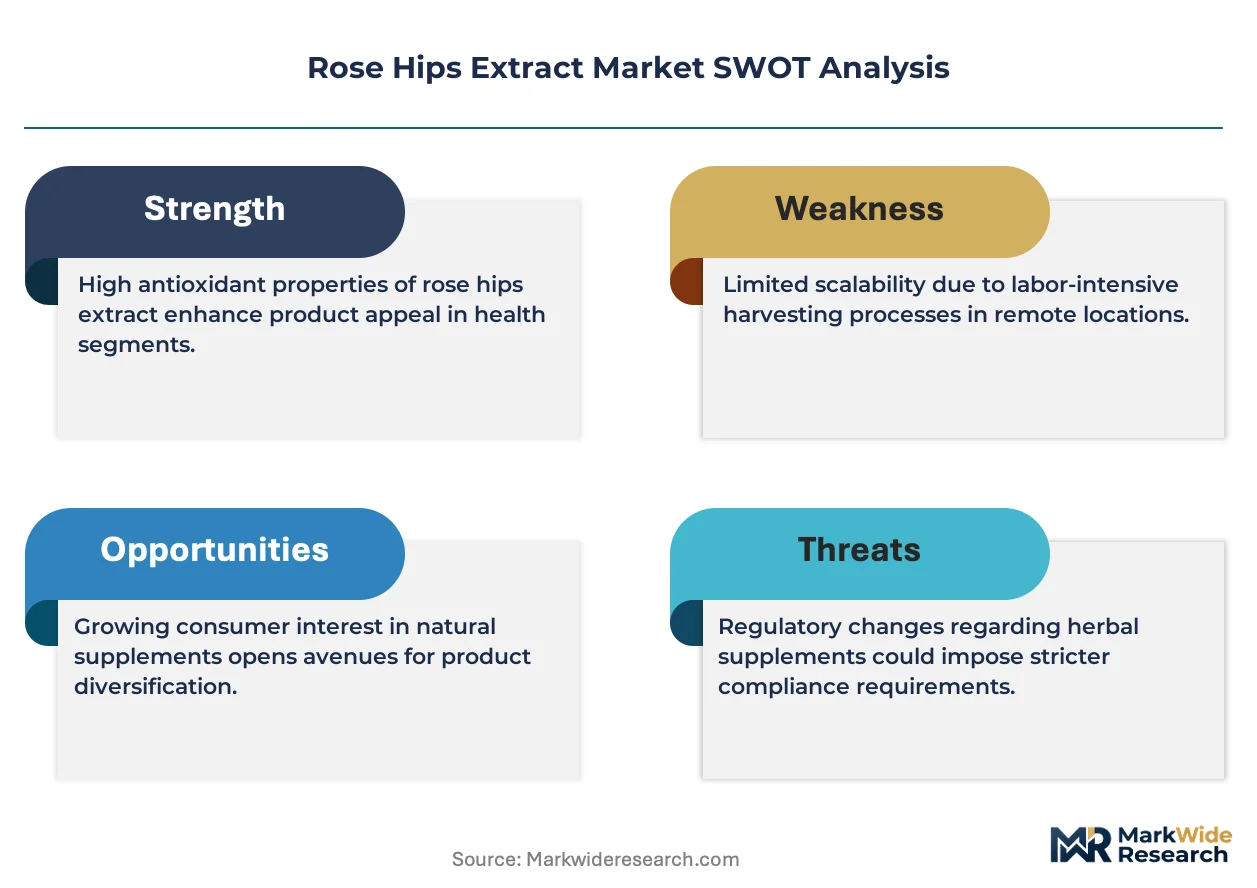
- Wild-harvest supply volatility:Rosa canina L. raw material availability fluctuates with Balkan and Eastern European climatic cycles, concentrating risk among extractors without contracted cultivation partnerships.
- Galactolipid standardization costs:Analytical method development for 0.5-5% galactolipid quantification requires HPLC-ELSD infrastructure that mid-tier extractors struggle to amortize across low-volume SKUs.
- Synthetic vitamin C substitution:Ascorbic acid from fermented corn glucose retains cost advantages in mass-market fortification, capping rose hips extract penetration in price-sensitive commodity channels.
Strategic Opportunities
- USDA organic equivalency expansion:Bilateral organic recognition agreements between the US and select Eastern European sourcing regions are opening tariff-advantaged supply corridors for certified extract lines.
- Prescription-adjacent pharmaceutical channels:USP and EP monograph alignment is enabling extractors to access osteoarthritis and dermatology adjuvant markets previously served by synthetic anti-inflammatories.
- Halal and kosher certification convergence:Dual-certified production lines are capturing North American contract manufacturing demand from brands targeting diverse demographic distribution.
Industry Challenges
- Phytochemical analyst scarcity:Specialized competence in rose hips polyphenol fingerprinting and galactolipid quantification is concentrated among aging pharmacognosy specialists in Central European research institutes.
- Multi-jurisdiction dossier maintenance:Parallel FDA cGMP, EFSA Novel Food, and Health Canada NHP compliance documentation demands dedicated regulatory affairs capacity that fragments smaller extractor resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rose Hips Extract Market |
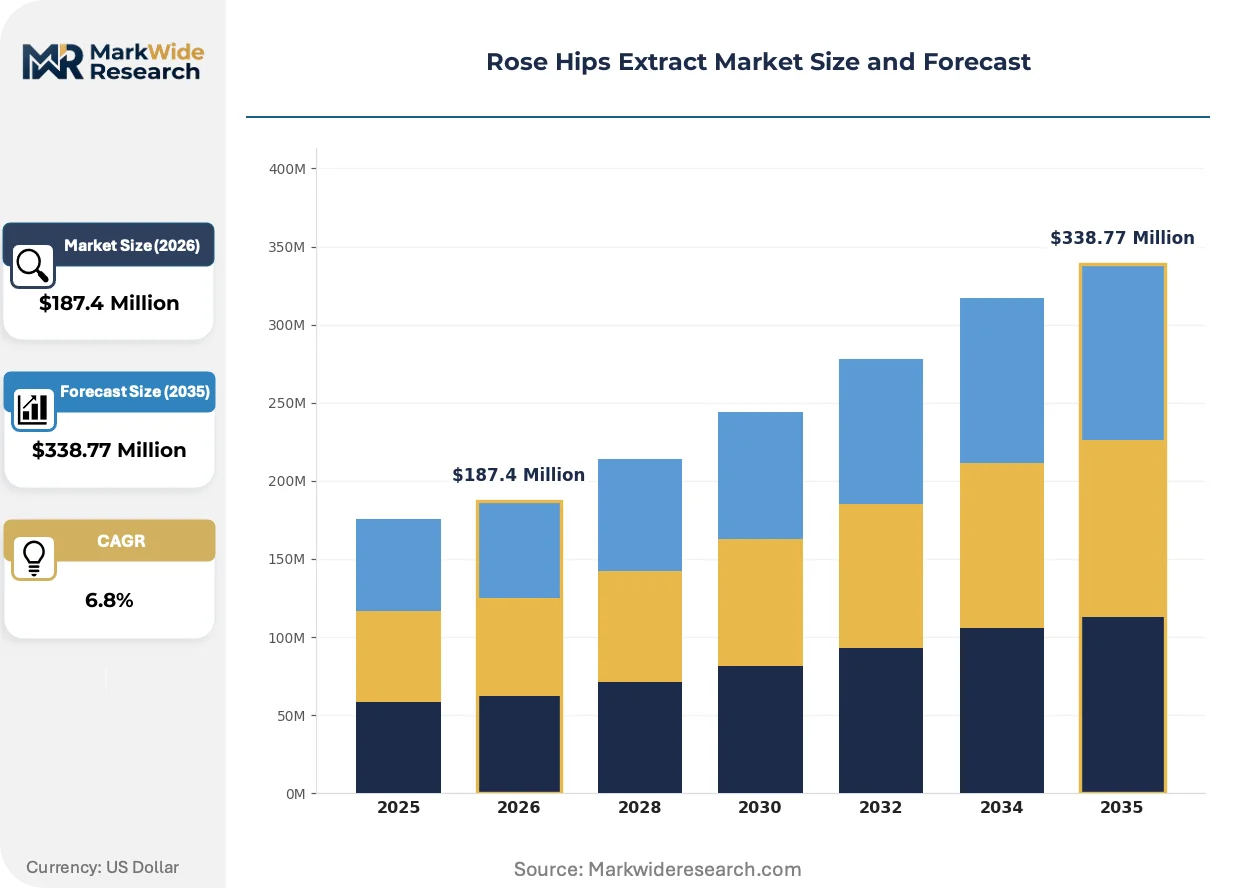
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tea Application: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements End User: Manufacturers, Retailers, Wholesalers, E-commerce Platforms Distribution Channel: Online, Offline, Health Stores, Specialty Stores |
| Companies Covered | Martin Bauer Group, Frutarom (IFF), Döhler GmbH, Sabinsa Corporation, Bio-Botanica Inc., Afrigetics Botanicals, AG Industries, Agroprodex Internacional S.A., A.Vogel AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rose Hips Extract Market Trends and Innovations
Extraction technology convergence and regulatory documentation automation are compressing time-to-market for standardized botanical actives while reshaping buyer-supplier contracting structures.
Supercritical CO2 extraction with integrated online IR spectroscopy is unifying real-time galactolipid monitoring with solvent-free processing. German and Swiss pharmaceutical-grade extractors are deploying this infrastructure to secure EFSA health claim eligibility. The technology is unifying quality assurance and production into single-pass operations that eliminate batch rejection risks.
EU F-Gas Regulation phase-down schedules are accelerating capital migration away from conventional solvent recovery systems. Extraction facilities in Germany and Poland are retrofitting closed-loop CO2 infrastructure to maintain operating permits. Pharmaceutical and cosmetic-grade extract segments bear the highest compliance burden, with smaller Balkan processors facing stranded asset risk.
Pre-formulated capsule bundling is consolidating procurement decisions among North American dietary supplement brands. Bulk powder spot purchasing is contracting as contract manufacturers demand single-SKU antioxidant-anti-inflammatory combinations with verified stability data. This pattern is most pronounced in US West Coast functional nutrition clusters where clean-label positioning commands shelf access.
Rose Hips Extract Market Segmentation
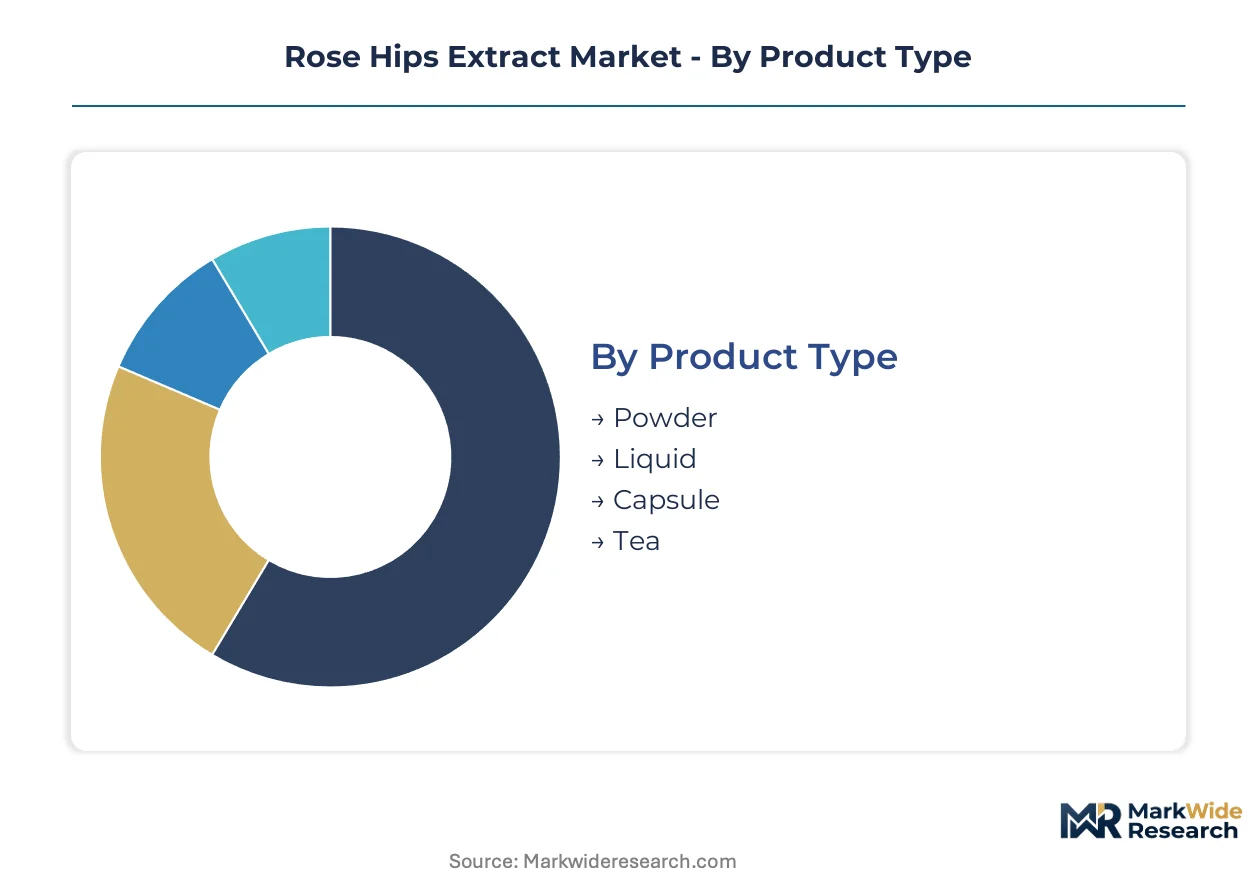
Rose hips extract procurement patterns diverge sharply across format stability requirements and end-use regulatory thresholds. Manufacturers prioritize powder and liquid matrices for divergent processing constraints, while pharmaceutical and cosmetic channels impose distinct standardization protocols.
Product Type:
Format selection tracks the upgrade cycle from bulk commodity sourcing toward pre-formulated, stability-verified delivery systems.
- Powder:Spray-dried or freeze-dried matrices standardized to 5-70% vitamin C content anchor high-volume blending operations for dietary supplement tablets and cosmetic dry mixes. Demand concentrates in German pharmaceutical-grade extractors supplying Martin Bauer Group, where lower unit logistics costs defend margin in multi-ton procurement contracts.
- Liquid:Aqueous ethanol or glycerin-based extracts with cold-fill compatibility capture functional beverage pipelines requiring heat-sensitive vitamin C retention. North American ready-to-drink brands are displacing powder sourcing as clean-label positioning demands transparent, single-ingredient liquid declarations.
- Capsule:Pre-formulated softgel and hardshell units combine rose hips extract with complementary botanicals for direct-to-consumer finished goods.
- Tea:Cut-and-sift or milled whole-fruit preparations serve traditional medicine channels in Eastern European and Balkan markets.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Application segmentation reflects divergent margin tiers tied to pharmacopeial documentation depth and clinical substantiation requirements.
- Food & Beverage:Functional fortification applications leverage liquid extract formats for cold-processed juices and fermented beverages. German and Polish beverage manufacturers prioritize EFSA Novel Food catalog-listed suppliers to preempt health claim rejection.
- Pharmaceuticals:USP or EP monograph-aligned extracts serve osteoarthritis adjuvant and dermatology prescription-adjacent channels. US and Swiss contract manufacturers demand batch-specific galactolipid certificates of analysis.
- Cosmetics:Antioxidant actives in topical formulations require INCI-compliant labeling and REACH registration for EU market access.
- Dietary Supplements:Single-serve capsule bundling consolidates procurement among North American brands seeking kosher and halal-certified supply lines.
Pharmaceuticals command the steepest expansion trajectory as prescription-adjacent channels open; Food & Beverage anchors absolute volume throughput.
End User:
Customer-type segmentation tracks the backward integration pressure from finished goods brands seeking captive extract supply.
- Manufacturers:Dietary supplement and cosmetic formulators with in-house blending capacity purchase bulk powder and liquid for SKU customization. Döhler GmbH's integrated flavor-botanical capabilities illustrate beverage-manufacturer demand for pre-standardized inputs.
- Retailers:Private-label contract manufacturing arrangements concentrate procurement decisions among US West Coast functional nutrition clusters.
- Wholesalers:Spot-market powder sourcing persists in price-sensitive commodity channels where synthetic vitamin C substitution caps botanical penetration.
- E-commerce Platforms:Direct-to-consumer brands demand small-batch, certified-organic extract lines with full traceability documentation.
Manufacturers dominate current volume; E-commerce Platforms are climbing the fastest as digital-native brands bypass traditional distribution.
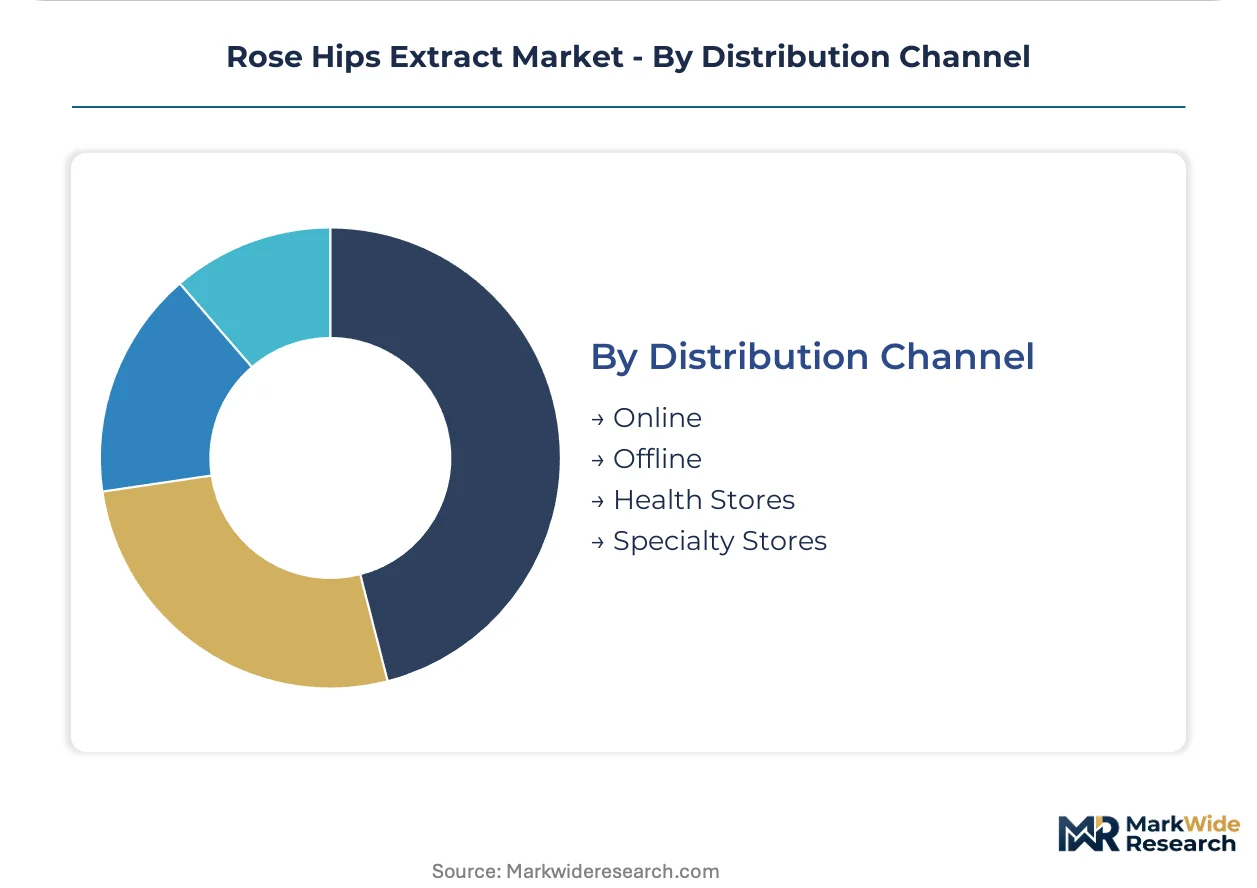
Distribution Channel:
Channel configuration reflects the tension between traceability-verified direct sourcing and established retail access.
- Online:B2B platforms and supplier-direct procurement enable small-batch certified extract access for emerging brands. US and Canadian dietary supplement startups leverage digital channels to bypass minimum order quantities imposed by traditional wholesalers.
- Offline:Conventional ingredient distributor networks maintain dominance in pharmaceutical-grade supply where audit-verified warehousing and chain-of-custody documentation are mandatory.
- Health Stores:Finished goods retail channels drive consumer-facing brand demand for pre-packaged capsule and tea formats.
- Specialty Stores:Professional-grade channels serving naturopathic practitioners and compounding pharmacies require extract lines with clinical trial backing.
Offline channels retain volume concentration; Online is gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade extraction capacity while the United States drives dietary supplement consumption. Wild-harvest supply chains anchor Balkan and Eastern European raw material flows. Regulatory divergence between FDA cGMPs and EFSA Novel Food standards fragments compliance investment across Atlantic suppliers.
Germany
Pharmaceutical-grade extraction infrastructure and beverage-application formulation capabilities concentrate procurement decisions among domestic manufacturers. EFSA Novel Food catalog listings and EU F-Gas Regulation compliance shape capital allocation toward supercritical CO2 processing. The Martin Bauer Group anchors concentrated production capacity in German extraction facilities serving European pharmaceutical supply chains.
United States
Single-serve capsule bundling and direct-to-consumer brand proliferation drive demand for kosher and halal-certified extract lines. FDA dietary supplement cGMPs determine market access thresholds and label claim permissibility for botanical suppliers. West Coast functional nutrition clusters concentrate private-label contract manufacturing arrangements among emerging brands.
Poland
Retrofitting of closed-loop CO2 infrastructure maintains operating permits under EU F-Gas Regulation phase-down schedules. Wild-harvest Rosa canina L. availability fluctuates with climatic cycles, concentrating risk among extractors without contracted cultivation partnerships. Processing facilities in Polish industrial zones serve as secondary extraction capacity for German pharmaceutical-grade supply.
Switzerland
Contract manufacturers demand USP and EP monograph-aligned extracts for osteoarthritis adjuvant and dermatology prescription-adjacent channels. Swissmedic pharmaceutical regulations enforce batch-specific galactolipid certificate requirements. Swiss extraction specialists deploy integrated online IR spectroscopy for real-time quality assurance in single-pass operations.
South Africa
Bilateral organic recognition agreements with the United States open tariff-advantaged supply corridors for certified extract lines. Indigenous botanical sourcing capabilities position regional suppliers for North American e-commerce platform demand. Afrigetics Botanicals anchors concentrated raw material procurement from contracted cultivation partnerships in Eastern Cape and KwaZulu-Natal growing regions.
Rose Hips Extract Market Competitive Landscape
The competitive structure tilts toward integrated extraction specialists with pharmacopeial documentation capabilities. Tiered player concentration separates pharmaceutical-grade extractors with USP alignment from beverage-application formulators and commodity powder suppliers. Three archetypes dominate: German pharmaceutical-grade specialists, North American certification-focused suppliers, and Balkan wild-harvest processors. Capacity expansion and regulatory dossier automation represent the dominant competitive moves as compliance costs fragment smaller extractor resources.
Among German extraction specialists, Martin Bauer Group and Döhler GmbH exemplify divergent strategic positioning within the same regulatory geography. Martin Bauer Group occupies a position representing pharmaceutical-grade supply concentration, while Döhler GmbH exemplifies integrated flavor-botanical formulation capabilities for beverage pipelines. Frutarom, now operating within IFF, represents the certification-focused archetype for North American dietary supplement brands seeking kosher and halal supply lines. These three entities collectively illustrate how regulatory geography and end-use specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Martin Bauer Group |
| Frutarom (IFF) |
| Döhler GmbH |
| Sabinsa Corporation |
| Bio-Botanica Inc. |
| Afrigetics Botanicals |
| AG Industries |
| Agroprodex Internacional S.A. |
| A.Vogel AG |
| Others |
Pricing and Supply Chain Analysis
Single-serve capsule bundling among North American dietary supplement brands is compressing bulk powder spot markets, forcing extractors toward pre-formulated stability-verified formats that command premium positioning. This procurement consolidation concentrates pricing power among German pharmaceutical-grade suppliers with integrated supercritical CO2 infrastructure while squeezing Balkan wild-harvest processors on standardization costs.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects EFSA Novel Food substantiation investments and USP monograph alignment costs that smaller extractors cannot amortize. Three-tier pricing structure across pharmaceutical, beverage-application, and commodity powder levels tracks certification depth and galactolipid standardization precision. Cost-down pressure on economy-grade powder accelerates because synthetic vitamin C from fermented corn glucose retains cost advantages in mass-market fortification. Contract manufacturers demonstrate highest price sensitivity, while Swiss prescription-adjacent channels absorb premiums for batch-specific analytical documentation.
Supply Chain Analysis
Rosa canina L. raw material availability rests on wild-harvest collection networks across Bulgaria, Romania, and Serbia, with climatic cycles in Balkan growing regions introducing annual volume volatility. Aqueous ethanol and supercritical CO2 extraction equipment draws from German and Swiss specialty engineering suppliers, while analytical reference standards for galactolipid quantification hinge on Central European pharmacognosy institutes. Single-source vulnerability concentrates in wild-harvest supply channels lacking contracted cultivation partnerships. Distribution runs through audit-verified ingredient distributor networks for pharmaceutical-grade supply, with B2B platforms capturing emerging brand procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Rose Hips Extract Market is becoming a vertical-integration race as extractors pursue captive control over standardized raw material supply to defend margin against synthetic substitution and regulatory compliance cost escalation.
For Market Incumbents: Acquire contracted Rosa canina L. cultivation partnerships in Eastern European growing regions to insulate supply from climatic volatility. Secure supercritical CO2 infrastructure ahead of EU F-Gas Regulation phase-down deadlines that will strand conventional solvent recovery assets. Döhler GmbH's integrated flavor-botanical capabilities illustrate how beverage-application formulators can lock in cold-fill compatible liquid extract capacity before functional beverage pipelines consolidate procurement. For New Entrants and Emerging Players: USDA organic equivalency expansion between the United States and select Eastern European sourcing regions opens a window for tariff-advantaged certified extract lines targeting North American e-commerce platform demand. Halal and kosher certification convergence captures contract manufacturing demand from West Coast functional nutrition clusters seeking diverse demographic distribution. Direct-to-consumer digital-native brands represent the most penetrable channel, bypassing minimum order quantities imposed by traditional wholesalers through supplier-direct procurement. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier extractors possessing pharmacopeial-grade documentation infrastructure and clinical trial backing for EFSA health claim eligibility, given tightening Novel Food substantiation requirements that filter out unverified botanical suppliers. Swiss and German pharmaceutical-grade specialists with USP or EP monograph alignment command acquisition premiums for prescription-adjacent channel access. Monitor EU F-Gas Regulation enforcement intensity as the inflection indicator for stranded asset risk among Balkan processors lacking CO2 retrofit capital.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Infrastructure Deployment | German extractors secure EFSA health claim eligibility through solvent-free processing with integrated online IR spectroscopy monitoring. |
| Contracted Cultivation Partnerships | Afrigetics Botanicals anchors South African supply through captive Rosa canina L. growing regions in Eastern Cape and KwaZulu-Natal. |
| Dual Halal-Kosher Certification | Frutarom within IFF captures North American contract manufacturing demand from brands targeting diverse demographic distribution channels. |
| Pre-formulated Capsule Bundling | Martin Bauer Group consolidates procurement decisions among dietary supplement brands seeking single-SKU antioxidant-anti-inflammatory combinations. |
| USP and EP Monograph Alignment | Swiss contract manufacturers access osteoarthritis adjuvant markets previously served by synthetic anti-inflammatories through batch-specific galactolipid certificates. |
Research Methodology
Multi-period observation of EFSA Novel Food catalog listings, FDA cGMP enforcement patterns, and supercritical CO2 infrastructure deployment anchored the trend analysis, supplemented by interviews with extraction facility operations managers, regulatory affairs specialists at botanical ingredient suppliers, dietary supplement brand procurement directors, and pharmacognosy researchers at Central European institutes. Secondary validation drew from EU F-Gas Regulation implementation schedules, USDA organic equivalency agreement texts, USP and EP monograph update notices, and customs trade data for Rosa canina L. raw material flows. Bottom-up volume modeling across powder, liquid, capsule, and tea formats triangulated against top-down value projections.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework, with pharmaceutical-grade, beverage-application, and commodity powder tiers receiving distinct growth assumptions. CAGRs were derived from trajectory fitting to historical procurement patterns and regulatory milestone timing. Industry-specific forecast inputs included supercritical CO2 capacity expansion pipelines, bilateral organic recognition agreement negotiations, and EFSA health claim assessment backlogs.
The model assumes a particular technology adoption path; alternative pathways for aqueous ethanol extraction with advanced solvent recovery would alter the outlook if EU F-Gas Regulation enforcement delays materialize. Forecasts reflect assumptions regarding wild-harvest yield stability, pharmacopeial monograph update schedules, and synthetic vitamin C price parity thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Avocado Oil Market
Ingredients
Rooster Comb Extract Market
Ingredients
Coconut Flour Market
Ingredients
Carrot Fiber Market
Ingredients
Cognitive Ingredients Market
Ingredients
Textured Wheat Protein Market
Ingredients
Food Grade Cassia Gum Powder Market
Ingredients
Dill Seed Oil Market
Ingredients
Global Egg White Peptide Market
Ingredients
Carob Protein Market
Ingredients
Pea Hull Fiber Market
Ingredients
Plant Based Thickener Market
Ingredients
Italy Soy Protein Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Soy Protein Isolate Market
Ingredients
Global Organic Personal Care Ingredients Market