
 Fermented Cucumber Market | 2026-2036
Fermented Cucumber Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Cucumber Market Foresight
Subscription-based replenishment programs for fermented cucumber assortments is recalibrating how households stock pantry staples. Mt. Olive Pickle Company leverages its direct-to-pantry subscription model to secure recurring revenue streams. The Kraft Heinz Company sustains broad retail shelf presence through multi-brand portfolio density. Conagra Brands anchors food service supply contracts with institutional buyers seeking consistent brine specifications.
Fermented cucumbers are cucumbers preserved through lacto-fermentation in brine solutions typically containing 5-8% salt concentration, producing lactic acid as the primary preservative and characteristic tangy flavor profile. This preservation method extends shelf life without artificial additives while delivering probiotic content valued in functional food applications. Dill Pickles occupy the largest volume position due to mainstream palate familiarity across North American and European households. Bread and Butter Pickles represent the fastest-growing product type as sweet-savory flavor profiles gain traction among younger retail consumers. Glass Jars command premium shelf positioning and margin pools, though Plastic Containers compete aggressively on logistics cost and breakage reduction.
FDA food safety standards govern acidified food regulations for fermented cucumber imports into the United States, while EFSA oversees additive-free labeling claims across European markets. BIS certification requirements in India create compliance thresholds for imported fermented products entering organized retail channels. Stakeholders must monitor evolving salt-content thresholds and probiotic labeling permissions as these regulatory variables will determine which production configurations sustain market access.
Market Dynamics
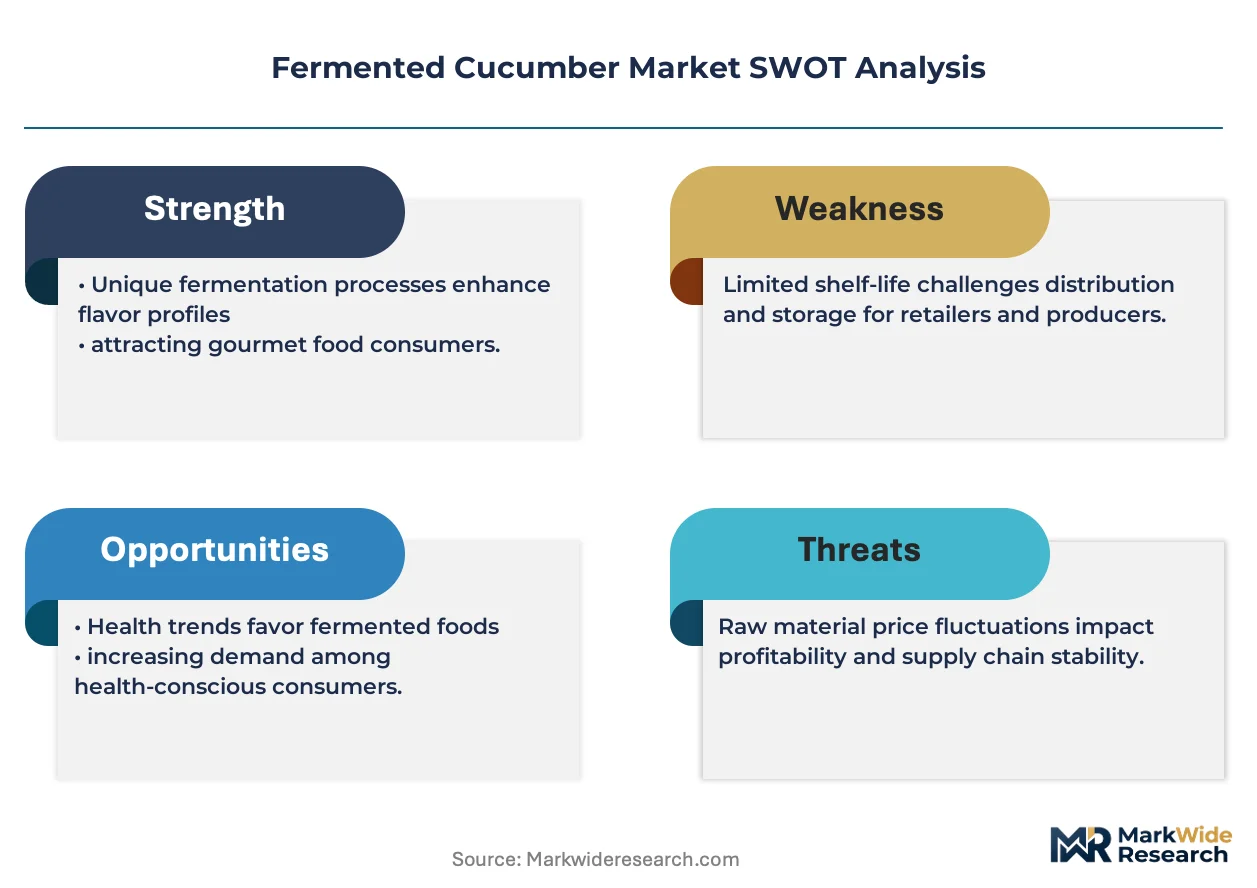
Salt-reduction mandates from FDA and EFSA are forcing reformulation of traditional brine protocols, compressing established fermentation timelines while preserving probiotic viability claims that anchor premium positioning.
Growth Catalysts
- EFSA additive-free labeling frameworks:Clean-label fermentation protocols gain shelf space advantage in German and French retail channels, rewarding producers who eliminate synthetic preservatives.
- Food service menu expansion:Quick-service chains and fast-casual operators are embedding fermented cucumbers across sandwich, bowl, and appetizer categories, driving institutional volume commitments.
- Lacto-fermentation biotechnology:Controlled starter culture applications are shortening production cycles while standardizing lactic acid profiles for mass-market consistency.
Market Restraints
- Sea salt price volatility:Input cost swings for Mediterranean and Himalayan sourcing regions compress margin pools for mid-tier producers operating on thin brine economics.
- Glass jar supply concentration:Premium packaging substrate depends on concentrated European and Chinese manufacturing clusters, exposing logistics fragility.
- Refrigerated distribution infrastructure gaps:Cold-chain limitations in emerging markets constrain probiotic-labeled product reach, privileging shelf-stable vinegar alternatives.
Strategic Opportunities
- India organized retail penetration:BIS certification creates compliance moats for early entrants capturing modern trade expansion in Mumbai, Delhi, and Bangalore corridors.
- Functional food convergence:Gut-health positioning intersects with sports nutrition and senior dietary segments, opening pharmacy and wellness channel placement.
- Direct-to-pantry subscription models:Recurring revenue mechanics bypass retail slotting fees while capturing household pantry-stocking automation.
Industry Challenges
- Microbiome certification timelines:Probiotic colony-forming unit validation protocols extend product development cycles, delaying market entry for reformulated lines.
- Legacy fermentation workforce scarcity:Traditional brine master expertise concentrates in Eastern European and Korean production clusters, limiting geographic replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Cucumber Market |
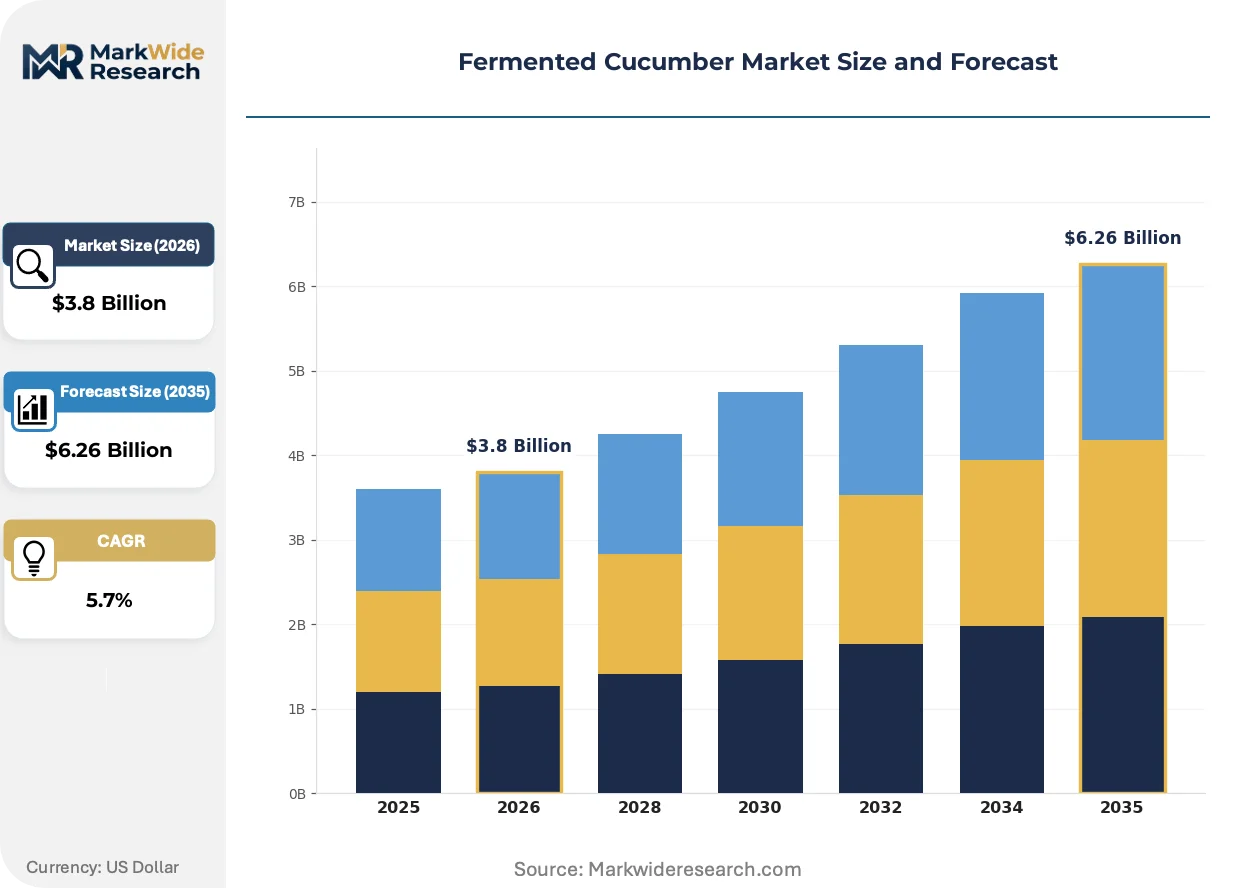
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dill Pickles, Bread and Butter Pickles, Kosher Pickles, Gherkins End User: Retail Consumers, Food Service, Food Manufacturers, Culinary Professionals Packaging Type: Glass Jars, Plastic Containers, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Mt. Olive Pickle Company, The Kraft Heinz Company, Conagra Brands, B&G Foods, Pinnacle Foods, Bay View Foods, McClure's Pickles, Del Monte Foods, Hengstenberg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Cucumber Market Shifts & Advancements
Clean-label fermentation is compressing synthetic additive reliance while expanding probiotic functionality claims into adjacent food categories. Three developments are restructuring competitive positioning.
Controlled atmosphere fermentation technology is expanding into industrial-scale cucumber processing, enabling precise temperature and humidity management that accelerates lactic acid production without compromising texture integrity. Mid-cap producers in Poland and Romania are retrofitting tank infrastructure to capture this capability. The technology is expanding into private-label supply contracts previously dominated by heritage brands with uncontrolled ambient fermentation methods.
REACH chemical safety evaluations in Europe are tightening scrutiny of brine additives and surface sanitizers used in fermentation facilities, compelling producers to document substance migration limits. German manufacturers face the most immediate compliance burden given their Central European supply hub status. EFSA guidance on novel fermentation substrates is prompting R&D redirection toward heritage cucumber varietals with natural sugar profiles that reduce supplemental sweetener dependency.
Household replenishment automation is displacing traditional supermarket pickup patterns for fermented cucumber assortments. Younger retail consumers in North American and Western European urban centers favor algorithmic pantry management over discretionary shelf browsing. Subscription-based models concentrate demand forecasting accuracy with direct-to-consumer operators, compressing working capital cycles for participants while stranding conventional retail-dependent competitors.
Fermented Cucumber Market Segmentation
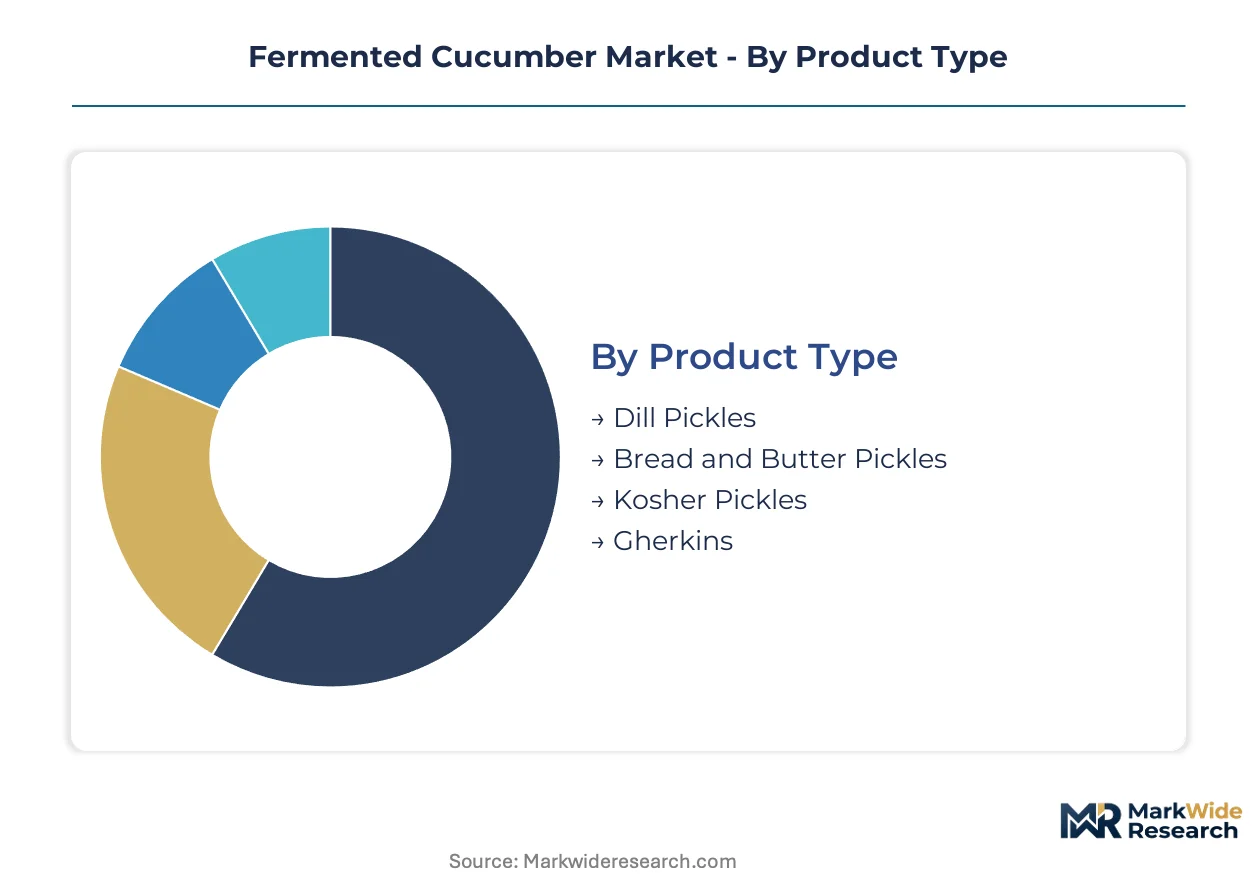
Segmentation in fermented cucumbers reveals how preservation protocols, packaging economics, and channel access fragment purchasing decisions across distinct buyer archetypes. Each dimension carries regulatory and logistics implications that reshape supplier priorities.
Product Type:
Palate familiarity and fermentation duration drive household pantry selection, with heritage recipes commanding loyalty while sweet-savory hybrids capture experimental buyers.
- Dill Pickles:Traditional lacto-fermentation with dill weed and garlic produces the tangy, aromatic profile anchoring North American and Central European consumption. Volume concentrates in Germany and the United States, where Hengstenberg and regional deli cultures sustain repeat purchase cycles. Salt-reduction mandates from EFSA and FDA are compressing brine formulations without sacrificing the characteristic bite that defines this segment.
- Bread and Butter Pickles:Sugar-augmented brines create the sweet-savory crossover profile expanding fastest among millennial and Gen-Z retail consumers in urban U.S. and Canadian markets. Demand tilts toward sandwich and burger applications in fast-casual food service channels seeking flavor differentiation.
- Kosher Pickles:Garlic-heavy, dill-forward fermentation adhering to Jewish dietary law specifications, with production gravity in Brooklyn and Chicago heritage facilities.
- Gherkins:Smaller-format cucumbers with higher skin-to-flesh ratios, popular in French and British cocktail garnishing and charcuterie board assembly.
Volume sits with Dill Pickles; growth tilts toward Bread and Butter Pickles.
End User:
Procurement specifications diverge sharply between household discretionary purchasing and institutional contracts governed by brine consistency mandates.
- Retail Consumers:Supermarket and subscription-based purchasers prioritizing clean-label claims, probiotic functionality, and pantry-stocking convenience. German households show highest per-capita consumption frequency.
- Food Service:Quick-service chains and fast-casual operators embedding fermented cucumbers across sandwich, bowl, and appetizer categories. This segment demands batch-to-batch brine standardization that only controlled fermentation biotechnology can deliver.
- Food Manufacturers:Industrial buyers sourcing bulk brined cucumbers for relish, sauce, and processed food ingredient applications.
- Culinary Professionals:Restaurant chefs and catering operations seeking heritage varietals and small-batch textures for menu differentiation.
Food Service commands the steepest expansion trajectory as menu placement deepens; Retail Consumers retain volume dominance through replenishment automation.
Packaging Type:
Unit economics and cold-chain requirements fragment container selection between premium positioning and logistics efficiency.
- Glass Jars:Premium shelf positioning with superior oxygen barrier properties preserving probiotic viability across extended retail dating. Margin pools concentrate here, though European and Chinese manufacturing concentration creates supply fragility.
- Plastic Containers:Polypropylene and PET formats competing aggressively on breakage reduction and freight cost optimization for mass-market retail.
- Cans:Shelf-stable thermal processing eliminating refrigeration requirements, dominant in food service bulk procurement and emerging market distribution.
- Pouches:Flexible format gaining traction in single-serve snacking and outdoor recreation channels, constrained by retort compatibility limitations.
Glass Jars anchor margin capture; Plastic Containers are gaining share fastest through retailer private-label expansion.
Distribution Channel:
Channel selection determines whether producers capture recurring revenue through direct relationships or absorb slotting fees and margin compression in consolidated retail.
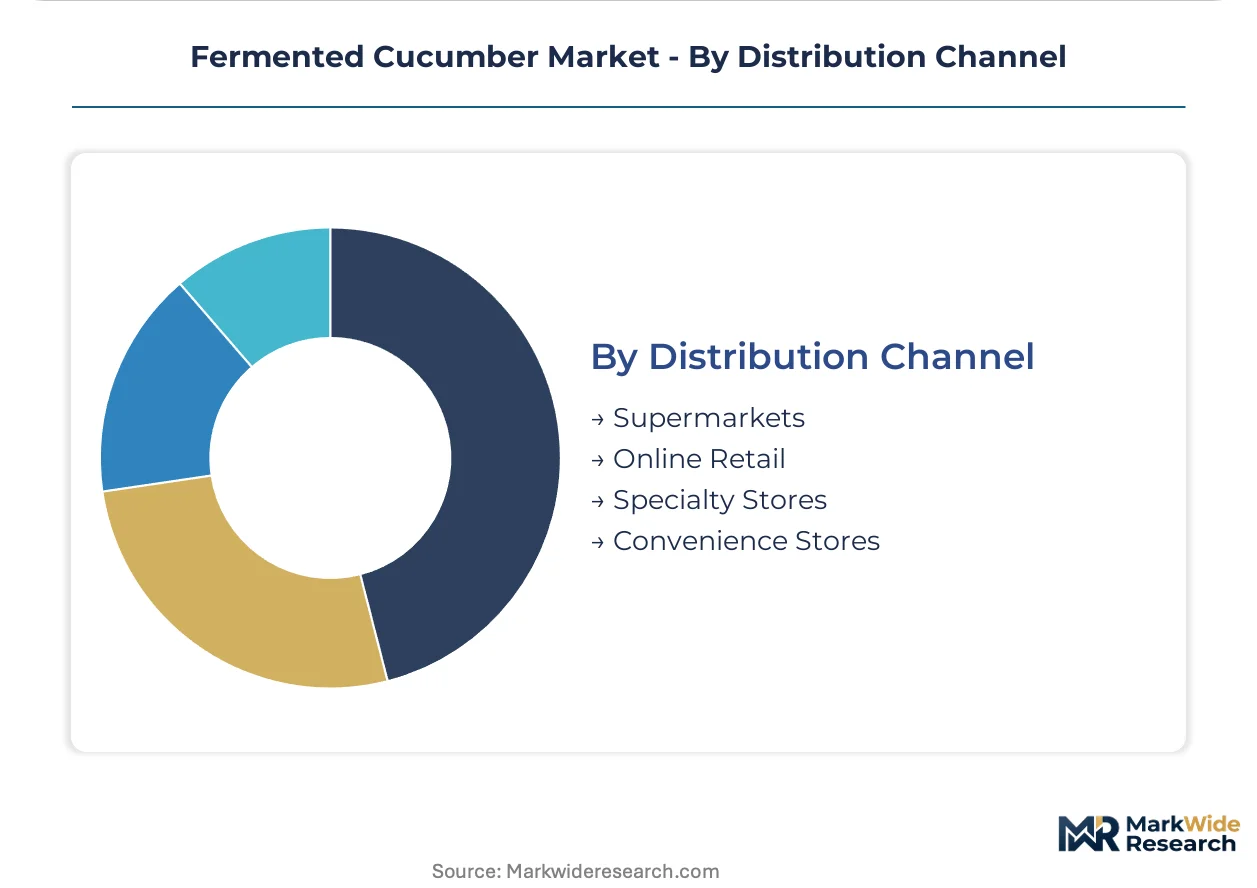
- Supermarkets:Dominant volume channel in Germany, France, and the United States, with shelf placement governed by category captain arrangements and promotional calendar coordination.
- Online Retail:Algorithmic pantry management and subscription replenishment concentrating demand forecasting accuracy with direct-to-consumer operators like Mt. Olive's subscription model.
- Specialty Stores:Gourmet and ethnic grocers curating heritage fermentation brands and imported Eastern European and Korean varieties.
- Convenience Stores:Single-serve and grab-and-go formats for immediate consumption, limited by refrigerated space constraints.
Supermarkets hold volume concentration; Online Retail is climbing the fastest as household replenishment automation displaces discretionary shelf browsing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German production clusters supply Central European demand while American households drive volume consumption through subscription channels. Salt-reduction mandates from EFSA and FDA are forcing brine reformulation across both supply zones. Emerging market cold-chain gaps privilege shelf-stable formats in India and Southeast Asia.
United States
Retail subscription models and quick-service menu embedding sustain volume leadership. FDA acidified food regulations govern import specifications and domestic production protocols. North Carolina and Michigan fermentation facilities anchor industrial-scale supply for national distribution networks.
Germany
Per-capita consumption frequency exceeds all other markets through heritage deli culture persistence. EFSA additive-free labeling frameworks reward clean-label producers with premium shelf positioning. Lower Saxony production clusters around Hengstenberg supply Central European retail and food service channels.
India
Organized retail expansion in Mumbai, Delhi, and Bangalore corridors creates first-mover advantages for compliant entrants. BIS certification requirements erect compliance thresholds for imported products entering modern trade. Cold-chain infrastructure gaps in secondary cities constrain probiotic-labeled product reach.
Poland
Controlled atmosphere fermentation technology adoption is accelerating among mid-cap producers seeking private-label contracts. REACH chemical safety evaluations tighten scrutiny of brine additives and surface sanitizers. Warsaw and Łódź processing clusters are retrofitting tank infrastructure to capture biotechnology efficiencies.
Canada
Health Canada and PMRA oversight aligns with FDA standards for acidified food imports from American suppliers. Bread and Butter Pickle preference skews younger in Toronto and Vancouver urban markets. Quebec heritage fermentation traditions sustain artisanal production alongside industrial-scale imports.
Fermented Cucumber Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct fermentation technology tiers. The market structures around heritage brands with uncontrolled ambient methods, mid-cap specialists retrofitting controlled atmosphere systems, and private-label suppliers competing on logistics cost. Strategic moves concentrate on M&A consolidation of regional fermentation facilities and backward integration into cucumber cultivation to secure varietal consistency.
Within the heritage brand tier, Hengstenberg exemplifies Central European production gravity through multi-generational brine expertise. Mt. Olive Pickle Company and The Kraft Heinz Company occupy positions across the North American retail spectrum, with the former representing direct-to-consumer subscription innovation and the latter exemplifying multi-brand portfolio density for shelf presence. Conagra Brands anchors food service supply relationships through institutional contract structures.
| Leading Market Players |
|---|
| Mt. Olive Pickle Company |
| The Kraft Heinz Company |
| Conagra Brands |
| B&G Foods |
| Pinnacle Foods |
| Bay View Foods |
| McClure's Pickles |
| Del Monte Foods |
| Hengstenberg |
| Others |
Supply & Pricing Matrix
Mediterranean sea salt price indices cascade through fermentation facility cost structures, compressing mid-tier producer margins while concentrating pricing power with heritage brands commanding Central European retail shelf space. Salt-reduction mandates from EFSA and FDA amplify this dynamic by forcing brine reformulation investments that smaller operators cannot absorb.
Pricing Analysis
Margin tightening in standard-tier product lines reflects sea salt cost volatility and synthetic additive elimination investments demanded by clean-label protocols. Three-tier pricing structure across premium, standard, and economy levels separates glass-jar probiotic SKUs commanding shelf-space premiums from plastic-container mass-market formats and canned shelf-stable alternatives. Food service buyers exhibit lowest price sensitivity due to batch-to-batch consistency requirements, while retail private-label purchasers drive hardest cost negotiations.
Supply Chain Analysis
Direct-to-pantry subscription channels handle recurring household demand while food service distribution feeds from institutional procurement hubs in Germany, Poland, and the United States. Raw material flows draw from Mediterranean and Himalayan salt sourcing regions, Lower Saxony cucumber cultivation clusters, and European glass manufacturing concentrations. Single-source vulnerability in jar substrate supply exposes margin pools to logistics disruption. Distribution runs through refrigerated networks for probiotic-labeled SKUs and ambient channels for thermally processed alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass jar manufacturing capacity constraints in European and Chinese production clusters prop pricing premiums for probiotic-positioned SKUs, sustaining supply-constrained market dynamics.
For Market Incumbents: Anchor Central European supply hub status through controlled atmosphere fermentation retrofit investments in Poland and Romania. Defend against private-label encroachment by securing backward integration into heritage cucumber varietal cultivation. Certification moats around EFSA additive-free labeling and FDA acidified food compliance represent defensible margin preservation levers. For New Entrants and Emerging Players: Algorithmic pantry management adopters in North American urban corridors represent the most penetrable buyer archetype for subscription-native positioning. White-space concentration sits with functional food convergence into pharmacy and wellness channels. Direct-to-pantry automation bypasses retail slotting fee barriers that strand conventional entrants. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Polish and Romanian fermentation facilities with retrofit-capable tank infrastructure. Long-term viability hinges on controlled biotechnology adoption and clean-label certification positioning. Salt-reduction mandate compliance timelines serve as the critical inflection signal for production configuration obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Atmosphere Fermentation Retrofit | Polish and Romanian mid-caps capture private-label contracts from heritage brands. |
| Backward Integration into Cucumber Cultivation | Heritage varietal control secures consistent sugar profiles for reduced-sweetener brines. |
| Direct-to-Pantry Subscription Launch | Mt. Olive's model demonstrates recurring revenue mechanics bypassing retail slotting fees. |
| EFSA Additive-Free Certification Investment | German retail channels reward clean-label protocols with premium shelf positioning. |
| Functional Food Channel Expansion | Gut-health positioning opens pharmacy and sports nutrition placement adjacent to probiotics. |
Research Methodology
Trade publications, customs records, and fermentation industry association reports formed the secondary backbone, cross-referenced with primary interviews across brine masters at heritage facilities, food service procurement directors, retail category buyers, and regulatory affairs specialists at EFSA and FDA. Bottom-up volume triangulation across product type, packaging format, and distribution channel segments converged with top-down value estimates derived from production facility capacity assessments.
Historical trendline analysis established baseline growth patterns across dill pickle, bread and butter, and kosher segments, with projection modeling incorporating packaging substrate cost trajectories, salt-reduction compliance timelines, and subscription channel penetration curves. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory implementation schedules.
Revisions become necessary when EFSA probiotic labeling guidance shifts, sea salt supply disruptions materialize, or cold-chain infrastructure investments in India accelerate faster than baseline assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Chile Fruits and Vegetables Market