
 Edible Peanut Oil and Soybean Oil Market | 2026-2036
Edible Peanut Oil and Soybean Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Peanut Oil and Soybean Oil Market Insights
The gap between premium cold-pressed peanut oil and commodity solvent-extracted soybean oil is shifting from a price spread into a supply chain divergence. Wilmar International Limited leverages its crushing and refining footprint across Asia to sustain volume leadership in refined soybean oil. Cargill, Incorporated anchors its position through backward integration into oilseed origination and crush capacity in North and South American hubs. Bunge Limited differentiates by controlling export logistics and destination refining assets that link Brazilian soybean supply to Asian food manufacturers.
Edible peanut oil and soybean oil comprise triglyceride-based vegetable fats extracted from Arachis hypogaea and Glycine max seeds, respectively, with peanut oil typically containing 40-50% monounsaturated oleic acid and soybean oil delivering 50-60% polyunsaturated linoleic acid for frying, baking, and salad dressing formulations. Refined peanut oil leads foodservice demand due to its high smoke point and allergen-stripped profile suitable for commercial kitchens. The household segment shows fastest growth in pouches and smaller bottles through online channels, while bulk packaging still captures margin pools in wholesale supply to bakery and industrial food processors.
China's SAMR enforces GB standards for solvent residue limits and aflatoxin B1 caps in peanut oil, while India's FSSAI mandates labeling for refined versus unrefined categories and fortification disclosures. These frameworks shape import acceptance criteria and domestic blender compliance costs. Stakeholders must monitor how biofuel mandates in major soybean-producing jurisdictions redirect crush capacity away from food-grade oil output.
Market Dynamics
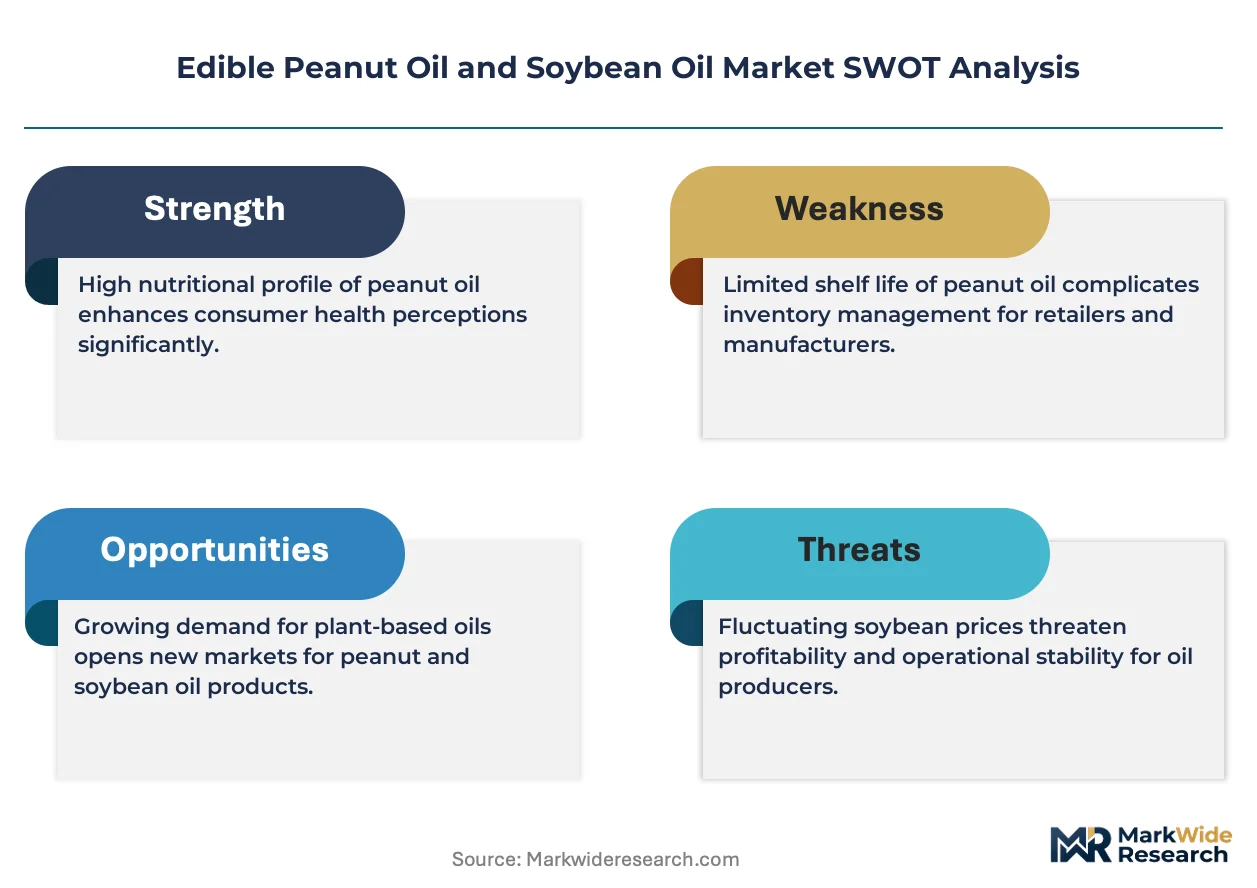
Food safety tightening in China and India is compressing solvent-extracted supply while cold-pressed capacity scales to meet allergen-stripped foodservice demand. This regulatory-cost divergence is restructuring crush economics across Asian refining networks.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory vitamin A and D fortification in refined edible oils is pulling soybean oil into institutional feeding programs and mid-tier retail.
- High-heat frying adoption:Southeast Asian quick-service chains are specifying refined peanut oil for its 450°F smoke point and extended fry-life in wok stations.
- Urban household premiumization:Indian metro consumers are displacing mustard oil with odor-neutral soybean and peanut oils for multicuisine home cooking.
Market Restraints
- Groundnut input volatility:Indian monsoon irregularity and West African supply disruptions concentrate peanut oil feedstock risk in three origin belts.
- GB standard compliance costs:China's SAMR aflatoxin B1 caps and solvent residue limits require laboratory upgrades that eliminate small-scale crushers.
- Palm oil price undercutting:Malaysian and Indonesian palm oil maintains a persistent cost advantage in mass-market frying applications.
Strategic Opportunities
- India tier-two urbanization:Cities such as Indore, Lucknow, and Coimbatore show underpenetrated demand for branded pouch formats in modern trade.
- Biorefinery co-product valorization:Soybean meal and peanut cake protein isolates are expanding into plant-based meat formulations.
- E-commerce direct-to-household:Quick-commerce platforms are building cold-pressed oil private labels with same-day delivery in Indian metros.
Industry Challenges
- Refinery capex intensity:Continuous deodorization and winterization units require capital commitments that strain mid-scale processors.
- Allergen segregation protocols:Foodservice distributors must maintain dedicated storage and transport for peanut oil to prevent cross-contamination liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Peanut Oil and Soybean Oil Market |
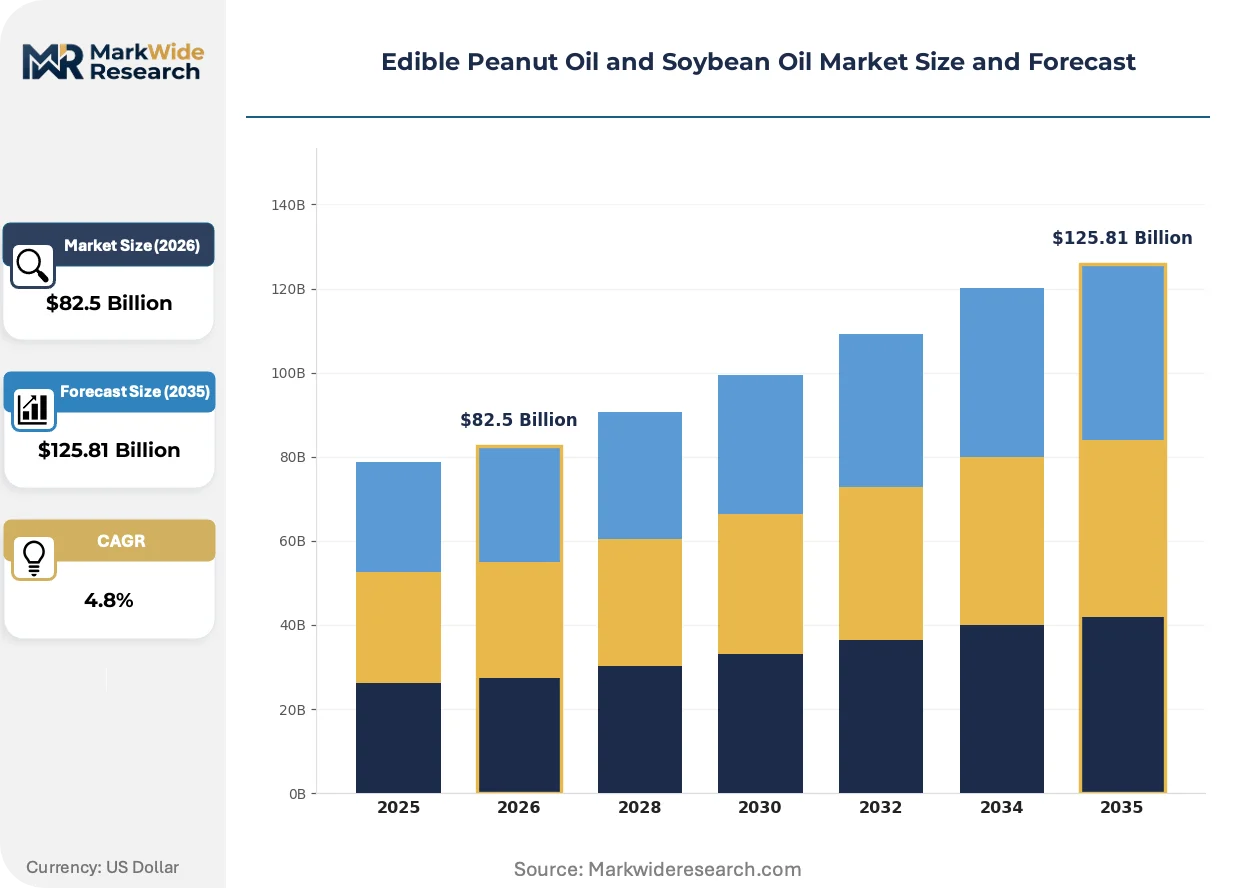
| Market Size in 2026 | $82.5 Billion |
| Market Size in 2035 | $125.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Peanut Oil, Unrefined Peanut Oil, Refined Soybean Oil, Unrefined Soybean Oil End User: Household, Food Industry, Foodservice, Bakery Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bottles, Cans, Pouches, Bulk |
| Companies Covered | Wilmar International Limited, Archer Daniels Midland Company, Cargill, Incorporated, Bunge Limited, AAK AB, Shandong Luhua Group Co., Ltd, COFCO Corporation, Olam International, Liberty Oil Mills Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Peanut Oil and Soybean Oil Market Trends and Innovations
Processing technology and distribution infrastructure are converging to separate commodity solvent-extracted supply from premium cold-pressed positioning. Three developments are compressing legacy economics.
Supercritical CO2 extraction is expanding into mid-scale peanut oil production, stripping allergens without hexane while preserving tocopherol content. Indian and Chinese equipment suppliers are scaling 50-tonne-per-day units for regional processors. This technology is expanding into foodservice contract manufacturing where clean-label claims command shelf-space premiums.
China's SAMR is tightening GB 2716-2018 solvent residue maximums from 50 mg/kg to 10 mg/kg for "pressed" oil labeling claims. Refiners must reconfigure extraction lines or surrender premium positioning. Indonesian and Malaysian exporters to China are accelerating third-party testing to maintain import clearance velocity.
Indian quick-commerce platforms are unbundling bulk household oil purchasing into weekly 1-liter pouch subscriptions. Blinkit and Zepto are building captive cold-pressed labels with 30-minute delivery guarantees. This model concentrates in Bangalore, Mumbai, and Delhi NCR where dual-income households trade storage space for convenience.
Edible Peanut Oil and Soybean Oil Market Segmentation
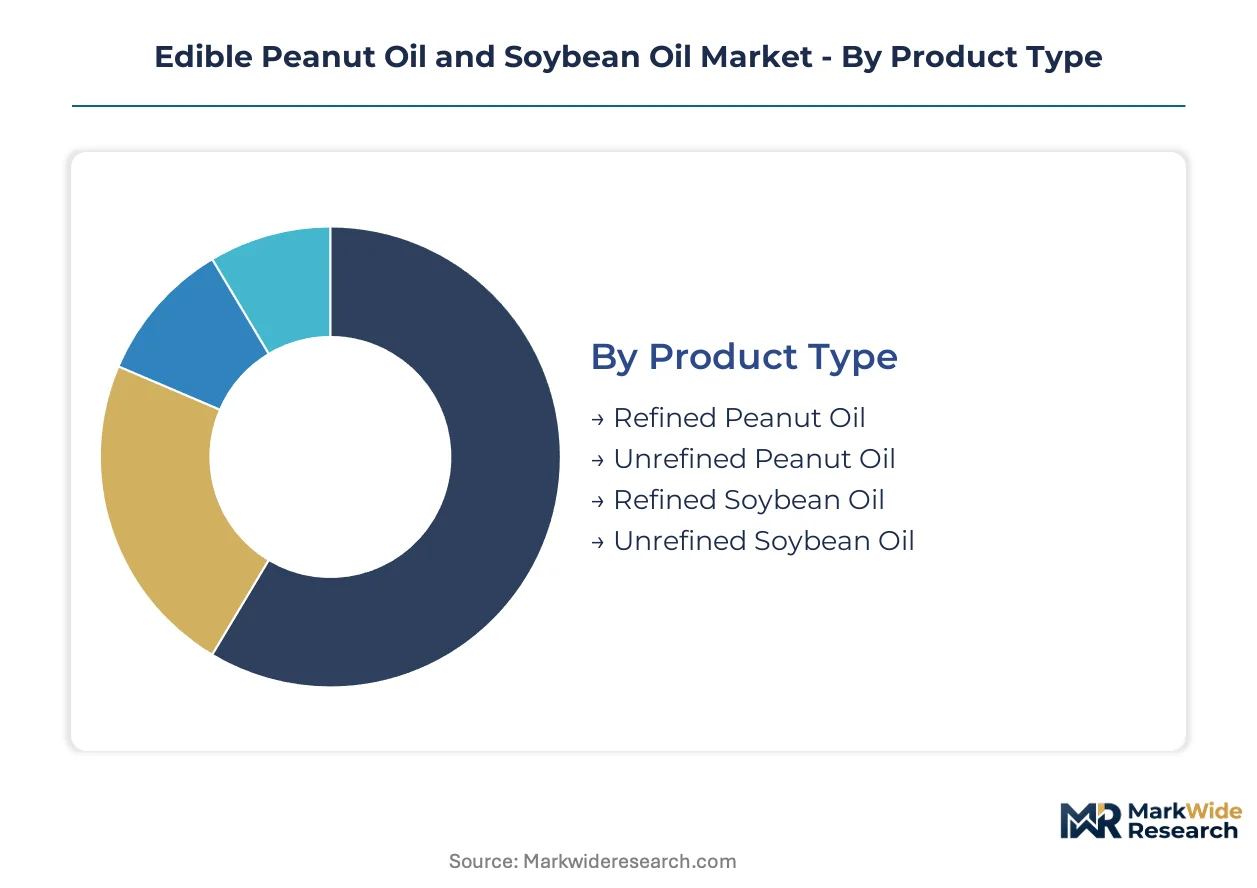
Segmentation in the edible peanut oil and soybean oil market reveals how processing grade, end-use application, and channel economics partition margin pools. Buyers upgrade from unrefined to refined grades as food safety standards tighten, while packaging format shifts track urban household convenience demands against industrial volume procurement.
Product Type:
Upgrade cycles from unrefined to refined grades accelerate where SAMR and FSSAI enforcement raises the cost of solvent residue compliance, pushing food manufacturers toward certified refining networks.
- Refined Peanut Oil:Solvent-extracted or physically refined to achieve sub-10 mg/kg solvent residues and stripped allergen proteins. Southeast Asian quick-service chains specify this grade for 450°F smoke point performance in wok frying stations.
- Unrefined Peanut Oil:Cold-pressed or expeller-pressed retaining tocopherols and characteristic aroma. Premium positioning in Indian metro households through quick-commerce private labels with same-day delivery guarantees.
- Refined Soybean Oil:Degummed, neutralized, and deodorized to deliver 50-60% linoleic acid content with extended fry-life. India's FSSAI fortification mandates pull this grade into institutional feeding programs and mid-tier retail distribution.
- Unrefined Soybean Oil:Crude or degummed-only processing for industrial non-food applications and limited direct consumption. Regional crushers in Brazil and Argentina supply this grade to biodiesel blenders redirecting food-grade crush capacity.
Refined soybean oil sits at the top of the volume ranking, with refined peanut oil climbing the fastest on foodservice specification demand.
End User:
Customer type segmentation tracks divergent procurement logic between price-sensitive institutional buyers and convenience-prioritizing urban households.
- Household:Pouch and bottle formats through modern trade and quick-commerce. Indian metro consumers displace mustard oil with odor-neutral soybean and peanut oils for multicuisine home cooking flexibility.
- Food Industry:Bulk tanker supply to bakery, confectionery, and processed food manufacturers. Continuous deodorization specifications required for extended shelf-life applications in ambient-stable packaged foods.
- Foodservice:High-heat frying applications demanding refined peanut oil's smoke point stability and allergen-stripped safety profile. Dedicated storage and transport protocols prevent cross-contamination liability in distributor networks.
- Bakery:Specialized shortening and laminating fat formulations requiring controlled solid fat content through interesterification or fractionation of base oils.
Food industry procurement dominates tonnage, with household demand expanding most quickly through e-commerce channel buildout.
Distribution Channel:
Channel structure reflects the unbundling of bulk procurement into smaller, more frequent replenishment cycles as urban storage constraints reshape buying behavior.
- Online:Quick-commerce platforms with 30-minute delivery guarantees. Blinkit and Zepto build captive cold-pressed labels in Bangalore, Mumbai, and Delhi NCR where dual-income households trade pantry space for convenience.
- Supermarkets:Branded pouch and bottle formats with FSSAI fortification labeling visibility. Modern trade penetration expanding in Indian tier-two cities such as Indore, Lucknow, and Coimbatore.
- Specialty Stores:Cold-pressed and organic positioning with traceability claims. Supercritical CO2 extraction equipment suppliers target this channel for clean-label premium capture.
- Wholesale:Bulk tanker and drum supply to industrial processors and foodservice distributors. Margin compression from palm oil price undercutting in mass-market frying applications.
Wholesale retains the largest volume share, with online channels gaining share fastest on quick-commerce infrastructure investment.
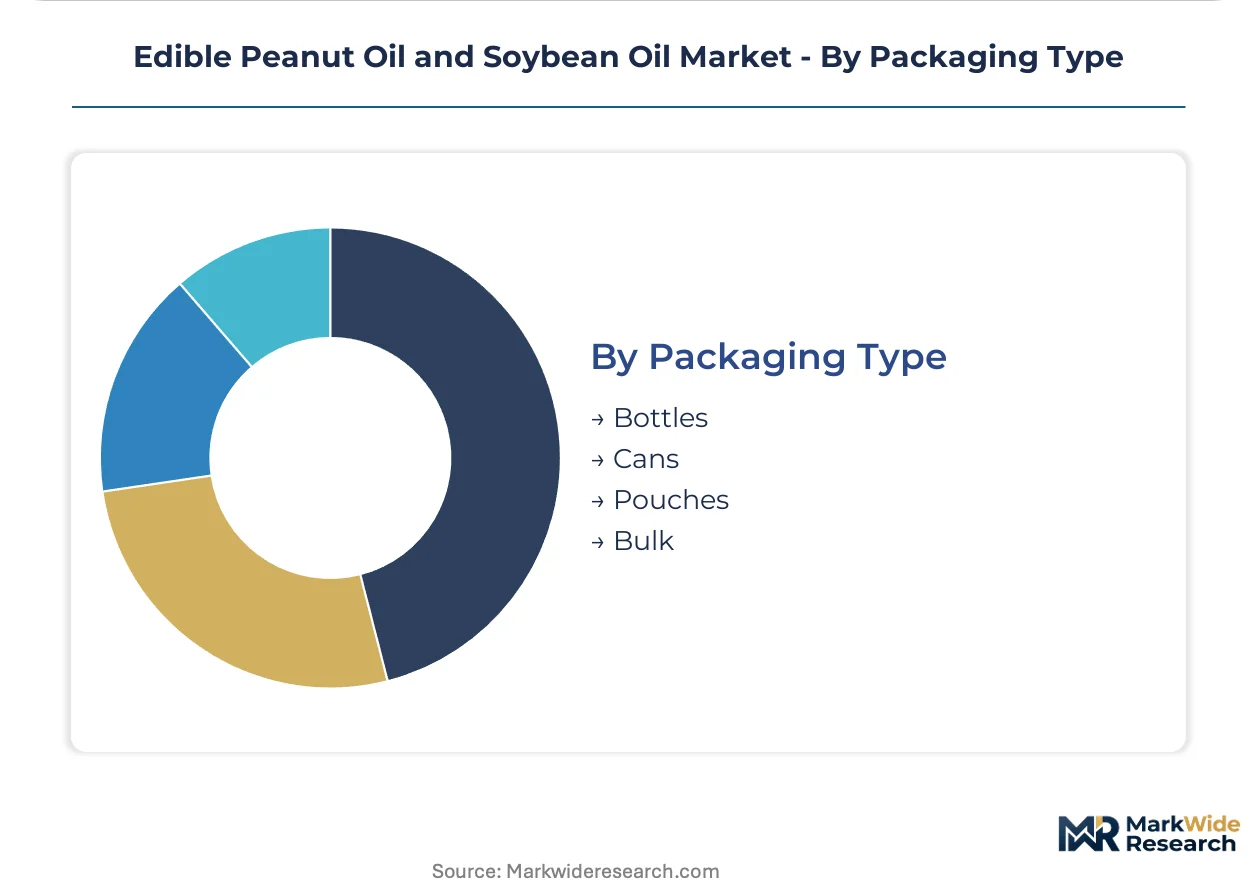
Packaging Type:
Packaging economics balance shelf-space efficiency against consumer convenience and industrial handling requirements.
- Bottles:Standard 1-liter and 5-liter PET or glass formats for household retail. India's tier-two urbanization drives branded bottle penetration in modern trade expansion.
- Cans:Metal packaging for export stability and traditional market preferences. Chinese import protocols require third-party testing for aflatoxin B1 compliance in containerized shipments.
- Pouches:Flexible 1-liter formats for quick-commerce weekly subscription models. Material cost advantage over bottles with reduced logistics cube for last-mile delivery density.
- Bulk:Tanker, flexitank, and drum supply to industrial crushers, refiners, and food manufacturers. Continuous deodorization and winterization unit capex requirements strain mid-scale processor participation.
Bulk packaging commands the highest absolute tonnage, with pouches showing the steepest expansion trajectory on quick-commerce format standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's crushing capacity dwarfs India's fragmented refining base, yet Indian urban households now outpace Chinese foodservice operators in per-capita edible oil switching velocity.
China
Urban foodservice chains in Shanghai and Guangzhou specify refined peanut oil for high-heat wok applications. SAMR enforces GB 2716-2018 solvent residue maximums at 10 mg/kg for pressed oil labeling. Shandong Province hosts the densest cluster of supercritical CO2 extraction equipment suppliers scaling 50-tonne-per-day units for regional processors.
India
Metro households in Mumbai and Delhi NCR displace mustard oil with odor-neutral soybean and peanut oils for multicuisine cooking flexibility. FSSAI mandates vitamin A and D fortification labeling for all refined edible oils. Indore, Lucknow, and Coimbatore show underpenetrated demand for branded pouch formats in modern trade expansion.
United States
Food manufacturers anchor procurement of refined soybean oil for extended shelf-life packaged foods. FDA enforces Food Safety Modernization Act traceability requirements for oilseed processing facilities. Iowa and Illinois crush capacity concentrates supply origination for export-oriented refining networks.
Brazil
Biodiesel blenders redirect soy crush capacity away from food-grade oil output toward renewable diesel feedstock. ANVISA aligns import protocols with CODEX aflatoxin standards for peanut oil shipments. Mato Grosso and Paraná soybean belt logistics hubs control export timing to Asian destination refiners.
Indonesia
Palm oil price undercutting persists in mass-market frying applications, compressing peanut oil penetration. National food safety agency enforces maximum aflatoxin B1 limits for imported peanut oil consignments. Java-based refiners upgrade deodorization units to maintain China export clearance velocity under tightening GB standards.
Edible Peanut Oil and Soybean Oil Market Competitive Landscape
Top-tier vendors anchor integrated crush-refine-export networks, while mid-scale processors concentrate in single-origin cold-pressed positioning. The vendor base stratifies across three archetypes: multinational agribusiness conglomerates controlling origination-to-destination logistics, Asian refining specialists leveraging regional oilseed access, and equipment-technology providers enabling clean-label extraction scale-up. Dominant competitive moves include backward integration into oilseed origination and strategic port terminal investments that lock in Asian import clearance priority.
Among Singapore-based integrated agribusiness operators, Wilmar International Limited occupies a position exemplifying volume leadership through crushing and refining footprint concentration across Asia. Cargill, Incorporated and Bunge Limited represent the North American multinational archetype, with Cargill anchoring backward integration into oilseed origination and crush capacity in North and South American hubs, while Bunge exemplifies export logistics control linking Brazilian soybean supply to Asian food manufacturers. These three entities sit within the tier where destination refining assets and origination networks create procurement stickiness with institutional buyers.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Bunge Limited |
| AAK AB |
| Shandong Luhua Group Co., Ltd |
| COFCO Corporation |
| Olam International |
| Liberty Oil Mills Limited |
| Others |
Pricing and Supply Chain Analysis
Supercritical CO2 extraction equipment scaling across Shandong Province and Indian regional hubs is compressing legacy hexane-based processing economics while concentrating premium-grade supply among mid-scale processors with clean-label certification. This technology transition simultaneously raises capital barriers for solvent-extracted commodity supply and creates margin capture opportunities for allergen-stripped foodservice contract manufacturers.
Pricing Analysis
Bundled refining-certification-logistics services command premiums against unbundled commodity spot transactions. Three-tier pricing structure across premium cold-pressed, standard refined, and economy solvent-extracted levels separates FSSAI-fortified retail pouches from bulk industrial tankers. Price differentiation rests on smoke-point certification and aflatoxin B1 testing documentation. Cost compression in economy-grade supply is intensifying because Indonesian palm oil maintains persistent undercutting in mass-market frying. Foodservice quick-service chains show least price sensitivity due to liability-driven specification requirements, while institutional feeding programs exhibit highest sensitivity to fortification mandate compliance costs.
Supply Chain Analysis
Domestic-content mandates in India's FSSAI fortification labeling and China's GB 2716-2018 solvent residue standards are reshaping sourcing toward certified regional crushing networks. Geographic supply concentrates in China, India, and Brazil. Raw material dependencies draw from Argentine soybean belts, West African groundnut origins, and Indian monsoon-dependent peanut harvests. Single-source vulnerability runs through Indonesian palm oil substitution pressure in Southeast Asian foodservice procurement. Distribution runs through wholesale tanker networks to industrial processors, with quick-commerce platforms building parallel last-mile infrastructure for household pouch replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier displacement of mustard oil in Indian metros and co-product valorization of protein isolates into plant-based meat formulations.
For Market Incumbents: To counter quick-commerce private-label encroachment in Bangalore and Delhi NCR, anchor backward integration into Shandong Province supercritical CO2 equipment partnerships and lock exclusive refining capacity under FSSAI fortification certification. Prioritize captive supply of high-oleic peanut varieties to secure smoke-point performance differentiation against commodity soybean oil substitution. For New Entrants and Emerging Players: Enter via tier-two Indian cities such as Indore, Lucknow, and Coimbatore where modern trade penetration remains underdeveloped for branded pouch formats. Target quick-commerce weekly subscription models with 1-liter flexible packaging optimized for 30-minute delivery density. Build go-to-market through Blinkit and Zepto platform partnerships rather than traditional wholesale distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian regional crushers lacking continuous deodorization capex for FSSAI compliance. Long-term viability centers on biorefinery co-product positioning where peanut cake and soybean meal protein isolates feed plant-based meat formulation demand. Watch for inflection in Chinese SAMR enforcement velocity against Indonesian and Malaysian exporters as signal for certified-refining asset scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Shandong equipment suppliers enable mid-scale processors to capture clean-label premiums in foodservice contract manufacturing. |
| Backward Integration into High-Oleic Seed Origination | Crushers securing proprietary peanut varieties lock smoke-point performance specifications against commodity substitution. |
| Quick-Commerce Private Label Partnership | Blinkit and Zepto platform access concentrates household pouch demand in Mumbai and Delhi NCR metro corridors. |
| Biorefinery Co-Product Valorization | Soybean meal and peanut cake protein isolates expand addressable market into plant-based meat formulation supply. |
| FSSAI Fortification Certification Investment | Continuous deodorization and vitamin A/D dosing equipment qualifies refined oils for institutional feeding program procurement. |
Research Methodology
Direct dialogue with crushing plant managers, FSSAI compliance officers at Indian refiners, quick-commerce category buyers, and Southeast Asian foodservice procurement directors grounded qualitative assessment in operational realities. Secondary validation drew from China SAMR GB standard filings, Indian customs edible oil import records, SEC 10-K disclosures of listed agribusiness operators, and CODEX aflatoxin guideline documentation. Bottom-up volume modeling across processing grades and top-down macroeconomic anchoring ensured cross-verified outputs.
Segmented projections across refined versus unrefined grades, household versus foodservice versus food industry end-use, and online versus wholesale channel distribution generated volume and value trajectories across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating urbanization rates, quick-commerce penetration curves, and biofuel mandate diversion impacts on crush capacity allocation. Industry-specific inputs included monsoon variability coefficients for Indian groundnut yields and Chinese import clearance velocity indices.
The model holds under stable regulatory enforcement intensity and intact logistics infrastructure; deviation in SAMR inspection velocity or Indonesian palm oil export tax policy would shift supply-cost curves and crush-margin distributions. Forecasts reflect documented assumptions regarding FSSAI fortification mandate adherence rates and supercritical CO2 equipment deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Soy Protein Market
Ingredients
Revivable Yeast Market
Ingredients
Global Dry Yeast Market
Ingredients
Rose Hips Extract Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Europe Agar Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
All Purpose Flour Market
Ingredients
Glucomannan Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Bean Ingredients Market
Ingredients
Liquid Feed Market
Ingredients
Seaweed Extracts Market