
 Konjac Flour Market | 2026-2036
Konjac Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Konjac Flour Market Outlook
The price-performance gap between pharmaceutical-grade konjac flour and commodity food-grade powder is hardening as extraction purity standards diverge. Hubei Yizhi Konjac Biotechnology anchors its position through captive glucomannan refining operations in China's Hubei province. NOW Foods differentiates via certified organic and non-GMO konjac positioning in North American health channels. FMC Corporation leverages its broader hydrocolloid portfolio to cross-sell konjac into industrial food systems.
Konjac flour consists of dried and milled tuber flesh from Amorphophallus konjac, typically containing 40-60% glucomannan polysaccharide by dry weight, with viscosity grades ranging from 20,000 to 40,000 mPa·s depending on particle mesh and extraction method. Manufacturers deploy wet milling followed by ethanol precipitation to achieve pharmaceutical-grade purity above 90% glucomannan content for capsule and tablet binders. Konjac powder dominates current volume flows through established thickening applications in noodles and surimi, while konjac gels command margin premiums in cosmeceutical facial masks and wound dressing substrates. Food and beverages absorbs the largest absolute tonnage, though nutraceuticals represents the fastest-expanding application as prebiotic fiber claims gain regulatory traction in multiple jurisdictions.
China's SAMR enforces GB standards for konjac food additives, while the FDA maintains GRAS notification requirements for novel glucomannan concentrations in U.S. dietary supplements. The EU's EFSA evaluates health claim substantiation for konjac-derived cholesterol reduction, directly shaping permissible marketing language across member states. Japan's Ministry of Health, Labour and Welfare codifies konjac as a traditional foodstuff with distinct processing standards. Stakeholders must monitor evolving prebiotic classification frameworks in major import markets, as fiber-specific health claims become the primary battleground for product positioning and price realization.
Market Dynamics
The Konjac Flour Market is bifurcating around extraction purity grades, as pharmaceutical-grade glucomannan specifications diverge sharply from commodity food-grade benchmarks, reshaping investment priorities across the value chain.
Growth Catalysts
- Prebiotic fiber regulatory traction:EFSA health claim evaluations for cholesterol reduction are unlocking premium positioning in European nutraceutical channels, expanding addressable patient populations beyond traditional food applications.
- East Asian processing cluster dominance:Japan's shirataki noodle culture sustains captive demand for ultra-high viscosity konjac grades, insulating premium producers from commodity price cycles through long-term supply agreements.
- Soluble fiber supplementation protocols:Clinical adoption of glucomannan in metabolic syndrome management protocols is accelerating prescription-grade sourcing requirements from compounding pharmacies and functional food formulators.
Market Restraints
- Amorphophallus konjac cultivation concentration:Raw tuber supply concentrates in China's mountainous southwestern provinces, exposing processors to monsoon-dependent harvest volatility and regional climate shocks.
- Ethanol precipitation cost structure:Pharmaceutical-grade extraction requires food-grade ethanol volumes that fluctuate with biofuel policy arbitrage, compressing margins for purity-focused producers.
- Hydrocolloid substitution dynamics:Xanthan gum and guar gum maintain cost advantages in industrial thickening applications, limiting konjac penetration in price-sensitive mass-market sauces and dressings.
Strategic Opportunities
- Wound dressing substrate applications:Konjac gel biocompatibility properties are attracting medical device manufacturers seeking alternatives to synthetic hydrogels for chronic wound management.
- Clean-label cosmetic channel expansion:Korean beauty supply chains are integrating konjac-derived facial mask substrates as silicone-free positioning claims gain traction among ingredient-conscious consumers.
- China's dual carbon policy alignment:Konjac cultivation's low water intensity relative to starch crops positions the sector for agricultural carbon credit monetization under MEE sustainability frameworks.
Industry Challenges
- Glucomannan assay standardization gaps:Inconsistent viscosity testing methodologies between GB standards and USP monographs create cross-border shipment rejections and working capital freezes.
- Captive refining equipment lead times:Pharmaceutical-grade precipitation and drying systems face 18-month procurement backlogs from specialized European equipment vendors, delaying purity upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Konjac Flour Market |
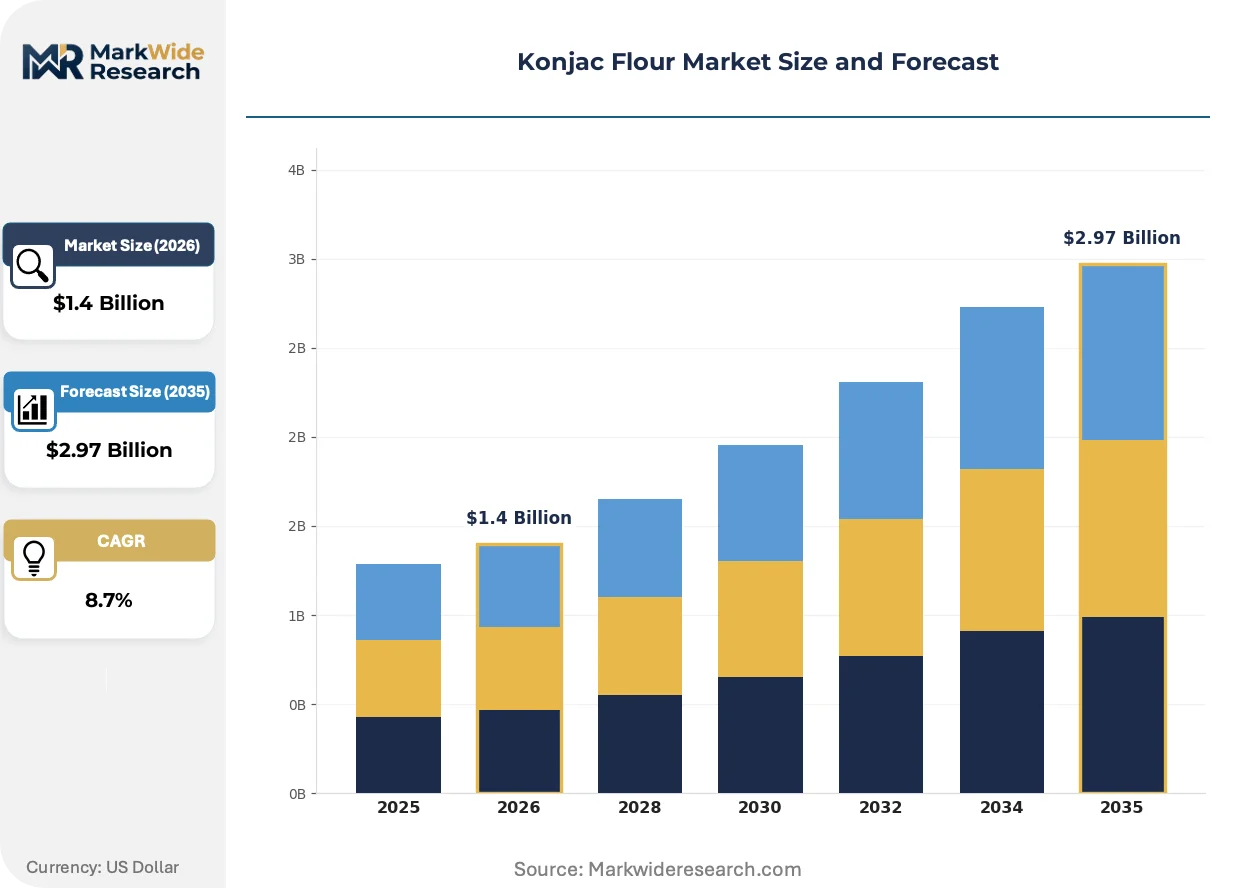
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Konjac Powder, Konjac Noodles, Konjac Chips, Konjac Gels Application: Food & Beverages, Pharmaceuticals, Nutraceuticals, Cosmetics End User: Restaurants, Retailers, Food Manufacturers, Health Stores Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Shanghai Brilliant Gum, NOW Foods, Hubei Yizhi Konjac Biotechnology, Henan Xinchun Food Industry, Shaanxi Jintai Konjac Industrial Development, Baoji Konjac Chemical, FMC Corporation, Won Long Konjac, NAH Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Konjac Flour Market Strategic Shifts
Processing technology advances and regulatory recalibration are compressing the traditional purity-grade hierarchy, enabling mid-tier producers to capture premium positioning through targeted certification investments rather than legacy extraction scale.
Enzymatic extraction protocols using cellulase and pectinase pre-treatment are electrifying yield recovery rates from konjac tuber flesh, enabling processors to achieve 85% plus glucomannan purity without ethanol-intensive precipitation stages. Nutraceutical capsule manufacturers in North American health channels are adopting these enzymatic grades at accelerating volumes, collapsing the traditional three-tier pricing structure that separated pharmaceutical, food, and feed-grade specifications.
EFSA's evolving substantiation requirements for Article 13.1 health claims on cholesterol reduction are forcing reformulation transparency across European functional food portfolios, with glucomannan-specific clinical trial investments now prerequisite for marketing authorization. Manufacturers targeting EU member states are restructuring R&D budgets toward human intervention studies, prioritizing dossier completeness over incremental viscosity improvements in competitive positioning.
Ingredient sourcing decisions in North American clean-label retail channels now prioritize certified organic and non-GMO verification chains over bulk viscosity specifications, compressing traditional specification-based procurement workflows. Natural products distributors are consolidating supplier panels around vertically integrated farm-to-flour traceability systems, with third-party audit documentation displacing certificate-of-analysis dominance in buyer evaluation criteria.
Konjac Flour Market Segmentation
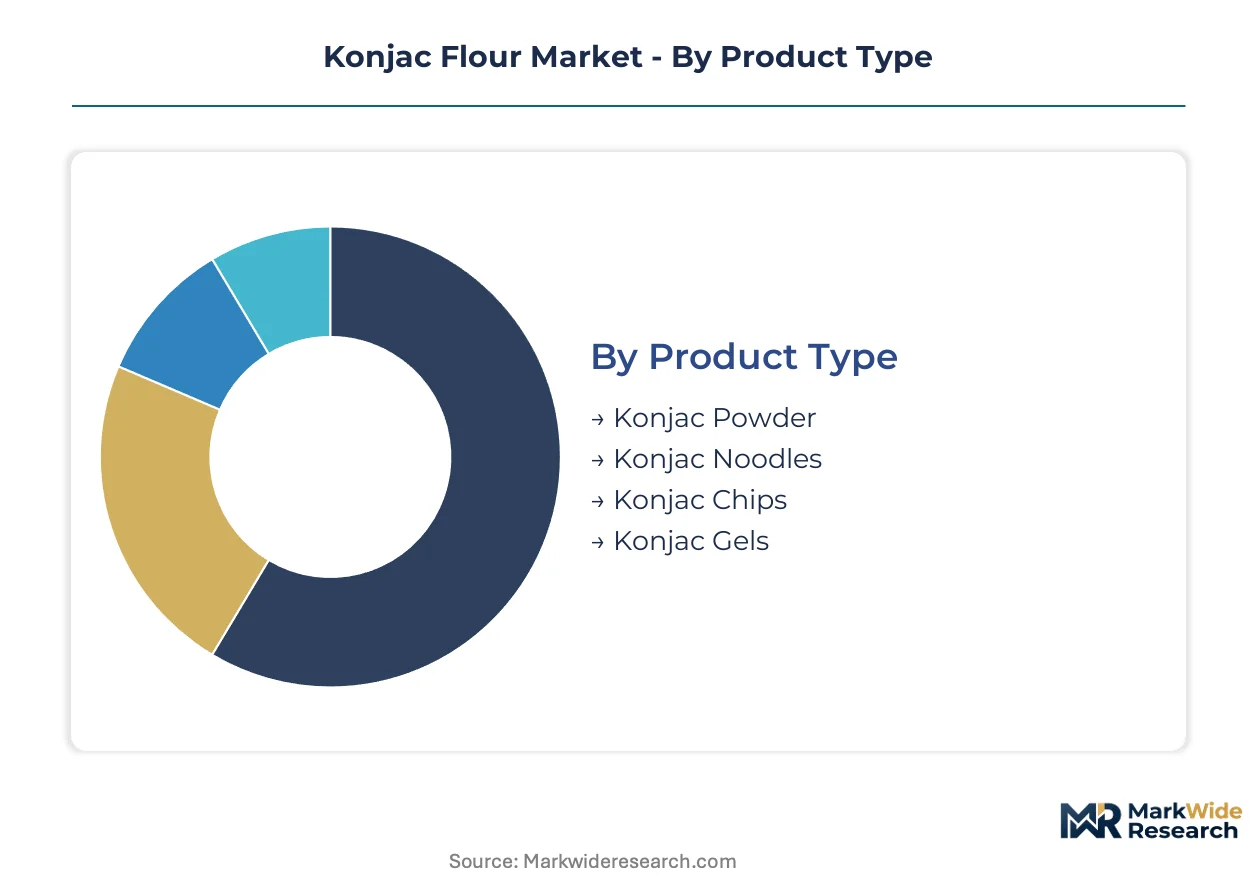
Segmentation in konjac flour reflects divergent purity requirements across pharmaceutical, food, and cosmetic channels. Buyers prioritize viscosity specifications or clean-label certification depending on end-use, fragmenting procurement workflows across the value chain.
Product Type:
Cost tier determines equipment investment and extraction chemistry selection for processors.
- Konjac Powder:Dried and milled tuber flesh containing 40-60% glucomannan polysaccharide, with viscosity grades from 20,000 to 40,000 mPa·s. Food manufacturers in East Asian processing clusters absorb the largest absolute tonnage for noodle and surimi thickening, though ethanol precipitation costs pressure margin structures for purity-focused grades.
- Konjac Gels:Hydrated glucomannan matrices formed through alkali coagulation, achieving biocompatible hydrogel structures. Korean beauty supply chains and medical device manufacturers in Japan are driving demand for silicone-free cosmetic substrates and chronic wound dressing alternatives, capturing margin premiums unavailable in commodity powder markets.
- Konjac Noodles:Alkali-set shirataki formulations with ultra-high water-binding capacity. Japan's traditional food culture sustains captive demand through long-term supply agreements.
- Konjac Chips:Dehydrated tuber slices for reconstitution in food service. Restaurants in Sichuan and Guizhou provinces favor this format for regional hotpot applications.
Konjac powder leads on scale; konjac gels lead on momentum.
Application:
Regulatory claim substantiation requirements reshape formulation transparency and R&D budget allocation.
- Food & Beverages:Established thickening applications in noodles, surimi, and low-calorie formulations dominate current volume flows. China's SAMR enforces GB standards for food additive specifications, while Japan's Ministry of Health, Labour and Welfare maintains distinct traditional foodstuff classifications.
- Nutraceuticals:Prebiotic fiber supplements and metabolic syndrome management protocols are accelerating prescription-grade sourcing. EFSA health claim evaluations for cholesterol reduction are unlocking premium positioning in European channels, forcing manufacturers toward human intervention study investments.
- Pharmaceuticals:Capsule and tablet binders requiring above 90% glucomannan purity through wet milling and ethanol precipitation. USP monograph compliance creates cross-border shipment friction against GB standard methodologies.
- Cosmetics:Facial mask substrates and topical delivery systems leveraging konjac's biocompatibility. Clean-label positioning displaces silicone-based alternatives in ingredient-conscious retail channels.
Food and beverages leads on scale; nutraceuticals leads on momentum.
End User:
Volume concentration and certification requirements fragment procurement authority across the demand base.
- Food Manufacturers:Industrial-scale formulators of noodles, sauces, and meat analogues. Procurement prioritizes bulk viscosity specifications and supply security over organic certification.
- Restaurants:Food service operators in East Asian markets, particularly Japan's shirataki-specialty establishments and China's hotpot chains. Sourcing emphasizes consistent hydration performance and regional taste profiles.
- Health Stores:North American natural products distributors consolidating supplier panels around vertically integrated farm-to-flour traceability. Third-party audit documentation now dominates buyer evaluation criteria.
- Retailers:Supermarket and specialty channel buyers curating clean-label portfolios. Certified organic and non-GMO verification chains command procurement priority over bulk specifications.
Food manufacturers leads on scale; health stores leads on momentum.
Distribution Channel:
Channel selection reflects buyer sophistication and certification documentation requirements.
- Online:Direct-to-consumer platforms and B2B marketplaces for nutraceutical and cosmetic ingredients. North American health channels favor certified organic positioning in e-commerce workflows.
- Specialty Stores:Korean beauty supply chains and Japanese traditional food retailers. Curated assortment demands vertical integration proof and batch-level traceability.
- Supermarkets:Mass-market retail for konjac noodles and powder in East Asian markets. Price sensitivity limits penetration of premium-grade specifications.
- Wholesale:Industrial ingredient distributors serving food manufacturers and pharmaceutical compounders. Volume discounts and long-term contracting dominate procurement terms.
Wholesale leads on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy alignment contrasts with Japan's traditional foodstuff codification, revealing divergent regulatory pathways for konjac cultivation and processing across East Asian markets.
China
Pharmaceutical-grade extraction demand and nutraceutical fiber supplementation are accelerating investments in Hubei province's refining clusters. SAMR enforces GB standards for food additive specifications while MEE sustainability frameworks create agricultural carbon credit opportunities. The Yangtze River Delta processing corridor concentrates wet milling and ethanol precipitation capacity for export-grade glucomannan.
Japan
Shirataki noodle culture sustains captive demand for ultra-high viscosity konjac grades through long-term supply agreements. The Ministry of Health, Labour and Welfare maintains distinct traditional foodstuff classifications separate from novel food regulations. Kansai region specialty manufacturers dominate premium-grade alkali-set gel production for domestic and regional export channels.
United States
Clean-label retail channels prioritize certified organic and non-GMO verification chains over bulk viscosity specifications. FDA GRAS notification requirements govern novel glucomannan concentrations in dietary supplements. California-based natural products distributors are consolidating supplier panels around vertically integrated farm-to-flour traceability systems.
Germany
EFSA health claim evaluations for cholesterol reduction are unlocking premium positioning in European nutraceutical channels. REACH compliance and evolving clean-label regulations tighten purity benchmarks for glucomannan extraction. Bavaria's functional food formulators are restructuring R&D budgets toward human intervention studies for dossier completeness.
South Korea
Korean beauty supply chains integrate konjac-derived facial mask substrates as silicone-free positioning claims gain traction. MFDS cosmetic ingredient regulations shape biocompatibility testing requirements for topical delivery systems. Seoul Capital Area cosmetic manufacturers are driving demand for hydrogel-grade konjac matrices.
Konjac Flour Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade extraction capacity, while mid-scale processors compete on enzymatic yield recovery and certification speed. The vendor base stratifies around three archetypes: captive refining operators with upstream tuber control, certified organic specialists serving North American health channels, and diversified hydrocolloid portfolios cross-selling into industrial food systems. Dominant competitive moves include backward integration into cultivation zones and strategic partnerships with medical device manufacturers for wound dressing substrates.
Among China-based biotechnology operators, Hubei Yizhi Konjac Biotechnology Co., Ltd. exemplifies the captive refining archetype, while Henan Xinchun Food Industry Co., Ltd. occupies a position within mid-tier enzymatic extraction specialists. NOW Foods represents the certified organic positioning strategy in North American health channels, and FMC Corporation anchors the diversified hydrocolloid portfolio approach.
| Leading Market Players |
|---|
| Shanghai Brilliant Gum |
| NOW Foods |
| Hubei Yizhi Konjac Biotechnology |
| Henan Xinchun Food Industry |
| Shaanxi Jintai Konjac Industrial Development |
| Baoji Konjac Chemical |
| FMC Corporation |
| Won Long Konjac |
| NAH Foods |
| Others |
Value Chain & Pricing Dynamics
Certified organic procurement mandates from North American health stores are forcing upstream processors to restructure extraction workflows around third-party audit documentation, compressing margin structures for non-certified grades while elevating price floors for verified supply chains.
Pricing Analysis
Capacity additions in China's Hubei province are reshaping price floors for pharmaceutical-grade konjac flour. Three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by glucomannan purity percentage and organic certification status. Cost compression in food-grade powder segments is intensifying because enzymatic extraction protocols are collapsing traditional grade boundaries. Industrial food manufacturers exhibit highest price sensitivity, while medical device manufacturers for wound dressing substrates show least.
Supply Chain Analysis
Domestic-content requirements under China's dual carbon policy are reshaping sourcing patterns for export-bound processors. Raw tuber supply concentrates in China's Sichuan, Yunnan, and Guizhou provinces, with refining capacity anchored in Hubei. Production draws from Amorphophallus konjac cultivation, food-grade ethanol volumes, and specialized European precipitation equipment. Single-source vulnerability concentrates in monsoon-dependent harvest cycles. Distribution runs through Yangtze River Delta export corridors and Japanese Kansai region specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EFSA cholesterol reduction claim evaluations driving premium nutraceutical demand across European channels.
For Market Incumbents: Deploy backward integration into Sichuan and Yunnan cultivation zones to secure captive tuber supply against climate volatility. Invest in enzymatic extraction R&D to defend margin position against pharmaceutical-grade ethanol cost swings. NOW Foods' certified organic positioning and Hubei Yizhi's captive refining operations illustrate divergent defensive levers against hydrocolloid substitution threats from xanthan and guar gum. For New Entrants and Emerging Players: The premium-to-economy price gap in North American health channels offers white-space entry through certified organic konjac powder targeting natural products distributors. Korean beauty supply chains for silicone-free facial mask substrates present the most penetrable application segment. Pursue farm-to-flour traceability partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale enzymatic extraction specialists achieving 85% plus glucomannan purity without ethanol-intensive stages. Long-term viability centers on regulatory claim substantiation capabilities across EFSA, FDA, and SAMR jurisdictions. Target processors with in-house clinical trial infrastructure. Watch for EFSA Article 13.1 health claim authorization timelines as the inflection signal for European nutraceutical channel premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive tuber supply from Sichuan and Yunnan provinces insulates processors from monsoon harvest volatility. |
| Enzymatic Extraction Scale-Up | Cellulase and pectinase protocols collapse traditional three-tier pricing by achieving pharmaceutical-grade purity without ethanol precipitation. |
| EFSA Health Claim Dossier Investment | Human intervention studies for cholesterol reduction unlock premium positioning in European nutraceutical channels. |
| Medical Device Partnership | Wound dressing substrate supply agreements with Japanese and Korean manufacturers capture margin premiums unavailable in commodity powder markets. |
| Carbon Credit Monetization | MEE sustainability framework alignment positions konjac cultivation for agricultural carbon credit revenue under China's dual carbon policy. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with konjac flour processors, nutraceutical formulators, cosmetic R&D directors, and regulatory affairs specialists at SAMR and EFSA with secondary validation through FDA GRAS notifications, EFSA health claim submissions, Chinese customs trade data, and USP monograph revisions. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Historical reference periods anchored the projection horizon to established growth trajectories in glucomannan extraction capacity and nutraceutical fiber adoption. The analytical framework modeled product type, application, end user, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate synthesis incorporating enzymatic yield recovery trends and EFSA claim authorization timelines as konjac-specific forecast inputs.
Caveats apply where EFSA health claim rejections, FDA GRAS notification delays, or monsoon-driven harvest failures could materially shift the outlook. Forecasts reflect assumptions around regulatory claim substantiation investment levels and enzymatic extraction technology diffusion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vegetable Powder Market
Ingredients
Dill Seed Oil Market
Ingredients
Synephrine Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Oak Extract Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
Homecare Ingredients Market
Ingredients
Global Dry Yeast Market
Ingredients
Codonopsis Extract Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Hexane-Free Protein Market
Ingredients
North America Soy Protein Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Pea Flour Market