
 Fat Powders Market | 2026-2036
Fat Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Powders Market Foresight
Premium-grade spray-dried fat powders with microencapsulation specs is redrawing competitive boundaries across the industry. Kerry Group plc leverages its R&D intensity in flavor-fat delivery systems to command technical partnerships with multinational beverage brands. Cargill anchors its position through backward integration into palm and coconut oil sourcing, securing cost visibility from plantation to powder. MEGGLE Food Ingredients specializes in dairy-fat powder formulations, occupying a defensible niche in European bakery applications.
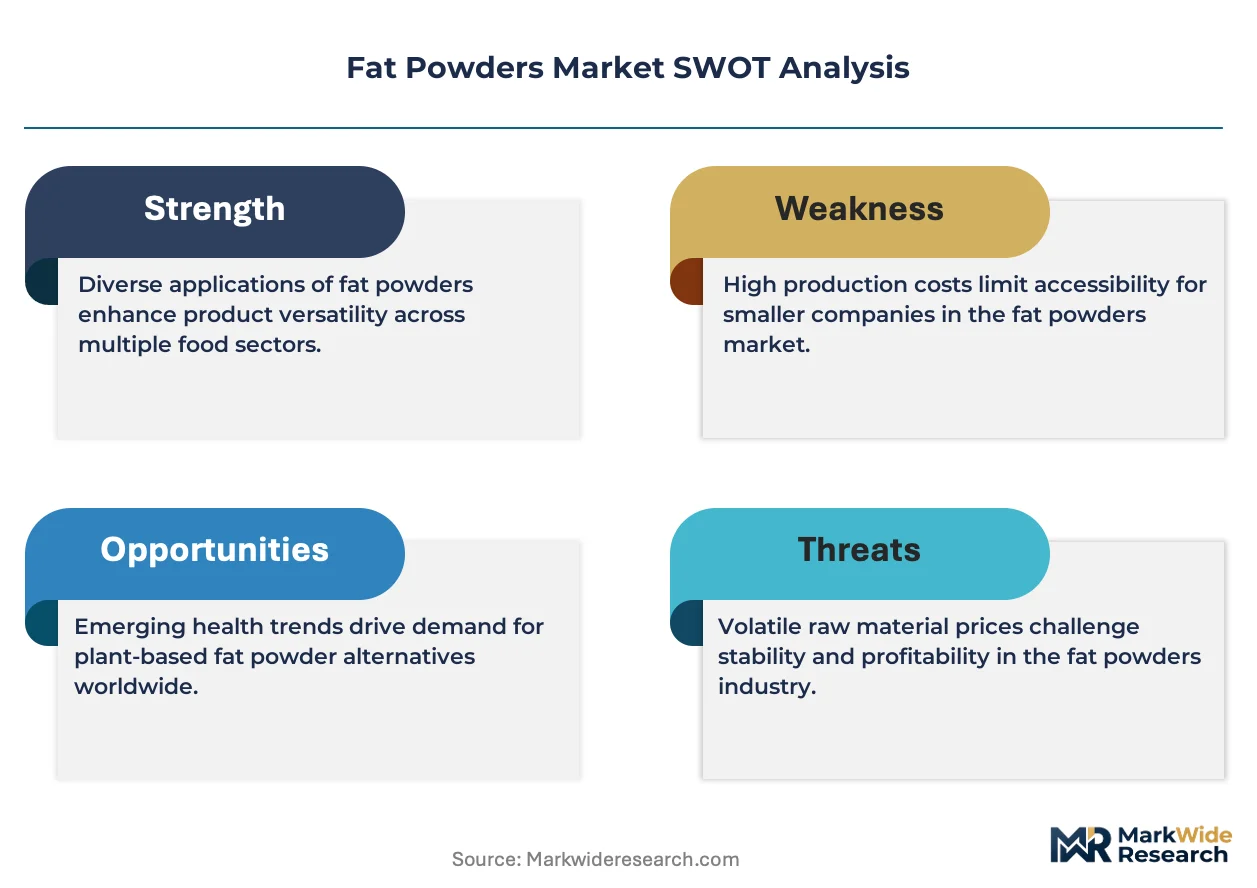
Fat powders are lipid-based particulate products manufactured through spray drying, fluid bed agglomeration, or chilling and grinding, typically containing 50–80% fat content on a dry-weight basis with carbohydrate or protein carriers to ensure flowability and oxidative stability. They serve as functional ingredients that provide mouthfeel, emulsification, and caloric density in processed foods without the handling constraints of liquid oils. Milk powder and whey powder segments lead current volume owing to entrenched dairy processing infrastructure and established clean-label positioning in infant nutrition and sports beverages. Coconut powder and vegetable powder categories represent the fastest-expanding demand pools as plant-based formulation trends accelerate across confectionery and dairy alternatives, though margin concentration remains tighter due to raw material price volatility in tropical oil markets.
FDA standards for GRAS notification and allergen labeling shape product development pathways for US-bound fat powder exports, while EFSA thresholds for 3-MCPD esters and glycidyl esters in refined vegetable oils directly constrain formulation choices for European food manufacturers. BIS certification requirements for milk powder imports into India create non-tariff barriers that favor suppliers with established analytical testing partnerships. Stakeholders must monitor evolving maximum residue limits for process contaminants and traceability mandates across multiple jurisdictions to sustain market access and avoid reformulation costs.
Market Dynamics
The EU Green Deal's deforestation-free supply chain rules are forcing vegetable-derived fat powder suppliers to reconfigure sourcing networks and invest in traceability infrastructure at unprecedented speed.
Growth Catalysts
- Clean-label emulsification demand:Food manufacturers across bakery and confectionery verticals are replacing synthetic emulsifiers with powdered fat systems to meet retailer clean-label mandates.
- REACH compliance incentives:European formulators are accelerating adoption of spray-dried fat powders to circumvent stricter chemical additive restrictions in processed foods.
- Plant-based dairy alternatives:Coconut and palm-derived powders are capturing formulation share in oat milk and almond yogurt production as mouthfeel standards tighten.
Market Restraints
- Tropical oil price volatility:Coconut and palm kernel feedstock costs swing with El Niño patterns and Indonesian export levy adjustments, compressing margin predictability.
- 3-MCPD ester limits:EFSA thresholds for process contaminants in refined vegetable oils constrain formulation flexibility and disqualify some Asian-sourced refined bases.
- Spray-drying energy intensity:Natural gas and electricity inputs represent 35-45% of powder production costs, exposing processors to European carbon pricing mechanisms.
Strategic Opportunities
- Microencapsulation R&D partnerships:Beverage brands are co-developing flavor-fat delivery systems with powder specialists to replace liquid oil dosing in ready-to-drink products.
- Indian import certification pathways:BIS-compliant testing partnerships unlock access to dairy-fat powder demand in infant nutrition and traditional sweets manufacturing.
- Carbon-negative spray drying:Biogas and electrified drying installations qualify for EU Green Deal transition financing and CSRD-aligned supply chain reporting.
Industry Challenges
- Process chemist scarcity:Lipid oxidation control and carrier matrix optimization require specialized expertise that outpaces European technical training pipeline output.
- Multi-jurisdiction residue compliance:Harmonizing 3-MCPD, glycidyl ester, and mineral oil limits across FDA, EFSA, and BIS frameworks demands redundant analytical capabilities.
- Legacy dairy infrastructure lock-in:Milk powder plants face retrofit costs for vegetable oil handling and hydrogenation-free process lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Powders Market |
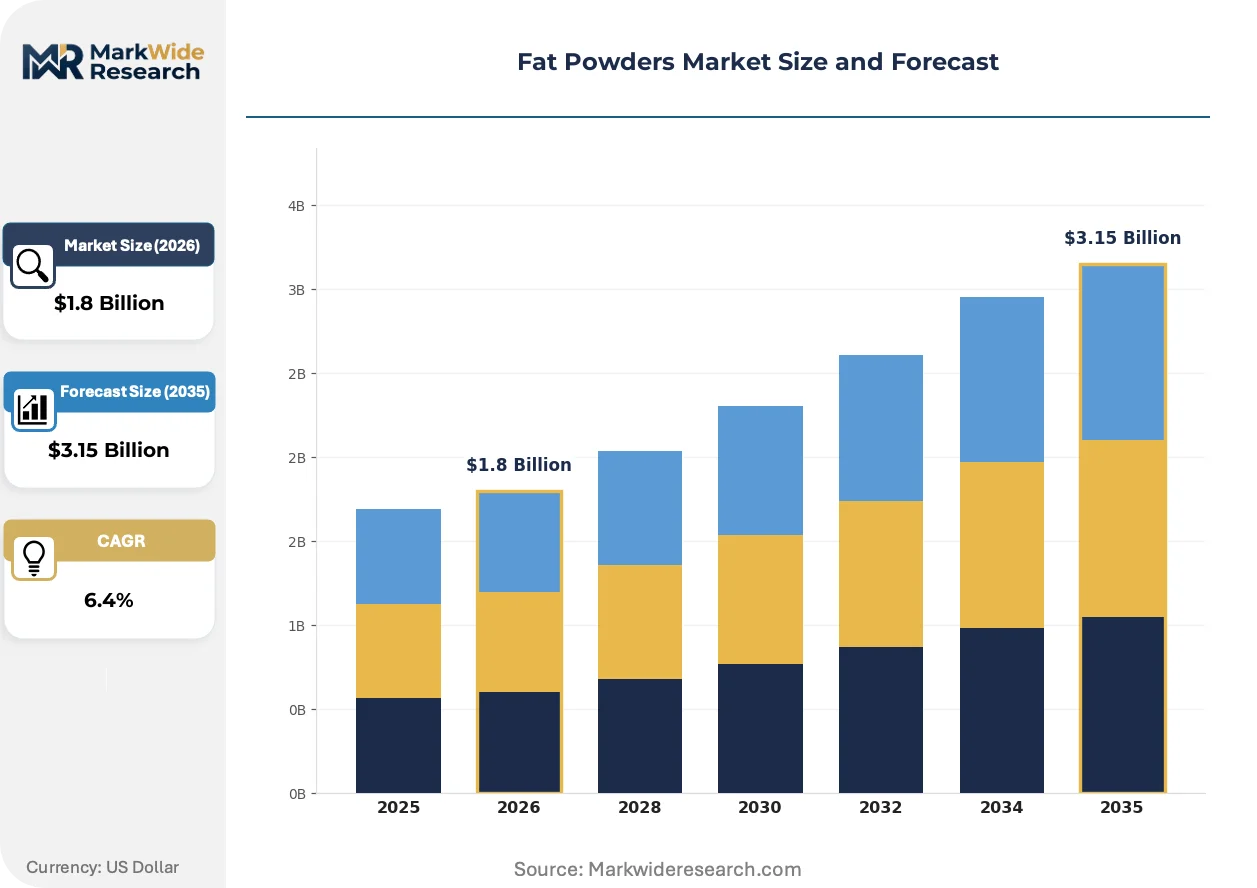
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Coconut Powder, Vegetable Powder, Whey Powder Application: Beverages, Bakery, Confectionery, Dairy Form: Instant, Granulated, Spray Dried, Flaked End User: Food Manufacturers, Restaurants, Retailers, Nutraceuticals |
| Companies Covered | Koninklijke FrieslandCampina NV, Kerry Group plc, Cargill, MEGGLE Food Ingredients, Vreugdenhil Dairy Foods, Dairygold Co-Operative Society Limited, Hoogwegt International B.V., Mokate Ingredients, Drytech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Powders Market Shifts & Advancements
Microencapsulation technology is redrawing technical specifications across beverage and sports nutrition applications, while regulatory pressure on process contaminants accelerates equipment replacement cycles.
Advanced spray-drying with inline microencapsulation is bifurcating the technical tier of fat powder supply. Premium beverage brands in Germany and the Netherlands are specifying 50-micron particle sizes with 12-month oxidative stability guarantees. This capability compression is separating R&D-intensive suppliers from commodity powder traders.
EFSA's evolving glycidyl ester and 3-MCPD ester thresholds are forcing European refiners to adopt molecular distillation and enzymatic interesterification. Palm oil-derived powder volumes face disproportionate impact as Malaysian and Indonesian suppliers race to install mitigation equipment. Reformulation toward coconut and shea alternatives is accelerating in Dutch and Belgian compound chocolate manufacturing.
Buyers are consolidating supplier relationships around integrated traceability platforms. German bakery ingredient clusters now require blockchain-verified deforestation-free palm certificates and batch-level contaminant testing. Direct procurement from spray-drying specialists is displacing traditional trading house intermediaries in Hamburg and Rotterdam port zones.
Fat Powders Market Segmentation
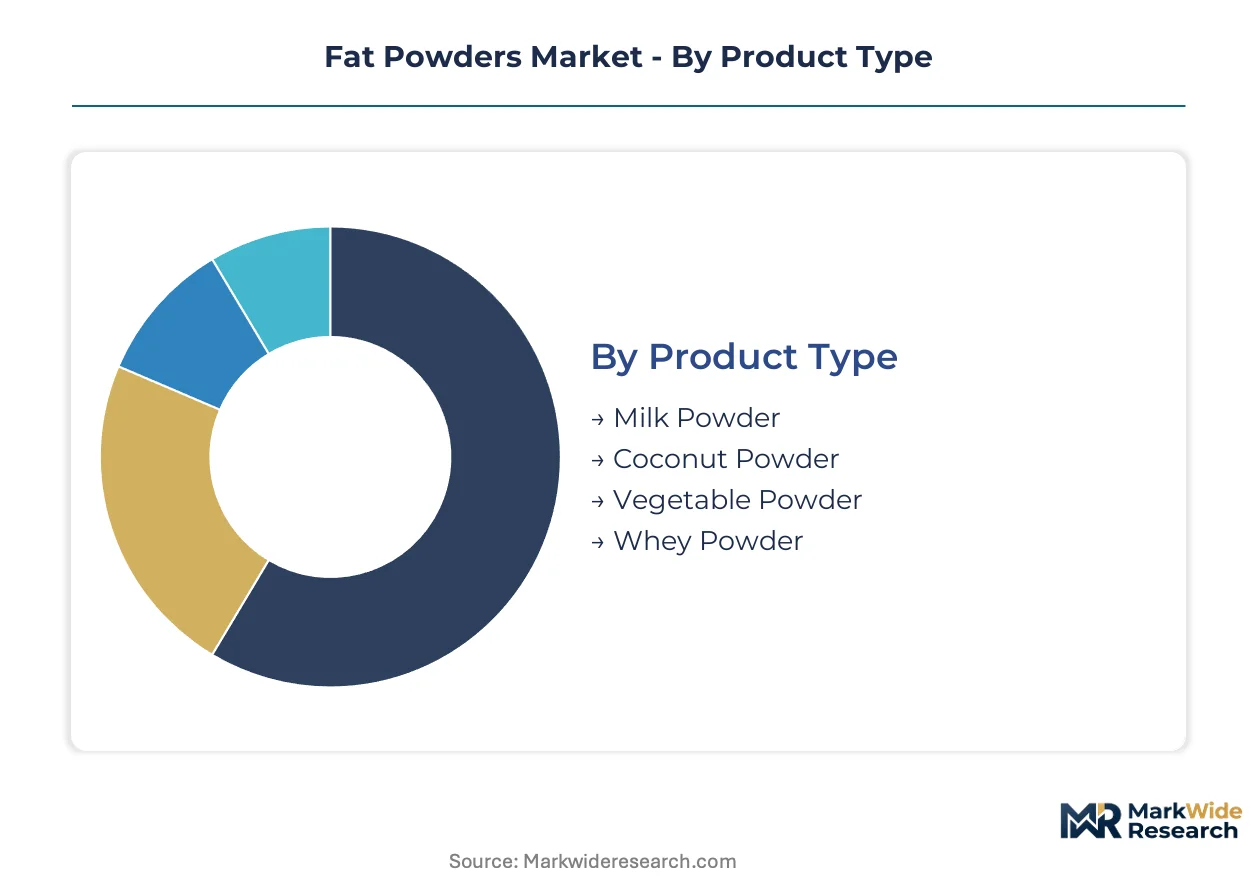
Fat powder segmentation reveals how technical specifications align with divergent regulatory pathways across export markets. Powdered lipid systems must satisfy distinct contaminant thresholds, carrier matrix requirements, and labeling mandates depending on their intended geography and end-use application.
Product Type:
EFSA's 3-MCPD ester and glycidyl ester limits create sharp formulation divergence between dairy-derived and vegetable-origin powders, while FDA GRAS notification pathways favor established milk protein carriers for US-bound shipments.
- Milk Powder:Spray-dried butterfat and anhydrous milk fat formulations leverage entrenched dairy processing infrastructure across Germany and the Netherlands. German bakery ingredient clusters around Lübeck specify 80% fat content with lactose carrier matrices to meet clean-label emulsification mandates in artisan bread production.
- Coconut Powder:Medium-chain triglyceride concentrates from spray-dried coconut oil are gaining formulation share in Dutch and Belgian plant-based dairy alternatives. EFSA process contaminant thresholds constrain sourcing to refiners with molecular distillation capability, compressing qualified supplier pools.
- Vegetable Powder:Palm and palm kernel-derived powders face EU Green Deal deforestation-free certification requirements that disqualify non-traceable supply chains.
- Whey Powder:Dairy permeate and whey protein-lipid complexes serve sports nutrition applications with established BIS certification pathways for Indian import access.
Established volume favors milk powder; emerging adoption favors coconut powder.
Application:
End-use differentiation tracks mouthfeel performance requirements and oxidative stability demands across processing intensities.
- Beverages:Microencapsulated fat powders with 50-micron particle specifications enable oil-in-water emulsion stability in ready-to-drink protein shakes. Dutch beverage brands co-develop flavor-fat delivery systems with powder specialists to replace liquid oil dosing lines.
- Bakery:High-fat powders with 12-month oxidative stability guarantees anchor clean-label reformulations in Hamburg's industrial bread manufacturing. REACH compliance incentives accelerate displacement of synthetic emulsifiers.
- Confectionery:Compound chocolate manufacturers in Belgium reformulate toward shea and coconut alternatives as Malaysian palm oil faces glycidyl ester scrutiny.
- Dairy:Infant nutrition applications demand batch-level contaminant testing and blockchain-verified traceability that only integrated dairy processors can supply.
Volume concentrates in bakery; steepest expansion trajectory appears in beverages.
Form:
Processing technology determines oxidative stability, reconstitution speed, and capital intensity for powder production.
- Spray Dried:Inline microencapsulation systems produce premium-grade powders with controlled particle size distribution for beverage emulsion stability. Natural gas and electricity inputs represent 35-45% of production costs, exposing European processors to carbon pricing mechanisms.
- Instant:Agglomerated particles with enhanced cold-water solubility serve convenience-oriented food service applications in quick-service restaurant chains.
- Granulated:Fluid bed agglomeration yields free-flowing particles with reduced dusting for industrial bakery bulk handling systems.
- Flaked:Chilled and ground lipid flakes provide controlled melt profiles for confectionery tempering processes.
Technology leadership sits with spray dried; cost-sensitive adoption favors granulated.
End User:
Customer type dictates certification depth, volume scale, and technical service intensity.
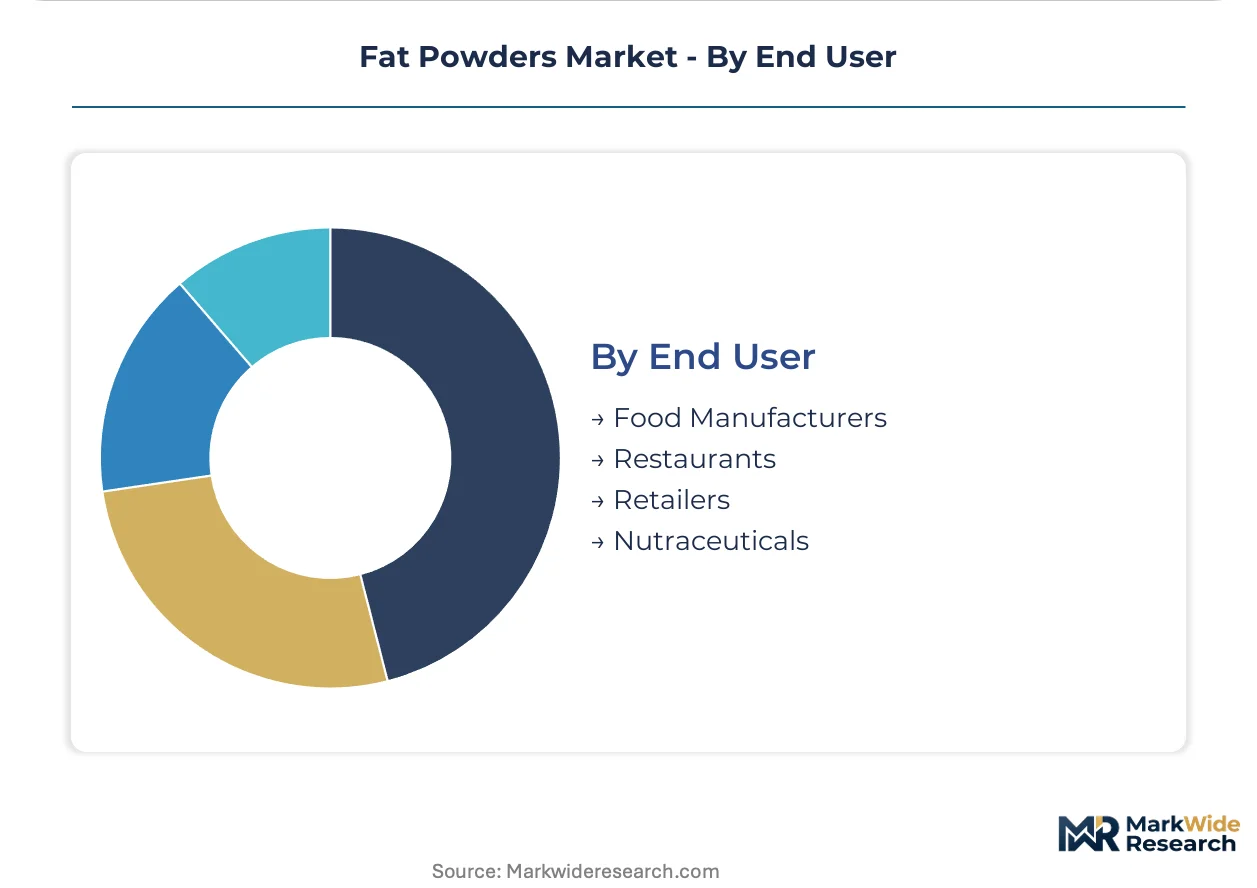
- Food Manufacturers:Integrated procurement teams demand blockchain-verified deforestation-free certificates and redundant contaminant testing across FDA, EFSA, and BIS frameworks. Direct supplier relationships are displacing trading house intermediaries in Rotterdam port zones.
- Nutraceuticals:Sports nutrition and infant formula brands specify premium microencapsulation with 12-month oxidative stability guarantees.
- Restaurants:Food service distributors prioritize instant reconstitution and bag-in-box packaging for back-of-house efficiency.
- Retailers:Private-label powder sourcing emphasizes clean-label positioning and competitive unit economics for shelf-stable baking mixes.
Procurement sophistication peaks with food manufacturers; margin expansion favors nutraceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vegetable-derived fat powder supply chains concentrate in coastal refining corridors with established spray-drying infrastructure and port access to tropical oil feedstocks. Germany anchors European formulation demand through its industrial bakery cluster, while Asian processing hubs face EU Green Deal compliance pressure.
Germany
Clean-label bakery reformulations drive demand for 80% fat-content milk powders in the Lübeck-Hamburg corridor. EFSA's 3-MCPD ester thresholds disqualify non-compliant Asian refined oils, compressing qualified supplier pools. The Hamburg port zone sees direct procurement displacing traditional trading intermediaries as blockchain-verified deforestation-free certificates become mandatory.
Netherlands
Dutch beverage brands co-develop microencapsulated flavor-fat delivery systems for ready-to-drink protein shakes. REACH compliance incentives accelerate synthetic emulsifier displacement in Rotterdam's food ingredient trading hub. Belgian compound chocolate manufacturers reformulate toward shea and coconut alternatives as palm oil faces glycidyl ester scrutiny.
United States
FDA GRAS notification pathways favor established milk protein carriers for infant nutrition and sports beverage applications. EPA energy efficiency standards shape spray-drying facility investments in California's dairy processing corridor. Midwest milk powder plants face retrofit costs for vegetable oil handling and hydrogenation-free process lines.
India
BIS certification requirements for milk powder imports create non-tariff barriers favoring suppliers with analytical testing partnerships in infant nutrition and traditional sweets manufacturing. FSSAI contaminant thresholds align with tightening international standards. Maharashtra's dairy processing infrastructure serves domestic demand while import-dependent coastal states absorb certified foreign supply.
Indonesia
Export levy adjustments on palm kernel feedstock generate margin volatility for European powder processors dependent on tropical oils. The country's national food safety regulator enforces evolving maximum residue limits for process contaminants. Sumatran and Kalimantan plantation zones invest in traceability infrastructure to satisfy EU Green Deal deforestation-free mandates.
Fat Powders Market Competitive Landscape
Concentration sits with diversified ingredient conglomerates and dairy-specialized processors. The vendor base spans three tiers: multinational conglomerates with backward integration into oilseed crushing, European dairy cooperatives with entrenched spray-drying assets, and regional specialists in microencapsulation technology. Strategic moves center on R&D partnerships for flavor-fat delivery systems and carbon-negative drying facility investments qualifying for EU transition financing.
Within the dairy cooperative tier, Koninklijke FrieslandCampina NV exemplifies European milk powder infrastructure scale. Kerry Group plc and Cargill occupy positions spanning ingredient technology and upstream oilseed control. MEGGLE Food Ingredients represents specialized dairy-fat formulation expertise. These three anchors illustrate divergent competitive vectors: cooperative ownership structure, multinational R&D intensity, and captive supply chain integration.
| Leading Market Players |
|---|
| Koninklijke FrieslandCampina NV |
| Kerry Group plc |
| Cargill |
| MEGGLE Food Ingredients |
| Vreugdenhil Dairy Foods |
| Dairygold Co-Operative Society Limited |
| Hoogwegt International B.V. |
| Mokate Ingredients |
| Drytech |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Rotterdam traders and Malaysian palm refiners lock in both supply access and price visibility for vegetable-derived fat powders, insulating European processors from El Niño-driven feedstock volatility while compressing spot-market liquidity for smaller compounders.
Pricing Analysis
EU Green Deal deforestation-free certification dictates the pricing tier structure across fat powder supply. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified sustainable grades from conventional traceable lots and unverified commodity volumes. Pricing pressure stems from natural gas and electricity inputs representing substantial production costs, exposing spray-dryers to European carbon pricing mechanisms. Food manufacturers with integrated procurement teams demonstrate lowest price sensitivity, while independent bakeries and regional confectioners face acute margin compression.
Supply Chain Analysis
Strait of Malacca transit underwrites the bulk of palm kernel and coconut oil feedstock movement to European spray-drying facilities. Supply concentrates in Indonesia, Malaysia, and the Philippines for tropical oil extraction, with Germany and the Netherlands hosting downstream powder processing. Raw material dependencies rest on plantation crude palm oil, refined coconut oil, and dairy butterfat streams. Single-source vulnerability in Malaysian molecular distillation capacity for 3-MCPD mitigation creates bottleneck risk. Distribution runs through Rotterdam and Hamburg port zones with direct supplier relationships displacing traditional trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with regulatory-driven certification tiers creating defendable niches for specialists with analytical capabilities and traceability infrastructure that commodity traders cannot replicate.
For Market Incumbents: Compound technical service intensity around microencapsulation R&D partnerships with Dutch beverage brands seeking flavor-fat delivery systems. Deepen backward integration into plantation traceability platforms to preempt EU Green Deal compliance costs. Defend against emerging Asian refiners installing molecular distillation by locking German bakery clusters into multi-year clean-label supply contracts. For New Entrants and Emerging Players: Lead with BIS-certified testing partnerships to unlock Indian dairy-fat powder demand in infant nutrition and traditional sweets manufacturing. Target Maharashtra's import-dependent coastal states where analytical capabilities gaps persist. Pursue carbon-negative spray drying installations qualifying for EU Green Deal transition financing as differentiated market entry. For Investors and Strategic Acquirers: European dairy cooperatives with entrenched spray-drying assets and hydrogenation-free process lines represent the most attractive acquisition archetype for long-term viability across the 5-10 year window. Monitor EFSA threshold tightening for 3-MCPD esters and glycidyl esters as inflection indicator for equipment replacement cycles and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Traceability | EU Green Deal deforestation-free mandates force captive supply verification from Sumatran and Kalimantan zones. |
| Microencapsulation R&D Partnership | Kerry Group plc's technical collaborations with multinational beverage brands demonstrate premium pricing capture. |
| Carbon-Negative Spray Drying Installation | Biogas and electrified drying qualifies for CSRD-aligned supply chain reporting and transition financing. |
| BIS Certification Pathway Development | Analytical testing partnerships unlock access to Indian infant nutrition and traditional sweets manufacturing demand. |
| Molecular Distillation Capability Addition | EFSA process contaminant thresholds disqualify Asian refiners without mitigation equipment, compressing qualified supplier pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with spray-drying plant managers, procurement leads at German bakery ingredient clusters, regulatory affairs directors navigating EFSA and FDA frameworks, and technical R&D heads specializing in lipid oxidation control. Secondary validation drew from EU Green Deal implementation documents, EFSA scientific opinions on process contaminants, BIS certification requirements, customs trade data for tropical oil flows, and SEC filings from diversified ingredient conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Across the analysis window, the forecast framework modeled powder production capacity utilization, feedstock price elasticity, and regulatory compliance cost trajectories. Segmentation dimensions included product type differentiation between dairy-derived and vegetable-origin powders, application intensity across bakery and beverage verticals, form technology from spray-dried to granulated, and end-user procurement sophistication tiers. CAGRs were derived from trend extrapolation of clean-label adoption curves and plant-based formulation shifts, with explicit incorporation of EU carbon pricing pass-through assumptions and tropical oil supply volatility patterns.
Forecasts assume regulatory continuity in EU Green Deal implementation, EFSA contaminant thresholds, and FDA GRAS notification pathways; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Indonesian export levy adjustments and El Niño pattern intensities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Spirulina Powder Market