
 Dry Malt Products Market | 2026-2036
Dry Malt Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Malt Products Market Foresight
Maltster apprenticeship pipelines across Central Europe is collapsing, constraining output from heritage kilning operations. Boortmalt leverages its integrated supply chain from field to drum to secure raw barley access across multiple harvest zones. Muntons PLC anchors British brewing demand through dedicated malt extract production for industrial ale and stout manufacturers. Viking Malt competes aggressively in Nordic specialty markets with precision-roasted flaked malt varieties for craft distillers.
Dry malt products comprise partially germinated cereal grains that undergo controlled kilning and dehydration to achieve specific diastatic power, color ratings measured in EBC or Lovibond units, and enzymatic profiles for fermentation or flavoring purposes. Dry malt extract dominates commercial volume due to its shelf stability and standardized fermentability for large-scale beverage production. Bakery applications represent the fastest-growing segment as clean-label formulators replace refined sugars with malt powder for browning and moisture retention. Dry malt syrup occupies a narrower margin pool, serving niche confectionery clients who require specific viscosity and Maillard reaction control.
The EU Green Deal and REACH frameworks pressure maltsters to document carbon intensity across kilning and drying stages, while the FDA and USDA in the United States enforce mycotoxin thresholds and grain handling sanitation for imported malt ingredients. EFSA guidelines on acrylamide formation during roasting further constrain process parameters for darker malt varieties. Stakeholders must monitor how divergent sustainability verification schemes between European and North American regulators reshape cross-border ingredient sourcing decisions.
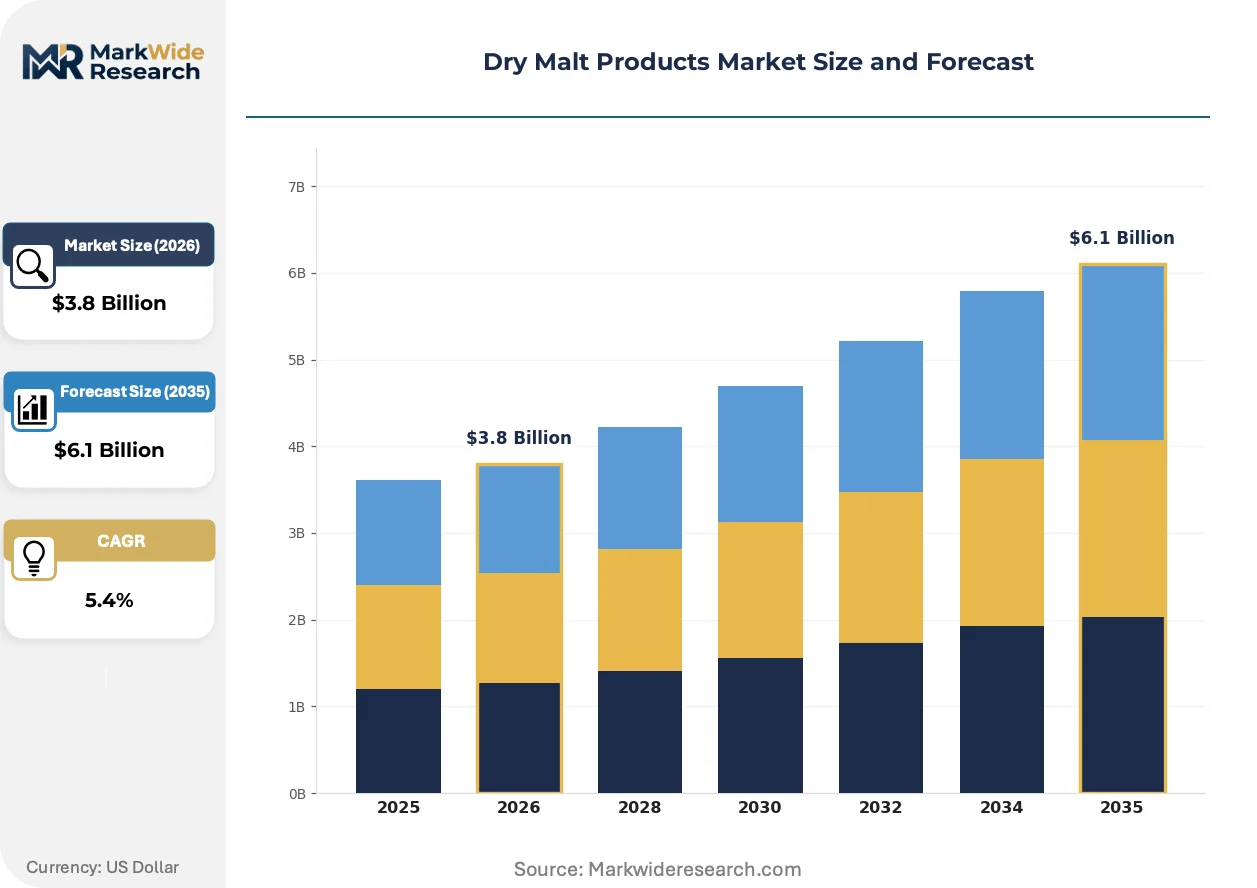
Market Dynamics
EU Green Deal carbon accounting mandates are forcing maltsters to retool kilning operations toward energy recovery systems, restructuring capital deployment across European production bases and reshaping supplier qualification criteria for North American craft brewery procurement.
Growth Catalysts
- EU Green Deal compliance requirements:Maltsters investing in heat-recovery kilning systems gain preferred supplier status with sustainability-scoring brewers in Germany and Denmark.
- Clean-label bakery formulation:Industrial bakers in France and Italy are substituting refined sugars with malt powder to achieve Maillard browning without artificial additives.
- Specialty distilling expansion:Nordic craft distillers are sourcing precision-roasted flaked malts for whiskey and gin base spirits, creating premium extract demand.
Market Restraints
- Barley supply concentration:Heritage kilning operations in Central Europe depend on contracted spring barley from limited Polish and Czech growing regions.
- Acrylamide threshold constraints:EFSA guidelines on roasting temperatures restrict color development for darker malt varieties above 300 EBC.
- Apprenticeship pipeline collapse:Traditional floor malting skills are vanishing as master maltsters retire without trained replacements in Bavaria and Bohemia.
Strategic Opportunities
- US craft brewery procurement:Small-batch brewers in Colorado and Oregon seek specialty dry malt extracts with documented carbon intensity for sustainability marketing.
- Confectionery viscosity customization:Niche chocolate and caramel manufacturers require specific dry malt syrup grades for controlled Maillard reaction timing.
- Heat pump kilning technology:Electrification incentives under Germany's Federal Funding for Efficient Buildings program accelerate fossil fuel displacement in roasting operations.
Industry Challenges
- Diastatic power standardization:Batch-to-batch enzyme variability in heritage floor malting complicates contract brewing specifications for consistency-dependent lager producers.
- REACH documentation burden:Chemical safety data requirements for roasted malt dust classifications strain compliance resources at mid-scale maltsters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Malt Products Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Malt Extract, Dry Malt Powder, Dry Malt Syrup, Flaked Malt Application: Beverages, Bakery, Confectionery, Nutritional Products End User: Food Manufacturers, Breweries, Home Brewers, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Malteurop Group, Boortmalt, Rahr Corporation, Simpsons Malt, Muntons PLC, Cargill, Soufflet Group, Viking Malt, GrainCorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Malt Products Market Shifts & Advancements
Electrification of thermal processes and precision fermentation analytics are converging to redefine malt quality assurance, while sustainability verification schemes fragment across Atlantic regulatory jurisdictions.
Electromagnetic kilning using radio frequency heating is supplanting conventional gas-fired roasting for specialty malt color development. Craft maltsters in Belgium and the Netherlands are piloting these systems for small-batch precision. The technology is compressing energy intensity metrics for dark malt varieties while enabling real-time moisture control previously unattainable with conductive heat transfer.
REACH framework amendments on substance of very high concern listings are extending disclosure requirements to roasted grain byproducts. Maltsters must now document acrylamide precursor pathways through their kilning curves. Dark roast specialists in Ireland and Scotland face reformulation pressure as ECHA evaluates lower-temperature process alternatives.
Brewery technical buyers now demand lot-level carbon intensity certificates ahead of price negotiations. Large-scale ale manufacturers in England are consolidating supplier rosters to vendors with verified Scope 3 barley sourcing. This behavioral pivot concentrates procurement volume with integrated field-to-drum operators who control cultivation data.
Dry Malt Products Market Segmentation
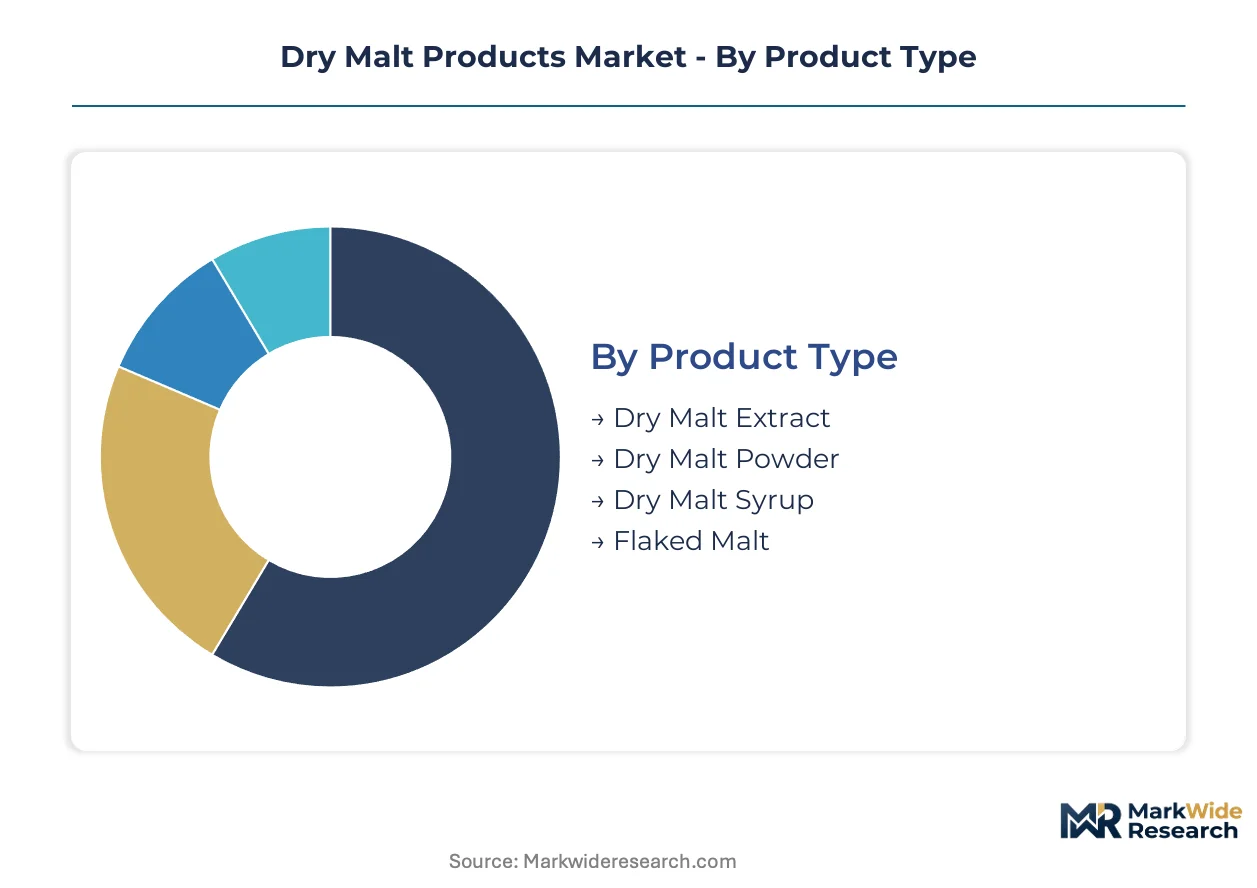
Dry malt products serve divergent technical requirements across brewing, baking, and industrial food systems. Segmentation reveals how extraction methods, moisture content, and enzymatic activity determine channel access and customer procurement behavior.
Product Type:
Channel mix varies sharply: extract and powder dominate institutional procurement through wholesale distributors, while syrup and flaked varieties concentrate in specialty retail and direct-to-brewery supply chains.
- Dry Malt Extract:Concentrated soluble solids derived from mashed, filtered, and spray-dried wort, standardized to specific fermentability and color ratings. Large-scale ale and lager manufacturers in Germany and England procure through contracted drum quantities with documented carbon intensity certificates for sustainability compliance.
- Dry Malt Powder:Finely milled kilned malt with intact enzymatic diastatic power for dough conditioning and browning reactions. Industrial bakers in France and Italy are substituting refined sugars with malt powder to achieve clean-label Maillard browning without artificial additives.
- Dry Malt Syrup:Hygroscopic concentrated solution with controlled viscosity and reducing sugar content for confectionery timing control. Niche caramel and chocolate manufacturers require specific syrup grades for precise Maillard reaction management.
- Flaked Malt:Pre-gelatinized rolled grains for rapid starch conversion in distilling mashes. Nordic craft distillers source precision-roasted flaked varieties for whiskey and gin base spirits.
By volume, Dry Malt Extract leads. By growth pace, Dry Malt Powder is expanding most quickly.
Application:
Cost tier stratification separates commodity beverage brewing from premium bakery and confectionery formulation where ingredient certification commands price premiums.
- Beverages:Beer, malt beverages, and fermented drinks requiring standardized fermentability, diastatic power, and color development. German lager producers and British ale manufacturers consolidate procurement with integrated field-to-drum operators controlling barley cultivation data.
- Bakery:Bread, rolls, and pastry applications leveraging malt enzymes for dough conditioning and crust color. Clean-label formulators across France, Italy, and Denmark are accelerating procurement as refined sugar replacement intensifies.
- Confectionery:Caramel, chocolate, and candy production requiring specific viscosity and controlled browning kinetics. Specialty manufacturers demand lot-level documentation for acrylamide precursor management under EFSA guidelines.
- Nutritional Products:Malt-based supplements and functional foods emphasizing natural sweetness and mineral content. Health-positioned brands in the Netherlands and Belgium source organic-certified extracts for infant and sports nutrition lines.
Beverage applications command the largest revenue pool. Bakery applications are gaining share fastest on clean-label substitution trends.
End User:
Customer type determines order scale and specification rigor, from bulk drum contracts for food manufacturers to small-batch specialty sourcing for home brewers.
- Food Manufacturers:Industrial-scale bakeries, confectioners, and ingredient blenders requiring consistent enzymatic specifications and allergen documentation. Procurement concentrates through wholesale distributors with integrated quality certification.
- Breweries:Commercial beer producers ranging from mass-market lager facilities to craft microbreweries. Colorado and Oregon craft brewers seek specialty extracts with documented carbon intensity for sustainability marketing differentiation.
- Home Brewers:Amateur and semi-professional brewing enthusiasts purchasing smaller package sizes through specialty retail and online channels. This segment accesses premium specialty malts unavailable at industrial scale.
- Restaurants:Gastropubs, brewpubs, and bakery kitchens using malt ingredients for house-made preparations. Limited volume but high margin through specialty store and foodservice distributor channels.
Food Manufacturers represent the deepest volume base. Breweries show the steepest specification evolution toward traceability and carbon accounting.
Distribution Channel:
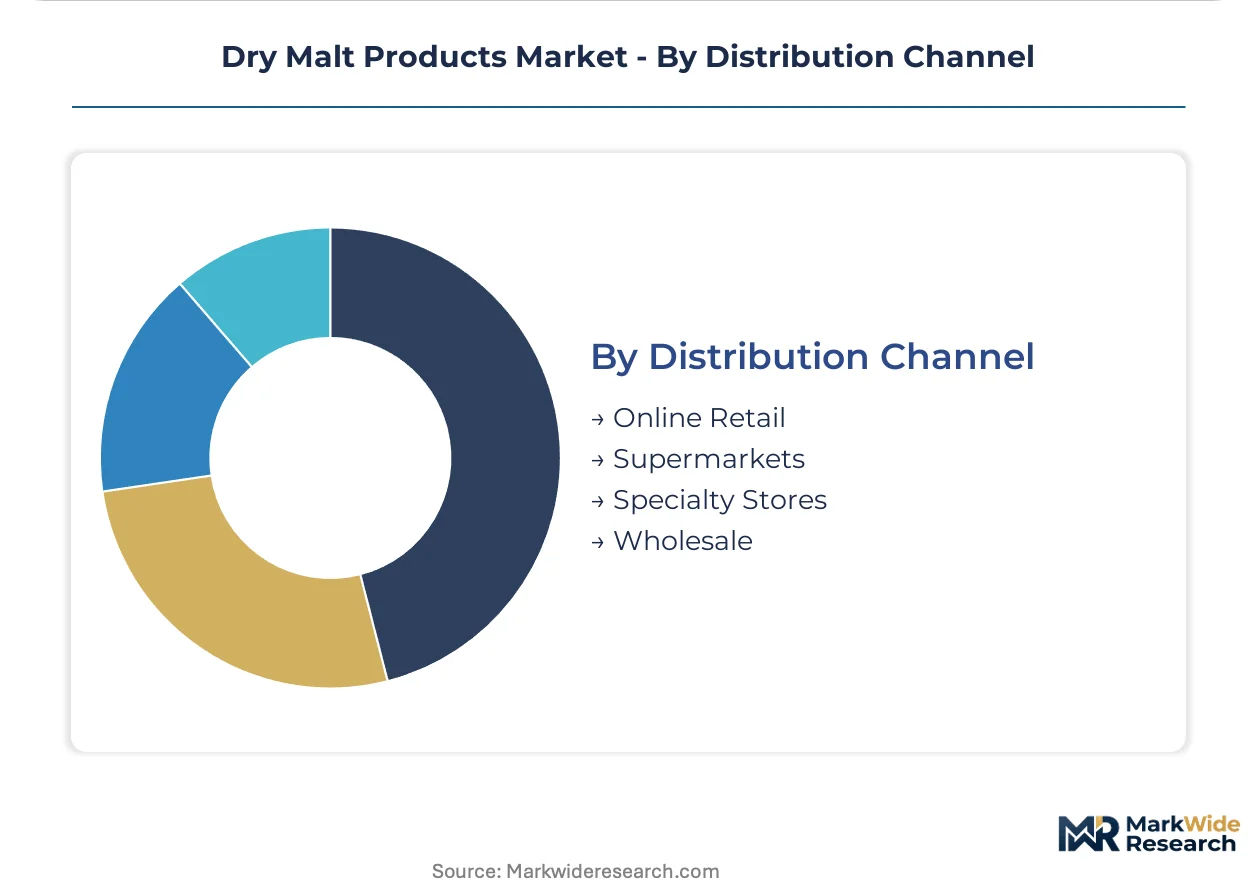
Supply concentration varies by geography: wholesale dominates Central European brewing corridors, while online retail penetrates fragmented craft and home-use markets in North America.
- Online Retail:Direct-to-consumer and small-business platforms serving home brewers and specialty food producers. E-commerce penetration is climbing fastest for flaked malt varieties and organic-certified extracts.
- Supermarkets:Mass-market retail chains stocking consumer-format malt powder and syrup for home baking. Limited penetration outside German-speaking markets with strong traditional baking culture.
- Specialty Stores:Homebrew supply shops, bakery ingredient distributors, and craft food retailers. These channels capture premium pricing through technical consultation and curated specialty assortments.
- Wholesale:Industrial distributors and ingredient brokers supplying food manufacturers and breweries at drum and tote quantities. Integrated maltsters leverage captive supply chains to secure preferred supplier status.
Wholesale channels move the largest absolute volume. Online retail is expanding most quickly on craft brewing democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon accounting mandates are restructuring procurement priorities across malt-dependent industries. The report traces how regulatory pressure cascades through national production bases and supplier qualification criteria.
Germany
Craft brewery expansion in Bavaria and Berlin drives specialty extract procurement with documented carbon intensity certificates. The Federal Funding for Efficient Buildings program accelerates heat pump kilning adoption among mid-scale maltsters. Munich and Hamburg anchor industrial brewing corridors where integrated field-to-drum operators consolidate preferred supplier status.
United States
Colorado and Oregon craft brewers source small-batch specialty extracts for sustainability marketing differentiation. FDA and USDA mycotoxin thresholds enforce grain handling sanitation standards for imported malt ingredients. The Pacific Northwest brewing cluster concentrates procurement with vendors offering lot-level carbon accounting documentation.
France
Industrial bakers across Île-de-France and Auvergne-Rhône-Alpes substitute refined sugars with malt powder for clean-label Maillard browning. EFSA acrylamide guidelines constrain roasting temperatures for darker varieties above 300 EBC. Lyon and Paris bakery ingredient distributors report accelerating procurement from organic-certified extract suppliers.
United Kingdom
Large-scale ale manufacturers in England consolidate supplier rosters to integrated operators controlling barley cultivation data. REACH framework amendments extend disclosure requirements to roasted grain byproducts. Burton-upon-Trent and London brewing facilities prioritize Scope 3 verified sourcing for sustainability compliance.
Belgium
Electromagnetic kilning pilots using radio frequency heating compress energy intensity metrics for dark malt varieties. ECHA evaluations of lower-temperature process alternatives pressure dark roast specialists toward reformulation. Brussels and Antwerp craft maltsters lead small-batch precision roasting technology adoption.
Dry Malt Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the dry malt products sector. The market structure consolidates around integrated agricultural processors with captive barley supply chains and independent specialty maltsters with precision roasting capabilities. Three archetypes dominate: field-to-drum integrated operators controlling cultivation data, heritage floor malting specialists with enzymatic consistency expertise, and regional extract processors serving bakery and confectionery channels. Competitive moves center on heat-recovery kilning capital deployment and carbon intensity certification acquisition for preferred supplier positioning.
Among integrated supply chain operators, Boortmalt and Malteurop Group exemplify the field-to-drum archetype with multi-harvest zone raw material access. Muntons PLC anchors British brewing demand through dedicated extract production capabilities. Viking Malt occupies a position within Nordic specialty markets precision-roasting flaked varieties for craft distilling applications. These three companies represent distinct competitive vectors: agricultural integration, regional brewing anchoring, and specialty roasting precision.
| Leading Market Players |
|---|
| Malteurop Group |
| Boortmalt |
| Rahr Corporation |
| Simpsons Malt |
| Muntons PLC |
| Cargill |
| Soufflet Group |
| Viking Malt |
| GrainCorp |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon accounting certificates now gate both supplier qualification and price differentiation simultaneously, forcing maltsters to invest in heat-recovery kilning before accessing premium procurement tiers. This regulatory layer compresses margins for uncertified operators while rewarding integrated field-to-drum competitors with documented Scope 3 barley sourcing.
Pricing Analysis
Geographic price spreads widen between German heat-pump kilned specialty extracts and conventional gas-fired alternatives from Central European heritage operations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and carbon intensity documentation, with craft brewers in Colorado and Oregon showing least price sensitivity for lot-level traceability. Pricing pressure stems from energy cost differentials as electrification incentives reshape German production economics, while contract brewers in England negotiate hardest on per-kilogram rates for base malt extracts.
Supply Chain Analysis
Inbound logistics costs from Baltic Sea port congestion and container availability constraints on the Hamburg-Rotterdam trade lane are elevating landed costs for North American craft brewery procurement. Supply concentrates in Germany, France, and the United Kingdom for kilned malt production, with raw barley drawn from Polish and Czech growing regions. Single-source vulnerability runs through contracted spring barley from limited harvest zones. Distribution runs through wholesale industrial distributors and ingredient brokers supplying food manufacturers at drum quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where carbon intensity certification and technical consultation layers expand faster than commodity extract volume. Maltsters bundling lot-level traceability with brewing optimization support capture recurring revenue streams beyond per-kilogram sales.
For Market Incumbents: Secure preferred supplier status with sustainability-scoring brewers by accelerating heat pump kilning deployment under Germany's Federal Funding for Efficient Buildings program. Defend against electromagnetic kilning disruptors in Belgium and the Netherlands by locking multi-year barley cultivation contracts across Polish and Czech harvest zones. Consolidate procurement volume with integrated field-to-drum data control to outcompete heritage floor malting specialists facing apprenticeship pipeline collapse.
For New Entrants and Emerging Players: Lead with precision-roasted flaked malt varieties for Nordic craft distillers where Viking Malt's dominance remains penetrable through electromagnetic radio frequency heating pilots. Target bakery applications in France and Italy where clean-label sugar substitution accelerates faster than brewing demand. Deploy direct-to-brewery technical consultation models bypassing wholesale distributor markups for small-batch Colorado and Oregon craft brewers.
For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural conglomerates divesting non-core malt processing divisions lacking carbon accounting infrastructure. Long-term viability centers on electrified kilning capabilities and captive barley supply chains over the next decade. Watch for inflection when ECHA lower-temperature process alternatives force dark roast specialists toward capital-intensive reformulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Kilning Adoption | German Federal Funding incentives accelerate fossil fuel displacement in roasting operations. |
| Carbon Intensity Certification | Lot-level documentation unlocks preferred supplier status with sustainability-scoring brewers. |
| Electromagnetic Kilning Pilots | Belgian and Dutch craft maltsters compress energy metrics for dark malt varieties. |
| Backward Integration into Barley Cultivation | Multi-harvest zone access secures raw material against Polish and Czech supply concentration. |
| Technical Consultation Service Layer | Brewing optimization support captures recurring revenue beyond commodity extract sales. |
Research Methodology
Initial hypotheses were tested against primary input from maltster operations directors, craft brewery procurement managers, bakery ingredient formulators, and distillery technical leads and refined through secondary validation. Primary fieldwork combined structured interviews across German, British, and French production facilities with trade data from customs records and industry association filings. Secondary sources incorporated EU ETS carbon accounting disclosures, EFSA acrylamide guideline documentation, and SEC filings from publicly traded agricultural processors. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Variance decomposition across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by revenue contribution and penetration elasticity. Industry-specific forecast inputs included kilning technology adoption curves under EU Green Deal compliance timelines and craft brewery sustainability procurement scoring methodologies.
Underlying assumptions cover regulatory enforcement continuity for REACH and EU Green Deal frameworks, with deviation risk concentrated in ECHA lower-temperature process alternative rulings and Baltic Sea logistics disruption. Forecasts reflect these documented conditions with model sensitivity to barley harvest variability and electrification incentive program extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Home Baking Ingredients Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Icing Shortening Market
Ingredients
Europe Soy Protein Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Broccoli Powder Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
Textured Soy Flour Market
Ingredients
Confectionery Ingredients Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
Banana Flour Market
Ingredients
Energy Ingredients Market
Ingredients
Spelt Flour Market
Ingredients
Compressed Yeast Market
Ingredients
North America Cocoa Products Market