
 Plant Sterols and Esters Market | 2026-2036
Plant Sterols and Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Sterols and Esters Market Insights
European phytosterol extraction capacity is restructuring around certified sustainable feedstock sourcing. BASF SE leverages backward integration into tall oil refining to secure raw material consistency. DSM Nutritional Products anchors its position through pharmaceutical-grade esterification technology. Cargill Incorporated competes via global oilseed processing networks that span multiple continents.
Plant sterols and esters comprise steroid alcohols structurally similar to cholesterol, typically derived from vegetable oils and tall oil pitch through solvent extraction or supercritical CO2 processing, then esterified with fatty acids to improve lipid solubility for food matrix incorporation. Their primary commercial purpose centers on blocking intestinal cholesterol absorption, enabling FDA-authorized coronary heart disease risk reduction claims in qualifying foods. Powder formulations dominate functional food manufacturing due to superior flow properties and shelf stability in baked goods and spreads. Dietary supplements in softgel delivery represent the fastest-expanding application channel as consumers seek concentrated daily intake formats. Pharmaceutical firms occupy the highest-margin end-user tier where sterol esters serve as active pharmaceutical ingredients in prescription lipid management therapies.
EFSA health claims regulation governs permissible cholesterol reduction messaging across European Union member states, while FDA qualified health claims provide the parallel framework in the United States. BIS fortification standards in India and FSSAI labeling requirements increasingly influence export-oriented manufacturers targeting South Asian markets. Stakeholders must monitor evolving national maximum-level regulations for sterol incorporation in conventional foods versus restricted therapeutic categories.
Market Dynamics
EFSA health claims authorization is compressing competitive timelines as European functional food manufacturers race to reformulate cholesterol-lowering portfolios before labeling windows close.
Growth Catalysts
- FDA Qualified Health Claims:The framework permits coronary heart disease risk reduction messaging on qualifying foods, directly expanding permissible marketing territory for sterol-fortified spreads and dairy in the United States.
- Germany:Food technologists in this market pioneer sterol-fortified dairy applications, creating template formulations that accelerate adoption across neighboring EU member states.
- Supercritical CO2 Processing:This extraction technology reduces solvent residues in pharmaceutical-grade sterol production, opening prescription lipid management channels previously closed to food-grade suppliers.
Market Restraints
- Tall Oil Pitch Volatility:Crude tall oil supply concentrates in Nordic pulp mill networks, exposing sterol extractors to input cost swings when paper production cycles fluctuate.
- Maximum-Level Caps:FSSAI labeling requirements in India impose strict sterol concentration ceilings in conventional foods versus therapeutic categories, fragmenting formulation strategies for export-oriented manufacturers.
- Cholesterol Absorption Inhibitors:Prescription alternatives like ezetimibe compete for the same clinical endpoints, capping consumer willingness to pay premium prices for food-based interventions.
Strategic Opportunities
- South Asian Markets:BIS fortification standards in India create compliance-aligned entry points for manufacturers with existing EFSA-authorized production systems.
- Softgel Supplements:This delivery format captures consumers seeking concentrated daily intake outside food matrix constraints, bypassing formulation stability challenges in baked goods.
- EU Green Deal:Sustainable feedstock certification requirements favor producers with backward integration into certified tall oil refining, disadvantaging spot-market dependent competitors.
Industry Challenges
- Esterification Specialist Talent:Pharmaceutical-grade lipid chemistry expertise concentrates in Basel and Rotterdam corridor firms, creating recruitment bottlenecks for capacity expansions elsewhere.
- Multi-Jurisdiction Claim Alignment:Reconciling FDA qualified health claim language with EFSA Article 13.1a authorization demands parallel legal review processes that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Sterols and Esters Market |
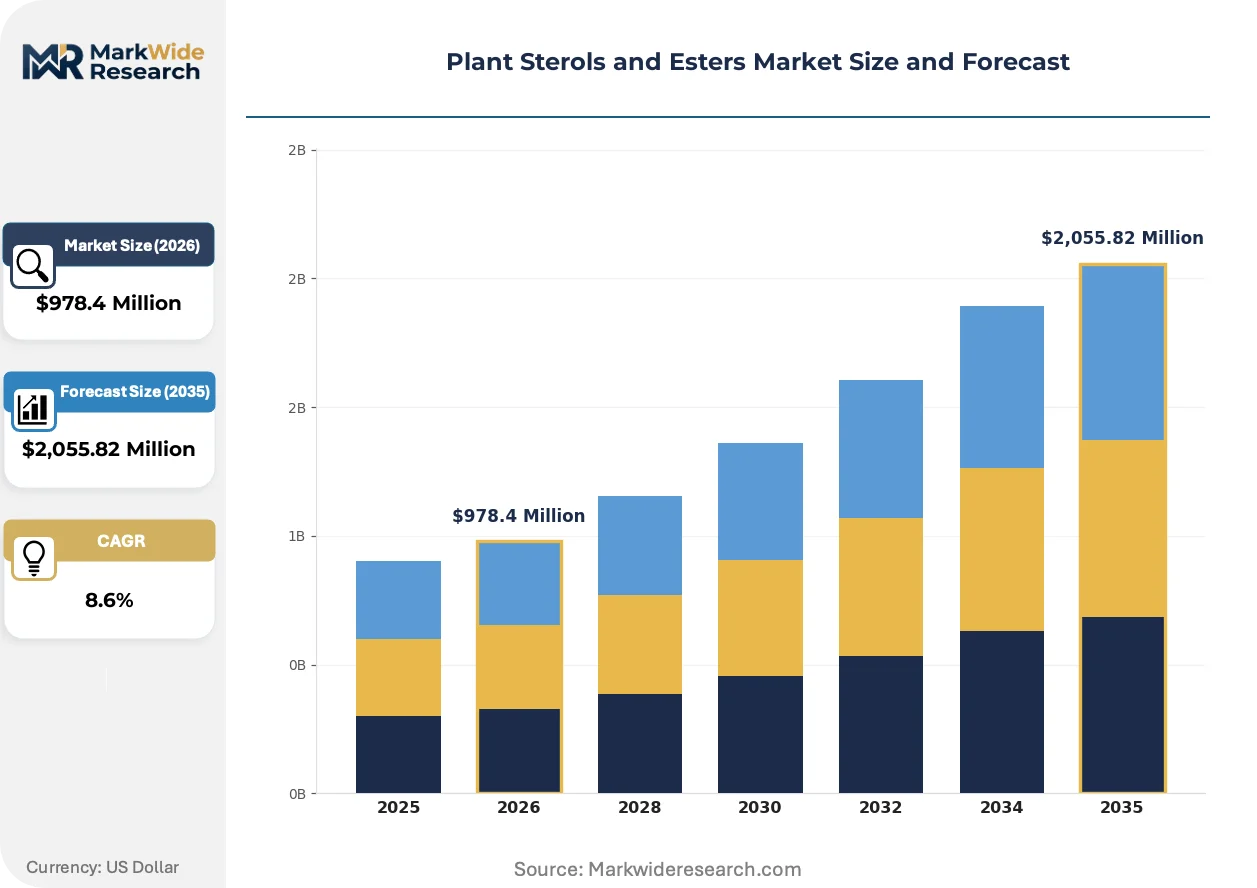
| Market Size in 2026 | $978.4 Million |
| Market Size in 2035 | $2,055.82 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Softgel Application: Functional Foods, Dietary Supplements, Beverages, Confectionery End User: Food Manufacturers, Nutraceutical Companies, Beverage Producers, Pharmaceutical Firms Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesalers, Distributors |
| Companies Covered | Raisio Plc, Enzymotech Ltd., BASF SE, DSM Nutritional Products, Bunge Limited, Cargill Incorporated, Arboris LLC, Xi’an Healthful Biotechnology Co., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Sterols and Esters Market Trends and Innovations
Technology convergence and regulatory harmonization pressures are compressing product development cycles while fragmenting competitive advantage sources across extraction, esterification, and formulation stages.
Supercritical CO2 extraction systems paired with in-line chromatographic purification are unifying food-grade and pharmaceutical-grade sterol output streams from single production assets. Nordic refiners deploy these integrated lines to serve both spreads manufacturers and prescription API contractors without batch segregation. This capability convergence is collapsing the historical quality-tier segmentation that protected premium pricing in pharmaceutical channels.
EFSA's 2023 clarification on cumulative sterol intake thresholds is tightening Article 13.1a claim substantiation requirements across EU member states. Food manufacturers must now demonstrate batch-to-batch consistency below maximum daily intake levels previously treated as guidelines. German dairy processors face the steepest compliance costs due to their concentration in multi-component fortified product lines where sterol dosing interacts with other bioactive ingredients.
Direct-to-consumer supplement channels are capturing cholesterol-conscious buyers who previously relied on physician-guided food substitution advice. Subscription-based softgel providers bypass retail pharmacy distribution entirely, capturing lifetime value through automated replenishment. This channel disintermediation is most advanced in US metropolitan markets where telehealth lipid screening has normalized self-directed management protocols.
Plant Sterols and Esters Market Segmentation
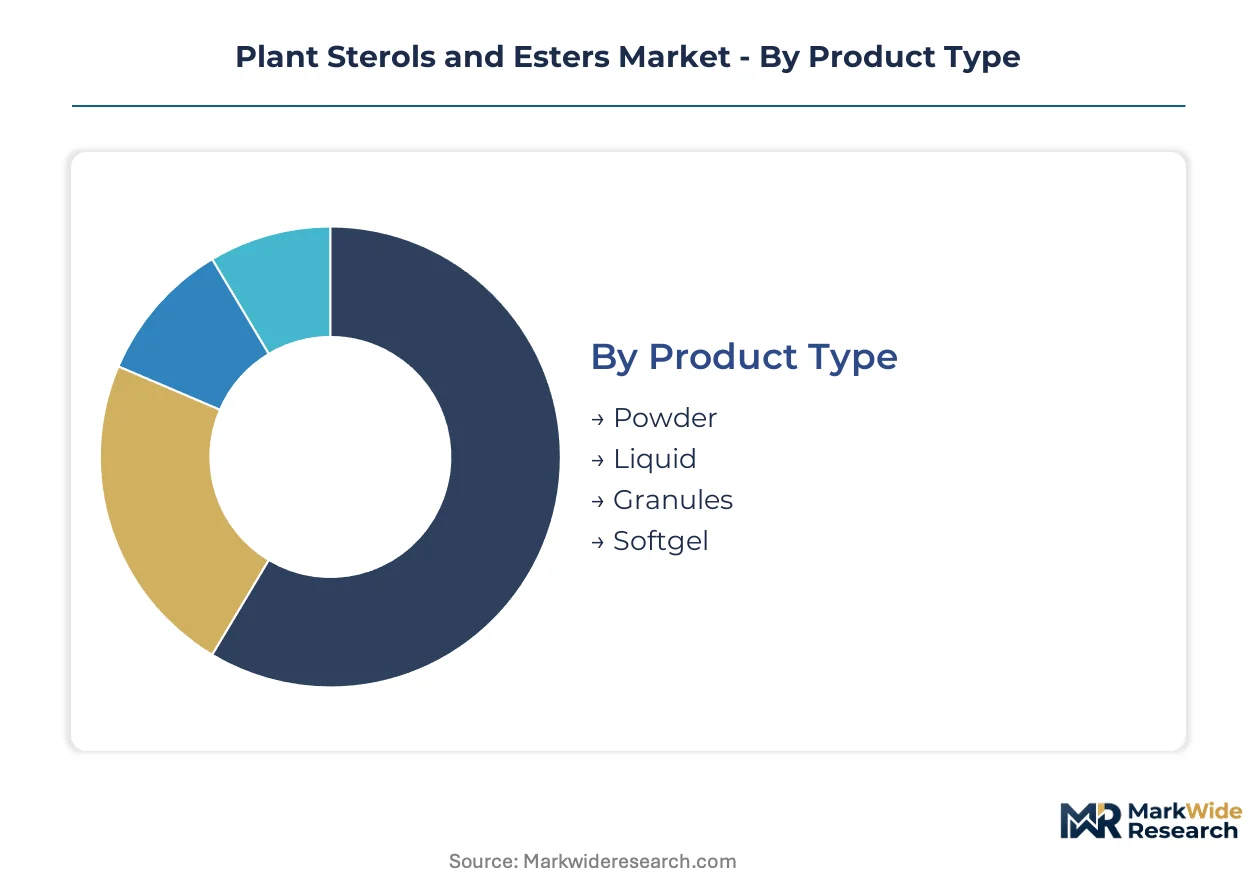
Product form and delivery channel determine regulatory pathway and margin structure in plant sterols commerce. Each segment carries distinct certification burdens from FDA qualified health claims, EFSA Article 13.1a authorization, or pharmaceutical-grade API standards.
Product Type:
FDA and EFSA authorization requirements diverge sharply across physical formats, with powder and liquid facing food-grade scrutiny while softgel triggers pharmaceutical-grade compliance.
- Powder:Free-flowing micronized sterol esters optimized for baked goods and spread matrices. German dairy processors concentrate demand here, driven by EFSA's batch-to-batch consistency mandates for multi-component fortified products.
- Liquid:Oil-dispersed sterol esters with enhanced lipid solubility for beverage fortification. Nordic refiners using supercritical CO2 extraction dominate supply, serving spreads manufacturers who require seamless oil-phase incorporation without solvent residues.
- Granules:Agglomerated particles for controlled-release supplement tablets. Nutraceutical contract manufacturers in Basel corridor favor this format for tableting efficiency.
- Softgel:Encapsulated oil concentrates for direct-to-consumer supplement channels. Telehealth lipid screening normalization in US metropolitan markets accelerates subscription-based replenishment demand.
Leading the category by volume: Powder. Growing fastest: Softgel.
Application:
End-use concentration shapes formulation stability requirements and shelf-life specifications across food, supplement, and beverage matrices.
- Functional Foods:Sterol-fortified spreads, dairy, and baked goods carrying cholesterol-reduction health claims. EFSA's cumulative intake threshold clarification tightens compliance costs for German multi-component product lines.
- Dietary Supplements:Concentrated daily intake formats outside food matrix constraints. Direct-to-consumer channels bypass retail pharmacy distribution entirely, capturing lifetime value through automated replenishment.
- Beverages:Oil-in-water emulsion systems requiring specialized homogenization. Stability challenges limit sterol loading compared to solid matrices.
- Confectionery:Fat-based delivery vehicles masking sterol taste profiles. Lower regulatory scrutiny permits experimental positioning.
Functional Foods commands the largest revenue pool. Dietary Supplements climbs the fastest.
End User:
Customer type determines pricing power and technical service intensity, with pharmaceutical firms demanding pharmaceutical-grade documentation and food manufacturers prioritizing cost efficiency.
- Food Manufacturers:Spread and dairy processors requiring EFSA-compliant formulation support. German technologists pioneer template applications accelerating EU-wide adoption.
- Nutraceutical Companies:Supplement brands sourcing concentrated actives for softgel and tablet production. Subscription commerce integration distinguishes leading buyers.
- Beverage Producers:Functional drink formulators navigating emulsion stability challenges. Smaller volume concentration limits supplier negotiation leverage.
- Pharmaceutical Firms:Prescription lipid management therapy developers sourcing API-grade sterol esters. Supercritical CO2 purification opens channels previously closed to food-grade suppliers.
Food Manufacturers anchor demand volume. Pharmaceutical Firms capture premium pricing tiers.
Distribution Channel:
Channel selection determines customer acquisition economics and regulatory documentation transfer requirements.
- Online Retail:Direct-to-consumer platforms capturing cholesterol-conscious buyers through telehealth-integrated screening protocols. Subscription mechanics optimize lifetime value.
- Brick-and-Mortar Stores:Pharmacy and mass retail requiring shelf-stable packaging and prominent health claim positioning. EFSA and FDA labeling compliance demands parallel legal review.
- Wholesalers:Volume aggregation for food service and institutional procurement. Price transparency compresses margins.
- Distributors:Regional specialists providing technical formulation support to smaller food manufacturers. Relationship depth defends position against direct sourcing.
Brick-and-Mortar Stores maintains volume leadership. Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic tall oil pitch refineries anchor European extraction capacity, while German dairy processors drive formulation innovation. India and the United States represent contrasting regulatory pathways for sterol-fortified products. China expands domestic refining to reduce import dependency.
Germany
Food technologists pioneer sterol-fortified dairy applications, creating template formulations for EU-wide adoption. EFSA Article 13.1a authorization mandates batch-to-batch consistency below cumulative intake thresholds. The Cologne-Düsseldorf corridor concentrates multi-component fortified product development where sterol dosing interacts with other bioactives.
United States
FDA qualified health claims permit coronary heart disease risk reduction messaging on qualifying spreads and dairy. Telehealth lipid screening normalizes self-directed management protocols in metropolitan markets. Chicago-area food manufacturers prioritize powder formulations for baked goods matrix stability.
India
BIS fortification standards and FSSAI labeling requirements create compliance-aligned entry points for EFSA-authorized producers. Maximum-level caps fragment formulation strategies between conventional foods and therapeutic categories. Mumbai and Ahmedabad host export-oriented manufacturers navigating strict sterol concentration ceilings.
China
Domestic supercritical CO2 extraction capacity expands to secure pharmaceutical-grade sterol supply chains. GB standards govern food additive incorporation levels in functional products. The Yangtze River Delta concentrates tall oil derivative refining investments reducing Nordic import dependency.
Finland
Crude tall oil supply from pulp mill networks exposes extractors to input cost swings when paper production cycles fluctuate. EU Green Deal sustainable feedstock certification favors producers with backward integration into certified refining. The Kotka-Hamina cluster anchors Nordic sterol extraction infrastructure serving both food and pharmaceutical channels.
Plant Sterols and Esters Market Competitive Landscape
Global majors compete with regional champions across extraction technology and feedstock access. The market structures around three tiers: integrated chemical conglomerates with tall oil refining assets, specialized nutraceutical formulators, and regional oilseed processors. Strategic moves concentrate on backward integration into certified feedstock sourcing and pharmaceutical-grade esterification capacity expansion.
Within the integrated chemical tier, BASF SE and DSM Nutritional Products exemplify divergent approaches to quality-tier segmentation. Xi'an Healthful Biotechnology Co. occupies a position among Chinese specialists expanding domestic extraction capacity. Cargill Incorporated anchors the agricultural-originated supply vector through global oilseed processing networks.
| Leading Market Players |
|---|
| Raisio Plc |
| Enzymotech Ltd. |
| BASF SE |
| DSM Nutritional Products |
| Bunge Limited |
| Cargill Incorporated |
| Arboris LLC |
| Xi'an Healthful Biotechnology Co. |
| Archer Daniels Midland Company |
| Others |
Pricing and Supply Chain Analysis
Crude tall oil pitch feedstock costs cascade through three distinct pricing tiers as Nordic pulp mill supply fluctuations transmit downstream to pharmaceutical-grade API contractors, food-grade spread manufacturers, and dietary supplement softgel producers.
Pricing Analysis
Service bundling separates pharmaceutical-grade sterol esters from commodity food-grade powders, with API contractors paying premiums for batch documentation, stability testing, and regulatory submission support that spread manufacturers rarely require. Three-tier pricing structure across pharmaceutical, food-grade, and supplement economy levels reflects certification intensity rather than sterol concentration alone. Pricing pressure stems from supercritical CO2 extraction technology convergence collapsing historical quality-tier segmentation that protected pharmaceutical margins. Food manufacturers exhibit highest price sensitivity due to reformulation cost absorption under EFSA batch-to-batch consistency mandates, while pharmaceutical firms tolerate premium positioning for prescription lipid management API supply security.
Supply Chain Analysis
Reverse-logistics flows for sterol-containing products remain minimal given food matrix incorporation and supplement consumption patterns, though pharmaceutical API contractors maintain batch recall protocols for prescription lipid management therapies. Supply concentrates in Finland, Germany, and China, with Nordic tall oil pitch refineries anchoring European extraction capacity and Yangtze River Delta facilities expanding domestic Chinese pharmaceutical-grade output. Raw material dependencies center on crude tall oil from pulp mills, vegetable oil distillates from oilseed processing, and fatty acid feedstocks for esterification. Single-source vulnerability concentrates in Nordic pulp mill networks where paper production cycles dictate crude tall oil availability. Distribution runs through regional distributors providing technical formulation support to smaller food manufacturers, with direct-to-consumer supplement channels bypassing traditional wholesale aggregation entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction paired with in-line chromatographic purification is displacing legacy solvent-based processing, compressing product development cycles while fragmenting competitive advantage sources across extraction, esterification, and formulation stages.
For Market Incumbents: Anticipate technology convergence collapsing historical quality-tier segmentation by expanding pharmaceutical-grade esterification capacity in Basel and Rotterdam corridor facilities where specialist talent concentrates. Defend margin position through backward integration into certified tall oil refining assets that satisfy EU Green Deal sustainable feedstock requirements, disadvantaging spot-market dependent competitors facing procurement cost volatility.
For New Entrants and Emerging Players: Enter via South Asian markets where BIS fortification standards and FSSAI labeling requirements create compliance-aligned entry points for manufacturers with existing EFSA-authorized production systems. Target direct-to-consumer softgel supplement channels in US metropolitan markets where telehealth lipid screening has normalized self-directed management protocols and subscription-based replenishment captures lifetime value outside retail pharmacy distribution constraints.
For Investors and Strategic Acquirers: EFSA's cumulative sterol intake threshold clarification is the leading indicator that batch-to-batch consistency compliance costs will concentrate competitive advantage among producers with integrated extraction-to-esterification capabilities. Long-term viability favors acquisition targets possessing pharmaceutical-grade lipid chemistry expertise and certified sustainable feedstock sourcing rather than pure-play food-grade powder suppliers facing margin compression from technology convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tall Oil Refining | Secures certified sustainable feedstock supply under EU Green Deal requirements. |
| Pharmaceutical-Grade Esterification Capacity Expansion | Opens prescription lipid management API channels previously closed to food-grade suppliers. |
| Direct-to-Consumer Softgel Channel Development | Bypasses retail pharmacy distribution through telehealth-integrated subscription mechanics. |
| Multi-Jurisdiction Claim Alignment Investment | Reconciles FDA qualified health claims with EFSA Article 13.1a authorization for accelerated product launches. |
| Supercritical CO2 Extraction Technology Deployment | Unifies food-grade and pharmaceutical-grade output streams from single production assets. |
Research Methodology
Independent corroboration across primary interviews with extraction technology directors, food formulation technologists, pharmaceutical API procurement managers, and regulatory affairs specialists, combined with secondary validation through EFSA health claims registers, FDA qualified health claim notifications, BIS fortification standards documentation, and customs trade data, underwrites the qualitative findings. Bottom-up demand modeling from end-use consumption patterns and top-down supply capacity assessments from tall oil refining and oilseed processing infrastructure were cross-referenced to establish market sizing.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product form, application matrix, end-user pricing tier, and distribution channel regulatory pathway. CAGRs were derived from modeled adoption curves for supercritical CO2 extraction technology, EFSA compliance cost absorption patterns, and telehealth-integrated supplement channel penetration in metropolitan markets. Forecast inputs incorporated tall oil pitch supply volatility indices and pharmaceutical-grade certification timeline distributions.
Revisions become necessary when EFSA cumulative intake threshold enforcement intensifies, FDA qualified health claim language shifts, or Nordic pulp mill production cycles disrupt crude tall oil supply. Practitioners should monitor regulatory submission backlog durations, certified sustainable feedstock premium spreads, and direct-to-consumer supplement subscription cancellation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Terminalia Extract Market
Ingredients
Revivable Yeast Market
Ingredients
Fluid Lecithin Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Global Pulse Flours Market
Ingredients
Vegetable Powder Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Homecare Ingredients Market
Ingredients
Corn Starch Market
Ingredients
Vegetable Extract Market
Ingredients
Baobab Ingredient Market
Ingredients
Chewing Gum Base Market
Ingredients
Energy Ingredients Market
Ingredients
Middle East and Africa Pea Starch Market