
 Food Grade L-Arabinose Market | 2026-2036
Food Grade L-Arabinose Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade L-Arabinose Market Insights
Chinese fine-chemical producers is expanding crystallization capacity for food-grade rare sugars. Hunan Huachang Chemical leverages backward integration into corncob feedstock to secure raw material cost stability. Healtang Biotech anchors its position through continuous fermentation technology for L-arabinose isolation. BioCare Copenhagen differentiates via pharmaceutical-grade certification pathways that extend into European nutraceutical channels.
Food grade L-arabinose is a pentose monosaccharide extracted primarily from agricultural residues such as corn husks and sugar beet pulp, functioning as a low-calorie sweetener with demonstrated sucrose suppression properties and prebiotic activity. Powder formulations dominate current volume shipments due to stability in dry-blend manufacturing, while solution grades capture expanding demand from ready-to-drink beverage developers seeking liquid-phase integration. Nutraceutical applications represent the fastest-growing segment as dietary supplement producers reformulate glycemic control products, whereas food and beverage end-use maintains the largest absolute margin pool through established bakery and confectionery relationships.
FDA GRAS status and EFSA novel food evaluations shape ingredient approval timelines for L-arabinose incorporation across jurisdictions, with China's SAMR enforcing updated GB 1886 food additive purity standards that filter subscale producers. ISO 22000 and FSSC 22000 certifications now function as baseline qualification criteria for supplier selection by multinational food manufacturers. Stakeholders must monitor evolving glycemic health claims regulation and fermentation yield improvements to capture positioning in functional ingredient procurement decisions.
Market Dynamics
Continuous fermentation technology is compressing production costs for food-grade rare sugars while GB 1886 purity standards are filtering subscale Chinese suppliers from contract manufacturer qualification lists.
Growth Catalysts
- Prebiotic formulation demand:Dietary supplement producers in North America are reformulating glycemic control portfolios around sucrose suppression claims. FDA GRAS status accelerates inclusion timelines.
- Corncob residue valorization:Agricultural waste streams from corn processing regions are securing feedstock cost stability for crystallization capacity expansions.
- EFSA novel food pathways:European nutraceutical channels are opening to L-arabinose through pharmaceutical-grade certification extensions that differentiate supplier positioning.
Market Restraints
- Input cost volatility:Corn husk and sugar beet pulp prices fluctuate with agricultural commodity cycles, squeezing margin predictability for crystallization operators.
- Supply concentration risk:Chinese fine-chemical producers dominate crystallization capacity, creating single-geography dependency for multinational food manufacturers.
- Technical substitution threat:Allulose and other rare sugars offer comparable low-glycemic profiles, fragmenting sweetener procurement budgets.
Strategic Opportunities
- Beverage liquid-phase integration:Ready-to-drink developers are demanding solution grades that bypass dry-blend reconstitution steps.
- India FSSAI approval runway:Functional ingredient registration pathways remain underpenetrated relative to formulation activity in dietary supplement clusters.
- ISO 22000 baseline elevation:Certification inflation is creating tiered supplier segmentation that rewards early FSSC 22000 adopters with multinational access.
Industry Challenges
- Fermentation yield optimization:Continuous isolation processes require specialized biochemical engineering talent scarce in traditional sugar processing regions.
- Dual certification timelines:Simultaneous FDA GRAS maintenance and EFSA novel food evaluation stretches regulatory affairs capacity at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade L-Arabinose Market |
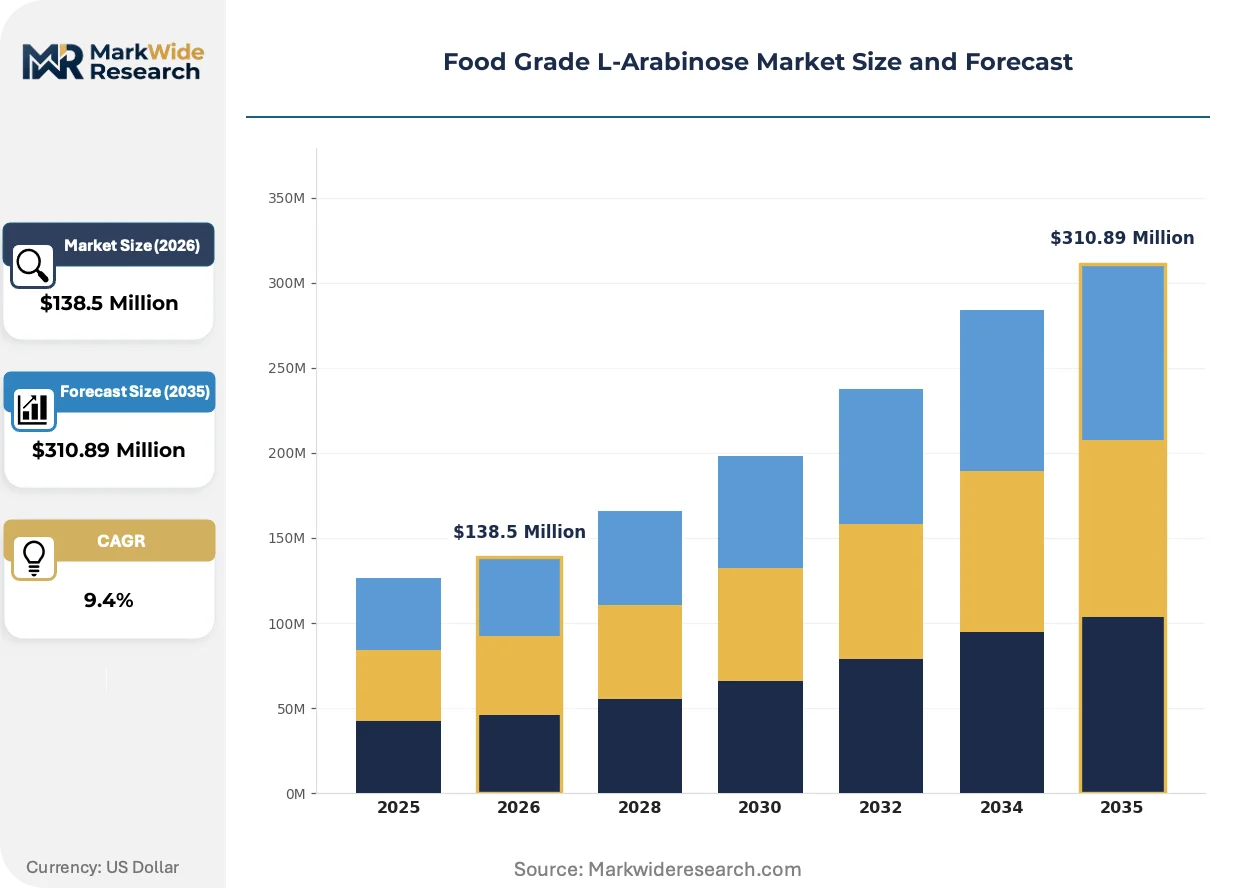
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $310.89 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Crystals Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics End User: Food Manufacturers, Beverage Companies, Dietary Supplement Producers, Cosmetic Brands Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | DuPont de Nemours, Inc., Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Cargill, Incorporated, Hunan Huachang Chemical Co., Ltd., BioCare Copenhagen, Healtang Biotech Co., Ltd., Futaste Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade L-Arabinose Market Trends and Innovations
Bioprocess intensification and regulatory certification inflation are restructuring how rare sugar suppliers qualify for multinational procurement lists.
Continuous fermentation technology is expanding into food-grade L-arabinose isolation from batch crystallization methods. Beverage formulators seeking liquid-phase integration are accelerating adoption of solution-grade outputs. This shift is compressing dry-blend powder margins while rewarding producers with integrated fermentation-to-filtration capabilities.
China's SAMR enforcement of updated GB 1886 food additive purity standards is disqualifying subscale extraction operators from contract manufacturer supply bases. Multinational food manufacturers are now requiring ISO 22000 and FSSC 22000 certifications as baseline qualification criteria. The tightening is concentrating supplier relationships around backward-integrated corncob processors with in-house analytical capabilities.
Certification-driven procurement preferences are displacing price-first supplier selection in North American dietary supplement manufacturing. Contract manufacturers are consolidating ingredient sourcing around dual-certified rare sugar suppliers capable of supporting glycemic health claims documentation. This behavioral shift is most visible in Utah and California nutraceutical clusters where FDA inspection frequency has intensified.
Food Grade L-Arabinose Market Segmentation
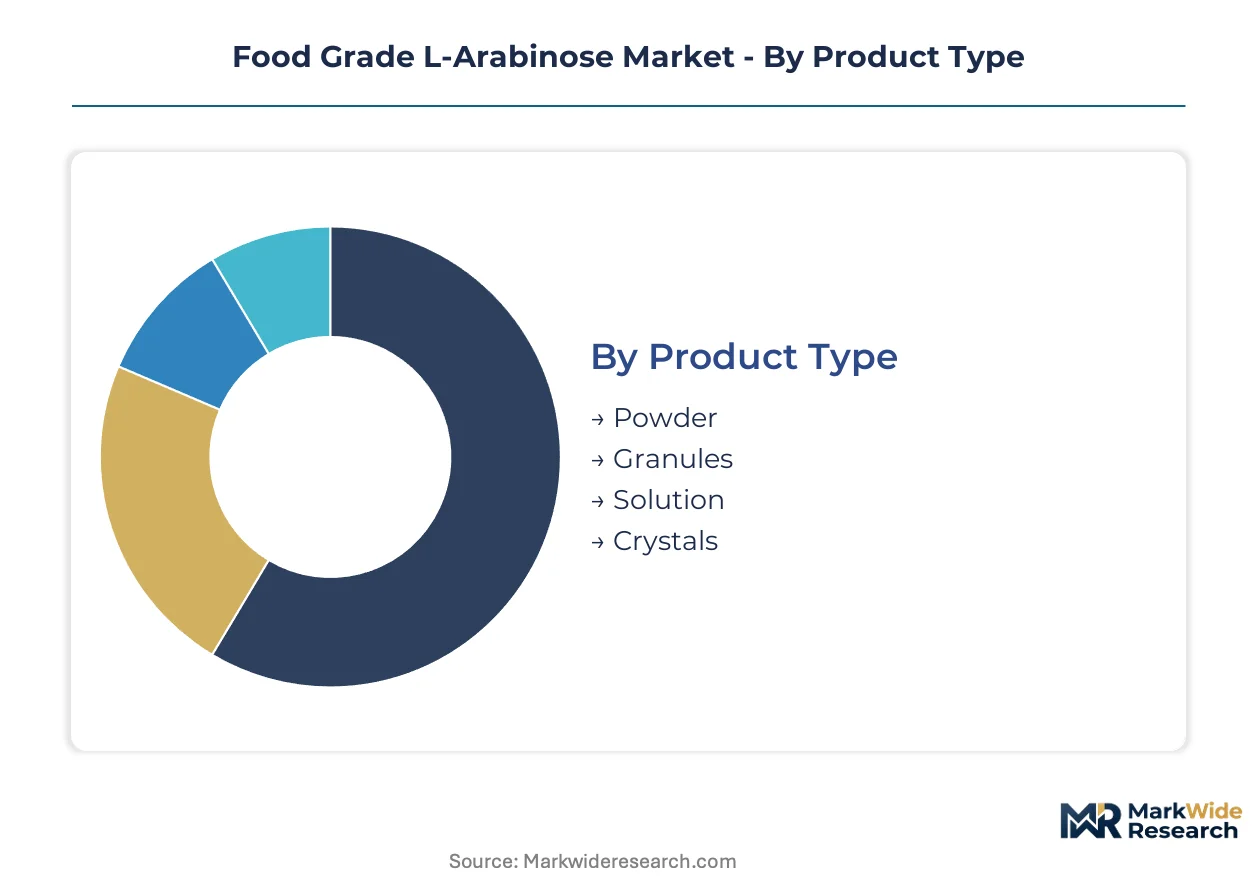
Segmentation in food-grade L-arabinose procurement reflects divergent certification burdens across physical forms and end-use channels. Powder and solution grades face distinct regulatory pathways, while nutraceutical applications demand pharmaceutical-grade documentation absent from standard food additive tiers.
Product Type:
Powder formulations carry baseline FDA GRAS documentation, whereas solution grades trigger additional stability testing and novel food evaluations in European jurisdictions.
- Powder:Dry-blend stable with extended shelf life under ambient storage. Food manufacturers in Utah and California nutraceutical clusters specify this grade for glycemic control supplement manufacturing where moisture sensitivity threatens active ingredient integrity.
- Solution:Liquid-phase integration bypasses reconstitution steps in ready-to-drink beverage development. Ready-to-drink developers in Copenhagen and Shanghai are accelerating procurement of this grade as continuous fermentation technology compresses liquid-phase production costs.
- Granules:Intermediate flow properties for tablet compression operations.
- Crystals:Highest purity tier for pharmaceutical-grade certification pathways.
Leading the category by volume: Powder. Growing fastest: Solution.
Application:
Application segments stratify by documentation intensity, with nutraceutical and pharmaceutical tiers requiring batch-specific certificates of analysis that food and beverage procurement rarely demands.
- Food & Beverage:Established bakery and confectionery relationships generate the largest absolute margin pool. FDA GRAS status accelerates inclusion timelines for sucrose suppression claims in US-manufactured products.
- Nutraceuticals:Dietary supplement producers reformulate glycemic control portfolios around prebiotic positioning. EFSA novel food evaluations stretch regulatory affairs capacity at mid-scale producers seeking European market entry.
- Pharmaceuticals:Demands pharmaceutical-grade certification with extended purity documentation.
- Cosmetics:Emerging application in microbiome-focused topical formulations.
Dominating procurement volume: Food & Beverage. Expanding most quickly: Nutraceuticals.
End User:
End user categories separate by technical specification depth, with dietary supplement producers imposing the most stringent analytical requirements on supplier qualification.
- Dietary Supplement Producers:Contract manufacturers consolidate sourcing around dual-certified rare sugar suppliers capable of supporting glycemic health claims documentation. ISO 22000 and FSSC 22000 certifications function as baseline qualification criteria.
- Beverage Companies:Formulation pipelines are expanding with low-glycemic sweeteners as solution-grade outputs enable liquid-phase integration without dry-blend reconstitution.
- Food Manufacturers:Procurement decisions prioritize cost stability from backward-integrated corncob processors.
- Cosmetic Brands:Emerging demand segment with microbiome positioning requirements.
Category volume leader: Food Manufacturers. Steepest expansion trajectory: Dietary Supplement Producers.
Distribution Channel:
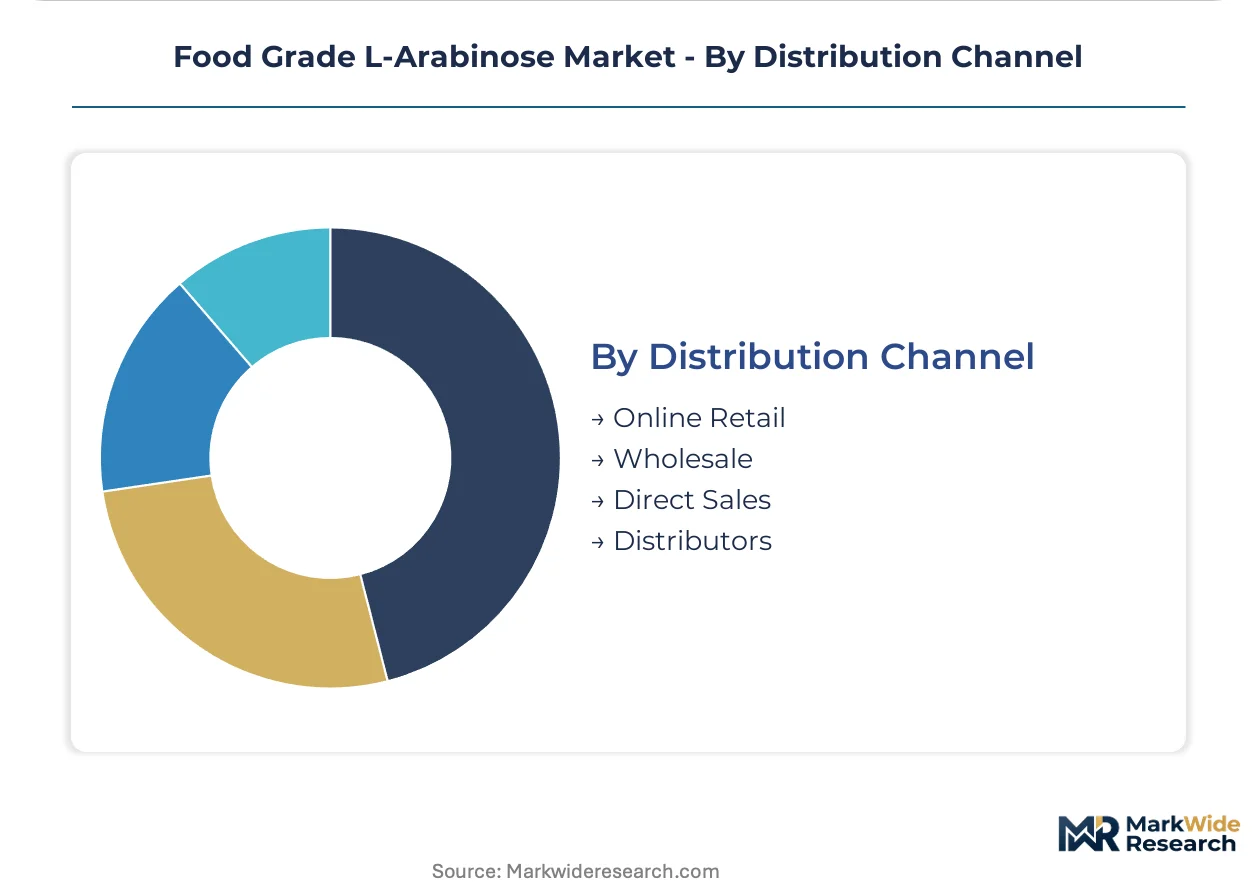
Channel selection reflects order scale and technical service requirements, with direct sales commanding specification-intensive nutraceutical accounts.
- Direct Sales:Multinational food manufacturers require in-house analytical capabilities and dedicated regulatory support. Relationships concentrate around Hunan and Shandong crystallization operators with backward-integrated corncob feedstock control.
- Distributors:Regional inventory positioning serves mid-scale beverage developers seeking shorter lead times than Chinese direct shipment allows.
- Wholesale:Volume aggregation for standard-grade powder procurement.
- Online Retail:Small-lot accessibility for cosmetic and research applications.
Volume concentration: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corncob feedstock availability in Shandong and Hunan provinces anchors crystallization capacity expansion for food-grade rare sugar isolation. Agricultural residue valorization programs in these regions secure cost-stable extraction economics against commodity volatility.
China
Dietary supplement contract manufacturers in Shandong and Hunan provinces drive powder-grade procurement volumes for glycemic control formulations. SAMR enforcement of updated GB 1886 food additive purity standards filters subscale extraction operators from multinational supply bases. Zhengzhou and Jinan industrial clusters concentrate continuous fermentation technology deployment for L-arabinose isolation.
United States
Utah and California nutraceutical clusters reformulate prebiotic portfolios around sucrose suppression claims with FDA GRAS documentation. FDA inspection frequency intensification pushes contract manufacturers toward dual-certified rare sugar suppliers. Salt Lake City dietary supplement producers consolidate sourcing around ISO 22000 and FSSC 22000 qualified crystallization operators.
Denmark
Copenhagen-based nutraceutical channels open to L-arabinose through pharmaceutical-grade certification extensions into European markets. EFSA novel food evaluation pathways stretch regulatory affairs capacity for mid-scale producers seeking market entry. Danish ingredient distributors anchor Nordic supply relationships with analytical capability requirements.
India
Dietary supplement clusters in Maharashtra and Gujarat await FSSAI functional ingredient registration pathway clarity for glycemic control product launches. FSSAI approval runway remains underpenetrated relative to formulation activity in domestic nutraceutical manufacturing. Mumbai and Ahmedabad contract manufacturers position for rare sugar inclusion pending regulatory timeline confirmation.
Germany
Bakery and confectionery manufacturers in Bavaria and North Rhine-Westphalia evaluate low-calorie sweetener alternatives for sucrose reduction claims. EFSA novel food status requirements shape ingredient approval timelines for L-arabinose incorporation. Munich industrial food technology clusters test liquid-phase integration of solution-grade outputs in ready-to-drink development pipelines.
Food Grade L-Arabinose Market Competitive Landscape
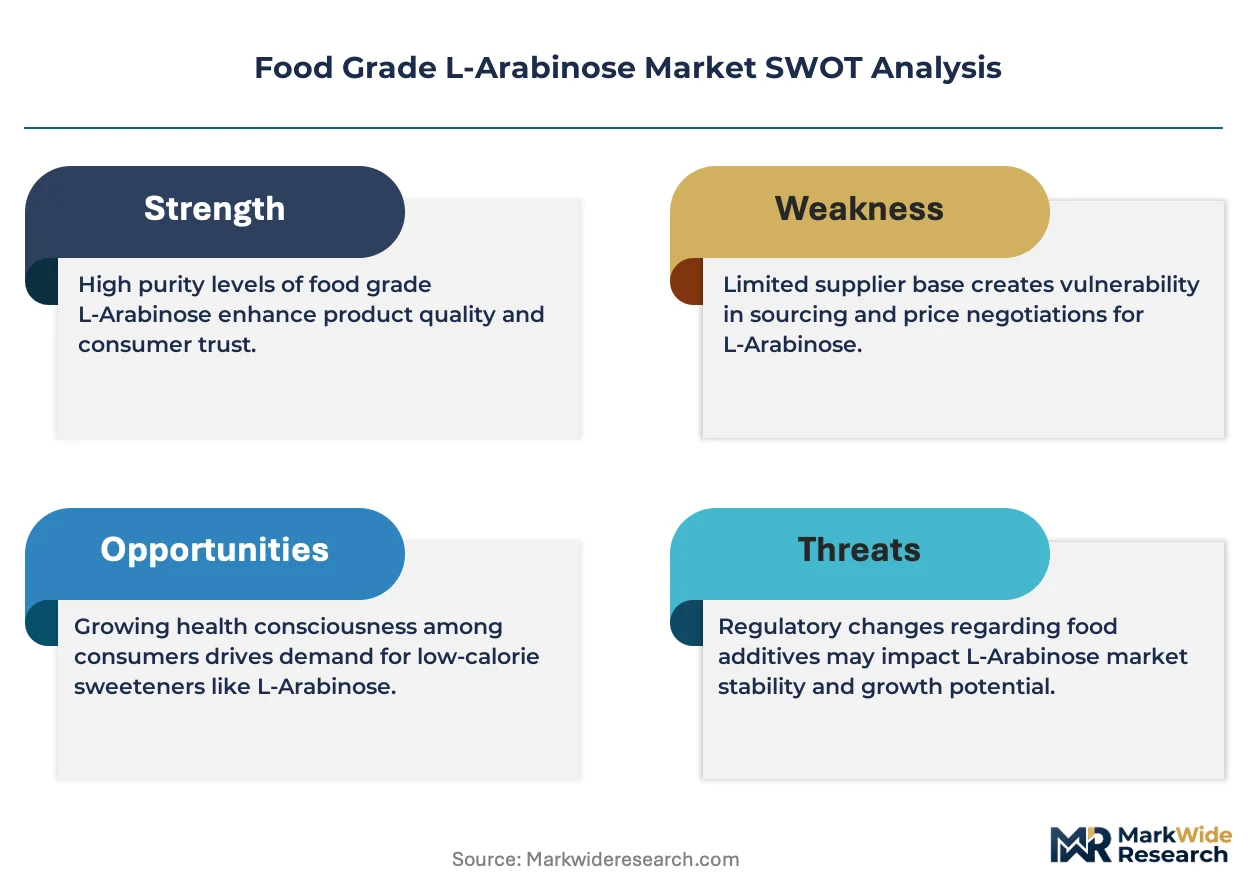
Global majors compete with regional champions across certification and feedstock integration dimensions. The supplier base concentrates around backward-integrated Chinese crystallization operators and European pharmaceutical-grade certifiers. Three archetypes dominate: corncob-integrated feedstock controllers, fermentation technology specialists, and dual-certified quality tier suppliers. Capacity expansion and certification inflation represent the dominant competitive moves reshaping procurement relationships.
Within the feedstock-integrated tier, Hunan Huachang Chemical Co., Ltd. and Healtang Biotech Co., Ltd. exemplify Chinese producers leveraging Shandong and Hunan agricultural residue access. BioCare Copenhagen occupies a position among European pharmaceutical-grade certifiers extending into nutraceutical channels. These three entities represent the geographic and certification segmentation structuring multinational supplier qualification.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Hunan Huachang Chemical Co., Ltd. |
| BioCare Copenhagen |
| Healtang Biotech Co., Ltd. |
| Futaste Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into corncob feedstock anchors both supply security and pricing power for crystallization operators in Shandong and Hunan provinces. Hunan Huachang Chemical and Healtang Biotech leverage captive agricultural residue streams to buffer margin compression from commodity volatility while commanding premium positioning through FSSC 22000 certification.
Pricing Analysis
Service bundling separates pharmaceutical-grade certification support from standard-grade powder transactions. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-additive levels reflects documentation intensity and regulatory liability. Pharmaceutical-grade tiers absorb stability testing and batch-specific analytical costs that standard food-grade procurement avoids. Pricing pressure stems from continuous fermentation yield improvements compressing liquid-phase production economics. Dietary supplement contract manufacturers in Utah and California clusters exhibit highest price sensitivity, whereas European nutraceutical channels accepting EFSA novel food pathways show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese crystallization capacity concentration in Shandong and Hunan provinces. Raw material flows draw from corncob residue streams and sugar beet pulp, with enzymatic extraction reagents and fermentation biocatalysts as critical process inputs. Tariff exposure threatens cost stability for North American contract manufacturers dependent on direct shipment from Zhengzhou and Jinan industrial clusters. Distribution runs through direct sales relationships for multinational food manufacturers requiring dedicated regulatory support, with regional distributors serving mid-scale beverage developers in Copenhagen and Shanghai seeking shorter lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous fermentation technology is displacing batch crystallization as the dominant isolation methodology, compressing production economics and recalibrating supplier qualification thresholds across procurement hierarchies.
For Market Incumbents: Deepen backward integration into agricultural residue streams to secure feedstock cost stability against commodity cycles. Expand crystallization capacity in corncob-processing regions with SAMR-aligned analytical capabilities. Allulose substitution threats and GB 1886 purity standard enforcement demand defensive certification investments in dual FDA-EFSA documentation pathways. For New Entrants and Emerging Players: Beverage companies seeking liquid-phase integration represent the most penetrable buyer archetype underserved by incumbent powder-grade specialization. Target solution-grade procurement in ready-to-drink development pipelines across Copenhagen and Shanghai clusters. India FSSAI registration runway offers geographic white space pending regulatory timeline confirmation. Lead with fermentation-to-filtration technical service capabilities rather than price competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global ingredient majors seeking rare sugar platform expansion. Five-to-ten year viability hinges on glycemic health claims regulatory clarity and prebiotic positioning durability. Target crystallization operators with backward-integrated feedstock control and existing dual-certification infrastructure. Fermentation yield improvement announcements from Healtang Biotech and Hunan Huachang Chemical signal inflection timing for capacity valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Healtang Biotech's technology deployment compresses liquid-phase production costs for beverage integration. |
| Backward Integration into Corncob Feedstock | Hunan Huachang Chemical secures raw material cost stability through captive agricultural residue streams. |
| Dual Certification Investment | FSSC 22000 and FDA GRAS documentation opens multinational food manufacturer procurement lists. |
| Pharmaceutical-Grade Certification Extension | BioCare Copenhagen's EFSA novel food pathway differentiation captures European nutraceutical channel premiums. |
| Solution-Grade Product Line Expansion | Liquid-phase outputs bypass dry-blend reconstitution for ready-to-drink beverage developers in Shanghai. |
Research Methodology
Independent corroboration across fermentation technology specialists, dietary supplement contract manufacturers, and food-grade chemical distributors underwrites the qualitative findings. Primary interviews engaged plant managers at Shandong and Hunan crystallization facilities, procurement leads at Utah and California nutraceutical clusters, and regulatory affairs directors navigating SAMR GB 1886 enforcement. Secondary validation drew from SAMR food additive filings, EFSA novel food evaluation registers, FSSC 22000 certification databases, and customs trade data for rare sugar imports. Bottom-up capacity assessments and top-down end-use demand estimation triangulate volume and value outputs.
Comparable-period anchoring to historical crystallization capacity deployment and fermentation yield improvement curves structured the projection horizon. Segmentation modeling spanned physical form, application tier, end-user category, and regional regulatory cluster. CAGRs derived from capacity expansion announcements, certification timeline analysis, and substitution elasticity estimates for allulose and other rare sugars. Glycemic health claims regulatory progression and prebiotic formulation adoption rates in North American dietary supplement manufacturing served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel food evaluation timelines, FSSAI functional ingredient registration clarity, and continuous fermentation technology diffusion rates. Forecasts reflect documented assumptions on certification inflation and feedstock cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Caramel Malt Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Microencapsulated Oil Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Fucoidan Extract Market
Ingredients
Plant Protein Ingredients Market
Ingredients
South America Spirulina Extract Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
Specialty Malt Market
Ingredients
Dark Yeast Extract Market
Ingredients
Yeast Peptide Market
Ingredients
Fruit Pectin Market
Ingredients
Carotenoids Market
Ingredients
Avocado Oil Market