
 Hydrolyzed Vegetable Protein Market | 2026-2036
Hydrolyzed Vegetable Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Vegetable Protein Market Analysis
REACH compliance is hardening the cost-of-entry calculus for hydrolyzed vegetable protein suppliers seeking European market access. Cargill, Incorporated leverages its backward integration into oilseed processing to control raw material quality and cost structures. Kerry Group plc anchors its position through flavor-house relationships that bundle HVP into savory systems for food manufacturers. Tate & Lyle PLC competes on enzymatic hydrolysis expertise that yields cleaner-tasting protein fractions for premium applications.
Hydrolyzed vegetable protein refers to plant-derived proteins—typically from soy, wheat, or corn—that undergo acid or enzymatic hydrolysis to break peptide bonds into smaller amino acid chains and peptides, producing a savory, umami-rich ingredient with molecular weights generally below 10 kDa. The process liberates free glutamic acid and other taste-active compounds, making HVP a functional flavor enhancer and partial sodium replacer in processed foods, animal feeds, and pharmaceutical formulations. Powder formats dominate current production volumes due to superior shelf stability and ease of dry-blending into seasoning matrices, while liquid concentrates capture expanding demand from ready-to-eat soup and sauce manufacturers seeking streamlined production workflows. Food and beverage applications absorb the majority of value, though dietary supplements represent the fastest-growing structural segment as sports nutrition brands reformulate with plant-derived amino acid sources.
EFSA evaluates hydrolyzed protein safety under Novel Food and food additive frameworks, while FDA regulates HVP through GRAS notifications and allergen labeling mandates for wheat and soy sources. China's SAMR enforces GB standards for hydrolyzed plant protein used in condiments and processed foods, creating a multi-jurisdictional compliance burden for international suppliers. Stakeholders must monitor evolving enzyme approval lists and allergen threshold regulations, as these will determine which hydrolysis technologies and source crops gain commercial traction across major demand centers.
Market Dynamics
Precision fermentation infrastructure is consolidating savory ingredient supply chains, enabling manufacturers to bypass traditional acid hydrolysis and achieve cleaner-label protein fractions that meet tightening EFSA additive specifications.
Growth Catalysts
- Plant-based meat analogue demand:Food manufacturers reformulate analogues with HVP to replicate umami depth without synthetic additives, pulling volume from traditional flavor houses.
- REACH compliance differentiation:Suppliers investing in enzymatic hydrolysis pathways secure preferential access to German and Dutch processed food clusters where additive scrutiny is intensifying.
- Sports nutrition amino acid sourcing:Dietary supplement brands substitute whey-derived peptides with hydrolyzed soy and wheat proteins to serve vegan-positioned product lines.
Market Restraints
- Input cost volatility:Soy and wheat protein concentrate prices fluctuate with commodity grain futures, compressing margin stability for non-integrated processors.
- Supply concentration risk:Enzyme supply for hydrolysis concentrates among Danish and Dutch specialty chemical producers, creating single-source vulnerability.
- Regulatory friction:FDA allergen labeling mandates for wheat and soy sources force dual-SKU production runs, inflating operational complexity.
Strategic Opportunities
- Precision fermentation scale-up:Biotech-enabled protein hydrolysate production bypasses crop dependency and achieves batch-to-batch consistency for pharmaceutical-grade applications.
- Clean-label condiment penetration:Sauce manufacturers in France and Italy reformulate with enzymatic HVP to eliminate E-number additives from premium product lines.
- Cell-culture media supplementation:Biopharma contract manufacturers adopt plant-derived peptide hydrolysates as serum replacements in fermentation processes.
Industry Challenges
- Enzymologist talent scarcity:Food-grade protease optimization requires rare cross-training in flavor chemistry and bioprocess engineering.
- Multi-jurisdictional dossier compilation:Novel Food approvals through EFSA demand 18-24 month timelines with no guarantee of positive opinions.
- Legacy acid hydrolysis asset stranding:Capital-intensive reactor fleets face accelerated obsolescence as enzymatic methods achieve cost parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Vegetable Protein Market |
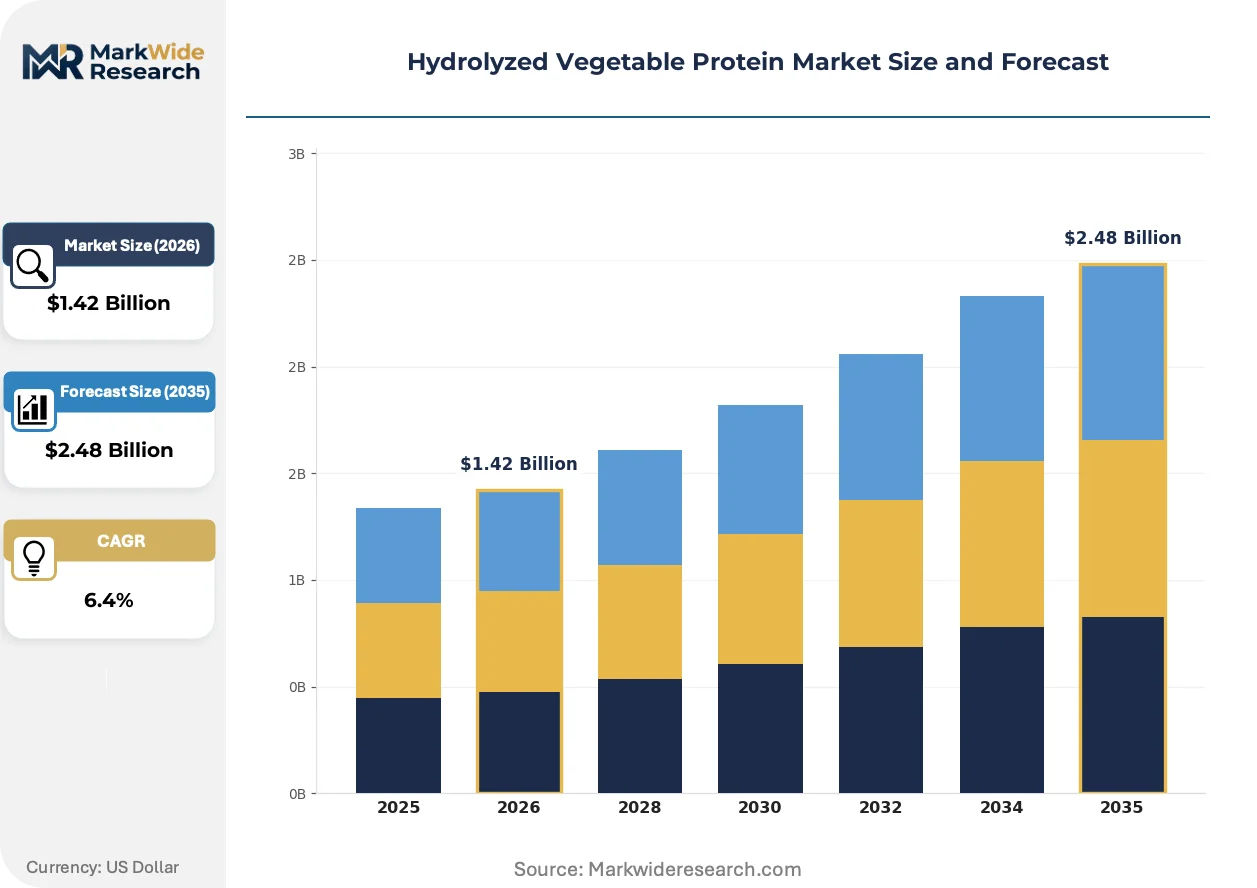
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Concentrate Application: Food & Beverage, Animal Feed, Dietary Supplements, Pharmaceuticals End User: Food Manufacturers, Nutraceutical Companies, Veterinary Clinics, Hospitals Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Tate & Lyle PLC, Kerry Group plc, Givaudan SA, Roquette Frères, Ajinomoto Co., Inc., Sensient Technologies Corporation, Titan Biotech, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Vegetable Protein Market Emerging Trajectories
Bioprocessing innovation is compressing the cost curve for enzymatic hydrolysis, enabling broader substitution of acid-catalyzed methods that dominate legacy production footprints.
Enzymatic hydrolysis is consolidating quality-tier differentiation in savory ingredients. Specialty proteases from Bacillus subtilis and Aspergillus oryzae achieve targeted peptide cleavage without Maillard-related off-notes. Premium soup and sauce manufacturers in Germany and Switzerland are adopting these inputs to eliminate "hydrolyzed protein" from ingredient declarations. The technology is consolidating market share among suppliers with captive enzyme development capabilities.
EFSA's 2023 updated guidance on food additive safety assessments is tightening specifications for 3-MCPD and glycidyl ester contaminants in acid-hydrolyzed proteins. Manufacturers must demonstrate sub-ppm thresholds through validated analytical methods. The regulatory pressure is accelerating capital redeployment toward enzymatic production lines, particularly among suppliers serving infant nutrition and clinical food segments where contaminant limits are most stringent.
Direct procurement relationships between hydrolyzed protein suppliers and plant-based meat startups are displacing traditional flavor-house intermediation. These arrangements specify custom peptide molecular weight distributions and glutamic acid liberation rates. The channel shift is most visible in California and Netherlands food technology clusters, where venture-backed alternative protein companies negotiate exclusive supply agreements for differentiated savory building blocks.
Hydrolyzed Vegetable Protein Market Segmentation
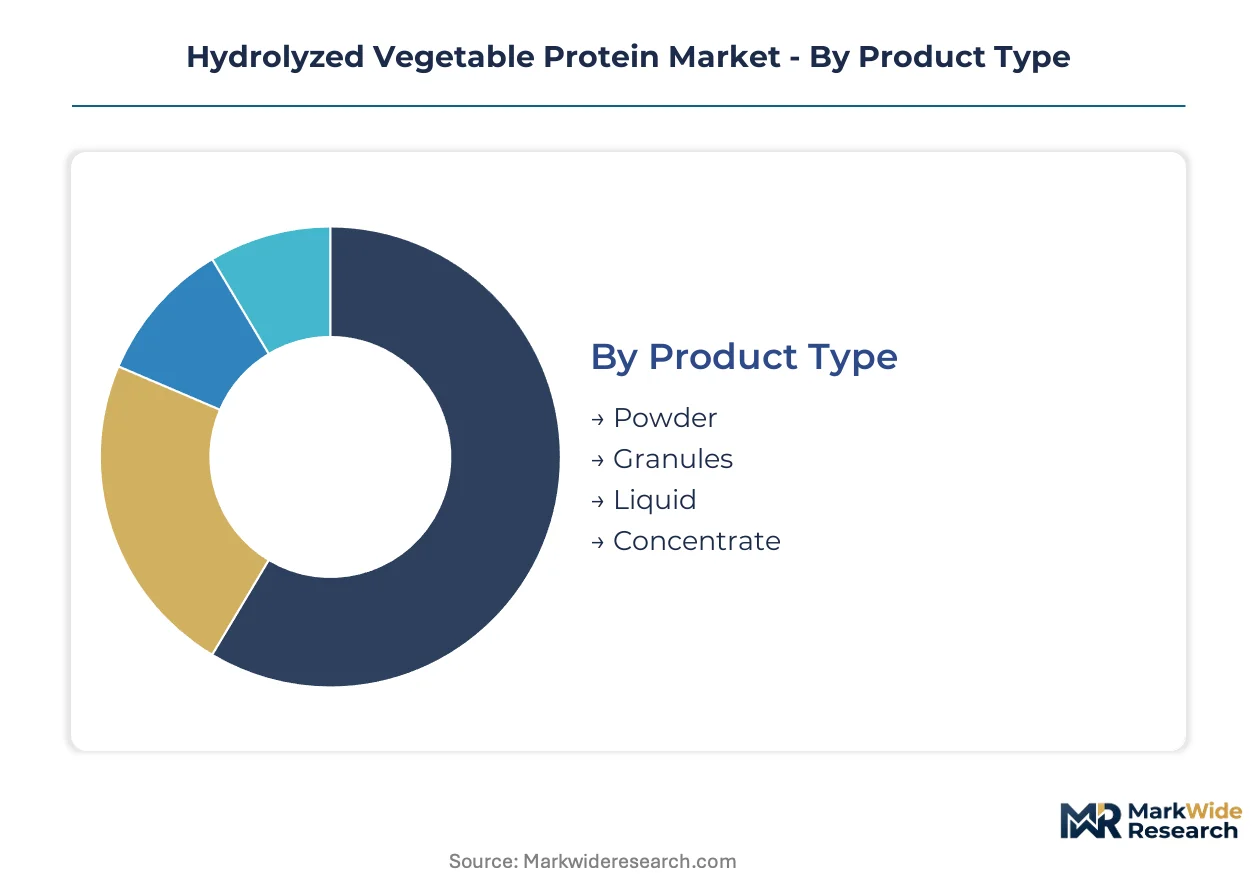
Segmentation in hydrolyzed vegetable protein reveals how capital deployment, regulatory exposure, and customer procurement sophistication vary across product formats and channel structures. Manufacturers optimize reactor configurations and enzyme selections differently depending on which segment anchors their revenue base.
Product Type:
Capital intensity diverges sharply across physical formats, with spray-drying infrastructure for powders demanding the heaviest upfront investment versus liquid handling systems that leverage existing tankage.
- Powder:Spray-dried fractions below 10 kDa molecular weight deliver superior shelf stability and blend seamlessly into dry seasoning matrices. German soup manufacturers and Dutch savory compounders absorb the majority of powder volume, driven by EFSA-compliant clean-label mandates that favor enzymatic over acid-hydrolyzed inputs.
- Liquid:Concentrated aqueous solutions enable streamlined incorporation into ready-to-eat sauces and broths without rehydration steps. French and Italian condiment producers are expanding liquid procurement to eliminate E-number additives from premium product lines, though cold-chain logistics inflate landed costs.
- Granules:Agglomerated particles bridge solubility and handling characteristics for mid-tier seasoning applications. Animal feed compounders in Denmark and Spain favor this format for uniform dispersion in pelleted rations.
- Concentrate:High-solids extracts serve pharmaceutical-grade peptide requirements and cell-culture media supplementation. Biopharma contract manufacturers in Switzerland and Massachusetts negotiate custom molecular weight specifications for serum replacement applications.
Most installed capacity flows through Powder. Expansion is steepest in Liquid.
Application:
Margin profiles stratify by end-use, with pharmaceutical and dietary supplement applications commanding premium pricing over commodity food volumes.
- Food & Beverage:Umami enhancement and sodium reduction in processed soups, sauces, and savory snacks constitute the foundational demand base. Plant-based meat analogue startups in California and the Netherlands are pulling volume directly from hydrolyzed protein suppliers, bypassing traditional flavor-house intermediation.
- Dietary Supplements:Free amino acid profiles from enzymatic hydrolysis serve vegan-positioned sports nutrition brands. German and UK supplement formulators are substituting whey-derived peptides with hydrolyzed soy and wheat proteins to capture flexitarian consumers.
- Animal Feed:Palatability enhancement and protein fortification in pet food and livestock rations. Spanish and Italian feed compounders integrate HVP into premium pet nutrition lines as grain-free formulations proliferate.
- Pharmaceuticals:Peptide hydrolysates function as culture media components and clinical nutrition inputs. Swiss and German biopharma manufacturers specify sub-ppm contaminant thresholds that only enzymatic production methods can reliably achieve.
Food & Beverage retains the dominant revenue share. Dietary Supplements is climbing the fastest.
End User:
Procurement sophistication determines supplier relationship structures, with direct technical partnerships replacing transactional spot purchasing among the most advanced buyers.
- Food Manufacturers:Integrated savory systems procurement from Cargill, Kerry, and Tate & Lyle dominates at scale. German processed food clusters leverage backward integration into oilseed processing to secure cost-advantaged HVP supply.
- Nutraceutical Companies:Specification-driven sourcing of amino acid profiles and peptide molecular weight distributions. UK and Scandinavian brands demand third-party verification of enzymatic hydrolysis methods for clean-label positioning.
- Veterinary Clinics:Specialized clinical nutrition and recovery formulations for companion animals. French and Italian veterinary channels show expanding interest in hydrolyzed protein for hypoallergenic pet diets.
- Hospitals:Enteral and parenteral nutrition applications requiring pharmaceutical-grade peptide fractions. German and Swiss clinical nutrition suppliers enforce the most stringent batch-to-batch consistency requirements.
Food Manufacturers command the largest procurement volumes. Nutraceutical Companies are gaining share fastest.
Distribution Channel:
Channel economics reflect customer scale and technical service requirements, with direct relationships capturing the most sophisticated buyers.
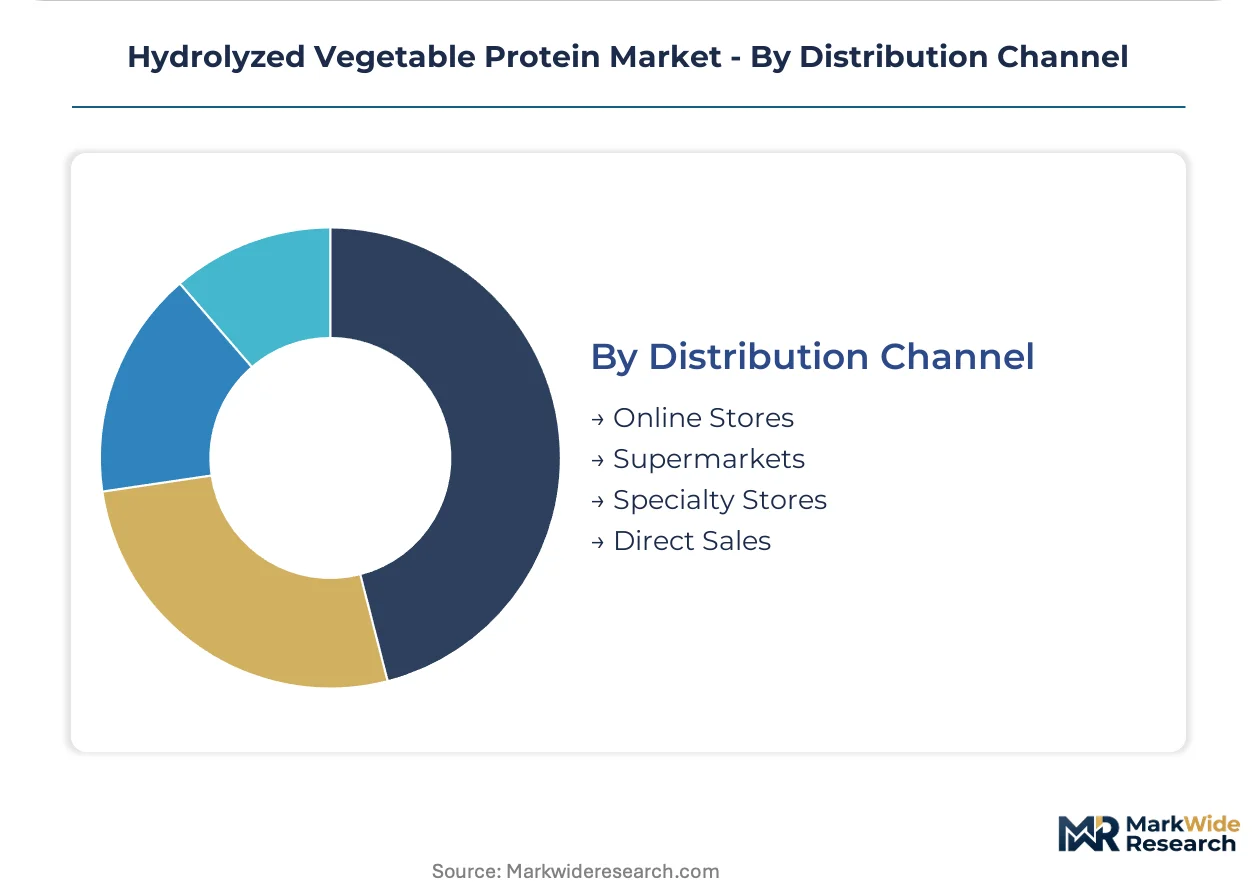
- Direct Sales:Technical partnership models for large-scale food and pharmaceutical manufacturers. German and Dutch processors negotiate multi-year supply agreements with embedded R&D collaboration for custom peptide profiles.
- Specialty Stores:Ingredient distribution to mid-tier seasoning houses and regional sauce producers. Italian and Spanish specialty distributors maintain technical sales capabilities for enzymatic product lines.
- Online Stores:E-commerce penetration for small-batch nutraceutical and pet food formulators. UK and German digital ingredient marketplaces are expanding HVP assortment breadth.
- Supermarkets:Limited retail presence confined to consumer-facing broth and seasoning brands. French and Italian retail channels show modest growth in premium clean-label condiments.
Direct Sales channels carry the highest volume throughput. Specialty Stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and enzymologists cluster in German processed food corridors and Dutch biotech hubs, anchoring European HVP innovation. California and Massachusetts food technology ecosystems pull talent from adjacent fermentation industries. Chinese flavor chemists concentrate in coastal manufacturing zones serving domestic condiment markets.
Germany
Precision fermentation expertise from pharmaceutical biotech feeds into enzymatic HVP production for clean-label soup manufacturers. REACH enforcement through ECHA tightens contaminant thresholds for acid-hydrolyzed imports. Cologne-Düsseldorf food processing corridors host backward-integrated oilseed processors controlling raw material flows.
United States
Plant-based meat startups in California negotiate direct supply agreements for custom peptide profiles, bypassing traditional flavor-house channels. FDA GRAS notification requirements for novel enzymatic methods extend approval timelines. Greater Boston biopharma clusters adopt pharmaceutical-grade hydrolysates for cell-culture media applications.
Netherlands
Specialty protease suppliers in Dutch chemical corridors dominate food-grade enzyme production for European HVP manufacturers. EFSA Novel Food frameworks scrutinize emerging fermentation-derived protein fractions. Wageningen food research ecosystems bridge academic enzymology with commercial savory ingredient development.
China
Domestic condiment manufacturers scale acid-hydrolyzed production for soy sauce and flavoring applications serving internal demand. SAMR GB standards enforce labeling and safety specifications for hydrolyzed plant proteins. Yangtze River Delta chemical processing zones concentrate legacy acid hydrolysis capacity.
Switzerland
Clinical nutrition and biopharma manufacturers enforce sub-ppm contaminant specifications that only enzymatic methods satisfy. Swissmedic pharmaceutical-grade requirements exceed EFSA food additive thresholds. Basel-Zurich life sciences corridors source custom molecular weight hydrolysates for enteral nutrition formulations.
Hydrolyzed Vegetable Protein Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered quality segments. Cargill, Incorporated leverages backward integration into oilseed processing to control raw material quality and cost structures. Kerry Group plc anchors its position through flavor-house relationships that bundle HVP into savory systems. Tate & Lyle PLC competes on enzymatic hydrolysis expertise that yields cleaner-tasting protein fractions. Consolidation pressures intensify as EFSA contaminant rules accelerate capital redeployment from acid to enzymatic production lines.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company represent conglomerates with captive oilseed processing assets that secure cost-advantaged raw material positions. Kerry Group plc occupies a position exemplifying the flavor-house bundling model that dominates technical service relationships with mid-scale food manufacturers. These three anchors illustrate how supplier archetypes map to customer procurement sophistication tiers.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Kerry Group plc |
| Givaudan SA |
| Roquette Frères |
| Ajinomoto Co., Inc. |
| Sensient Technologies Corporation |
| Titan Biotech |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Enzymologist talent concentration in Dutch biotech corridors and German food processing clusters drives labor-cost differentials that widen spreads between premium enzymatic and commodity acid-hydrolyzed tiers. REACH compliance investments in ECHA-registered facilities further stratify pricing structures as non-compliant imports face rejection at Rotterdam and Hamburg gateways.
Pricing Analysis
Bundled savory systems from flavor houses command premiums over unbundled commodity hydrolysates sold direct to plant-based meat startups. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in acid-hydrolyzed tiers is intensifying because EFSA contaminant thresholds strand legacy reactor assets. Mid-tier seasoning houses show highest price sensitivity, while Swiss biopharma contract manufacturers accept substantial premiums for sub-ppm peptide specifications.
Supply Chain Analysis
Single-source vulnerability sits with Danish and Dutch specialty protease suppliers that dominate food-grade enzyme production for European hydrolysis operations. Raw material flows draw from German oilseed processing clusters, Chinese soy protein concentrate facilities, and French wheat gluten extraction plants. Tariff exposure on enzyme imports from non-EU jurisdictions threatens margin stability for non-integrated processors. Distribution runs through direct technical partnerships with large-scale food manufacturers and specialty distributors serving mid-tier seasoning houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. EFSA's tightening 3-MCPD and glycidyl ester specifications pull demand toward enzymatic hydrolysates that acid-based production cannot reliably deliver.
For Market Incumbents: Anticipate accelerated asset stranding in acid hydrolysis reactor fleets as enzymatic methods achieve cost parity. Prioritize captive protease development capabilities to secure supply chain control. Invest in ECHA-registered production facilities to defend access to German and Dutch processed food clusters against REACH-compliant competitors. For New Entrants and Emerging Players: EFSA Novel Food frameworks in Europe open a window for precision fermentation-derived protein hydrolysates that bypass crop dependency entirely. Target Swiss and German biopharma contract manufacturers seeking serum replacement peptides with custom molecular weight specifications. Lead with pharmaceutical-grade quality positioning to capture premium tier margins unavailable to commodity acid-hydrolyzed suppliers. For Investors and Strategic Acquirers: Flavor-house conglomerates are the most active acquirer in this space, bundling hydrolyzed proteins into integrated savory systems. Five-to-ten year viability hinges on enzymatic technology transition completion. Watch EFSA additive safety assessment timelines as the inflection signal determining which hydrolysis technologies gain commercial traction.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Production Line Conversion | EFSA contaminant rules strand acid hydrolysis assets serving infant nutrition segments. |
| Backward Integration into Oilseed Processing | Cargill and ADM control soy and wheat raw material costs through captive crushing capacity. |
| Precision Fermentation Scale-Up | Biotech-enabled production achieves batch consistency for pharmaceutical-grade peptide applications. |
| Direct Supply Agreements with Plant-Based Meat Startups | California and Netherlands food technology clusters bypass traditional flavor-house intermediation. |
| Captive Protease Development Capabilities | Bacillus subtilis and Aspergillus oryzae strain optimization secures quality-tier differentiation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged food technologists at German soup manufacturers, procurement leads at Dutch savory compounders, enzymologists at Wageningen research ecosystems, and regulatory affairs specialists navigating EFSA Novel Food frameworks. Secondary validation drew from EFSA guidance documents, ECHA REACH registration databases, SAMR GB standards filings, and FDA GRAS notification records. Bottom-up volume builds across product formats and applications triangulated against top-down industry consensus.
Historical reference periods anchored projections across the analysis window. The analytical framework modeled segmentation dimensions spanning physical format, end-use application, hydrolysis technology type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating plant-based meat analogue adoption rates and enzymatic technology substitution patterns. Forecast inputs included precision fermentation capacity buildout timelines and EFSA additive safety assessment pipeline visibility.
Revisions become necessary when EFSA contaminant threshold specifications tighten beyond current analytical detection capabilities or when enzyme supply disruptions from Danish and Dutch producers materialize. Forecasts reflect documented assumptions regarding technology cost curves and regulatory approval timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Synephrine Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Vegetable Extract Market
Ingredients
Fruit Concentrate Market
Ingredients
Dairy Ingredients Market
Ingredients
Europe Agar Market
Ingredients
North America Protein Ingredients Market
Ingredients
Cheese Powder Market
Ingredients
Global Amaranth Oil Market
Ingredients
North America Soy Protein Market
Ingredients
North America Soybean Oil Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Dry Malt Products Market
Ingredients
Oyster Shell Powder Market