
 South America Malt Ingredient Market | 2026-2036
South America Malt Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
South America Malt Ingredient Market Analytics
Buyer concentration among South American breweries is pivoting as craft producers fragment procurement while multinational beverage groups consolidate malt supply contracts. Maltexco S.A. anchors Chilean production with integrated barley-to-malt operations across the central valley. Cargill leverages its grain origination network to secure feedstock cost advantages for Brazilian malt houses. Malteurop competes through specialized roasting capabilities that serve premium brewing segments in Argentina and Uruguay.
Malt ingredients comprise germinated cereal grains—primarily barley and wheat—that undergo controlled kilning to develop enzymatic activity, color precursors, and soluble extract measured in degrees Lintner for diastatic power. These modified grains provide fermentable sugars, body, and flavor complexity to beer, spirits, baked goods, and savory snacks. Malt extract leads product value pools due to its shelf stability and concentrated shipping economics across Andean distribution corridors. Brewing dominates application demand, though food manufacturers represent the fastest-growing end user as clean-label malt sweeteners displace refined sugars in regional formulations. Bulk containers anchor packaging volume for industrial buyers, while bags sustain craft brewery flexibility.
Brazil's ANVISA enforces mycotoxin thresholds and traceability standards that elevate quality compliance costs for smaller maltsters. Argentina's national food safety authority aligns with Mercosur technical regulations on cereal processing hygiene, creating cross-border certification reciprocity. ISO 22000 and hazard analysis protocols increasingly gate supplier eligibility for multinational food manufacturers. Stakeholders must monitor how water stress regulations in Chile and Argentina's grain regions reshape barley cultivation economics and malt house siting decisions.
Market Dynamics
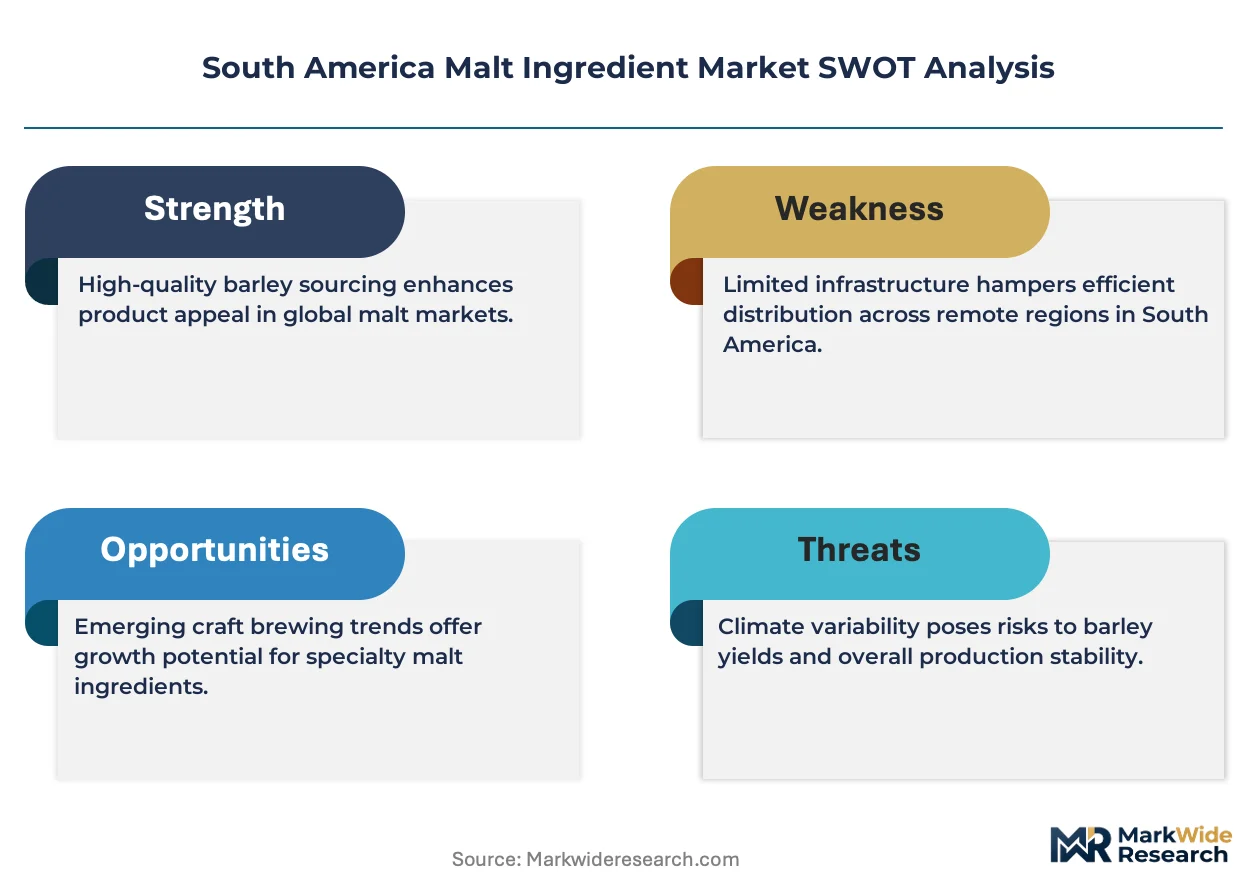
The South America malt ingredient market pivots on water stress regulations forcing malting technology upgrades across Chile's central valley and Argentina's Pampas belt, compressing legacy facility economics while rewarding capital-intensive efficiency investments.
Growth Catalysts
- Craft brewery proliferation:Small-batch producers across Brazil's São Paulo state and Argentina's Córdoba province fragment procurement patterns, creating distributed demand nodes that specialty maltsters exploit with flexible batch sizing.
- ANVISA traceability mandates:Brazil's food safety authority enforces lot-level mycotoxin documentation, accelerating quality-premium capture by certified malt houses that embed compliance into brand positioning.
- Barley varietal adaptation:Heat-tolerant cultivars developed in Argentina's INTA research network expand plantable acreage into marginal grain zones, diversifying domestic feedstock sourcing.
Market Restraints
- Input cost volatility:Natural gas prices for kilning operations swing with Argentina's energy import dependency, compressing margin predictability for malt houses without long-term fuel hedging.
- Supply concentration risk:Chile's malt production clusters in the Biobío and Maule regions, exposing buyers to seismic and drought disruption without geographic redundancy.
- Substitution pressure:Enzyme-adjunct brewing systems reduce malt intensity per hectoliter, threatening volume demand from industrial lager producers seeking cost optimization.
Strategic Opportunities
- Uruguay's underdeveloped malting base:The country's nascent craft brewing scene lacks domestic malt supply, creating first-mover positioning for Brazilian exporters with Mercosur tariff advantages.
- Clean-label malt sweeteners:Food manufacturers in Colombia and Peru—outside core malt demand centers—present white-space adoption for malt extract displacing refined sugars in bakery formulations.
- Water-efficient steeping systems:Chile's environmental ministry incentivizes closed-loop malting retrofits through accelerated depreciation, rewarding capital deployment in drought-stressed production zones.
Industry Challenges
- Malting technician scarcity:Germination control and kiln management expertise concentrates in Argentina's traditional grain belt, constraining facility expansion in Brazil's frontier production regions.
- ISO 22000 certification timelines:Multinational food manufacturer eligibility requires 12-18 month audit cycles, delaying revenue recognition for maltsters targeting ingredient-grade supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Malt Ingredient Market |
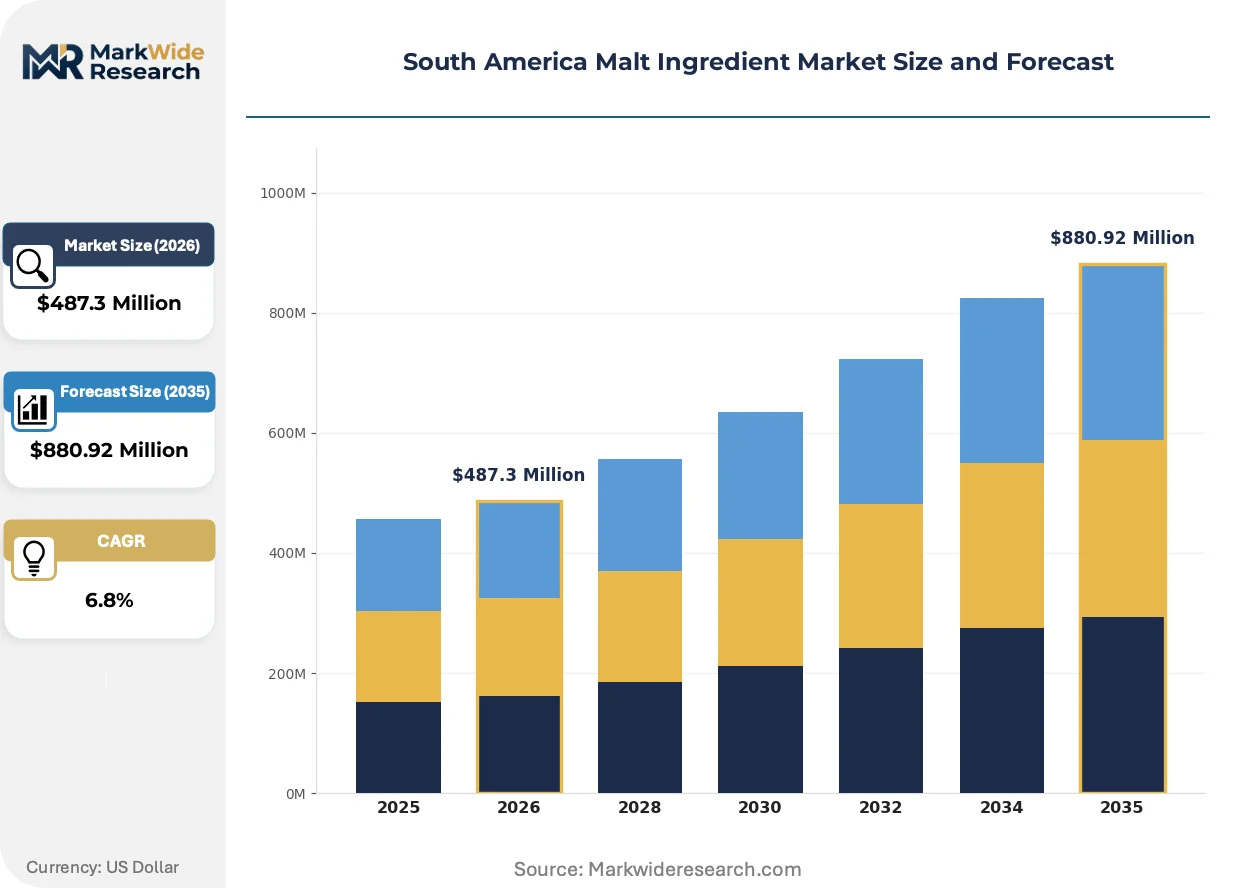
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Extract, Malted Barley, Malted Wheat, Crystal Malt Application: Brewing, Distilling, Baking, Snacks End User: Breweries, Distilleries, Bakeries, Food Manufacturers Packaging Type: Bags, Bulk Containers, Drums, Totes |
| Companies Covered | Maltexco S.A., Briess Malt, Axereal, Gusmer Enterprises, Rahr Corporation, Malteurop, GrainCorp, Groupe Soufflet, Cargill, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Malt Ingredient Market Evolving Landscape
Malting technology and procurement architecture are undergoing simultaneous restructuring across South America, driven by environmental compliance pressures and buyer fragmentation that reward operational flexibility over scale economies.
Continuous steeping and germination systems with automated moisture control are absorbing capital allocation from traditional compartment malting floors. Mid-sized Brazilian malt houses deploy these systems to reduce water consumption by half while maintaining enzymatic consistency. The technology is absorbing market share from legacy batch infrastructure that cannot meet ANVISA documentation requirements without manual intervention.
Argentina's national food safety authority alignment with Mercosur technical regulations on cereal processing hygiene creates cross-border certification reciprocity. Malt exporters in Buenos Aires province leverage this framework to access Brazilian industrial buyers without duplicate audits. Uruguay's brewing sector, lacking domestic regulatory capacity, imports exclusively from Mercosur-certified suppliers, concentrating procurement through recognized channels.
Contract structures are fragmenting as craft breweries reject annual volume commitments in favor of spot purchasing with 30-day terms. This pattern compresses working capital cycles for maltsters while elevating inventory risk. The shift is most visible in Brazil's southern states, where microbrewery density exceeds malt house distribution reach, forcing logistics reconfiguration toward smaller, more frequent deliveries.
South America Malt Ingredient Market Segmentation
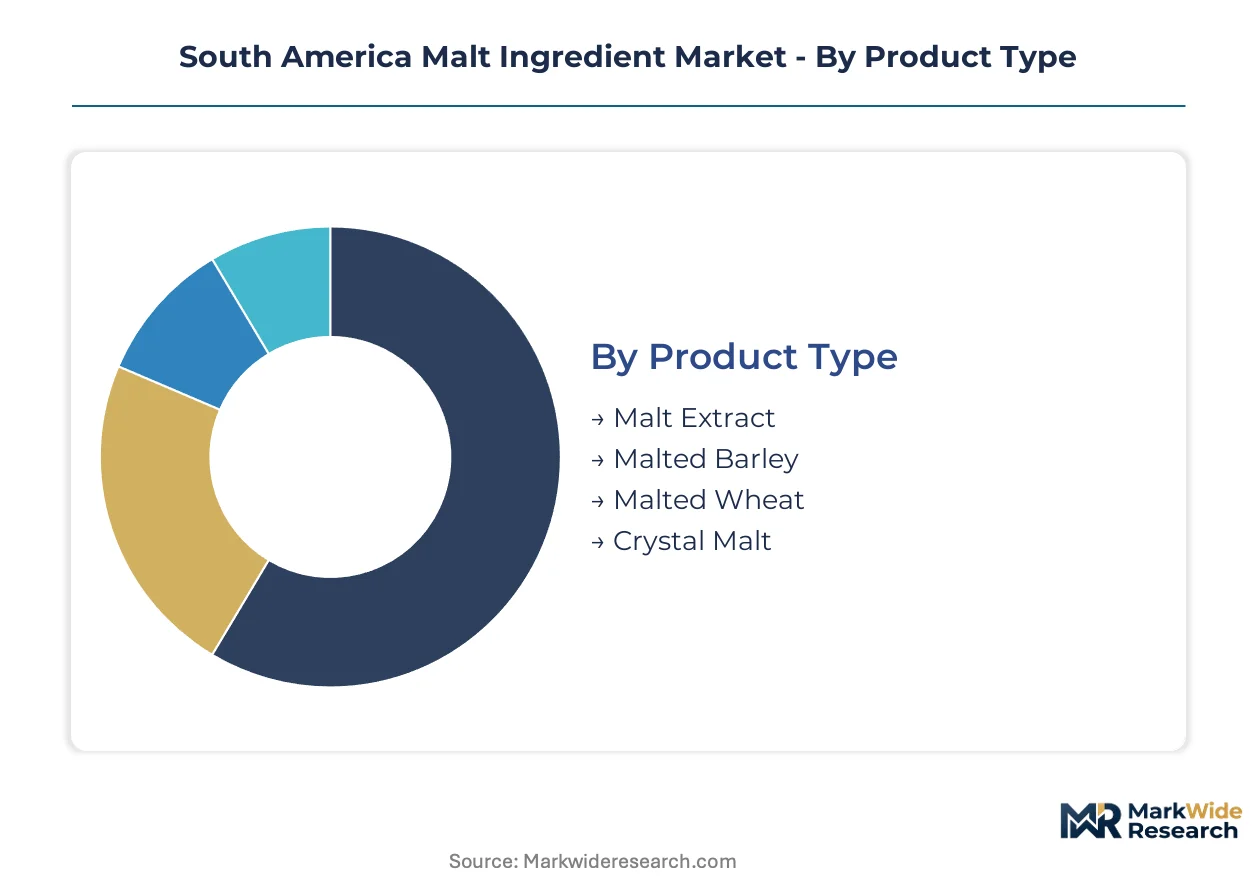
Malt ingredient procurement in South America fragments across technical specifications, regulatory thresholds, and logistics constraints that reshape supplier qualification requirements. Each segment carries distinct certification burdens and margin profiles that determine competitive positioning.
Product Type:
ANVISA traceability mandates apply differentially across product categories, with malt extract facing the strictest mycotoxin documentation while crystal malt navigates color specification protocols.
- Malt Extract:Concentrated soluble solids derived from mashed and evaporated malt deliver standardized fermentable sugar profiles for industrial brewing and food manufacturing. Demand concentrates in Brazil's São Paulo industrial corridor where large-scale bakeries and beverage producers require consistent diastatic power without batch-to-batch germination variance. ANVISA lot-level documentation requirements elevate compliance costs that certified malt houses capture as quality premiums.
- Malted Barley:Kilned germinated barley kernels provide enzymatic activity measured in degrees Lintner for starch conversion in brewing mashes. Argentina's Pampas region anchors supply through integrated barley-to-malt operations where proximity to Buenos Aires province breweries reduces inbound logistics exposure. INTA-developed heat-tolerant cultivars expand sourcing into marginal grain zones.
- Malted Wheat:Lighter kilning preserves delicate protein structures for wheat beer styles and specialty baking applications. Craft breweries in Brazil's southern states drive spot purchasing patterns.
- Crystal Malt:Stewed and roasted kernels develop caramelized sugars and color precursors measured in EBC units. Premium brewing segments in Uruguay import exclusively from Mercosur-certified suppliers.
Malted barley sits at the top of the volume ranking, with malt extract climbing the fastest.
Application:
Application segments diverge sharply in technical specification stringency, with brewing demanding enzymatic consistency while food manufacturing prioritizes clean-label positioning.
- Brewing:Controlled germination and kilning develop diastatic enzymes for starch conversion, color precursors, and flavor compounds in wort production. Brazil's craft brewery proliferation across São Paulo and Minas Gerais states fragments procurement toward flexible batch sizing and 30-day spot terms. Industrial lager producers maintain annual volume contracts with consolidated malt houses.
- Distilling:High-diastatic malt varieties maximize fermentable sugar yield for neutral spirit production. Argentina's Córdoba province distilleries source through Mercosur-certified channels leveraging cross-border reciprocity.
- Baking:Malt extract displaces refined sugars in clean-label formulations across Colombian and Peruvian bakery markets outside core malt demand centers.
- Snacks:Roasted malt powders contribute color and umami depth to savory formulations. Food manufacturers represent expanding adoption for natural ingredient positioning.
Brewing commands the dominant share, with baking expanding most quickly as clean-label sweeteners penetrate Andean food manufacturing.
End User:
End user scale determines procurement architecture, with multinational beverage groups consolidating contracts while microbreweries force logistics reconfiguration toward distributed delivery nodes.
- Breweries:Range from industrial lager producers with annual volume commitments to craft operators rejecting long-term contracts. Brazil's southern grain belt concentration creates supply-side clustering that microbreweries in underserved distribution zones must navigate through smaller, more frequent deliveries.
- Distilleries:Require high-extract malt varieties optimized for fermentation efficiency. Argentina's traditional grain belt concentrates germination control expertise.
- Bakeries:Industrial-scale operators in São Paulo state drive malt extract demand for standardized formulations.
- Food Manufacturers:Snack and confectionery producers adopt malt-based colorants and sweeteners for natural positioning. ISO 22000 certification gates eligibility for multinational supply contracts.
Breweries anchor procurement volume, with food manufacturers gaining share fastest as ingredient-grade specifications expand beyond traditional brewing applications.
Packaging Type:
Packaging selection reflects inventory velocity and handling infrastructure, with bulk formats dominating industrial procurement while flexible packaging sustains craft operator working capital constraints.
- Bulk Containers:Tanker and silo deliveries minimize per-unit handling costs for high-volume industrial breweries with dedicated intake infrastructure. Brazil's multinational beverage groups consolidate malt supply through long-term bulk contracts.
- Bags:25-50kg woven polypropylene sustains craft brewery flexibility with manageable capital outlay and storage footprint. Spot purchasing patterns elevate inventory risk for maltsters.
- Drums:Steel and fiber containers protect liquid malt extract from oxidation during Andean corridor distribution. Shelf stability drives value pool concentration.
- Totes:Intermediate bulk containers bridge industrial and craft scale requirements with returnable logistics options.
Bulk containers lead shipment volume, with bags showing the steepest expansion trajectory as craft brewery density exceeds malt house distribution reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the dominant share of South American malt demand while Argentina's integrated barley-to-malt corridor offers supply-side cost advantages that Brazilian importers increasingly contest.
Brazil
ANVISA traceability mandates on mycotoxin documentation reshape procurement toward certified malt houses with embedded compliance systems. São Paulo state's industrial brewery density fragments demand toward flexible batch sizing and spot purchasing with 30-day terms. The southern grain belt clusters malt production capacity where proximity to end-users compresses inbound logistics exposure.
Argentina
INTA-developed heat-tolerant barley cultivars expand plantable acreage into marginal grain zones, diversifying domestic feedstock sourcing. The national food safety authority's alignment with Mercosur technical regulations creates cross-border certification reciprocity that Buenos Aires province exporters exploit. Córdoba province distilleries anchor demand for high-diastatic malt varieties optimized for fermentation efficiency.
Chile
The environmental ministry's accelerated depreciation incentives for closed-loop malting retrofits reward capital deployment in drought-stressed production zones. Water stress regulations compress legacy facility economics across the Biobío and Maule regions where production concentrates. Maltexco S.A.'s integrated barley-to-malt operations span the central valley with captive supply chains.
Uruguay
The country's nascent craft brewing scene lacks domestic malt supply, creating first-mover positioning for Brazilian exporters with Mercosur tariff advantages. Exclusive reliance on Mercosur-certified suppliers concentrates procurement through recognized import channels. Montevideo's microbrewery density exceeds local distribution infrastructure, forcing logistics reconfiguration.
Colombia and Peru
Food manufacturers in these Andean markets present white-space adoption for malt extract displacing refined sugars in bakery formulations. ISO 22000 certification gates eligibility for multinational supply contracts with 12-18 month audit cycles. Bogotá and Lima industrial corridors drive standardized ingredient demand for clean-label positioning.
South America Malt Ingredient Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement nodes that fragment with craft brewery proliferation. The vendor base stratifies into three tiers: multinational grain traders with origination networks, integrated regional maltsters with captive barley supply, and specialized roasters serving premium brewing segments. Dominant competitive moves include backward integration into barley cultivation and technology licensing for water-efficient steeping systems.
Within the integrated regional tier, Maltexco S.A. and Malteurop exemplify archetypes that combine germination control expertise with geographic proximity to end-users. Cargill occupies a position among diversified conglomerates that leverage grain origination scale across Brazilian supply corridors. These three anchors represent distinct strategic postures: captive supply chain control, specialized roasting capabilities, and feedstock cost advantages through trading infrastructure.
| Leading Market Players |
|---|
| Maltexco S.A. |
| Briess Malt |
| Axereal |
| Gusmer Enterprises |
| Rahr Corporation |
| Malteurop |
| GrainCorp |
| Groupe Soufflet |
| Cargill |
| Others |
Value Network & Pricing Analysis
Family-owned malt houses across Argentina's Pampas region maintain disciplined pricing through captive barley cultivation, while Brazilian craft brewery fragmentation forces spot-market flexibility that erodes contract premiums. ANVISA certification costs concentrate margin capture among integrated operators with compliance infrastructure already embedded.
Pricing Analysis
Capacity additions in Brazil's southern grain belt are reshaping price floors for standard malt grades as new steeping systems reduce water-cost differentials. Three-tier pricing structure across premium-certified, standard-industrial, and economy-feed grades separates ANVISA-documented extract from uncertified commodity malt. Cost compression in economy tiers is intensifying because Argentine energy import dependency raises kilning fuel hedging expenses. Industrial lager producers with annual volume commitments show least price sensitivity; craft microbreweries on 30-day spot terms absorb maximum volatility.
Supply Chain Analysis
Barley feedstock rests on Argentine Pampas cultivation, Brazilian southern grain belt imports, and Chilean central valley production. Maltsters draw from natural gas for kilning operations, specialized germination control equipment, and moisture-monitoring automation systems. Single-source vulnerability concentrates in Chile's Biobío and Maule regions where seismic and drought exposure lacks geographic redundancy. Distribution runs through bulk tanker deliveries to industrial breweries, bagged shipments to craft operators, and drum containers for Andean malt extract corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America malt ingredient market functions as a stable compounder anchored by brewing demand that resists substitution despite enzyme-adjunct proliferation.
For Market Incumbents: Deploy backward integration into heat-tolerant barley breeding programs to secure feedstock cost advantages against Argentine INTA cultivar expansion. Consolidate roasting capacity in Mercosur-certified facilities to capture premium brewing segments in Uruguay and Paraguay while enzyme-adjunct systems threaten volume demand from industrial lager producers. For New Entrants and Emerging Players: Automated steeping systems with closed-loop water recycling offer technology-first positioning in Chile's drought-stressed central valley where environmental ministry incentives reward capital deployment. Target Colombia and Peru food manufacturing corridors with malt extract formulations displacing refined sugars in clean-label bakery applications, leveraging ISO 22000 certification to unlock multinational supply contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Brazilian maltsters lacking ANVISA-certified documentation systems but holding southern grain belt logistics advantages. Five-to-ten year viability hinges on water stress regulation enforcement expanding beyond Chile into Argentina's Pampas belt. Monitor INTA cultivar licensing agreements as inflection signal for feedstock cost curve direction.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Efficient Steeping Retrofit | Chile's environmental ministry accelerated depreciation rewards drought-zone capital deployment. |
| Mercosur Certification Expansion | Cross-border reciprocity unlocks Brazilian industrial buyers for Buenos Aires province exporters. |
| Heat-Tolerant Barley Breeding | INTA cultivar development expands plantable acreage into marginal Argentine grain zones. |
| Craft Distribution Reconfiguration | Smaller frequent deliveries address São Paulo microbrewery density exceeding malt house reach. |
| Clean-Label Sweetener Positioning | Malt extract penetration in Colombian and Peruvian bakery markets displaces refined sugars. |
Research Methodology
Bottom-up brewery procurement modeling reconciled against top-down grain origination tracking forms the analytical core of this study. Primary interviews with malt house operations directors, craft brewery procurement managers, ANVISA compliance officers, and grain trading desk heads combined with secondary validation from customs export records, SEC filings of listed grain traders, INTA agricultural research publications, and Mercosur technical regulation databases. Triangulation across supply-side capacity audits and demand-side purchasing pattern analysis ensures dimensional consistency.
Historical trendline analysis of malted barley and extract shipment volumes, cross-referenced with brewing capacity expansion permits and food manufacturer ingredient sourcing disclosures, established baseline growth trajectories. Segmentation dimensions modeled include product type, application, end-user scale, and packaging format across the projection horizon. CAGRs derived from regression analysis of brewing output correlations with malt intensity per hectoliter, adjusted for enzyme-adjunct substitution rates and water stress regulation implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Argentine energy import policy shifts and Chilean drought severity cycles. Assumptions reflect current ANVISA documentation requirements and Mercosur certification reciprocity frameworks. Material deviation in barley varietal adaptation rates or environmental ministry incentive program extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Passion Fruit Powder Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Clean Label Starch Market
Ingredients
Bean Ingredients Market
Ingredients
Acacia Gum Market
Ingredients
Sesame Oil Market
Ingredients
Europe Phytosterols Market
Ingredients
Chickpea Flour Market
Ingredients
African Brewing Enzymes Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Encapsulated Salt Market
Ingredients
Cheese Powder Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Cholesterol API Market
Ingredients
Casein Market
Ingredients
Polydextrose Ingredients Market