
 Facial Rejuvenation Market | 2026-2036
Facial Rejuvenation Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Rejuvenation Market Analysis
Modular treatment bundling is decoupling standalone procedure pricing from comprehensive facial rejuvenation packages, forcing buyers to evaluate component value separately. AbbVie leverages its integrated aesthetics portfolio across injectables and skincare to capture recurring patient visits. Galderma sustains competitive positioning through R&D intensity in biostimulatory fillers and toxin formulations. Merz Pharma anchors European market presence while extending distribution into Asian dermatology networks.
Facial rejuvenation encompasses minimally invasive and non-invasive procedures that restore skin elasticity, reduce rhytides, and replenish subcutaneous volume through neurotoxin injection, laser resurfacing, or collagen induction therapy. These interventions employ precise energy delivery systems or purified biologics administered at specified depths to achieve controlled tissue remodeling with defined downtime parameters. Injectables dominate current revenue pools due to repeat purchase behavior and established reimbursement pathways for therapeutic indications. Laser treatments represent the fastest-growing modality as fractional and picosecond platforms expand treatable indications beyond photoaging into melasma and scar revision. Combination treatments command premium positioning by addressing multiple aging vectors in single sessions.
FDA oversight of aesthetic devices and biologics mandates clinical trial evidence for safety endpoints before market authorization, while the EU Medical Device Regulation imposes stricter post-market surveillance on laser and energy-based systems. HIPAA compliance requirements shape how dermatology clinics and medspas manage patient imaging records and marketing communications. Stakeholders must monitor evolving regulatory distinctions between cosmetic and therapeutic indications as jurisdictions reassess classification frameworks for emerging biostimulatory agents.
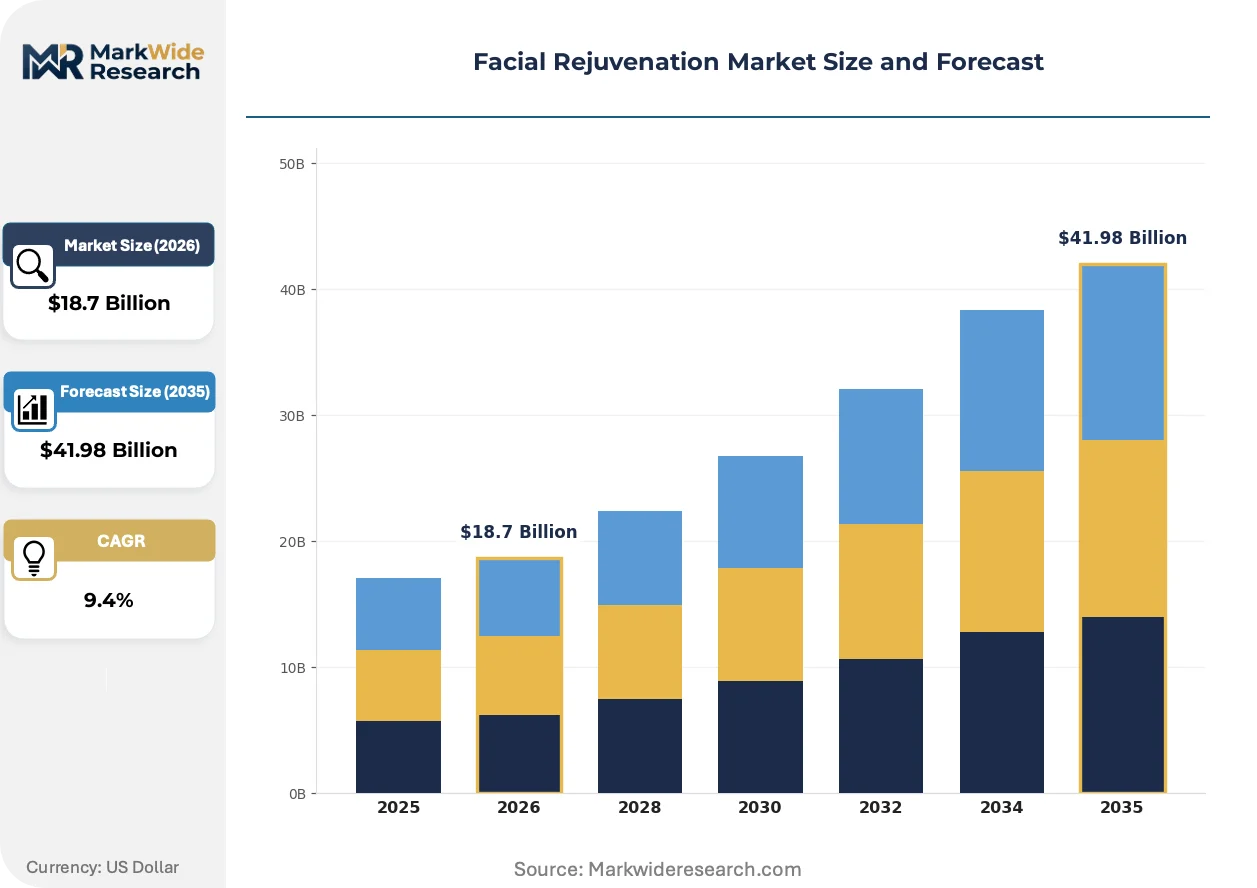
Market Dynamics
Injectable neurotoxins and biostimulatory fillers are compressing treatment intervals from annual to quarterly cycles, locking patients into recurring revenue streams that reshape clinic economics and manufacturer forecasting models.
Growth Catalysts
- Preventive Aesthetic Adoption:Millennials in the United States initiate neurotoxin protocols at earlier ages than prior cohorts, expanding the addressable patient base by decades.
- FDA 510(k) Pathway Efficiency:Streamlined clearance mechanisms for laser platform iterations accelerate commercialization timelines for fractional and picosecond systems.
- Biostimulatory Agent Classification:Regulatory frameworks in the European Union under MDR create distinct positioning for collagen-inducing fillers versus hyaluronic acid alternatives.
Market Restraints
- Hyaluronic Acid Price Volatility:Fermentation-derived raw material costs fluctuate with agricultural input markets, pressuring filler gross margins.
- Device Supply Concentration:German and Israeli laser component manufacturers control picosecond source technology, creating single-source dependencies.
- EU MDR Compliance Burden:Stricter post-market surveillance requirements for energy-based systems extend certification timelines and inflate documentation costs.
Strategic Opportunities
- Asian Dermatology Networks:Underdeveloped clinic density in South Korea and Japan creates whitespace for branded toxin and filler distribution partnerships.
- Combination Protocol Expansion:Bundling laser resurfacing with injectable volume restoration commands premium positioning per session.
- Telehealth Pre-Screening:Remote consultation platforms reduce patient acquisition costs and expand geographic catchment areas for metropolitan clinics.
Industry Challenges
- Injector Training Scarcity:Certified practitioners for advanced biostimulatory techniques remain concentrated in coastal United States markets, limiting service expansion.
- Legacy EMR Integration:HIPAA-compliant imaging systems for before-and-after documentation require costly upgrades at independent dermatology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Rejuvenation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Treatments, Chemical Peels, Microneedling End User: Dermatology Clinics, Beauty Spas, Hospitals, Homecare Procedure Type: Non-Invasive, Minimally Invasive, Complete Surgical, Combination Treatments Age Group: Millennials, Gen X, Baby Boomers, Seniors |
| Companies Covered | AbbVie, Galderma, Merz Pharma, Revance Therapeutics, Medytox, Ipsen, Hugel, Sientra, Sinclair Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Rejuvenation Market Emerging Trajectories
Energy delivery systems and biological formulations are converging to enable personalized treatment protocols that adapt to individual skin aging trajectories rather than standardized age-based approaches.
Microfocused ultrasound with visualization (MFU-V) technology is absorbing market share from traditional radiofrequency platforms by enabling precise depth-targeted collagen remodeling without surface damage. High-volume aesthetic chains in the United States deploy MFU-V as a standalone lift alternative for patients seeking injectable-free outcomes. The technology is absorbing revenue that previously flowed to surgical facelifts and thread-based interventions.
EU Medical Device Regulation (MDR) reclassification of intense pulsed light systems as Class IIa devices imposes clinical evidence requirements that smaller manufacturers cannot satisfy. European notified bodies have consolidated under MDR strain, creating bottlenecks for laser platform approvals. Aesthetic device distributors in Germany and France are absorbing extended lead times by pre-positioning inventory ahead of certification expiration.
Subscription-based maintenance programs are replacing per-procedure pricing at United States dermatology clinics, with patients committing to quarterly neurotoxin and biannual filler schedules. This model compresses patient lifetime value calculations and shifts revenue recognition patterns. Coastal metropolitan markets exhibit the highest subscription penetration, with Los Angeles and Miami clinics reporting majority enrollment in membership tiers.
Facial Rejuvenation Market Segmentation
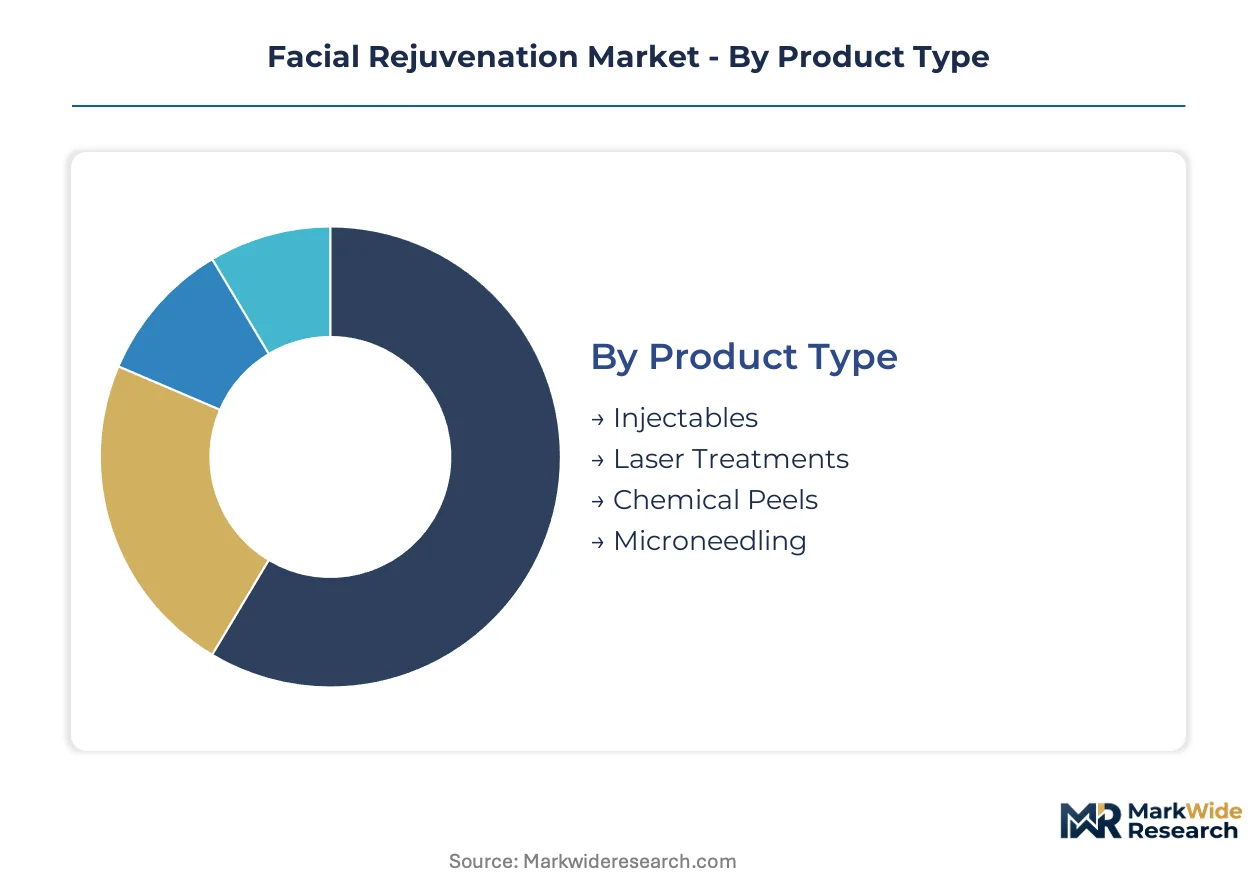
Facial rejuvenation revenue flows through distinct technical and channel pathways that determine margin profiles and patient acquisition costs. Manufacturers calibrate portfolio investments across these axes based on repeat purchase frequency and regulatory burden differentials.
Product Type:
Purified biologics and energy delivery systems anchor the technology stack, with formulation chemistry and wavelength engineering defining competitive moats.
- Injectables:Neurotoxin and hyaluronic acid formulations dominate procedure volume through quarterly retreatment cycles. United States dermatology clinics capture the majority of toxin revenue as millennials initiate preventive protocols at earlier ages than prior cohorts.
- Laser Treatments:Fractional and picosecond platforms expand treatable indications from photoaging into melasma and scar revision. FDA 510(k) pathway efficiency accelerates commercialization timelines for device iterations, compressing competitive windows.
- Chemical Peels:Acid-based exfoliation protocols address superficial photodamage with minimal capital requirements. Beauty spas deploy these as entry-tier services to funnel patients toward higher-margin injectable consultations.
- Microneedling:Collagen induction therapy penetrates at controlled depths to stimulate dermal remodeling. Homecare device variants create channel conflict with professional-grade systems.
Injectables lead on scale; laser treatments lead on momentum.
End User:
Channel economics vary sharply across clinical settings, with reimbursement access and regulatory oversight shaping service mix decisions.
- Dermatology Clinics:Physician-supervised settings command premium positioning for advanced biostimulatory techniques and combination protocols. Coastal United States markets concentrate certified practitioners, limiting geographic expansion.
- Beauty Spas:Non-medical aesthetic venues capture volume through lower price points and reduced downtime marketing. State-level scope-of-practice regulations constrain service menus in jurisdictions with strict supervision requirements.
- Hospitals:Academic medical centers integrate facial rejuvenation with reconstructive and therapeutic indications. Reimbursement pathways for therapeutic neurotoxin applications support procedure economics.
- Homecare:Consumer-directed devices and topical systems extend treatment intervals between professional visits. FDA clearance requirements for at-home energy-based devices create higher barriers than topical formulations.
Dermatology clinics capture the highest revenue per patient; beauty spas capture the highest procedure volume.
Procedure Type:
Invasiveness spectrums determine recovery parameters, risk profiles, and the competitive threat from surgical alternatives.
- Non-Invasive:Energy-based and topical interventions deliver results without epidermal breach. Microfocused ultrasound with visualization technology absorbs market share from traditional radiofrequency platforms by enabling precise depth-targeted collagen remodeling.
- Minimally Invasive:Injectable delivery and microneedling create controlled tissue response with defined downtime parameters. Subscription-based maintenance programs at United States clinics lock patients into quarterly neurotoxin and biannual filler schedules.
- Complete Surgical:Facelift and blepharoplasty procedures address advanced tissue laxity beyond non-surgical modalities. Revenue compression from effective non-invasive alternatives pressures surgical volume.
- Combination Treatments:Bundled protocols addressing multiple aging vectors command premium positioning per session. Los Angeles and Miami clinics report majority enrollment in membership tiers combining laser resurfacing with injectable volume restoration.
Minimally invasive procedures anchor current revenue; combination treatments are expanding most quickly.
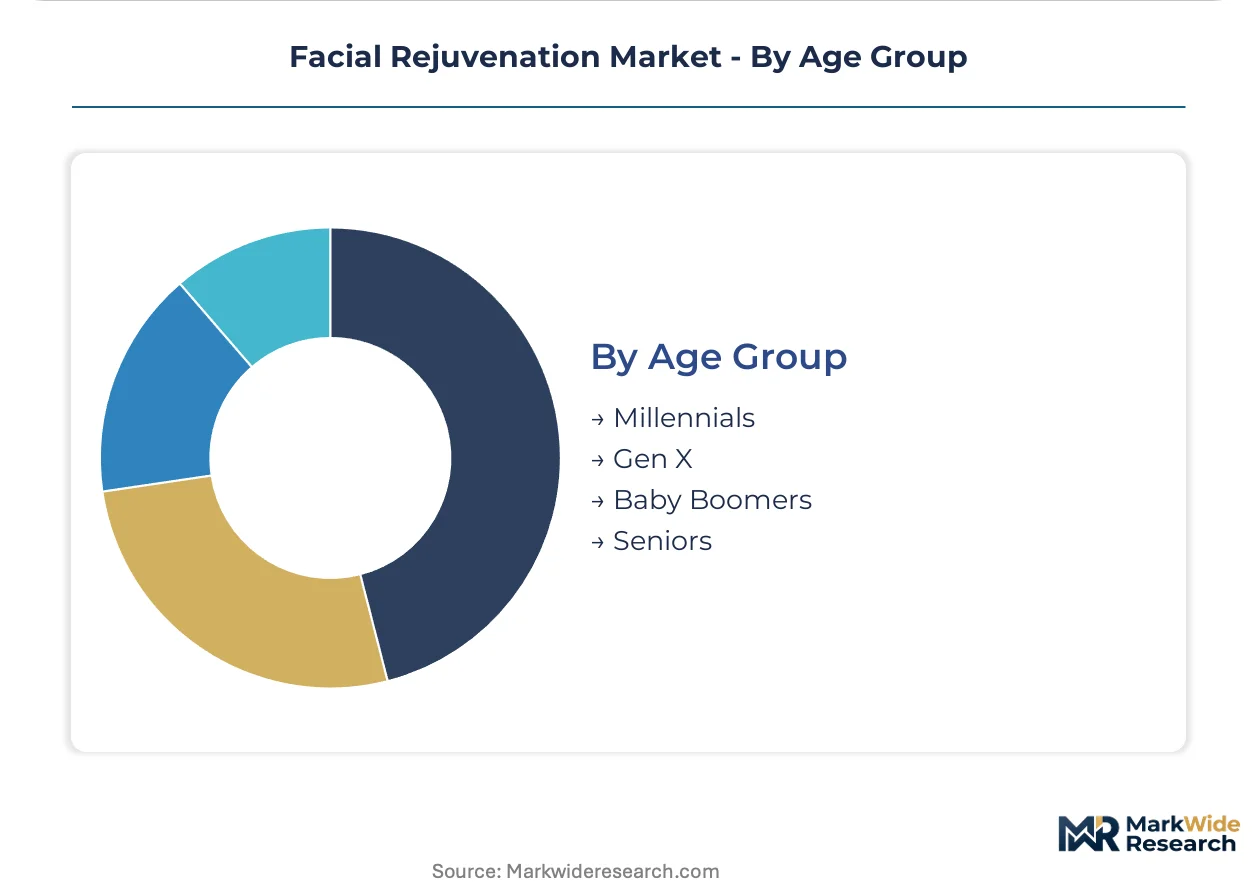
Age Group:
Generational cohorts exhibit distinct treatment initiation patterns, preventive versus corrective motivations, and price sensitivity profiles.
- Millennials:Preventive aesthetic adoption drives neurotoxin initiation decades earlier than prior cohorts. United States disposable income concentration supports premium procedure uptake in metropolitan markets.
- Gen X:Corrective interventions address established photodamage and volume loss with combination protocol acceptance. This cohort demonstrates highest willingness to pay for comprehensive treatment packages.
- Baby Boomers:Established aesthetic patients sustain filler and toxin maintenance with surgical consideration for advanced laxity. Loyalty to specific practitioners and clinics exceeds younger demographics.
- Seniors:Therapeutic indications including facial spasm and migraine drive neurotoxin utilization with aesthetic benefits as secondary outcomes. Medicare reimbursement pathways shape service delivery settings.
Millennials lead on patient lifetime value extension; Gen X leads on per-procedure spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facial rejuvenation techniques originated in European dermatology clinics during the mid-twentieth century before commercial scaling shifted to United States metropolitan markets. The industry's geographic center of gravity now spans North American, European, and East Asian innovation clusters with distinct regulatory pathways shaping local competitive dynamics.
United States
Millennial preventive aesthetic adoption drives neurotoxin volume growth decades earlier than prior demographic cohorts. FDA 510(k) pathway efficiency accelerates laser platform commercialization timelines for fractional and picosecond system iterations. Los Angeles and Miami clinic chains report majority patient enrollment in subscription-based maintenance tiers combining multiple modalities.
Germany
EU Medical Device Regulation reclassification of intense pulsed light systems as Class IIa devices imposes clinical evidence requirements on domestic manufacturers. German notified body consolidation under MDR strain creates certification bottlenecks for energy-based aesthetic platforms. Munich and Frankfurt distributors pre-position inventory ahead of certification expiration to absorb extended lead times.
South Korea
Underdeveloped clinic density relative to per-capita aesthetic demand creates whitespace for branded toxin and filler distribution partnerships. MFDS oversight of biostimulatory agents maintains distinct classification frameworks from hyaluronic acid alternatives. Seoul's Gangnam district concentrates advanced injector training facilities serving domestic and medical tourism patient flows.
Japan
Aging demographic profiles sustain corrective intervention demand with established willingness to pay for combination protocols. PMDA review timelines for novel neurotoxin formulations exceed FDA equivalents, compressing competitive windows for first-mover advantages. Tokyo and Osaka dermatology networks anchor premium service positioning across the East Asian market.
Brazil
Therapeutic neurotoxin indications including facial spasm drive utilization with aesthetic applications as secondary outcomes. ANVISA regulatory frameworks distinguish cosmetic from therapeutic device classifications, shaping manufacturer portfolio prioritization. São Paulo's aesthetic clinic density supports procedure volume leadership across Latin American markets.
Facial Rejuvenation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and injector certification requirements, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: integrated pharmaceutical portfolios spanning injectables and skincare, pure-play toxin specialists, and energy-based device manufacturers. Dominant competitive moves include R&D intensity in biostimulatory filler chemistry and geographic expansion into underpenetrated Asian dermatology networks.
Within the integrated portfolio tier, AbbVie and Galderma exemplify multi-modal aesthetic positioning that captures recurring patient visits across treatment categories. Merz Pharma anchors European market presence while extending distribution infrastructure into Asian markets. Revance Therapeutics occupies a specialist position focused on novel neurotoxin delivery technologies.
| Leading Market Players |
|---|
| AbbVie |
| Galderma |
| Merz Pharma |
| Revance Therapeutics |
| Medytox |
| Ipsen |
| Hugel |
| Sientra |
| Sinclair Pharma |
| Others |
Supply Flow & Price Mechanics
Millennial subscription enrollment at United States dermatology clinics is compressing per-procedure revenue recognition into quarterly membership cycles, forcing manufacturers to restructure volume forecasts around recurring consumption patterns rather than episodic purchases. This shift toward locked-in patient schedules reduces price transparency and embeds supply commitments into long-term clinic contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised combination protocols from standalone injectable services and entry-level chemical peels. FDA 510(k) clearance tier and injector certification grade drive price differentiation, with biostimulatory fillers commanding premiums over hyaluronic acid alternatives. Cost compression in the standard tier is intensifying because beauty spas absorb hyaluronic acid price volatility to maintain volume. Beauty spas exhibit highest price sensitivity; academic medical centers demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates under EU MDR are reshaping sourcing for energy-based device manufacturers, who must relocate component assembly to satisfy notified body certification requirements. German and Israeli suppliers control picosecond laser source technology, while South Korean fermentation facilities produce neurotoxin raw material. Single-source vulnerability in laser component manufacturing creates supply chain risk. Distribution runs through branded toxin and filler partnerships with metropolitan dermatology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial rejuvenation market functions as a regulatory compounder, with FDA 510(k) pathway efficiency for laser platforms and EU MDR reclassification timelines simultaneously accelerating commercialization windows and compressing competitive moats.
For Market Incumbents: Anchor market position through backward integration into biostimulatory filler raw material production, securing fermentation capacity against hyaluronic acid price volatility. Expand certified injector training infrastructure in underpenetrated Asian markets to preempt emerging entrant archetypes from capturing clinic network loyalty. Prioritize CE marking investment ahead of MDR certification bottlenecks. For New Entrants and Emerging Players: Telehealth pre-screening platforms offer the most penetrable route for patient acquisition cost reduction, enabling geographic catchment expansion without physical clinic infrastructure. Target South Korean and Japanese dermatology networks where branded distribution partnerships remain undersaturated. Deploy subscription-based maintenance software as the primary go-to-market angle to lock recurring revenue. For Investors and Strategic Acquirers: Asymmetric upside sits with biostimulatory filler specialists possessing differentiated collagen-inducing chemistry and established EU MDR technical documentation. Long-term viability hinges on regulatory pathway execution rather than manufacturing scale alone. Watch FDA clearance velocity for novel neurotoxin formulations as the inflection indicator for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Biostimulatory Filler R&D Intensity | Galderma's collagen-inducing formulations differentiate against commodity hyaluronic acid alternatives in EU markets. |
| Asian Distribution Partnership Expansion | Merz Pharma's Seoul and Tokyo clinic network extensions capture whitespace in underdeveloped dermatology infrastructure. |
| MFU-V Technology Platform Integration | High-volume United States chains deploy visualization-guided ultrasound as standalone surgical alternatives. |
| Subscription-Based Maintenance Programs | Los Angeles and Miami clinics report majority enrollment in membership tiers combining multiple modalities. |
| EU MDR Compliance Pathway Investment | German notified body consolidation creates certification bottlenecks requiring pre-positioned inventory strategies. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic operators, aesthetic device procurement managers, neurotoxin formulation chemists, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU MDR notified body databases, ClinicalTrials.gov aesthetic device registrations, and hospital procurement contract repositories. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segment estimates.
Segment-weighting approaches distributed value across injectable biologics, laser platforms, and combination protocols according to retreatment frequency and reimbursement pathway access. Product type, end-user channel, procedure invasiveness, and generational cohort dimensions structured the analytical framework across the projection horizon. CAGRs derived from historical procedure volume trajectories and pricing elasticity assumptions, with FDA clearance velocity and EU MDR certification timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for microfocused ultrasound with visualization would alter the outlook if radiofrequency platforms recapture collagen remodeling market share. Forecasts reflect assumptions around millennial preventive aesthetic initiation rates and EU notified body capacity expansion. Regulatory reassessment of biostimulatory agent classifications and hyaluronic acid raw material cost trajectories present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market