
 Global Aesthetic Fillers Market | 2026-2036
Global Aesthetic Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aesthetic Fillers Market Foresight
Buyer concentration among dermatology clinic chains and multi-site medspa networks is hardening as independent aesthetic practitioners face reimbursement compression and rising insurance costs. Galderma Pharma SA leverages its integrated dermal filler and toxin portfolio to secure preferred vendor status with large clinic groups. Merz Pharma anchors its position through sustained R&D investment in calcium hydroxylapatite formulations. Teoxane Laboratories differentiates via specialized hyaluronic acid products designed for dynamic facial zones.
Aesthetic fillers comprise biocompatible substances—predominantly hyaluronic acid, calcium hydroxylapatite, poly-L-lactic acid, polymethyl methacrylate, and collagen—engineered for subdermal or intradermal injection to restore volume, smooth rhytides, or enhance facial topography. These materials function through immediate physical displacement of tissue or gradual neocollagenesis, with rheological properties measured in G-prime and cohesivity determining clinical indication. Hyaluronic acid formulations dominate current revenue owing to reversibility with hyaluronidase and established safety profiles, while poly-L-lactic acid segments capture above-average margins in facial volumization protocols requiring staged treatment. Polymethyl methacrylate microspheres occupy a narrower niche due to permanent implant characteristics and stricter regulatory scrutiny.
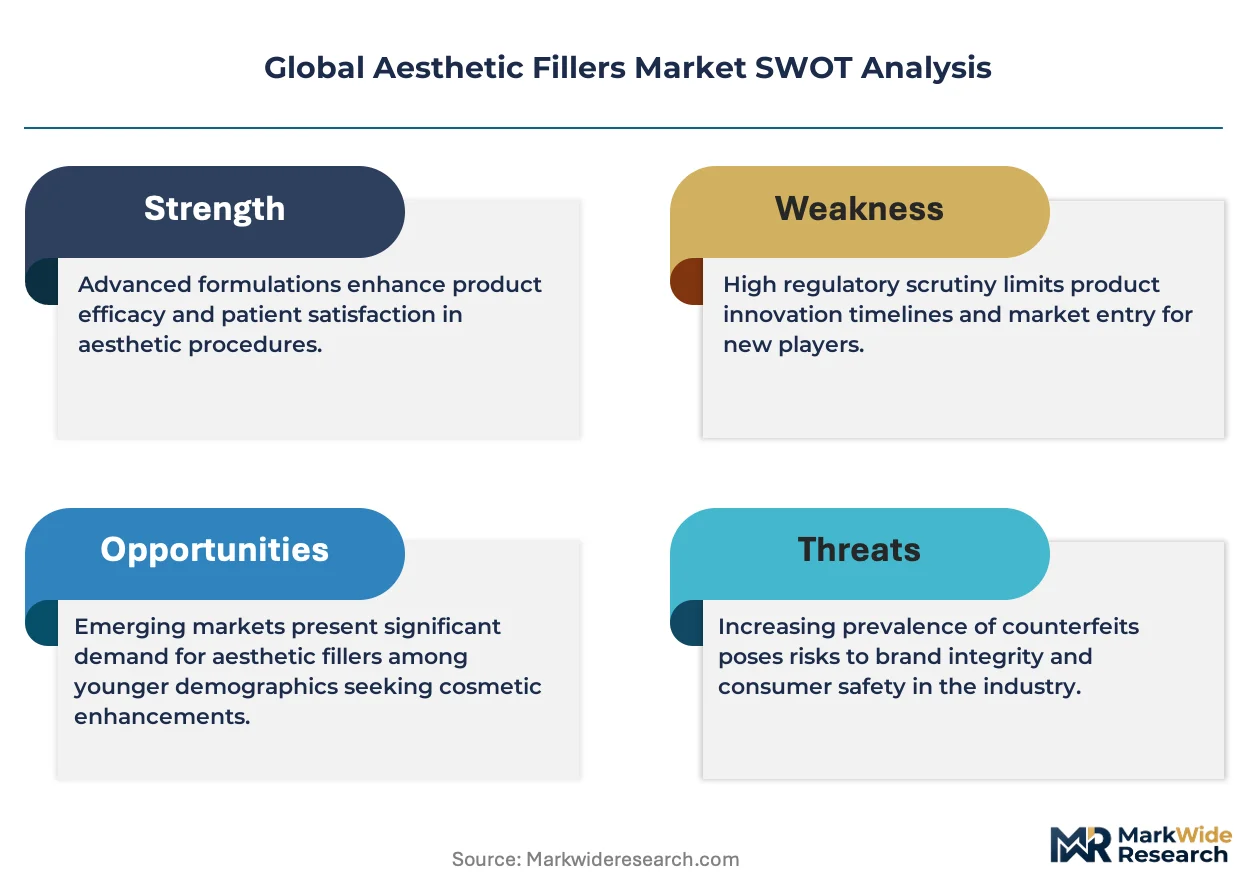
The FDA, EMA under MDR frameworks, and ANVISA collectively shape market access through divergent clinical evidence requirements and post-market surveillance obligations. FDA premarket approval pathways for permanent fillers demand larger safety cohorts than absorbable alternatives, while EMA MDR reclassification has extended notified body review timelines. Stakeholders must monitor evolving biocompatibility standards and traceability mandates that will determine which manufacturing configurations sustain commercial viability.
Market Dynamics
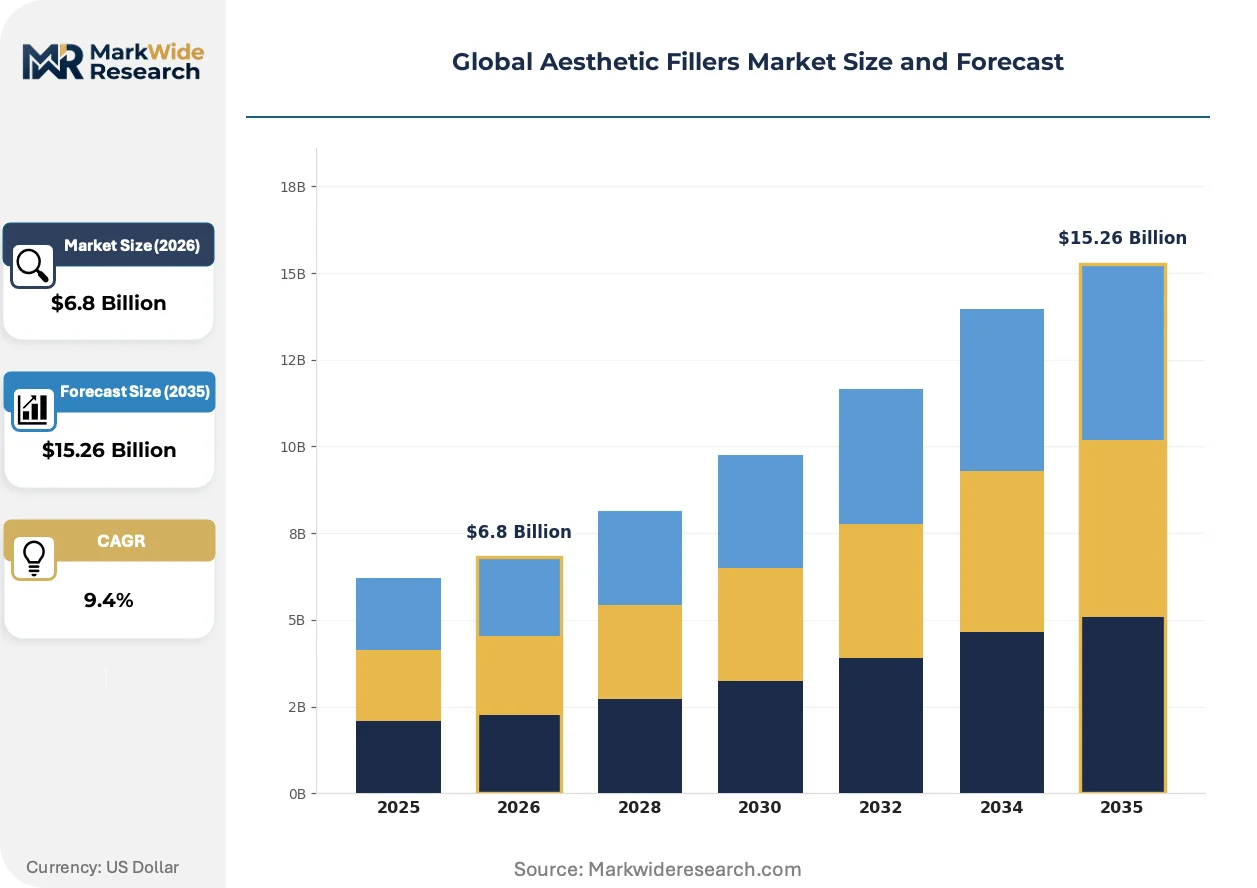
The aesthetic fillers sector is undergoing a structural compression as EU Medical Device Regulation reclassification extends notified body review timelines and concentrates procurement authority within consolidated clinic networks.
Growth Catalysts
- MDR Harmonization:The EU Medical Device Regulation creates a unified compliance pathway that reduces fragmentation for manufacturers with established quality systems. This accelerates market access for firms already holding CE marking.
- Medspa Network Expansion:Multi-site aesthetic clinic chains in the United States and South Korea are standardizing treatment protocols across locations. Their volume purchasing agreements drive demand for hyaluronic acid formulations with documented rheological profiles.
- Hyaluronidase Reversibility:The safety net of enzymatic dissolution is expanding clinical indications beyond traditional facial zones. Practitioners in Brazil now employ reversible fillers in high-risk anatomical areas previously reserved for surgical intervention.
Market Restraints
- Fermentation-Derived HA Feedstock Volatility:Pharmaceutical-grade sodium hyaluronate production depends on streptococcal fermentation capacity concentrated in Chinese and Japanese bioreactor facilities. Supply interruptions propagate directly to finished filler pricing.
- FDA PMA Cohort Requirements:Permanent implantable devices face substantially larger safety database demands than absorbable alternatives. Polymethyl methacrylate microsphere developers encounter extended timelines and capital requirements that deter market entry.
- Autologous Fat Transfer:Liposuction-derived adipocyte grafting offers permanent volumization without foreign material implantation. This substitute captures cases requiring large-volume facial restoration where synthetic fillers prove cost-prohibitive.
Strategic Opportunities
- India's Nascent Aesthetic Infrastructure:Metro hospital chains in Mumbai and Delhi are establishing dedicated cosmetic dermatology departments. The country's central pharmaceutical regulator has streamlined import licensing for established hyaluronic acid brands.
- Combination Toxin-Filler Protocols:Dynamic facial zone treatments integrating neuromodulator and volumizing agent administration are creating new service categories. This convergence requires coordinated formulation development and training curriculum design.
- Direct-to-Consumer Teleconsultation:Digital platforms are bypassing traditional referral pathways between aesthetic practitioners and prospective patients. South Korean mobile applications now facilitate virtual assessment and clinic matching for international medical tourists.
Industry Challenges
- Vascular Occlusion Management Competency:Injection-related arterial compromise requires immediate hyaluronidase administration and hyperbaric oxygen access. Training gaps in complication recognition persist among newly credentialed practitioners in rapidly expanding markets.
- Legacy Inventory Traceability:EUDAMED database integration demands serialization infrastructure that smaller manufacturing configurations struggle to fund. Batch-level tracking obligations extend from production through point-of-administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aesthetic Fillers Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-Lactic Acid, Polymethyl Methacrylate, Collagen Application: Facial Contouring, Wrinkle Reduction, Lip Enhancement, Hand Rejuvenation, Acne Scar Treatment End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Aesthetic Practitioners Delivery Method: Injectable, Topical, Implantable, Microneedling Assisted |
| Companies Covered | Allergan plc (AbbVie Inc.), Galderma Pharma SA, Merz Pharma, Teoxane Laboratories, Sinclair Pharma, Laboratories Vivacy SAS, Suneva Medical Inc., Integra Lifesciences, Zimmer Aesthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aesthetic Fillers Market Shifts & Advancements
Formulation science and delivery mechanisms are converging to enable personalized treatment protocols that match rheological properties to specific anatomical indications and patient tissue characteristics.
Cross-linked hyaluronic acid technology is modularizing around tunable G-prime and cohesivity parameters that practitioners select based on injection depth and tissue mobility requirements. Dermatology clinic chains in the United States are adopting rheology-matched product portfolios that standardize outcomes across provider networks. This technology is modularizing treatment planning into discrete, reproducible steps that reduce inter-practitioner variability and support scalable training programs.
The EU Medical Device Regulation reclassification of implantable substances has extended notified body review timelines from 12 to 24 months for novel filler submissions. Manufacturers are restructuring clinical evidence packages to address biocompatibility endpoints under ISO 10993 standards. Absorbable hyaluronic acid formulations face lighter evidentiary burdens than permanent polymethyl methacrylate alternatives, tilting R&D investment toward reversible platforms.
Patient acquisition patterns are fragmenting as social media platforms displace traditional referral networks between aesthetic practitioners and prospective clients. Instagram and TikTok content creators in Brazil and South Korea now drive clinic selection decisions through before-and-after documentation. This channel shift concentrates marketing expenditure toward digital asset production and influencer partnership structures rather than professional society engagement.
Global Aesthetic Fillers Market Segmentation
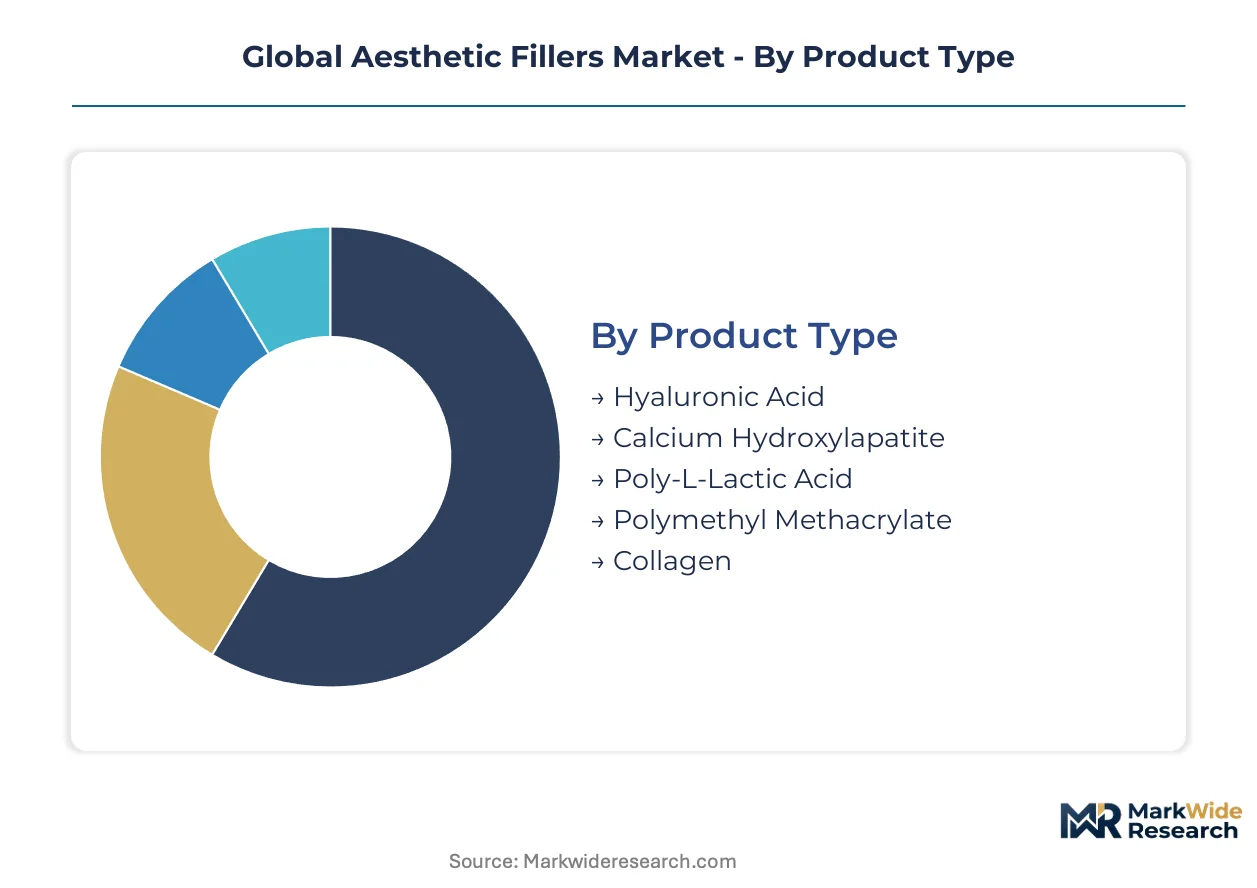
Segmentation in aesthetic fillers determines regulatory pathway complexity, reimbursement positioning, and practitioner training requirements. Manufacturers align R&D portfolios with specific segment characteristics to optimize clinical evidence investments and commercial launch timelines.
Product Type:
EMA MDR and FDA PMA requirements diverge sharply across material permanence, with absorbable formulations facing lighter evidentiary burdens than permanent implants.
- Hyaluronic Acid:Cross-linked sodium hyaluronate formulations dominate procedural volume due to enzymatic reversibility with hyaluronidase. Demand concentrates in United States dermatology clinic chains seeking standardized rheological portfolios with documented G-prime profiles for volume purchasing agreements.
- Calcium Hydroxylapatite:Biosynthetically produced microspheres suspended in aqueous gel carrier stimulate neocollagenesis through foreign body response. Brazil's aesthetic practitioners favor this material for hand rejuvenation and facial volumization where longer duration offsets higher per-procedure cost.
- Poly-L-Lactic Acid:Biodegradable polymer requiring reconstitution and staged injection protocols.
- Polymethyl Methacrylate:Permanent microsphere implants subject to FDA PMA cohort requirements exceeding absorbable alternatives.
- Collagen:Bovine and human-derived matrices with declining share amid HA substitution.
Leading the category by volume: Hyaluronic Acid. Expanding most quickly: Poly-L-Lactic Acid.
Application:
Cost tier stratification separates premium facial zones from standard indications, with complication risk profiles driving pricing differentiation.
- Facial Contouring:Midface volumization and jawline definition require high G-prime formulations with substantial lifting capacity. South Korean medspa networks standardize cheek and chin protocols across multi-site operations, creating demand for rheology-matched product lines.
- Wrinkle Reduction:Static rhytide correction in glabellar and nasolabial regions represents the most mature indication with established reimbursement codes.
- Lip Enhancement:High-cohesivity HA formulations designed for dynamic tissue mobility.
- Hand Rejuvenation:Dorsal volume restoration addresses age-associated fat atrophy.
- Acne Scar Treatment:Subcision-combined filler protocols for atrophic scarring.
Highest margin concentration: Facial Contouring. Steepest expansion trajectory: Lip Enhancement.
End User:
Customer type determines procurement scale, with consolidated networks extracting volume discounts unavailable to independent operators.
- Dermatology Clinics:Physician-supervised facilities with established complication management infrastructure and hyaluronidase inventory. United States multi-site networks concentrate purchasing authority through preferred vendor agreements with integrated toxin-filler portfolios.
- Cosmetic Surgery Centers:Hospital-affiliated or standalone surgical facilities combining invasive and non-invasive procedures.
- Medical Spas:Non-physician supervised or mid-level practitioner settings with standardized protocol menus.
- Aesthetic Practitioners:Independent solo operators facing reimbursement compression and rising malpractice premiums.
Dominant procurement volume: Dermatology Clinics. Gaining share fastest: Medical Spas.
Delivery Method:
Supply concentration in sterile manufacturing configurations favors established injectable platforms over emerging delivery innovations.
- Injectable:Needle and cannula-based subdermal or intradermal deposition remains the standard of care. Brazilian and South Korean markets drive demand for micro-cannula techniques reducing vascular compromise risk in high-risk anatomical zones.
- Topical:Transdermal penetration enhancers with limited commercial traction.
- Implantable:Surgical placement of permanent or semi-permanent devices.
- Microneedling Assisted:Fractional delivery combined with biostimulatory agents.
Representing the fastest-growing trajectory: Microneedling Assisted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for aesthetic fillers concentrates in three national markets where clinic network consolidation and regulatory frameworks have created distinct commercial environments. Each geography presents unique procurement patterns and compliance requirements that shape manufacturer market access strategies.
United States
Multi-site dermatology clinic chains in California and New York Metro drive volume purchasing agreements for hyaluronic acid portfolios with documented rheological profiles. FDA premarket approval pathways for permanent fillers demand substantially larger safety cohorts than absorbable alternatives, extending development timelines for novel formulations. The Greater Boston corridor hosts specialized training centers addressing vascular occlusion management competency gaps among newly credentialed practitioners.
South Korea
Seoul Capital Area medspa networks standardize cheek and chin protocols across multi-site operations, creating concentrated demand for high G-prime formulations. MFDS maintains streamlined registration pathways for established hyaluronic acid brands while requiring enhanced biocompatibility documentation under evolving ISO 10993 standards. Busan-Ulsan clusters serve as departure points for international medical tourists accessing combination toxin-filler protocols through digital consultation platforms.
Brazil
Aesthetic practitioners in São Paulo and Rio de Janeiro employ reversible fillers in high-risk anatomical zones previously reserved for surgical intervention, expanding clinical indications beyond traditional facial applications. ANVISA oversees import licensing and post-market surveillance for implantable devices with traceability mandates extending through point-of-administration. Calcium hydroxylapatite formulations capture preference for hand rejuvenation and facial volumization where longer duration offsets higher per-procedure cost.
Germany
EMA MDR reclassification has extended notified body review timelines from 12 to 24 months for novel filler submissions, concentrating procurement authority within consolidated clinic networks. Bavaria and North Rhine-Westphalia host manufacturing configurations investing in EUDAMED database integration and serialization infrastructure. German dermatology associations lead European training curriculum development for complication recognition and hyaluronidase administration protocols.
India
Metro hospital chains in Mumbai and Delhi are establishing dedicated cosmetic dermatology departments as central pharmaceutical regulator CDSCO streamlines import licensing for established hyaluronic acid brands. Maharashtra and Karnataka clusters attract medical tourists from Gulf states seeking cost-advantaged facial contouring procedures. Domestic fermentation-derived sodium hyaluronate production remains limited, creating dependency on Chinese and Japanese bioreactor feedstock supply.
Global Aesthetic Fillers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized rheology-matched portfolios and regional market access partnerships. The vendor base organizes around three tiers: integrated pharmaceutical conglomerates with toxin-filler portfolios, mid-scale specialists in calcium hydroxylapatite or poly-L-lactic acid formulations, and regional distributors leveraging import licensing relationships. Dominant competitive moves include securing preferred vendor status with consolidated clinic networks and restructuring clinical evidence packages to address MDR biocompatibility endpoints.
Within the integrated portfolio tier, Galderma Pharma SA and Merz Pharma exemplify archetypes combining dermal filler and neuromodulator offerings. Galderma anchors a position through sustained engagement with United States dermatology clinic chains seeking standardized product menus. Merz occupies a specialist position in biosynthetic microsphere technology. Among hyaluronic acid-focused laboratories, Teoxane Laboratories represents the dynamic facial zone specialization archetype with formulations designed for high-mobility tissue applications.
| Leading Market Players |
|---|
| Allergan plc (AbbVie Inc.) |
| Galderma Pharma SA |
| Merz Pharma |
| Teoxane Laboratories |
| Sinclair Pharma |
| Laboratories Vivacy SAS |
| Suneva Medical Inc. |
| Integra Lifesciences |
| Zimmer Aesthetics |
| Others |
Supply & Pricing Matrix
Cross-linked hyaluronic acid fermentation technology is displacing traditional extraction methods, simultaneously compressing per-unit production costs and concentrating pharmaceutical-grade sodium hyaluronate capacity within Chinese and Japanese bioreactor facilities. This dual effect grants incumbent manufacturers with captive fermentation assets substantial pricing leverage over competitors dependent on spot feedstock markets.
Pricing Analysis
Volume purchasing agreements from United States dermatology clinic chains capture standard-tier hyaluronic acid formulations at contracted rates, while premium G-prime calibrated portfolios for dynamic facial zones sustain elevated margins. Price differentiation rests on documented rheological profiles and FDA premarket approval status rather than brand heritage alone. Pricing pressure stems from reimbursement compression hitting independent aesthetic practitioners, who now represent the most price-sensitive buyer segment. Consolidated medspa networks extract least-sensitive positioning through multi-year preferred vendor arrangements.
Supply Chain Analysis
EMA MDR certification requirements and ISO 10993 biocompatibility testing protocols gate sterile manufacturing configurations to established producers with notified body relationships, effectively filtering regional entrants. Pharmaceutical-grade sodium hyaluronate feedstock concentrates in Chinese and Japanese fermentation facilities, while finished filler formulation and aseptic filling anchor in Germany, Switzerland, and the United States. Supply chain risk centers on single-source vulnerability for streptococcal fermentation capacity subject to biosafety containment disruptions. Distribution runs through specialized medical device distributors holding import licensing relationships with consolidated clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived HA feedstock concentration props pricing power for manufacturers with captive bioreactor capacity, creating a supply-constrained environment where capacity additions lag demand expansion from medspa network rollouts.
For Market Incumbents: Anchor preferred vendor status through integrated toxin-filler portfolio contracts with United States multi-site dermatology chains facing procurement consolidation pressure. Defend against autologous fat transfer substitution by expanding hyaluronidase reversal training infrastructure that permanent implants cannot replicate. Prioritize backward integration into pharmaceutical-grade sodium hyaluronate fermentation to secure feedstock autonomy against Chinese and Japanese supply volatility. For New Entrants and Emerging Players: Launch via import licensing partnerships with Mumbai and Delhi hospital chains establishing dedicated cosmetic dermatology departments as CDSCO streamlines established brand approvals. Target India's nascent aesthetic infrastructure where domestic fermentation capacity remains limited and pricing tolerance exceeds mature markets. Pursue white-space positioning in combination toxin-filler protocols requiring coordinated formulation development that incumbents address through bundled portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical conglomerates seeking dermal filler additions to neuromodulator portfolios. Long-term viability favors manufacturers with EUDAMED serialization infrastructure and MDR-compliant clinical evidence packages already submitted. Watch for hyaluronidase reversal adoption rates in Brazil's high-risk anatomical zone applications as signal of irreversible filler displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Expansion | EMA MDR reclassification extended review timelines to 24 months, privileging established CE marking holders. |
| Rheology-Matched Portfolio Development | United States clinic chains standardize G-prime documented formulations across multi-site operations. |
| Hyaluronidase Reversal Training Infrastructure | Brazilian practitioners now employ reversible fillers in anatomical zones previously reserved for surgery. |
| Fermentation Capacity Addition | Chinese and Japanese bioreactor concentration creates single-source vulnerability for pharmaceutical-grade HA feedstock. |
| Digital Consultation Platform Partnership | South Korean mobile applications facilitate virtual assessment for international medical tourists seeking toxin-filler protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across aesthetic practitioners, dermatology clinic procurement directors, biomedical engineers, and GPO contracts managers. FDA 510(k) and PMA submissions, EMA MDR technical documentation, ANVISA import licensing records, and MFDS registration databases provided cross-referenced validation. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures.
Granularity-level modeling captured product type, application indication, end-user facility type, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating hyaluronic acid formulation share shifts, calcium hydroxylapatite preference patterns in Brazil, and poly-L-lactic acid staged treatment protocol adoption. Forecast inputs included medspa network expansion rates, MDR implementation timeline assumptions, and fermentation capacity utilization indicators.
Regulatory enforcement intensity shifts, biosafety containment incidents at fermentation facilities, and clinic network consolidation pace are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding EUDAMED serialization infrastructure deployment and practitioner training curriculum standardization. A model refresh is warranted upon material change in notified body review timeline guidance or hyaluronidase reversal protocol adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Japan Facial Aesthetics Market