
 Aesthetic Lasers and Energy Devices Market | 2026-2036
Aesthetic Lasers and Energy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetic Lasers and Energy Devices Market Intelligence
Diode laser arrays are repositioning legacy ruby and alexandrite platforms in hair removal systems by delivering comparable efficacy at lower per-treatment energy costs. Cynosure leverages integrated cooling technologies to sustain premium positioning across dermatology channels. Cutera anchors its portfolio in multi-wavelength platforms that compete across skin resurfacing and body contouring indications. Alma Lasers dominates Asian distribution networks through localized manufacturing and region-specific regulatory registrations.
Aesthetic lasers and energy devices comprise solid-state, gas, and semiconductor-based systems emitting coherent or filtered broadband energy at wavelengths from 532 nm to 10,600 nm, designed to selectively target chromophores in dermal and subcutaneous tissue for therapeutic or cosmetic modification. Fractional CO2 and erbium laser platforms command the highest per-unit pricing within skin resurfacing, while intense pulsed light systems occupy higher-volume, lower-margin positions in pigmentation and vascular applications. Nd:YAG technology leads tattoo removal and hair reduction in darker skin phototypes where melanin absorption profiles demand longer wavelengths.
FDA 510(k) premarket notification and EU MDR conformity assessment create dual-track compliance burdens that filter smaller manufacturers from transatlantic distribution. China's NMPA medical device registration and South Korea's MFDS quality system requirements add further jurisdiction-specific testing protocols for optical output stability and biocompatibility. Stakeholders must monitor evolving energy-based device classification thresholds under FDA draft guidance and EU harmonized standards that could reclassify fractional systems to higher-risk categories.
Market Dynamics
Diode laser arrays are systematically eroding installed bases of ruby and alexandrite platforms across hair removal applications, compressing capital recovery timelines for legacy equipment holders and forcing accelerated refresh cycles in clinic networks.
Growth Catalysts
- FDA 510(k) streamlined pathways:Pre-market notification frameworks for laser-based devices accelerate clearance timelines for fractional and diode platforms, enabling faster commercialization of next-generation systems in US dermatology channels.
- Non-invasive procedure displacement:Body contouring and skin tightening applications are capturing volume from surgical liposuction and facelift procedures, redirecting capital expenditure toward energy-based devices in medical aesthetics clinics.
- Asian manufacturing localization:China and South Korea-based production facilities reduce per-unit landed costs for diode arrays and IPL handpieces, expanding addressable clinic tiers in Southeast Asian and Middle Eastern markets.
Market Restraints
- Optical component supply concentration:German and Japanese suppliers dominate precision lens and fiber-coupled diode manufacturing, creating input bottlenecks during demand surges.
- EU MDR conformity assessment burdens:Reclassification of fractional ablative systems under higher-risk categories extends technical documentation timelines and notified body queue delays.
- Intense pulsed light substitution pressure:Lower-cost IPL platforms capture pigmentation and vascular indications from laser systems in price-sensitive clinic tiers.
Strategic Opportunities
- India clinic network expansion:Tier-2 and Tier-3 city dermatology chains remain underpenetrated by fractional CO2 and radiofrequency platforms, offering first-mover positioning for localized service models.
- Combination therapy device convergence:Integrated platforms pairing 1,064 nm Nd:YAG with bipolar radiofrequency address cellulite and skin laxity in single sessions, commanding premium placement in high-volume aesthetics chains.
- China NMPA registration reciprocity:Streamlined approval pathways for devices already cleared by FDA or CE marking reduce duplicate clinical testing costs for manufacturers targeting domestic clinic procurement.
Industry Challenges
- Laser safety officer certification gaps:Clinic chains in emerging markets face shortages of credentialed technicians for Class 4 laser operation, limiting device utilization rates and creating liability exposure.
- Legacy system integration complexity:Proprietary software protocols from incumbent manufacturers obstruct third-party maintenance and consumable sourcing, locking clinics into elevated service contracts.
- Biocompatibility testing timeline compression:EU MDR requirements for updated ISO 10993 testing on handpiece materials extend product update cycles beyond typical technology refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetic Lasers and Energy Devices Market |
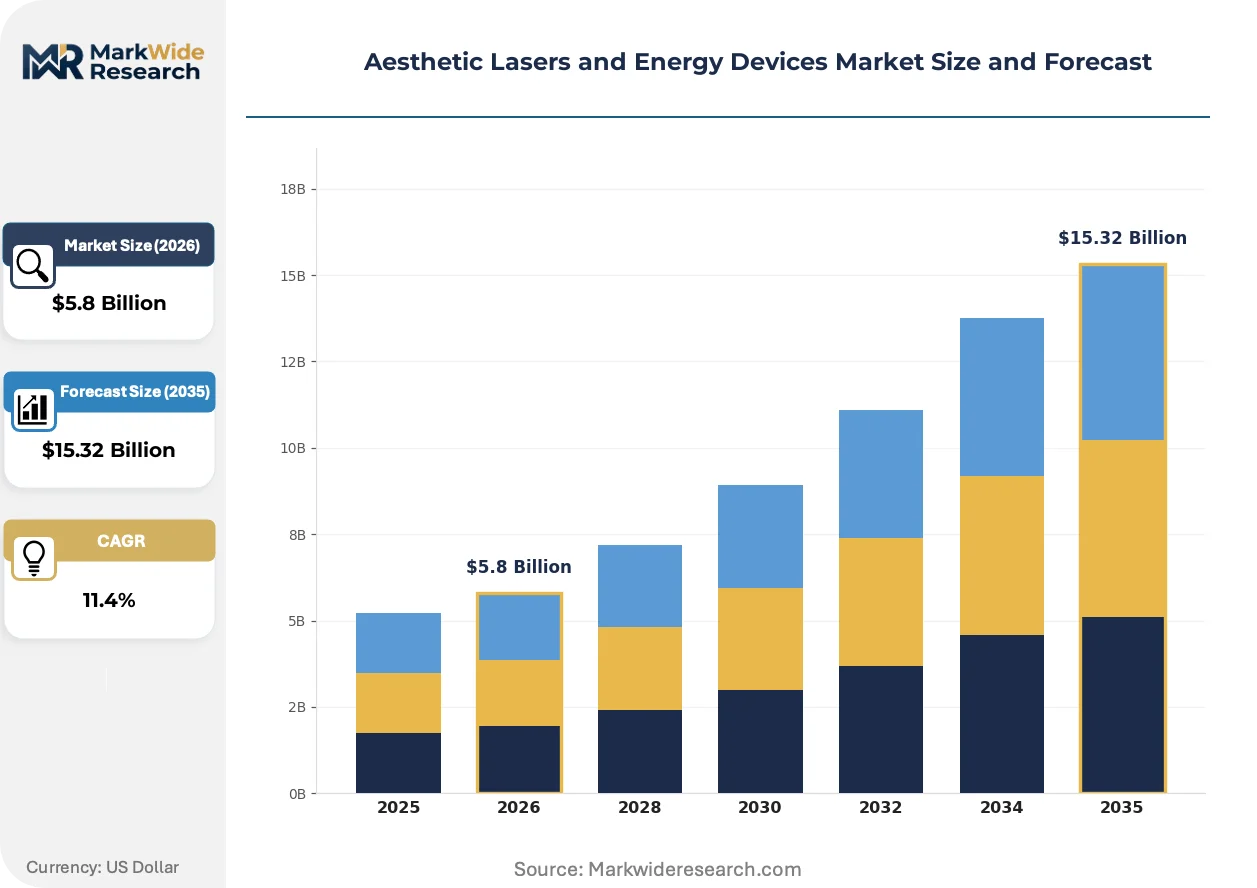
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Hair Removal, Skin Resurfacing, Body Contouring, Cellulite Treatment Technology: CO2 Laser, Nd:YAG Laser, Fractional Laser, Intense Pulsed Light End User: Dermatology Clinics, Cosmetic Surgery Centers, Spas, Medical Aesthetics Clinics Application: Acne Scar Treatment, Tattoo Removal, Skin Tightening, Pigmentation Removal |
| Companies Covered | Cynosure, Cutera, Lumenis, Alma Lasers, Candela Medical, Sciton, Fotona, Lutronic, Aerolase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetic Lasers and Energy Devices Market Strategic Shifts & Innovations
Hardware commoditization is compressing margins on standalone laser platforms while software-defined treatment protocols and integrated cooling systems emerge as primary differentiation vectors.
Picosecond-domain solid-state lasers are overtaking Q-switched Nd:YAG systems in tattoo removal applications by fragmenting ink particles more efficiently at shorter pulse durations. High-volume tattoo removal chains in the United States and Germany are retrofitting existing treatment rooms with picosecond platforms at accelerated replacement cycles. This technology shift is compressing residual value of installed Q-switched bases and forcing manufacturers to bundle trade-in programs with new system sales.
EU MDR harmonized standards for energy-based devices are tightening clinical evidence requirements for fractional ablative systems previously cleared under lighter predicates. Manufacturers must now generate prospective clinical data on adverse event profiles to maintain CE marking, extending time-to-market for platform refreshes by twelve to eighteen months. Dermatology device portfolios with heavy fractional CO2 exposure face disproportionate compliance burdens relative to non-ablative alternatives.
Clinic procurement committees are consolidating vendor relationships around single-source platforms offering multi-wavelength modularity, displacing the prior practice of acquiring best-of-breed devices per indication. Large aesthetics chains in South Korea and Brazil now demand unified service contracts spanning hair removal, vascular, and resurfacing modalities from single manufacturers. This concentration pattern favors integrated platform developers while squeezing specialized single-application device vendors from enterprise-tier accounts.
Aesthetic Lasers and Energy Devices Market Segmentation
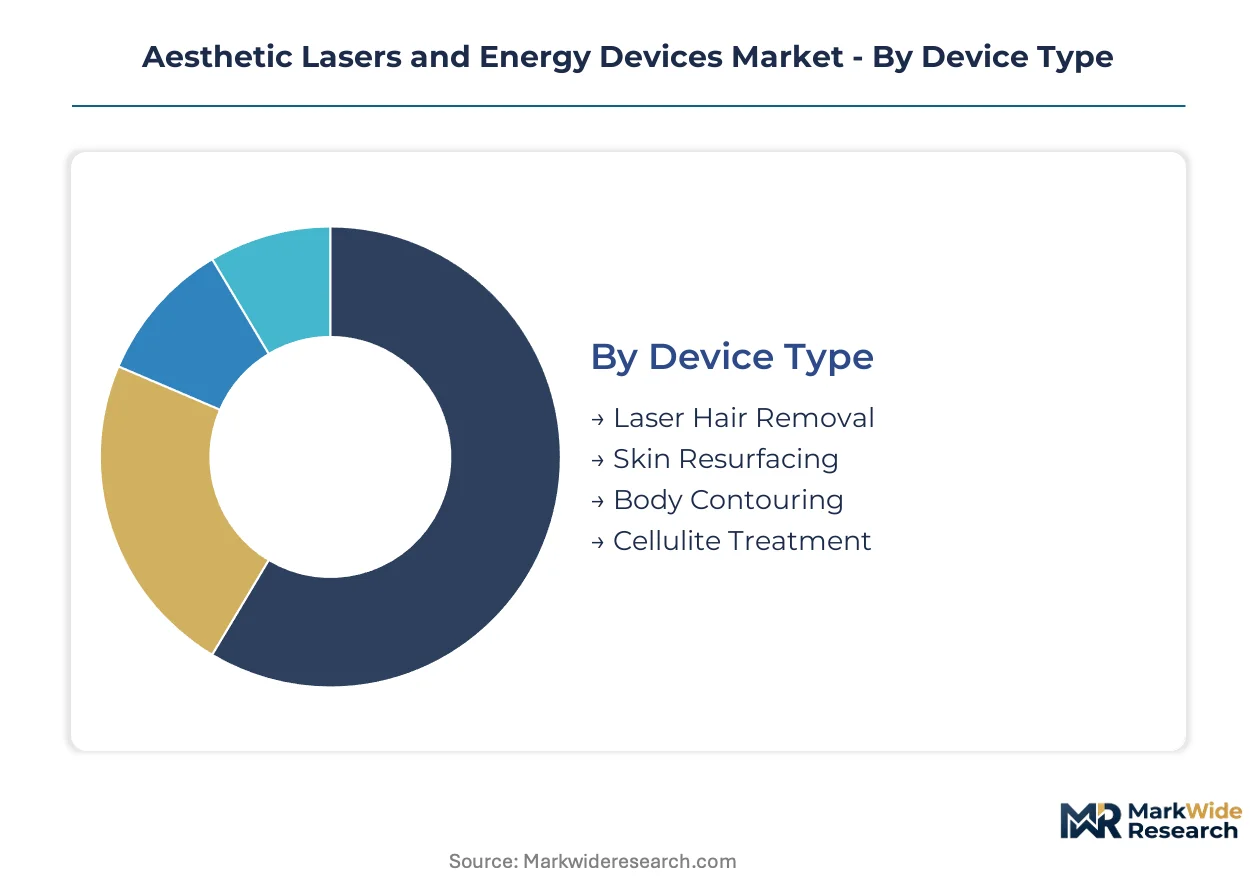
Capital allocation across device categories reflects divergent reimbursement profiles and utilization economics in aesthetic medicine. Procurement committees weight initial system cost against consumable attach rates and service contract terms when segmenting vendor portfolios.
Device Type:
Capital intensity varies sharply across modalities, with ablative platforms demanding 3-4x the upfront investment of non-ablative alternatives and compressing payback timelines in high-volume settings.
- Laser Hair Removal:Diode and alexandrite arrays dominate installed bases with high shot counts per handpiece. Demand concentrates in South Korean and Brazilian clinic chains where package pricing models depend on rapid treatment throughput. Per-pulse energy costs now determine vendor selection more than acquisition price alone.
- Skin Resurfacing:Fractional CO2 and erbium platforms command premium positioning through adjustable ablation depths. United States dermatology groups prioritize systems with integrated cooling to minimize downtime liability. Capital recovery extends 24-36 months versus 12-18 months for hair removal modalities.
- Body Contouring:Radiofrequency and cryolipolysis systems compete for non-invasive fat reduction volume.
- Cellulite Treatment:Subcision laser and acoustic wave platforms occupy niche positioning with limited reimbursement pathways.
Laser Hair Removal absorbs the bulk of installed capacity; Body Contouring is expanding most quickly.
Technology:
Wavelength specificity determines chromophore targeting precision and directly correlates with malpractice exposure in darker skin phototypes.
- CO2 Laser:10,600 nm emission enables controlled thermal ablation for deep resurfacing indications. United States academic medical centers maintain training programs around superpulsed variants. FDA 510(k) predicates for fractional delivery systems have tightened clinical evidence requirements under recent draft guidance.
- Nd:YAG Laser:1,064 nm penetration suits tattoo removal and hair reduction in Fitzpatrick types IV-VI. Chinese NMPA registrations for Q-switched platforms require optical stability testing under GB standards. Longer pulse durations reduce epidermal injury risk but demand higher fluence per treatment.
- Fractional Laser:Microthermal zone technology spans ablative and non-ablative variants with adjustable density parameters.
- Intense Pulsed Light:Filtered broadband sources occupy higher-volume, lower-margin positioning across pigmentation and vascular applications.
CO2 Laser platforms carry the heaviest capital burden; Fractional Laser configurations are gaining share fastest.
End User:
Procurement authority concentrates in physician-owned networks with centralized capital committees, displacing independent clinic purchasing autonomy.
- Dermatology Clinics:Board-certified practices prioritize FDA-cleared platforms with established adverse event profiles. United States multi-site groups negotiate enterprise pricing across 15-50 unit deployments. Malpractice carriers mandate laser safety officer certification for Class 4 system operation.
- Cosmetic Surgery Centers:Ambulatory surgical facilities integrate energy devices into pre- and post-operative protocols. South Korean hospital-affiliated aesthetics departments require MFDS quality system documentation for all capital equipment. Reimbursement coding complexity favors bundled procedure pricing.
- Spas:Non-medical settings face regulatory restrictions on device intensity parameters in most jurisdictions.
- Medical Aesthetics Clinics:Standalone facilities compete on device novelty and technician certification visibility.
Dermatology Clinics anchor procurement volume; Medical Aesthetics Clinics are scaling fastest.
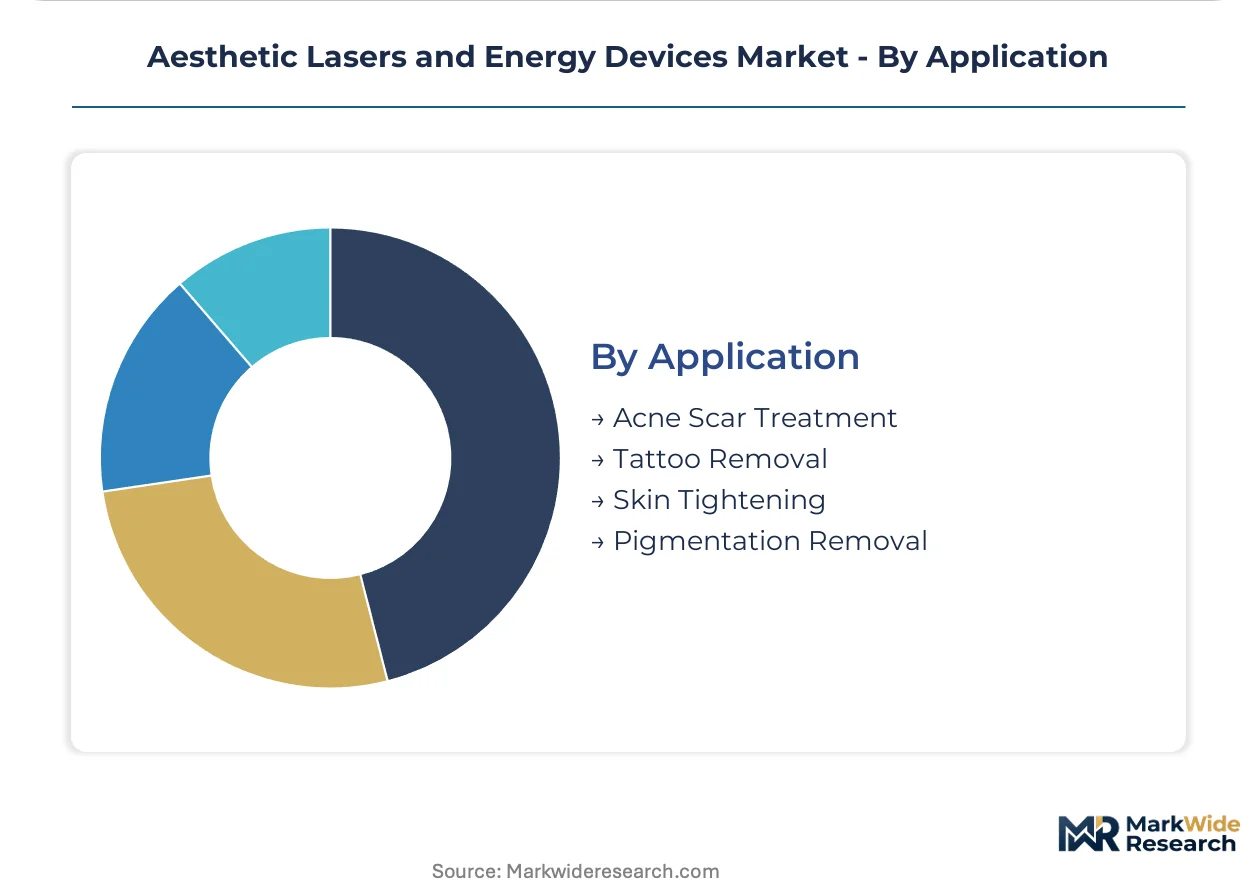
Application:
Indication-specific efficacy data increasingly determines payer coverage and consumer willingness to pay premium pricing.
- Acne Scar Treatment:Fractional laser and radiofrequency microneedling command premium positioning through collagen remodeling evidence. German dermatology practices publish prospective outcome data to support CE marking under EU MDR. Treatment protocols require 3-6 sessions with 4-6 week intervals.
- Tattoo Removal:Picosecond-domain solid-state systems are displacing Q-switched Nd:YAG in high-volume chains. United States removal specialists in Florida and Texas retrofit treatment rooms at accelerated replacement cycles. Ink particle fragmentation efficiency reduces total session counts by 30-40 percent.
- Skin Tightening:Radiofrequency and ultrasound platforms compete for non-surgical facelift alternatives.
- Pigmentation Removal:IPL and Q-switched lasers address solar lentigines and melasma with varying recurrence rates.
Acne Scar Treatment captures the highest per-procedure pricing; Tattoo Removal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Incheon Free Economic Zone concentrates aesthetic device manufacturing through tax incentives and duty-free imports on optical components. Clinic chains in Seoul deploy capital equipment at density levels unmatched elsewhere.
United States
Dermatology groups in Texas and Florida drive fractional laser procurement through high-volume aesthetic surgery demand. FDA 510(k) clearance pathways for diode and CO2 platforms enable faster commercialization than transatlantic alternatives. Miami-Dade and Orange County clinic clusters operate Class 4 systems under mandatory laser safety officer protocols.
Germany
EU MDR conformity assessment timelines shape device launch sequencing for manufacturers targeting European dermatology networks. REACH compliance on optical coatings and handpiece materials adds regulatory layers absent in other jurisdictions. Munich and Düsseldorf host precision optics suppliers serving fractional ablative system builders.
China
NMPA medical device registration reciprocity with FDA and CE marking reduces duplicate clinical testing for diode laser platforms. Domestic manufacturing in Jiangsu and Guangdong provinces cuts per-unit landed costs for IPL handpieces. Shanghai clinic chains negotiate enterprise pricing on multi-wavelength systems at scale.
South Korea
MFDS quality system requirements for optical output stability testing filter smaller manufacturers from hospital-affiliated aesthetics departments. Seoul Capital Area clinic density supports rapid capital recovery on hair removal and body contouring platforms. Busan-Ulsan manufacturing clusters produce diode arrays for regional export.
Brazil
ANVISA medical device registration creates compliance bottlenecks for fractional laser imports while favoring established distributors with local technical service infrastructure. São Paulo and Rio de Janeiro clinic chains demand Portuguese-language training protocols and maintenance contracts. Hair removal package pricing models depend on high shot-count diode systems.
Aesthetic Lasers and Energy Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform developers commanding enterprise-tier accounts while single-application vendors retreat to mid-market clinics. The vendor base concentrates around three strategic archetypes: multi-wavelength portfolio builders, regional distribution specialists with localized regulatory registrations, and precision component suppliers with captive diode manufacturing. M&A activity targets optical technology acquisitions and geographic footprint expansion into underpenetrated clinic networks.
Within the integrated platform tier, Cynosure and Cutera exemplify archetypes competing across dermatology channels through differentiated cooling and wavelength strategies. Alma Lasers occupies a position as a regional distribution anchor with Asian manufacturing localization. These three companies represent the dominant competitive positioning vectors in medical aesthetics procurement.
| Leading Market Players |
|---|
| Cynosure |
| Cutera |
| Lumenis |
| Alma Lasers |
| Candela Medical |
| Sciton |
| Fotona |
| Lutronic |
| Aerolase |
| Others |
Cost & Logistics Intelligence
EU MDR biocompatibility testing mandates under ISO 10993 standards gate qualified supply of handpiece materials and optical coatings, restricting vendor pools capable of serving premium-tier clinic procurement while sustaining elevated pricing for compliant platforms.
Pricing Analysis
Lead-time compression commands premium positioning in aesthetic laser procurement, with clinics paying marked-up rates for fractional CO2 platforms available under twelve-week delivery windows while spot inventory of diode arrays trades at discounted clearing levels. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and integrated cooling sophistication, with dermatology chains least sensitive to acquisition cost and med-spa networks most responsive to per-pulse energy economics. Price differentiation hinges on optical output stability certification and geographic service density. Margins are tightening due to IPL substitution in pigmentation applications.
Supply Chain Analysis
CE marking and FDA 510(k) qualification requirements filter optical component suppliers, with German precision lens manufacturers and Japanese fiber-coupled diode fabricators anchoring qualified supply bases for fractional and Nd:YAG platforms. Raw material flows draw from rare-earth mineral processing in China, sapphire substrate production in Russia and Ukraine, and germanium lens grinding in Japan. Single-source vulnerability concentrates in erbium-doped fiber amplifiers for advanced resurfacing systems. Distribution runs through authorized dealer networks with mandatory laser safety officer training bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision optics fabrication capacity constraints in Germany and Japan prop pricing power for qualified suppliers serving FDA-cleared platform builders.
For Market Incumbents: Lock in multi-year supply agreements with Japanese diode array manufacturers before capacity allocation tightens further. Acquire regional service capabilities in India and Southeast Asia to preempt emerging entrants from capturing clinic network expansion. Picosecond tattoo removal substitution threatens Q-switched Nd:YAG installed bases; accelerate trade-in program deployment to retain account control. For New Entrants and Emerging Players: Picosecond-domain solid-state architecture offers technology-first wedge into high-volume tattoo removal chains in Florida and Texas where replacement cycles compress. Target tier-2 Indian dermatology networks with localized Mandarin and Portuguese training protocols absent from incumbent portfolios. Pursue China NMPA registration reciprocity to bypass duplicate clinical testing costs. For Investors and Strategic Acquirers: MFDS adverse event disclosure spikes in Seoul clinic networks are the leading indicator that Korean regulatory scrutiny is intensifying for fractional ablative platforms, compressing valuations for non-compliant portfolios. Long-term viability favors integrated platform developers with captive cooling technology and multi-wavelength modularity. Acquisition target archetype: regional distribution specialists with localized registrations in underpenetrated Southeast Asian markets. Watch FDA draft guidance on fractional system reclassification as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment timelines determine competitive sequencing for European dermatology networks. |
| Hospital System Partnership | South Korean MFDS-compliant platforms secure preferred vendor status in Seoul Capital Area aesthetics departments. |
| Software Companion Development | AI-guided treatment parameter optimization differentiates premium platforms in United States multi-site clinic chains. |
| Reimbursement Strategy | Coding complexity for non-invasive body contouring shapes capital committee prioritization in cosmetic surgery centers. |
| Geographic Manufacturing Footprint | Jiangsu and Guangdong production localization cuts landed costs for IPL handpieces serving Southeast Asian expansion. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by structured interviews with biomedical engineers, dermatology clinic procurement directors, GPO contracts managers, and laser safety officers across United States, German, and South Korean markets. Primary fieldwork combined with FDA 510(k) clearance databases, NMPA registration records, EU MDR notified body documentation, and optical component import manifests. Bottom-up device shipment modeling triangulated against top-down clinic capital expenditure surveys.
Granularity-level modeling deployed wavelength-specific demand curves, skin phototype indication penetration rates, and regional regulatory cluster dynamics across the analysis window. Segmentation dimensions included device modality, ablative versus non-ablative technology tier, end-user facility type, and application-specific utilization intensity. CAGRs derived from installed base replacement cycles and clinic network expansion trajectories. Forecast inputs incorporated shot-count depreciation schedules and handpiece consumable attach rates.
Several conditions sit outside the modeled scope, including speculative reclassification of fractional systems under FDA draft guidance and raw material export restrictions on rare-earth elements. Forecasts reflect assumptions on optical component supply stability and clinic technician certification pipeline adequacy. A model refresh is warranted upon material change in EU MDR harmonized standards implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Australia Facial Injectable Market