
 Special Coagulation Tests Market | 2026-2036
Special Coagulation Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Special Coagulation Tests Market Analytics
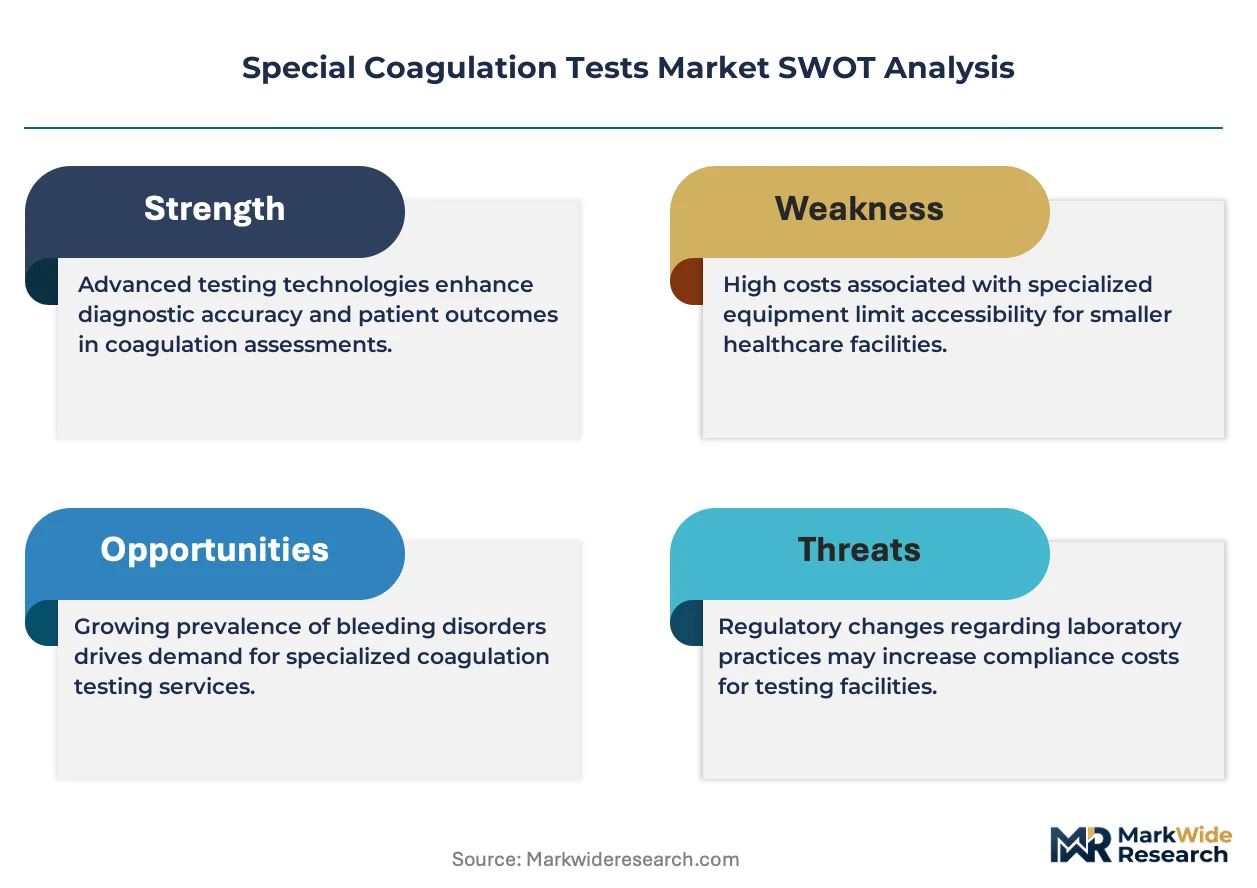
Modular assay bundling is restructuring how hospitals procure coagulation testing panels, shifting from standalone reagent contracts toward integrated platform agreements. Siemens Healthineers leverages its broad automation portfolio to anchor multi-year supply relationships with large health systems. Roche competes through high-throughput analyzer placements that sustain recurring consumable revenue streams. Diagnostica Stago specializes in hemostasis depth, occupying the premium tier for specialized thrombophilia and bleeding disorder diagnostics.
Special coagulation tests measure specific parameters of the blood clotting cascade, including prothrombin time (PT), activated partial thromboplastin time (APTT), fibrinogen concentration, and D-dimer levels, typically employing optical or mechanical detection methods with precision thresholds of 0.1 seconds for time-based assays. These tests serve critical functions in perioperative risk assessment, anticoagulant therapy monitoring, and thrombotic disorder diagnosis across acute and ambulatory care settings. The product type dimension shows D-dimer assays capturing expanding share in pulmonary embolism rule-out protocols, while the delivery mode segment reveals point-of-care testing generating premium pricing despite lower throughput, as hospitals prioritize rapid turnaround for emergency department triage. Application segmentation indicates surgical procedures and trauma management representing the most concentrated demand pools, though hematological disorder testing commands superior margins due to lower test commoditization.
FDA oversight of in vitro diagnostic devices shapes assay validation timelines and clinical claim substantiation, while the Clinical Laboratory Improvement Amendments (CLIA) govern laboratory accreditation and personnel competency standards that directly affect test deployment feasibility. The European Union's In Vitro Diagnostic Regulation (IVDR) is forcing manufacturers to rebuild technical documentation and clinical evidence packages, creating compliance cost barriers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor how consolidated purchasing by US hospital networks and European hospital federations reshapes contract structures, pricing leverage, and platform loyalty commitments across the forecast horizon.
Market Dynamics
Automated coagulation analyzer platforms are consolidating hospital laboratory purchasing decisions, shifting procurement from discrete reagent contracts toward multi-year integrated supply agreements that lock in platform loyalty and consumable recurring revenue.
Growth Catalysts
- Perioperative Screening Protocols:Surgical departments in US integrated health networks are mandating pre-surgical coagulation panels, expanding test volumes for thrombosis risk stratification and bleeding disorder detection.
- FDA Guidance Acceleration:The FDA's updated in vitro diagnostic device validation requirements are compressing assay development timelines, enabling faster commercialization of novel coagulation biomarkers for specialized indications.
- Point-of-Care Testing Expansion:Emergency departments are deploying compact coagulation analyzers for rapid D-dimer and PT/INR turnaround, prioritizing triage speed over laboratory throughput.
Market Restraints
- IVDR Compliance Burden:The European Union's In Vitro Diagnostic Regulation is forcing manufacturers to rebuild technical documentation and clinical evidence packages, creating capital-intensive barriers for smaller assay developers.
- Reagent Supply Concentration:Critical coagulation reagents depend on specialized protein fractionation facilities concentrated in Western Europe, exposing supply chains to geopolitical and logistics disruptions.
- Optical Detection Limitations:Lipemic and icteric sample interference in optical coagulation methods necessitates manual sample preprocessing, constraining full automation in high-volume settings.
Strategic Opportunities
- India's Diagnostic Infrastructure Buildout:The country's PLI scheme for medical device manufacturing is attracting coagulation analyzer assembly investments, creating localized supply for tier-2 and tier-3 hospital networks.
- AI-Assisted Result Interpretation:Machine learning algorithms trained on coagulation cascade patterns are converging with analyzer software to flag abnormal thrombosis risk profiles for hematologist review.
- Home Anticoagulation Monitoring:Direct-to-patient channels for portable INR testing devices are opening compliance monitoring opportunities outside traditional laboratory settings.
Industry Challenges
- Specialized Hematopathologist Shortage:Interpretation of complex coagulation profiles requires subspecialty expertise that academic medical centers struggle to recruit and retain.
- Legacy Analyzer Integration:Health systems running mixed-vendor coagulation platforms face middleware compatibility hurdles when consolidating data into enterprise laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Coagulation Tests Market |
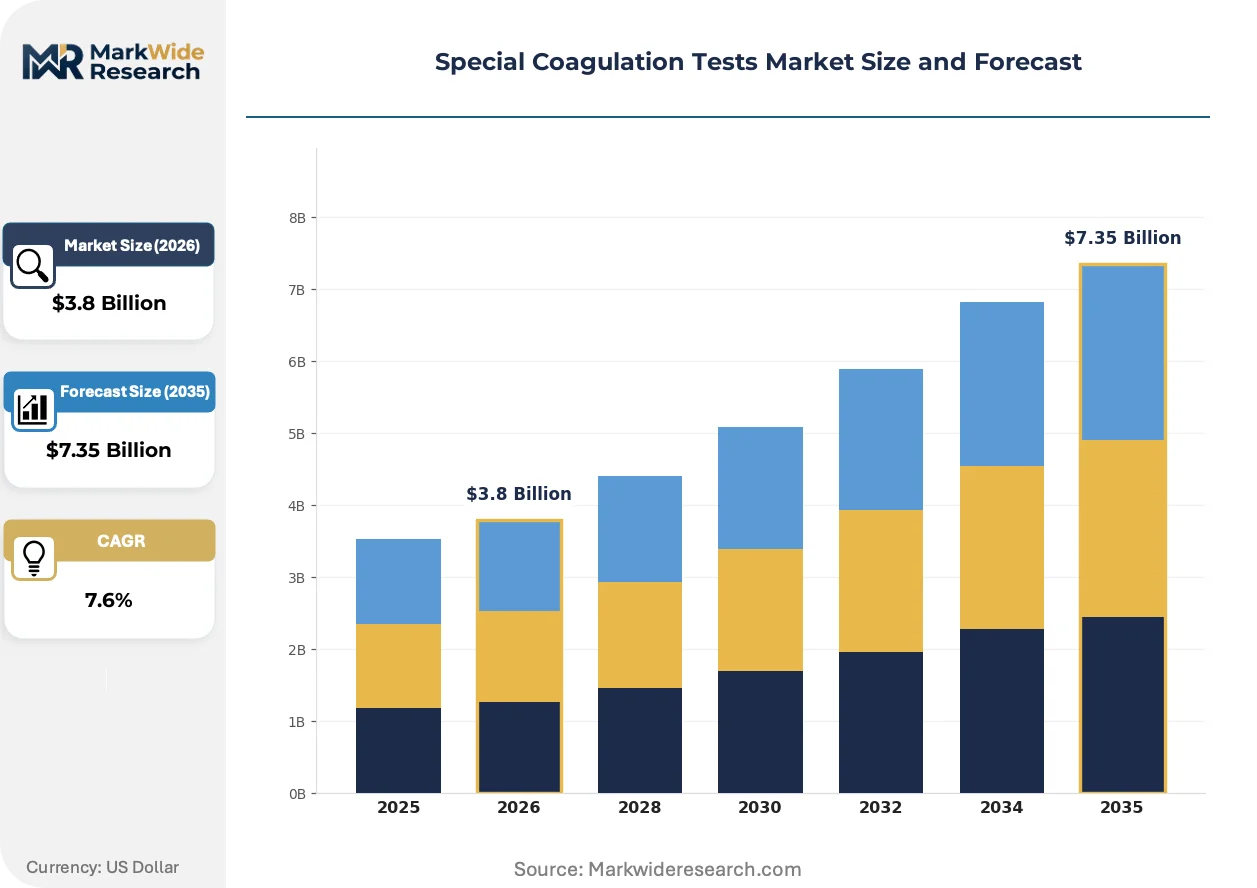
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PT, APTT, Fibrinogen, D-dimer Application: Surgical Procedures, Trauma Management, Hematological Disorders, Disease Diagnosis End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutes Delivery Mode: Point-of-Care Testing, Laboratory Testing, Home Testing, Automated Systems |
| Companies Covered | Roche, Abbott Laboratories, Sysmex Corporation, Siemens Healthineers, Diagnostica Stago, Werfen, Instrumentation Laboratory, Helena Laboratories, HemoSonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Coagulation Tests Market Evolving Landscape
Coagulation testing is migrating from centralized laboratory hubs toward distributed diagnostic nodes, driven by miniaturization of mechanical detection systems and pressure for emergency department throughput.
Mechanical clot detection technology is electrifying the standardization of coagulation results across variable sample conditions. Hospital laboratories in Germany and Switzerland are replacing legacy optical systems with viscoelastic and mechanical endpoint methods at accelerated replacement cycles. This technology shift is compressing inter-laboratory coefficient of variation for critical assays like fibrinogen and D-dimer, enabling network-wide harmonization of anticoagulant therapy protocols.
The European Union's In Vitro Diagnostic Regulation is restructuring competitive positioning for coagulation assay manufacturers. Technical documentation requirements for Class C and D devices now demand prospective clinical studies that extend validation timelines by 18-24 months. Specialized thrombophilia and bleeding disorder test panels face the steepest compliance burden, favoring established manufacturers with dedicated regulatory affairs infrastructure over emerging competitors.
Integrated health networks in the United States are consolidating coagulation testing procurement through enterprise-level platform agreements. Single-source contracts spanning analyzers, reagents, and service are displacing fragmented purchasing across individual hospital laboratories. This concentration is most visible in the Southeast and Midwest, where Catholic health systems and for-profit chains are standardizing on unified coagulation automation platforms to capture volume-based consumable discounts.
Special Coagulation Tests Market Segmentation
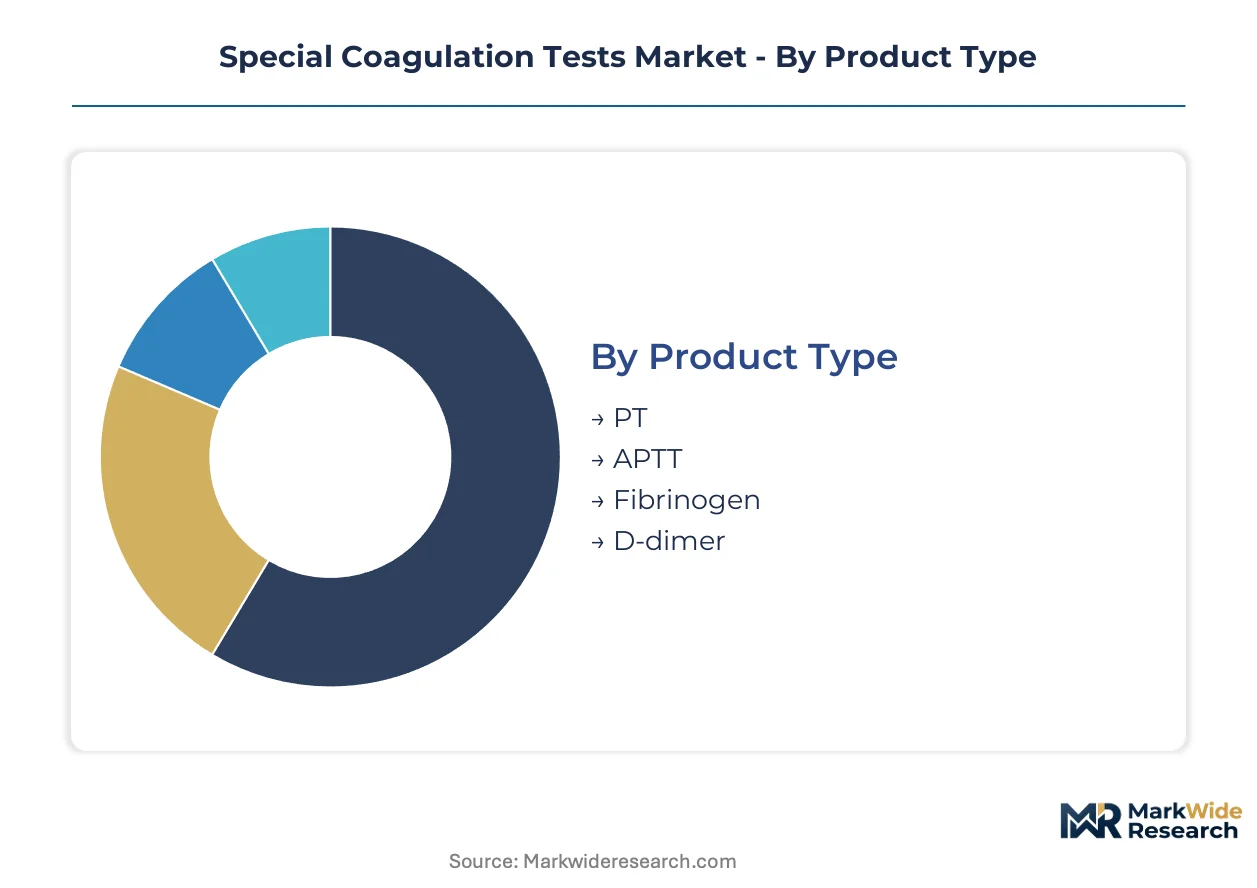
Segmentation in special coagulation testing reveals how procurement concentration and clinical workflow requirements reshape vendor strategies. Each dimension exposes distinct margin structures and technology substitution patterns that determine competitive positioning.
Product Type:
Supply concentration in coagulation reagent manufacturing favors assay platforms with captive protein fractionation capabilities and integrated detection systems.
- D-dimer:This fibrin degradation product assay employs latex-enhanced immunoturbidimetric detection with diagnostic cutoffs calibrated for pulmonary embolism exclusion protocols. Emergency departments in US integrated health networks are embedding D-dimer into rapid triage algorithms, compressing turnaround time requirements below 30 minutes.
- PT:Prothrombin time testing measures extrinsic pathway clotting factors using thromboplastin reagents with standardized international sensitivity indices. Warfarin therapy monitoring in anticoagulation clinics sustains high test frequency, though direct oral anticoagulant adoption is displacing volume in some patient cohorts.
- APTT:Activated partial thromboplastin time assays assess intrinsic and common pathway function through contact activation methods.
- Fibrinogen:Clauss-based and PT-derived methods quantify plasma fibrinogen concentration for bleeding risk stratification.
PT absorbs the bulk of installed capacity; D-dimer is expanding most quickly.
Application:
Margin differentiation across clinical applications correlates with test complexity and the scarcity of interpreting specialists.
- Hematological Disorders:Specialized coagulation panels for hemophilia, von Willebrand disease, and rare factor deficiencies require chromogenic substrate assays and mixing studies with extended incubation protocols. Academic medical centers in Germany and Switzerland maintain dedicated hemostasis reference laboratories, commanding premium pricing due to low test commoditization and subspecialty pathologist requirements.
- Surgical Procedures:Perioperative coagulation screening employs standardized PT/APTT panels with rapid turnaround mandates. Pre-operative assessment protocols in US hospital networks are expanding test volumes as integrated health systems mandate universal thrombosis risk stratification.
- Trauma Management:Massive transfusion protocols utilize viscoelastic whole blood assays alongside conventional coagulation tests.
- Disease Diagnosis:Thrombophilia workups and disseminated intravascular coagulation panels support complex diagnostic pathways.
Surgical procedures command the highest absolute test volumes; hematological disorders deliver the steepest margin expansion trajectory.
End User:
Customer consolidation patterns determine contract structure, with platform loyalty commitments varying by procurement autonomy.
- Hospitals:Central laboratory and point-of-care coagulation operations span high-throughput automation for routine assays and compact analyzers for emergency department deployment. US hospital networks are consolidating purchasing through enterprise agreements that bundle analyzers, reagents, and service across multi-hospital systems.
- Diagnostic Laboratories:Independent and hospital-affiliated reference labs process outsourced coagulation testing with emphasis on specialized assay menus and result standardization.
- Blood Banks:Donor screening and component processing operations require coagulation factor testing for plasma-derived product manufacturing.
- Research Institutes:Translational hemostasis research drives demand for novel biomarker assays and custom assay development services.
Hospitals anchor the installed base; diagnostic laboratories are gaining share fastest through reference test outsourcing.
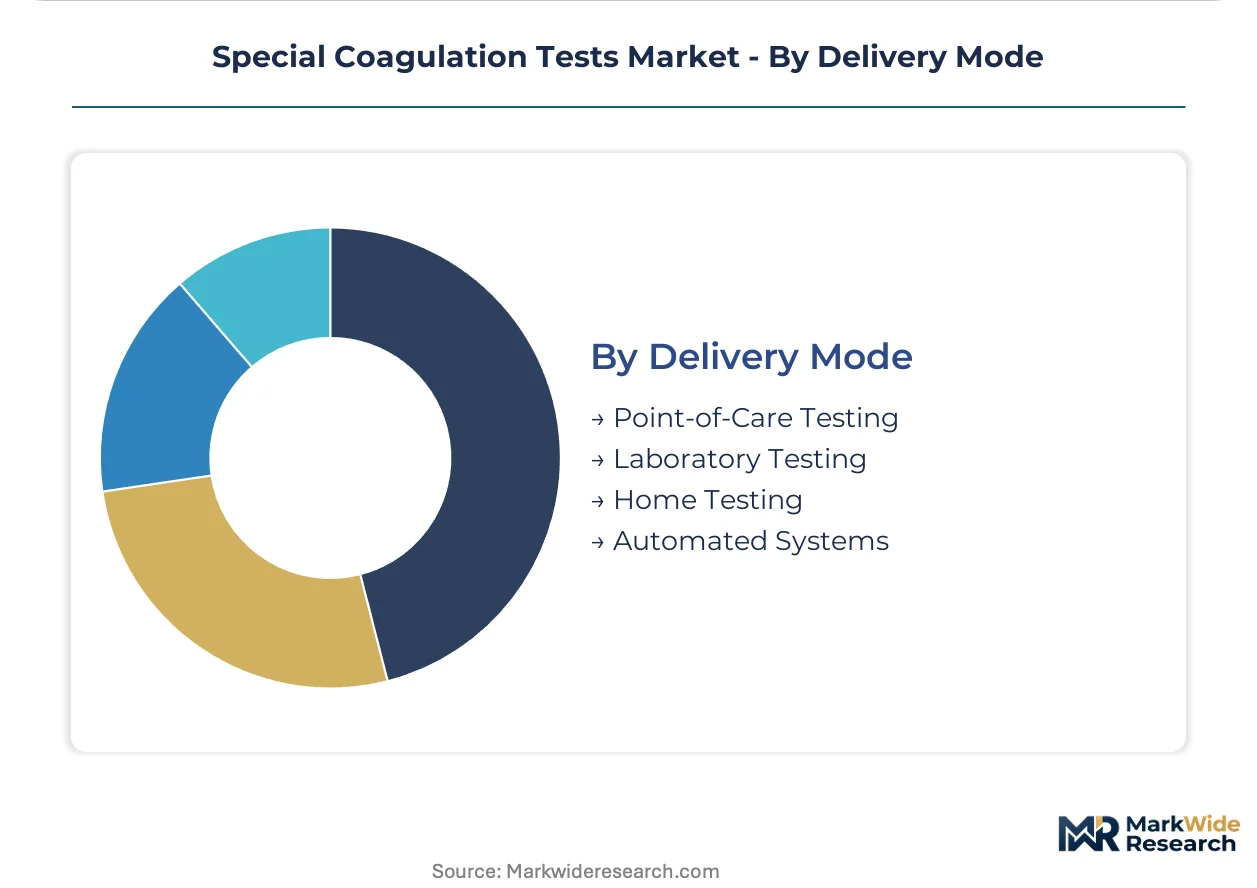
Delivery Mode:
Technology miniaturization is redistributing testing location, with workflow speed requirements overriding throughput optimization in acute care settings.
- Point-of-Care Testing:Compact coagulation analyzers employing optical or electrochemical detection deliver PT/INR and D-dimer results at the bedside or in ambulance transport. Emergency departments in the United States prioritize these devices for triage acceleration despite higher per-test costs and lower precision compared to laboratory methods.
- Automated Systems:High-throughput coagulation analyzers with random-access sampling and reflex testing algorithms dominate hospital central laboratory operations.
- Laboratory Testing:Conventional hub-and-spoke models concentrate specialized assays in reference facilities with subspecialty interpretation.
- Home Testing:Patient-operated INR monitoring devices with smartphone connectivity support oral anticoagulant compliance outside clinical settings.
Automated systems carry the majority of test volume; point-of-care testing is climbing the fastest as emergency workflow redesign accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of coagulation reagents concentrates in Western Europe, while demand growth accelerates in North America and Asia-Pacific hospital networks. This geographic split shapes regulatory compliance priorities and supply chain risk profiles across the forecast window.
United States
Integrated health networks in the Southeast and Midwest are consolidating laboratory purchasing through enterprise-level platform agreements. The FDA's updated in vitro diagnostic device guidance compresses assay validation timelines for novel biomarkers. Academic medical centers in Boston and the Research Triangle maintain dedicated hemostasis reference laboratories for specialized thrombophilia diagnostics.
Germany
Hospital federations are standardizing on mechanical clot detection systems to harmonize anticoagulant therapy protocols across network sites. The EU In Vitro Diagnostic Regulation imposes 18-24 month extensions on validation timelines for Class C and D coagulation devices. Industrial clusters in Bavaria and Baden-Württemberg host protein fractionation facilities supplying critical reagent inputs.
Switzerland
Premium-tier hemostasis diagnostics command superior margins due to subspecialty pathologist scarcity and low test commoditization. Swissmedic oversight aligns with IVDR technical documentation requirements for high-risk in vitro devices. Basel and Zurich anchor precision diagnostics manufacturing with integrated automation platform development.
India
Tier-2 and tier-3 hospital networks are expanding coagulation testing capacity through analyzer assembly investments under the PLI scheme for medical devices. CDSCO registration pathways for imported diagnostics create compliance hurdles for multinational manufacturers. Maharashtra and Karnataka are emerging as diagnostic infrastructure hubs with localized reagent production partnerships.
Japan
High-throughput automation dominates central laboratory operations in Tokyo and Osaka metropolitan hospital systems. PMDA quality management system inspections enforce stringent post-market surveillance for coagulation analyzers. The Kansai region concentrates hematology reference testing with standardized mechanical detection method adoption.
Special Coagulation Tests Market Competitive Landscape
The competitive structure tilts toward diversified diagnostics conglomerates with captive automation platforms. Three to five multinational manufacturers capture the majority of installed analyzer base and consumable recurring revenue. Two strategic archetypes dominate: broad-portfolio automation suppliers anchoring multi-year supply contracts, and specialized hemostasis depth players occupying premium niches. Competitive moves center on platform loyalty lock-in through integrated reagent agreements and regulatory compliance infrastructure scaling to absorb IVDR documentation burdens.
Among diversified diagnostics conglomerates, Roche, Siemens Healthineers, and Abbott Laboratories exemplify the automation-platform archetype. Roche occupies a position as a high-throughput analyzer supplier sustaining consumable revenue streams. Siemens Healthineers anchors multi-year supply relationships through broad automation portfolio bundling. Abbott Laboratories sits within the point-of-care testing expansion vector with compact analyzer placements for emergency department triage. Diagnostica Stago represents the specialized hemostasis depth tier, focusing on premium thrombophilia and bleeding disorder diagnostics. Werfen and Sysmex Corporation round out the competitive set with regional strength in mechanical detection systems and hematology-coagulation integration.
| Leading Market Players |
|---|
| Roche |
| Abbott Laboratories |
| Sysmex Corporation |
| Siemens Healthineers |
| Diagnostica Stago |
| Werfen |
| Instrumentation Laboratory |
| Helena Laboratories |
| HemoSonics |
| Others |
Value Network & Pricing Analysis
The EU In Vitro Diagnostic Regulation gates both qualified supply and premium-tier pricing access, forcing manufacturers to absorb 18-24 month validation extensions that compress margins on standard assays while insulating premium thrombophilia panels from price competition.
Pricing Analysis
Margin tightening in standard PT and APTT assays reflects procurement consolidation by US integrated health networks demanding volume-based consumable discounts. Three-tier pricing structure across premium, standard, and economy levels differentiates by test complexity and regulatory certification tier, with hematological disorder panels commanding substantial premiums due to subspecialty pathologist scarcity. Cost-down pressure on economy-tier reagents accelerates as hospital laboratories standardize on single-source platform agreements. Emergency departments exhibit lowest price sensitivity for point-of-care testing, prioritizing sub-30-minute turnaround over per-test cost.
Supply Chain Analysis
Dual-sourcing requirements from US hospital networks and European hospital federations mandate multi-supplier qualification for critical thromboplastin and D-dimer reagents, constraining sole-source dependencies despite Western European supply concentration. Protein fractionation facilities in Germany, Switzerland, and Austria anchor reagent manufacturing, drawing from specialized plasma-derived inputs, chromogenic substrates, and latex nanoparticle suspensions. Single-source vulnerability concentrates in Bavarian industrial clusters exposed to energy cost volatility. Distribution runs through integrated health network procurement offices and diagnostic laboratory consortiums with enterprise-level contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized coagulation testing operates as a supply-constrained market where protein fractionation capacity bottlenecks prop pricing power for manufacturers with captive reagent production.
For Market Incumbents: Deploy platform loyalty lock-in through multi-year integrated supply agreements spanning analyzers, reagents, and service to defend against point-of-care testing substitution. Deepen backward integration into protein fractionation capacity in Germany and Switzerland to secure reagent supply autonomy against IVDR compliance disruptions. For New Entrants and Emerging Players: Launch via India's PLI scheme for medical device manufacturing to capture tier-2 and tier-3 hospital network expansion with localized analyzer assembly. Target emergency department point-of-care deployment as the most penetrable segment, leveraging compact mechanical detection systems that bypass optical method interference limitations. For Investors and Strategic Acquirers: FDA guidance acceleration on novel biomarker validation is the leading indicator that specialized assay developers will command premium acquisition multiples. Mid-cap manufacturers with dedicated regulatory affairs infrastructure and established IVDR technical documentation packages represent the optimal acquisition archetype. Watch for mechanical clot detection technology adoption inflection in German and Swiss hospital federations as signal of platform replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Buildout | Prospective clinical studies for Class C and D devices extend validation timelines, favoring established manufacturers with dedicated regulatory infrastructure. |
| Mechanical Detection Platform Migration | Viscoelastic and mechanical endpoint methods compress inter-laboratory coefficient of variation for fibrinogen and D-dimer assays across German hospital networks. |
| Enterprise Procurement Consolidation | Single-source contracts spanning analyzers, reagents, and service displace fragmented purchasing across US Southeast and Midwest hospital systems. |
| Point-of-Care Emergency Department Deployment | Compact analyzers with sub-30-minute turnaround capture triage workflow redesign despite higher per-test costs than laboratory methods. |
| AI-Assisted Result Interpretation Integration | Machine learning algorithms trained on coagulation cascade patterns flag abnormal thrombosis risk profiles for hematologist review. |
Research Methodology
Document review covered FDA 510(k) filings, EU IVDR technical documentation databases, and hospital procurement contract registries, complemented by interviews with hematology laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at IVD manufacturers. Secondary validation drew from CMS Medicare reimbursement data, hospital capital expenditure disclosures, and protein fractionation industry trade statistics. Bottom-up test volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Segment-level outputs across product type, application, end user, and delivery mode dimensions were generated through structured forecasting frameworks incorporating installed base replacement cycles, reagent consumption rates per analyzer, and platform loyalty commitment durations. CAGRs were derived from regression analysis of historical test volume growth against surgical procedure expansion, anticoagulant therapy prevalence, and emergency department throughput redesign. Industry-specific inputs included thrombophilia diagnostic panel adoption curves and point-of-care testing penetration rates by hospital network type.
IVDR compliance timeline extensions, protein fractionation facility capacity constraints, and hematopathologist workforce availability are the dominant revision risks to demand and pricing assumptions. Deviation in regulatory enforcement intensity or reagent supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Fertility Testing Market
Testing Services
Blood Pressure Test Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
INR Test Meter Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Cannabis Testing Services Market