
 Europe Collagen Peptide Products Market | 2026-2036
Europe Collagen Peptide Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Collagen Peptide Products Market Foresight
German gelatin and collagen peptide producers are repositioning capacity toward higher-margin hydrolyzed grades for nutraceutical and pharmaceutical buyers. GELITA AG leverages its century-old extraction expertise and integrated bovine and porcine supply chains to dominate technical-grade supply across the continent. Rousselot sustains competitive positioning through specialized marine collagen capabilities sourced from Atlantic fisheries. Weishardt Group anchors its presence in food-grade gelatin while extending into pharmaceutical-grade peptides for tablet and capsule formulations.
Collagen peptide products comprise enzymatically hydrolyzed collagen proteins with molecular weights typically ranging from 2,000 to 5,000 Daltons, delivering bioavailable amino acids for tissue repair and functional nutrition applications. Hydrolyzed collagen dominates value generation due to its solubility profile and clean-label compatibility across beverage and powder formats. Nutraceutical applications represent the fastest-expanding demand pool, while personal care formulations in France and Italy concentrate margin capture through premium dermal positioning. Powder and liquid forms lead volume throughput, though capsules are gaining traction among health professional channels seeking precise dosing protocols.
EFSA novel food authorization pathways and EU health claims regulations govern market entry and label permissibility for collagen peptide products across member states. REACH compliance and ECHA substance registration requirements shape raw material sourcing decisions for marine and bovine feedstocks. France's ANSM and Germany's BfArM maintain distinct pharmaceutical-grade oversight that fragments compliance architecture. Stakeholders must monitor evolving EFSA opinions on collagen-specific health claims and adapt formulation strategies to preempt restrictive classification in key member states.
Market Dynamics
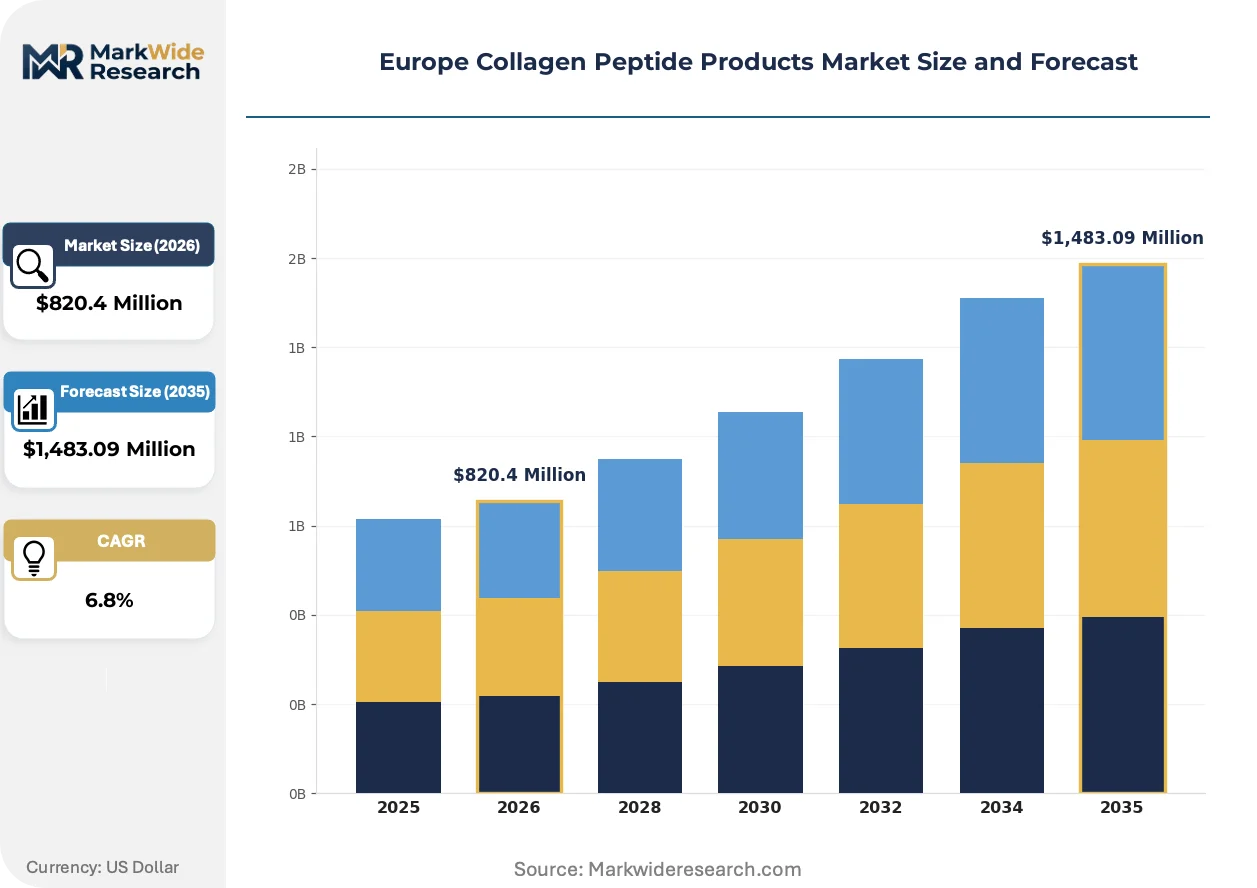
EFSA novel food authorization pathways and evolving EU health claims regulations are fragmenting product development timelines while concentrating competitive advantage among producers with established regulatory dossiers and integrated bovine supply chains.
Growth Catalysts
- REACH-compliant marine sourcing:Atlantic fishery byproduct utilization is expanding raw material availability for hydrolyzed peptide production while satisfying ECHA substance registration requirements for novel feedstock categories.
- German pharmaceutical-grade demand:BfArM-oversight tablet and capsule formulations are absorbing increasing volumes of low-endotoxin collagen peptides for joint health and wound healing applications.
- Clean-label beverage integration:Powder and liquid format compatibility is accelerating nutraceutical adoption across French and Italian functional food channels seeking solubility without stabilizer additives.
Market Restraints
- Bovine-derived input volatility:Hide and bone supply fluctuations from European abattoir consolidation are compressing margins for gelatin-based peptide producers dependent on cattle byproduct streams.
- EFSA health claim uncertainty:Pending opinions on collagen-specific beauty-from-within and joint mobility claims are freezing label permissibility investments and delaying new product launches across member states.
- Plant protein substitution:Pea and rice protein hydrolysates are capturing share in mass-market sports nutrition where collagen's amino acid profile lacks tryptophan completeness.
Strategic Opportunities
- Eastern European pharmacy channels:Poland and Romania's expanding dermocosmetic retail networks remain underpenetrated for premium marine collagen positioning versus saturated Western European markets.
- CSRD-aligned sustainable sourcing:The EU Corporate Sustainability Reporting Directive is creating procurement preference for marine collagen with fishery improvement project certification and traceable Atlantic origin.
- Precision fermentation convergence:Recombinant collagen expression technologies are opening pharmaceutical-grade supply pathways independent of animal agriculture and associated regulatory complexity.
Industry Challenges
- Multi-jurisdictional dossier management:France's ANSM pharmaceutical-grade requirements diverge from Germany's BfArM specifications, forcing parallel compliance investments for cross-border product distribution.
- Enzymatic hydrolysis capex intensity:Food-grade to pharmaceutical-grade upgrading requires dedicated cleanroom extraction capacity and validated endotoxin control systems that strain mid-capitalization producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Collagen Peptide Products Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,483.09 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Supplements, Collagen-infused Beverages Application: Nutraceuticals, Personal Care, Food & Beverages, Pharmaceuticals Form: Powder, Liquid, Capsules, Tablets Customer Type: Retail Consumers, Manufacturers, Health Professionals, Wholesalers |
| Companies Covered | GELITA AG, Rousselot, Weishardt Group, Tessenderlo Group, Nestle SA, Nutraformis Limited, Carylye, Rejuvenated Ltd, Italgelatine SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Collagen Peptide Products Market Shifts & Advancements
Peptide molecular weight customization and extraction process intensification are compressing production economics while enabling novel application formats across nutraceutical and personal care verticals.
Continuous enzymatic hydrolysis reactor technology is decentralizing production scale economics by enabling smaller-batch, higher-frequency manufacturing with reduced WIP inventory and faster specification switching for contract peptide houses serving multiple end-use segments.
EFSA's evolving position on collagen-specific health claims under Regulation (EC) No 1924/2006 is forcing reformulation toward generic structural protein messaging while concentrating R&D investment on clinical trial generation for future article 13.5 submissions in joint and skin health categories.
Professional channel preference for precise dosing protocols is displacing bulk powder dominance in German and French pharmacy settings, with capsule and stick-pack formats capturing shelf space previously occupied by canister products and driving packaging line reconfiguration investments among contract manufacturers.
Europe Collagen Peptide Products Market Segmentation
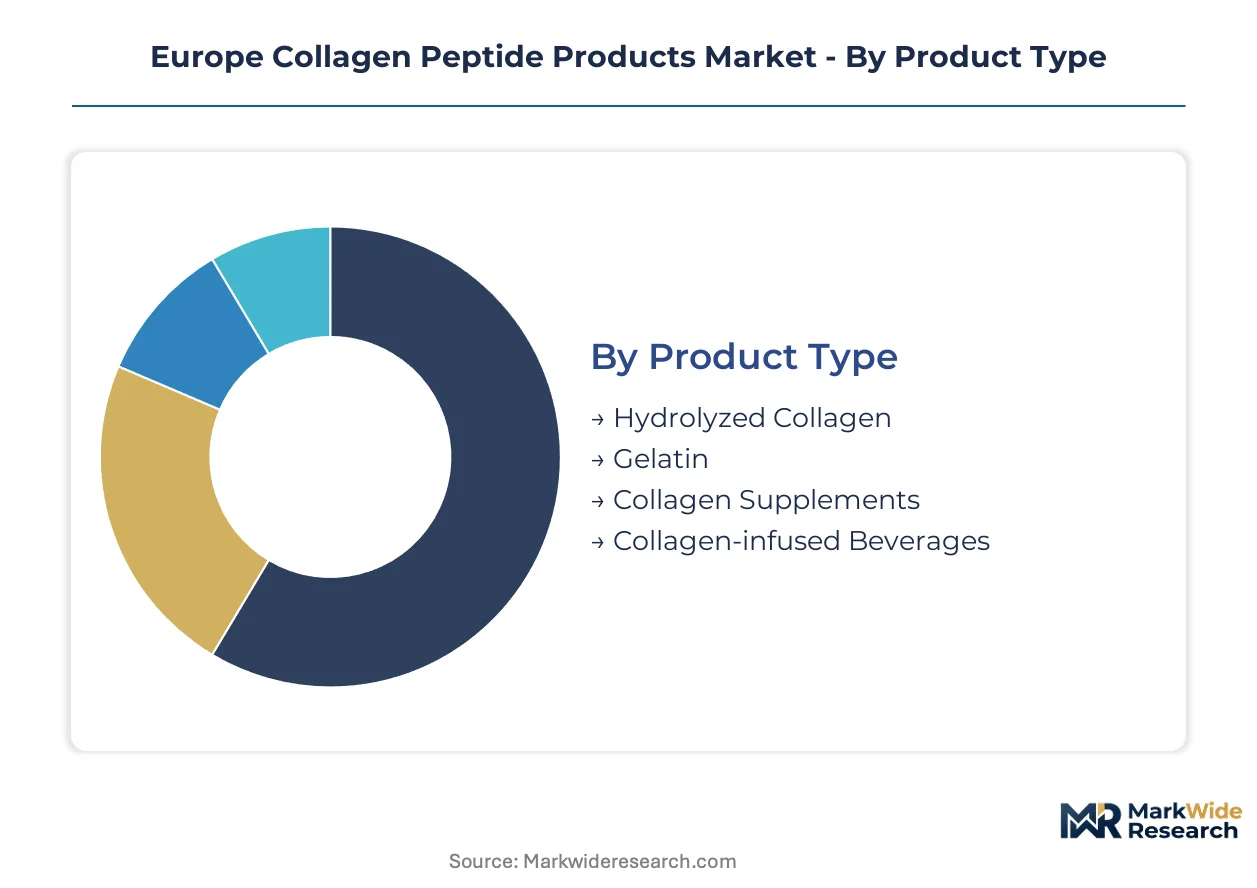
Collagen peptide value chains fragment across four distinct dimensions, each governing margin capture and regulatory exposure differently. Product type and application splits determine EFSA pathway complexity, while form and customer channel selections dictate working capital intensity and shelf positioning economics.
Product Type:
Volume throughput concentrates in commodity-grade hydrolyzed powders, while premium extraction technologies command price multiples in specialized pharmaceutical and marine grades.
- Hydrolyzed Collagen:Enzymatically cleaved proteins with molecular weights between 2,000 and 5,000 Daltons deliver superior solubility for beverage and powder formulations. German and French nutraceutical manufacturers absorb the majority of continental supply for joint health and skin elasticity positioning.
- Gelatin:Partially hydrolyzed collagen with higher Bloom strength specifications serves food-grade applications including confectionery and dairy stabilization. Italian and Spanish food processors remain the dominant demand concentration for technical-grade gelatin in dessert and yogurt applications.
- Collagen Supplements:Finished-dose formats combining peptides with cofactors like vitamin C and hyaluronic acid target pharmacy and direct-to-consumer channels.
- Collagen-infused Beverages:Ready-to-drink functional formats with clean-label positioning capture urban convenience demand in Paris and Berlin metropolitan retail.
Mature deployment sits with Hydrolyzed Collagen. Newer deployment is concentrated in Collagen-infused Beverages.
Application:
Regulatory classification intensity varies sharply across end-use segments, with pharmaceutical pathways demanding BfArM and ANSM compliance while nutraceutical routes navigate EFSA health claim uncertainty.
- Nutraceuticals:Dietary supplement and functional food applications represent the steepest expansion trajectory as aging demographics in Germany and France prioritize preventive joint and skin health interventions.
- Personal Care:Topical dermal formulations in French and Italian premium cosmetics command margin premiums through marine collagen positioning and anti-aging messaging.
- Food & Beverages:Clean-label protein fortification in dairy alternatives and sports nutrition drives powder and liquid format adoption.
- Pharmaceuticals:Low-endotoxin grades for wound healing matrices and tablet binders require dedicated extraction validation under national pharmaceutical regulator oversight.
Volume leadership belongs to Nutraceuticals. Margin concentration sits with Personal Care.
Form:
Packaging line investments and dosing precision requirements create distinct competitive moats across physical formats, with stick-pack and capsule equipment demanding capital commitments that exclude smaller contract manufacturers.
- Powder:Bulk canister and sachet formats dominate household penetration through e-commerce and mass retail channels, offering cost efficiency at volume scale.
- Liquid:Ready-to-drink and concentrate formats require aseptic filling capacity and shorter shelf-life management, concentrating supply among integrated beverage manufacturers.
- Capsules:Precise dosing protocols in German and French pharmacy channels are displacing bulk powders among health professional recommendations.
- Tablets:Compressed formulations with excipient compatibility for pharmaceutical-grade specifications serve BfArM-oversight joint health applications.
Production scale favors Powder. Channel premiumization is accelerating fastest in Capsules.
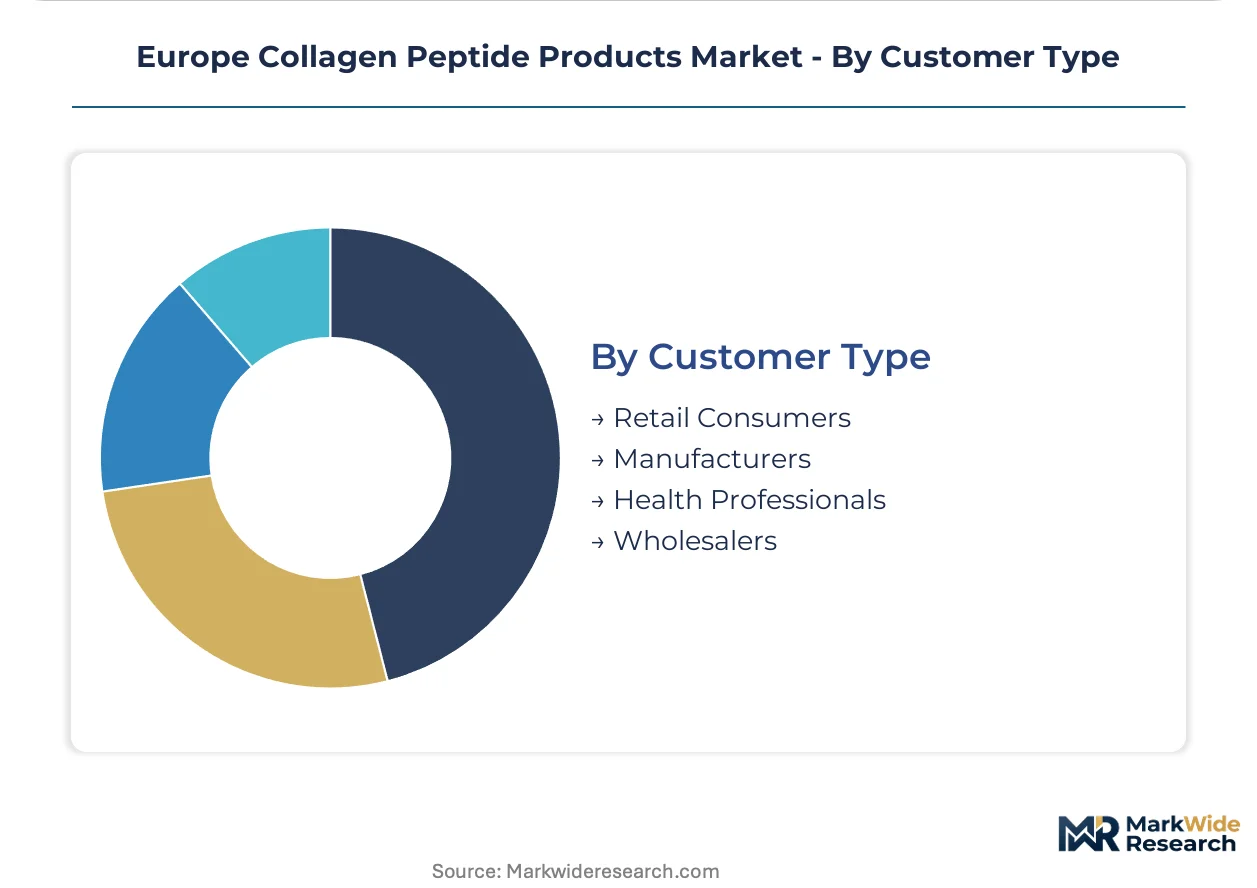
Customer Type:
Procurement sophistication and specification stringency create tiered supplier relationships, with health professional and manufacturer channels demanding certificate of analysis documentation that retail and wholesale segments bypass.
- Retail Consumers:Direct-to-consumer e-commerce and pharmacy purchases drive branded finished-product demand with label transparency expectations.
- Manufacturers:Food, beverage, and cosmetics formulators purchase technical-grade peptides for downstream product integration with customized molecular weight specifications.
- Health Professionals:German and French pharmacy and clinical nutrition channels prescribe precise-dose collagen interventions for joint mobility and wound recovery protocols.
- Wholesalers:Distribution intermediaries aggregate fragmented demand across Eastern European markets with lower minimum order quantities and extended payment terms.
Specification intensity peaks with Health Professionals. Volume aggregation runs through Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlantic fishery byproducts from French and Spanish coastal operations anchor marine collagen supply chains, while Central European abattoir networks sustain bovine and porcine feedstock flows for hydrolyzed peptide production.
Germany
BfArM oversight of pharmaceutical-grade tablet and capsule formulations drives demand for low-endotoxin collagen peptides in joint health applications. REACH compliance requirements shape raw material sourcing decisions for bovine-derived inputs. The Frankfurt-Rhine-Main corridor concentrates extraction capacity serving nutraceutical contract manufacturers.
France
ANSM pharmaceutical-grade specifications and premium dermal positioning in Parisian cosmetics channels command margin multiples for marine collagen peptides. EFSA health claim uncertainty under Regulation (EC) No 1924/2006 is freezing label investments for beauty-from-within products. The Provence-Alpes-Côte d'Azur region hosts specialized marine extraction facilities leveraging Mediterranean and Atlantic fishery networks.
Italy
Technical-grade gelatin demand from confectionery and dairy processors in Emilia-Romagna sustains volume throughput for partially hydrolyzed collagen. Clean-label beverage integration is accelerating powder format adoption among functional food formulators. The Lombardy cluster around Milan anchors personal care peptide supply for premium cosmetics manufacturers.
United Kingdom
Post-Brexit divergence from EU health claims frameworks is creating parallel compliance investments for collagen supplement distributors. Pharmacy channel professionalization in Greater London is displacing bulk powders with precise-dose capsule formats. The Southeast England corridor concentrates direct-to-consumer e-commerce fulfillment for branded finished products.
Poland
Expanding dermocosmetic retail networks in Warsaw and Krakow remain underpenetrated for premium marine collagen positioning versus saturated Western European markets. CSRD-aligned sustainable sourcing requirements are creating procurement preference for fishery improvement project certification. The Silesian industrial zone hosts emerging contract manufacturing capacity for Eastern European pharmacy distribution.
Europe Collagen Peptide Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and recombinant expression pathways. The vendor base stratifies across integrated extraction specialists, pharmaceutical-grade refiners, and finished-dose formulators. Three archetypes dominate: century-old gelatin houses with captive abattoir supply, marine-focused peptide specialists with Atlantic fishery partnerships, and branded nutraceutical marketers with pharmacy channel access. Competitive moves concentrate on enzymatic hydrolysis capacity expansion and CSRD-aligned sustainable sourcing certification.
Within the integrated extraction tier, GELITA AG and Rousselot exemplify divergent feedstock strategies—one anchored in Central European bovine and porcine supply chains, the other in Atlantic marine sourcing. Weishardt Group occupies a position bridging food-grade gelatin and pharmaceutical-grade peptide refinement. These three entities represent the continuum from commodity technical grades through validated low-endotoxin specifications for BfArM and ANSM oversight.
| Leading Market Players |
|---|
| GELITA AG |
| Rousselot |
| Weishardt Group |
| Tessenderlo Group |
| Nestle SA |
| Nutraformis Limited |
| Carylye |
| Rejuvenated Ltd |
| Italgelatine SpA |
| Others |
Supply & Pricing Matrix
Bovine hide and bone procurement costs from Central European abattoir networks cascade through three distinct pricing tiers, with pharmaceutical-grade hydrolyzed peptides commanding multiples over technical gelatin grades due to endotoxin validation and BfArM compliance overhead.
Pricing Analysis
Service bundling separates certified low-endotoxin supply with full regulatory dossier support from unbundled commodity peptide transactions. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-grade levels reflects certification intensity and molecular weight specification stringency. Cost compression in food-grade gelatin is intensifying because Italian and Spanish confectionery buyers are consolidating procurement volumes. Retail consumers through direct-to-consumer channels show highest price sensitivity, while German pharmacy buyers under BfArM oversight demonstrate lowest elasticity due to therapeutic positioning requirements.
Supply Chain Analysis
EFSA novel food authorization and REACH substance registration act as qualification gates that filter feedstock suppliers and concentrate procurement relationships among validated Atlantic fishery and Central European abattoir partners. Germany, France, and Spain anchor continental supply through GELITA AG's integrated bovine operations and Rousselot's marine extraction network. Raw material flows draw from cattle byproduct streams, Atlantic fish skin and scale, and porcine dermal tissue. Single-source vulnerability concentrates in pharmaceutical-grade peptide refining where dedicated cleanroom capacity is tethered to specific national regulator approvals. Distribution runs through integrated nutraceutical contract manufacturers serving pharmacy and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis cleanroom capacity scarcity across Germany and France is propping pricing power for validated low-endotoxin supply, creating a supply-constrained investment environment where capacity addition timelines exceed demand growth trajectories.
For Market Incumbents: To counter precision fermentation entrants targeting pharmaceutical-grade supply independence, accelerate backward integration into Atlantic fishery improvement project partnerships and expand dedicated BfArM-validated extraction capacity in the Frankfurt-Rhine-Main corridor. Lock in long-term offtake agreements with Polish and Romanian dermocosmetic distributors before marine collagen positioning saturates Eastern European pharmacy channels.
For New Entrants and Emerging Players: Polish pharmacy buyers remain underserved for premium marine collagen capsules versus saturated German and French markets. Target Romanian dermocosmetic retail networks with CSRD-aligned fishery certification messaging. Deploy direct-to-consumer subscription models with precise-dose stick-pack formats to bypass incumbent control over integrated contract manufacturing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap peptide refiners with stranded food-grade capacity and convertible cleanroom infrastructure in France and Italy. Five-to-ten year viability hinges on successful pharmaceutical-grade upgrading and EFSA health claim dossier navigation. Watch for EFSA opinions on collagen-specific joint and skin claims as inflection signal for label permissibility investments and new product launch acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishery Networks | CSRD-aligned Atlantic sourcing secures marine feedstock preference under EU sustainability reporting mandates. |
| Pharmaceutical-Grade Cleanroom Expansion | BfArM and ANSM validation enables low-endotoxin supply for German and French pharmacy channels. |
| Precision Fermentation Partnership | Recombinant collagen expression bypasses animal agriculture volatility and REACH registration complexity. |
| Eastern European Distribution Buildout | Polish and Romanian pharmacy networks offer first-mover positioning before Western saturation spreads eastward. |
| EFSA Health Claim Dossier Investment | Article 13.5 clinical trial generation preempts regulatory restriction and unlocks label permissibility for beauty-from-within positioning. |
Research Methodology
Trade databases, EFSA novel food authorization registers, and REACH substance filings formed the secondary backbone, supplemented by primary interviews with extraction plant managers, nutraceutical contract manufacturing procurement leads, French and German pharmacy category buyers, and marine fishery improvement project coordinators. Bottom-up and top-down triangulation validated volume estimates across hydrolyzed collagen, gelatin, and finished-dose format segments.
Bottom-up modeling anchored forecasts to enzymatic hydrolysis capacity utilization rates, molecular weight specification premiums, and channel-specific pricing differentials across powder, liquid, capsule, and tablet formats. Top-down validation cross-checked against aging demographic expenditure patterns, EFSA regulatory timeline assumptions, and CSRD procurement preference diffusion. CAGRs were derived from segment-level volume trajectories and price realization trends across the analysis window.
Revisions become necessary when EFSA health claim opinions restrict label permissibility, Atlantic fishery supply disruptions materialize, or precision fermentation technologies achieve cost parity with animal-derived extraction. A model refresh is warranted upon material change in BfArM or ANSM pharmaceutical-grade specification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Magtein Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Immunostimulants Market