
 Aesthetic Devices Market | 2026-2036
Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetic Devices Market Intelligence
Leasing and pay-per-procedure financing is tilting competitive access toward mid-tier dermatology chains that previously could not afford capital-intensive laser platforms. Alma Lasers leverages flexible placement programs to extend its footprint across medical spas in North America. Candela Medical anchors its position through vertically integrated service contracts that lock in recurring revenue from installed ultrasound and radiofrequency bases.
Aesthetic devices comprise electromechanical and optical systems engineered to deliver controlled thermal, mechanical, or electromagnetic energy to cutaneous and subcutaneous tissues, with output parameters typically ranging from nanosecond pulse durations for Q-switched lasers to sustained radiofrequency delivery at 1–40 MHz for tissue tightening. These systems serve commercial purposes across skin rejuvenation, body contouring, and hair removal procedures performed in clinical and non-clinical settings. Laser devices occupy the largest revenue pool due to their versatility across multiple indications, while radiofrequency devices represent the fastest-expanding segment as practitioners adopt multipolar and fractional systems for collagen remodeling with reduced downtime. Body contouring applications command premium pricing relative to hair removal, reflecting higher device complexity and consumable attachment requirements.
FDA premarket notification requirements under 21 CFR 878.4810 govern laser and light-based surgical instruments, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa and IIb aesthetic equipment entering European markets. These frameworks elevate barriers for new entrants without established regulatory affairs capabilities and shift procurement criteria toward vendors with proven clearance portfolios. Stakeholders must weigh reimbursement asymmetries across national health systems against out-of-pocket aesthetic spending trends when allocating R&D and commercial resources.
Market Dynamics
Radiofrequency multipolar systems are compressing treatment protocols from six sessions to two, forcing device vendors to restructure consumable revenue models and service contract pricing to protect margin pools.
Growth Catalysts
- Non-surgical body contouring protocols:Cryolipolysis and high-intensity focused electromagnetic platforms expand addressable patient populations beyond traditional liposuction candidates into medical spa channels.
- FDA 510(k) clearance for combination systems:Dual-modality devices integrating laser with radiofrequency reduce capital expenditure per treatment room for dermatology chains.
- Post-pandemic aesthetic spending persistence:Out-of-pocket expenditure on elective procedures demonstrates stickiness among high-income demographics in the United States.
Market Restraints
- Optical component supply concentration:German and Japanese precision laser source manufacturers control critical diode and fiber supply, exposing device assemblers to input bottlenecks.
- EU MDR clinical evidence requirements:Stricter post-market surveillance and notified body capacity constraints extend time-to-market for Class IIb aesthetic equipment by 18-24 months.
- At-home IPL substitution:Consumer-grade intense pulsed light devices capture maintenance-phase hair removal demand, compressing clinic visit frequency for established patients.
Strategic Opportunities
- Men's aesthetic services underpenetration:Hair restoration and body contouring protocols tailored to male anatomy remain underserved relative to female-skewed device design heritage.
- AI-guided treatment parameter optimization:Machine vision systems that auto-calibrate energy delivery based on real-time tissue response reduce operator skill variance.
- Subscription-based device access:Hardware-as-a-service models lower entry barriers for independent dermatology practices in secondary United States metropolitan markets.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-disciplinary expertise combining optical physics with thermal tissue modeling commands premium compensation, constraining R&D team scaling.
- Legacy EMR integration complexity:Aesthetic-specific practice management software lacks standardized APIs with hospital system electronic medical records, complicating hospital-affiliated cosmetic center deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetic Devices Market |
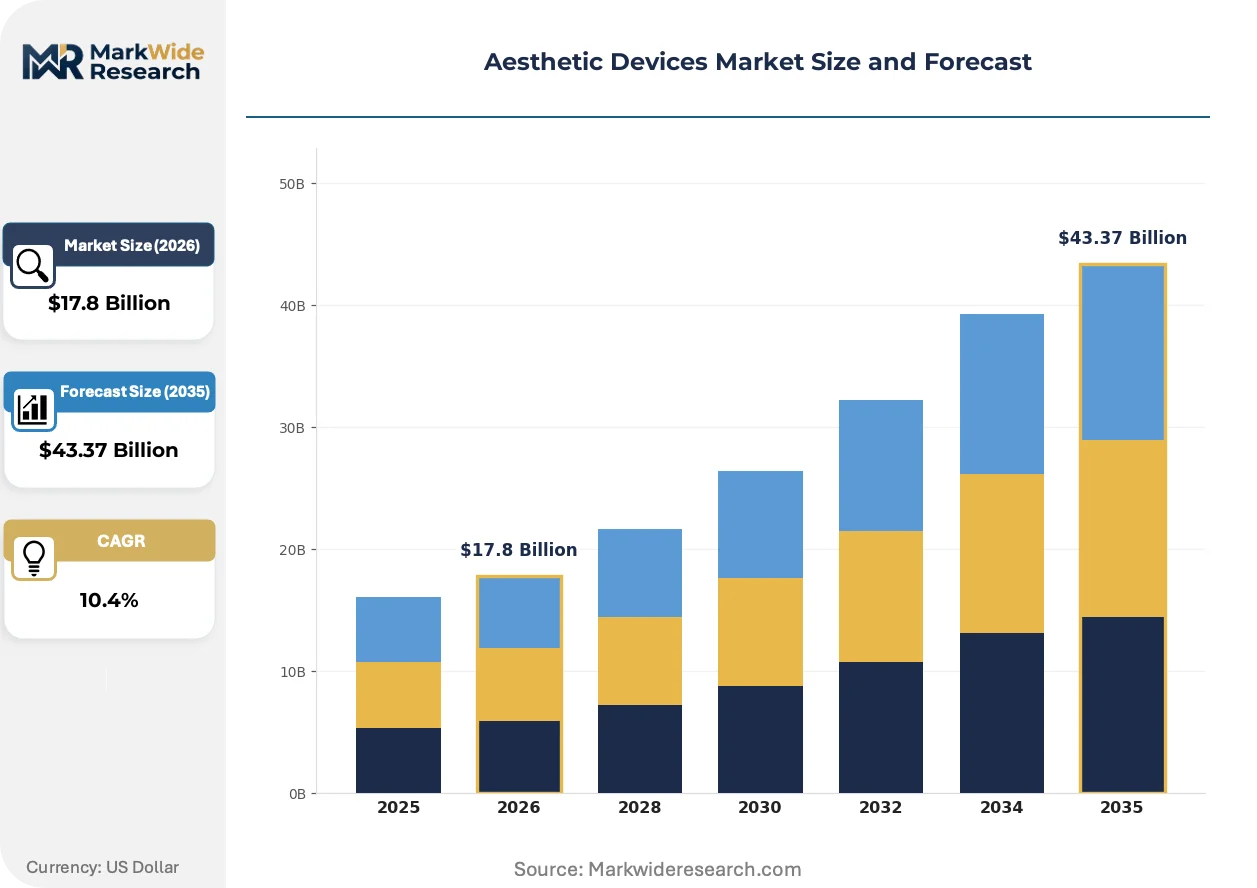
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $43.37 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Light Therapy Equipment, Radiofrequency Devices, Ultrasound Machines, Microdermabrasion Systems Technology: Fractional, Intense Pulsed Light, Cryolipolysis, Thermage, Electroporation Application: Skin Rejuvenation, Body Contouring, Hair Removal, Scar Treatment, Cellulite Reduction End User: Dermatology Clinics, Medical Spas, Cosmetic Surgery Centers, Wellness Clinics, Aesthetic Practitioners |
| Companies Covered | Bausch Health Companies (Solta Medical), Candela Medical, AbbVie (Allergan Aesthetics), InMode, Cutera, Cynosure, Alma Lasers, Merz Aesthetics, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetic Devices Market Strategic Shifts & Innovations
Energy-based platforms are converging with diagnostic imaging and automated feedback systems, transforming device value propositions from standalone hardware to integrated treatment ecosystems that capture patient data across multiple touchpoints.
Picosecond laser technology is collapsing the efficacy gap between tattoo removal and benign pigmented lesion treatments, enabling dermatology clinics to consolidate device footprints. High-volume chains in Texas and Florida are retiring nanosecond platforms ahead of standard depreciation cycles. The technology is collapsing capital allocation per indication served, pressuring vendors to defend placement through software-locked consumable ecosystems.
The EU Medical Device Regulation's enhanced clinical evaluation requirements for Class IIa and IIb aesthetic equipment are elevating documentation burdens for radiofrequency and ultrasound systems. Manufacturers without established European authorized representatives face extended conformity assessment timelines. German and French notified bodies are prioritizing cardiovascular and orthopedic submissions, forcing aesthetic device sponsors to queue for limited regulatory bandwidth.
Practitioner procurement committees are unbundling after-sales service from capital purchase agreements, treating maintenance and training as separately negotiable line items. Independent medical spas in California and New York are sourcing third-party technical service providers at 30-40% below OEM rates. This behavior is most visible among mid-tier chains that lack sufficient installed base volume to command preferential vendor attention.
Aesthetic Devices Market Segmentation
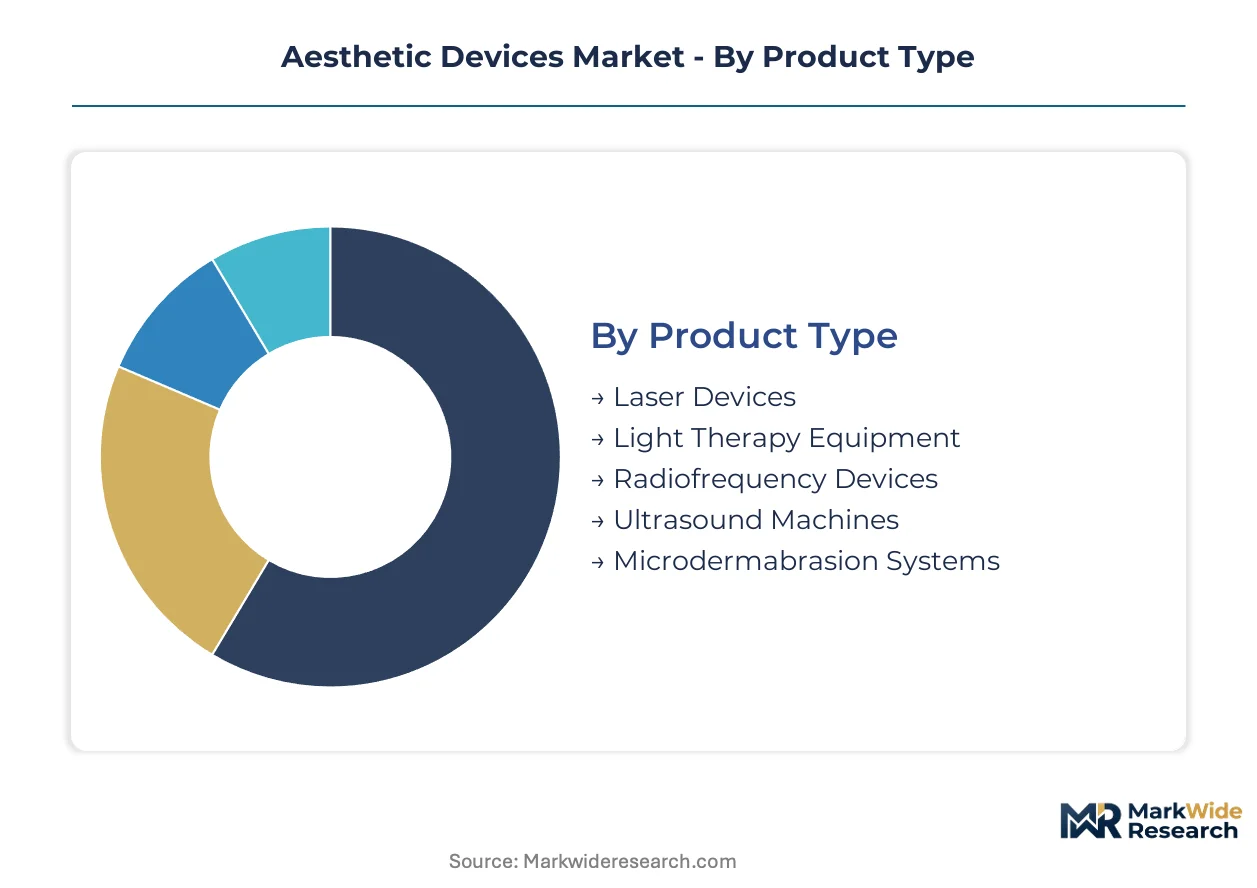
Device segmentation in aesthetic markets determines procurement patterns, service contract structures, and consumable revenue durability. Vendors configure placement programs and pricing tiers around product-technology-application intersections rather than hardware specifications alone.
Product Type:
After-sales service intensity varies dramatically across product categories, with laser platforms requiring quarterly optical alignment and radiofrequency systems demanding annual handpiece refurbishment cycles.
- Laser Devices:Electromechanical systems delivering coherent light across nanosecond to picosecond pulse durations for pigmented lesion and tattoo removal. Demand concentrates in high-volume dermatology chains across Texas and Florida where practitioners consolidate multiple wavelength platforms into single vendor relationships to streamline preventive maintenance scheduling.
- Radiofrequency Devices:Multipolar and fractional systems operating at 1–40 MHz for collagen remodeling with reduced downtime. Adoption accelerates fastest among medical spas in California and New York seeking to compress treatment protocols from six sessions to two, forcing vendors to restructure consumable revenue models.
- Light Therapy Equipment:LED and narrowband systems for inflammatory skin conditions with minimal consumable requirements.
- Ultrasound Machines:High-intensity focused and micro-focused platforms for non-surgical lifting with steep operator training curves.
- Microdermabrasion Systems:Mechanical exfoliation devices with lowest capital intensity and minimal regulatory burden.
Laser devices hold the largest share; momentum sits with radiofrequency devices.
Technology:
Technology selection drives capital allocation per treatment room, with fractional platforms commanding premium placement alongside combination systems that reduce square footage requirements.
- Fractional:Ablative and non-ablative laser delivery creating microscopic treatment zones for skin resurfacing. Dermatology clinics in hospital-affiliated cosmetic centers prioritize fractional CO2 and erbium systems for their versatility across scar revision and photoaging indications.
- Cryolipolysis:Controlled cooling platforms for fat cell apoptosis without tissue suction. Medical spa chains in secondary United States metropolitan markets favor cryolipolysis for its minimal operator skill variance and predictable outcomes that reduce liability exposure.
- Intense Pulsed Light:Broadband flashlamp systems for vascular and pigmented lesion treatment with high consumable turnover.
- Thermage:Monopolar radiofrequency technology for skin tightening with single-treatment protocols.
- Electroporation:Pulsed electrical field systems for transdermal drug delivery with emerging aesthetic applications.
Fractional technology holds the largest share; cryolipolysis is expanding most quickly.
Application:
Application focus determines device complexity tiers and consumable attachment requirements, with body contouring protocols sustaining premium pricing relative to maintenance-phase hair removal.
- Body Contouring:Cryolipolysis, radiofrequency, and high-intensity focused electromagnetic protocols for non-surgical fat reduction and muscle toning. Cosmetic surgery centers in Florida and Arizona deploy combination platforms to capture patients seeking alternatives to traditional liposuction without operating room overhead.
- Skin Rejuvenation:Laser resurfacing, radiofrequency tightening, and light therapy for photoaging and texture improvement. Wellness clinics in California integrate skin rejuvenation into membership-based service bundles to drive recurring visit frequency.
- Hair Removal:Laser and intense pulsed light systems with compressed margins due to at-home IPL substitution.
- Scar Treatment:Fractional laser and microneedling radiofrequency for traumatic and surgical scar revision.
- Cellulite Reduction:Subcision radiofrequency and acoustic wave platforms with variable efficacy evidence.
Skin rejuvenation holds the largest share; body contouring is gaining share fastest.
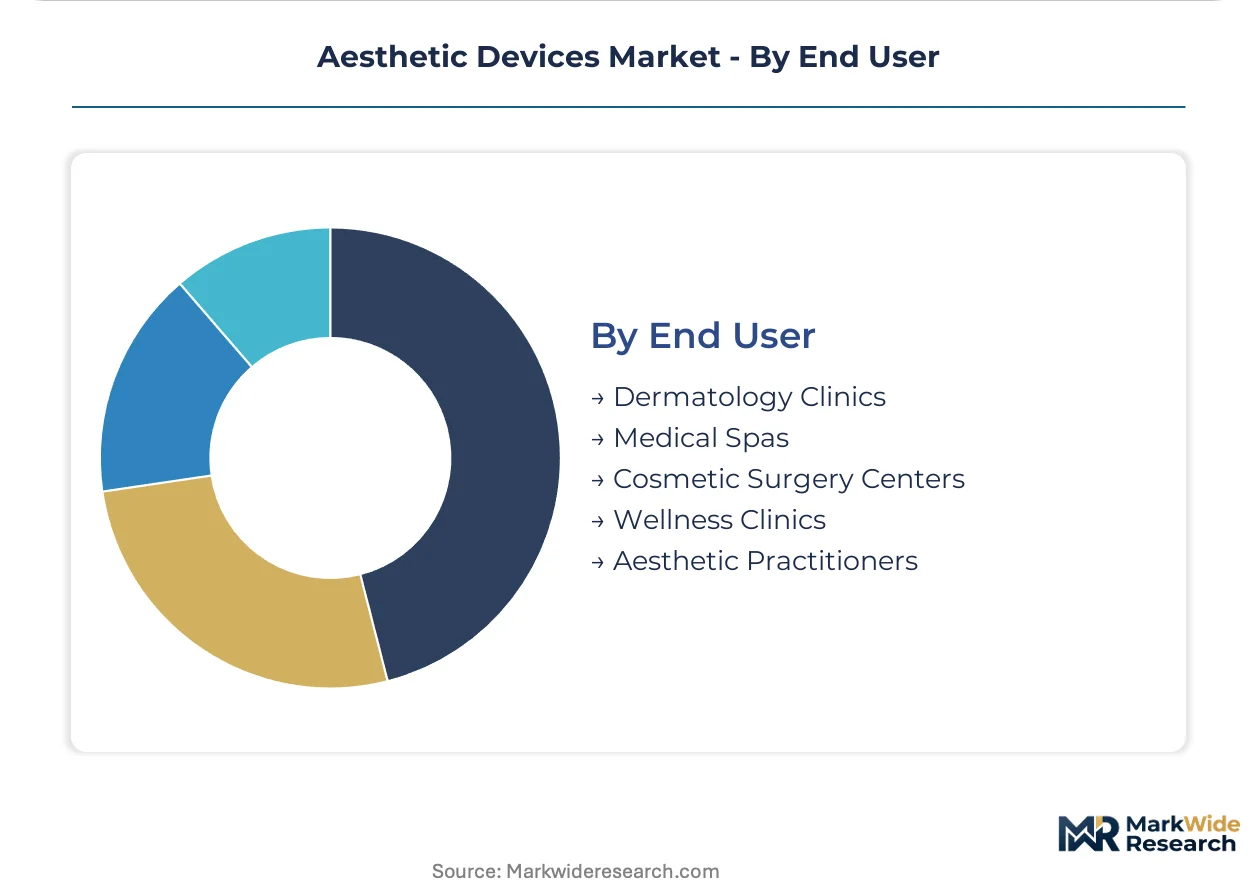
End User:
End user category shapes procurement committee composition and financing preferences, with independent practitioners prioritizing subscription access over capital purchase.
- Dermatology Clinics:Physician-supervised practices with highest device utilization rates and preventive maintenance discipline. High-volume chains in Texas negotiate vertically integrated service contracts that lock in recurring revenue from installed ultrasound and radiofrequency bases.
- Medical Spas:Non-physician operated facilities with flexible financing requirements and rapid technology turnover. Mid-tier chains previously excluded from capital-intensive laser platforms now access hardware through leasing and pay-per-procedure arrangements.
- Cosmetic Surgery Centers:Hospital-affiliated and independent surgical practices with EMR integration complexity.
- Wellness Clinics:Holistic health facilities expanding into aesthetic services with limited clinical infrastructure.
- Aesthetic Practitioners:Independent solo operators with highest price sensitivity and third-party technical service sourcing.
Dermatology clinics hold the largest share; medical spas show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and EU MDR clinical evidence requirements are diverging procurement criteria across major markets, with reimbursement asymmetries and out-of-pocket spending patterns reshaping vendor commercial resource allocation.
United States
High-volume aesthetic chains in Texas and Florida drive laser platform consolidation, with dermatology clinics negotiating vertically integrated service contracts. FDA premarket notification requirements under 21 CFR 878.4810 govern laser and light-based surgical instruments. Hospital-affiliated cosmetic centers in California face legacy EMR integration complexity.
Germany
Precision laser source manufacturers control critical diode and fiber supply for device assemblers worldwide. The EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa and IIb aesthetic equipment. Notified bodies in Munich and Frankfurt prioritize cardiovascular submissions, forcing aesthetic device sponsors into extended conformity assessment queues.
Brazil
Medical spa channels expand cryolipolysis adoption as patient volumes for non-surgical body contouring climb. ANVISA regulatory frameworks govern medical device registration with evolving post-market surveillance requirements. São Paulo-based aesthetic chains source third-party technical service providers at rates below OEM contracts.
Japan
Radiofrequency multipolar systems compress treatment protocols, pressuring vendors to restructure consumable revenue models. PMDA and METI oversight ensures alignment with JIS standards for electromagnetic medical equipment. Tokyo cosmetic centers lead adoption of AI-guided treatment parameter optimization systems.
United Arab Emirates
Wellness clinics in Dubai integrate skin rejuvenation into membership-based service bundles. MOHAP medical device regulations require local authorized representatives for commercial distribution. Abu Dhabi hospital-affiliated cosmetic centers deploy combination laser-radiofrequency platforms to reduce capital expenditure per treatment room.
Aesthetic Devices Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated service ecosystems and software-locked consumable models. Strategic archetypes include premium-tier laser platform vendors with proprietary wavelength portfolios, mid-tier radiofrequency specialists offering flexible financing placement programs, and diversified aesthetics conglomerates leveraging cross-selling across injectables and devices. Dominant competitive moves encompass backward integration into precision optical component supply and subscription-based hardware-as-a-service market entry.
Among Israel-based electromechanical specialists, InMode and Alma Lasers exemplify the flexible-placement archetype, while Candela Medical occupies a position within the vertically integrated service-contract tier. These three entities anchor distinct competitive vectors: wavelength diversification, financing innovation, and recurring revenue capture from installed device bases.
| Leading Market Players |
|---|
| Bausch Health Companies (Solta Medical) |
| Candela Medical |
| AbbVie (Allergan Aesthetics) |
| InMode |
| Cutera |
| Cynosure |
| Alma Lasers |
| Merz Aesthetics |
| Lumenis |
| Others |
Cost & Logistics Intelligence
Overcapacity in German precision laser diode manufacturing is compressing component pricing while simultaneously elevating supplier selectivity toward FDA-cleared device assemblers with volume commitments. This utilization asymmetry rewards vertically integrated vendors with captive optical sourcing while forcing mid-tier radiofrequency specialists to absorb margin erosion on non-critical subsystems.
Pricing Analysis
Certification level creates the primary spread across device tiers, with FDA 510(k)-cleared platforms commanding placement premiums over CE-marked equivalents in United States dermatology chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales bundling intensity and software-locked consumable ecosystems. Cost compression in standard-tier radiofrequency systems is intensifying because medical spa procurement committees unbundle service contracts from capital purchases. Independent practitioners in secondary metropolitan markets exhibit highest price sensitivity, while hospital-affiliated cosmetic centers prioritize total cost-of-ownership over upfront capital expenditure.
Supply Chain Analysis
Export-control restrictions on high-power diode laser technology limit component flows from German and Japanese precision manufacturers to non-allied device assemblers. Geographic supply concentration centers on Germany for optical subsystems, Japan for fiber laser sources, and Israel for radiofrequency handpiece engineering. Raw material dependencies include rare-earth doped fibers, precision ceramic substrates, and medical-grade aluminum housings. Single-source vulnerability in Q-switched laser cavity manufacturing exposes vendors to allocation risk during demand surges. Distribution runs through authorized representatives with regional service depots for preventive maintenance scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary expertise combining optical physics with thermal tissue modeling commands compensation premiums that constrain R&D team scaling across the vendor base. This capability bottleneck shapes competitive durability more than capital access or regulatory clearance velocity.
For Market Incumbents: Insulate installed base revenue through software-locked consumable ecosystems that tie treatment parameters to proprietary handpiece authentication. Backward integration into precision optical component supply secures allocation priority during input shortages. Defend against third-party technical service encroachment by embedding predictive maintenance algorithms that void warranties upon unauthorized calibration. For New Entrants and Emerging Players: Men's aesthetic services in hair restoration and body contouring represent the most penetrable entry point given persistent underpenetration relative to female-skewed device design heritage. AI-guided treatment parameter optimization for operator skill variance reduction offers differentiation without wavelength portfolio depth. Subscription-based hardware-as-a-service models lower entry barriers for independent dermatology practices in secondary United States metropolitan markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among radiofrequency specialists with multipolar platforms that compress treatment protocols and accelerate handpiece refurbishment cycles. Long-term viability hinges on regulatory bandwidth access in European notified body queues and FDA premarket notification velocity. Acquisition target archetype: Israeli electromechanical specialists with flexible placement programs and established Middle Eastern distribution. Signal to watch: ANVISA registration timelines for medical spa channel expansion in São Paulo-based aesthetic chains.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States market entry for dual-modality laser-radiofrequency platforms in dermatology chains. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend conformity assessment timelines for Class IIb aesthetic equipment. |
| Hospital System Partnership | Resolves legacy EMR integration complexity for cosmetic centers affiliated with California health systems. |
| Software Companion Development | Machine vision calibration systems reduce operator skill variance and defend against third-party service providers. |
| Reimbursement Strategy | Out-of-pocket aesthetic spending persistence in United States high-income demographics supports premium pricing durability. |
Research Approach
Cross-validation between primary interviews with biomedical engineers and GPO contracts managers anchors the qualitative findings on procurement committee behavior and service contract unbundling. Secondary validation draws from FDA 510(k) premarket notification databases, EU MDR notified body submission records, and hospital procurement databases. Bottom-up triangulation aggregates device placement volumes by end-user category while top-down cross-checks against customs records for precision optical component trade flows.
Calibration against historical placement cycles and regulatory approval timelines ensures forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application indication, and end-user procurement archetype. CAGRs derive from fitted growth curves applied to base-year market sizing, with sensitivity testing around FDA clearance velocity and EU MDR notified body capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in discretionary healthcare spending patterns or medical device reimbursement policy would shift the trajectory. Forecasts reflect assumptions on treatment protocol compression rates and consumable revenue model restructuring. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Recanalization System Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Skincare Devices Market
Medical Devices
General Surgical Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
EEG Electrodes Market
Medical Devices
Medical Pendant Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Global Medical Device Labeling Market