
 Asia Pacific Aesthetics Market | 2026-2036
Asia Pacific Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Aesthetics Market Analysis
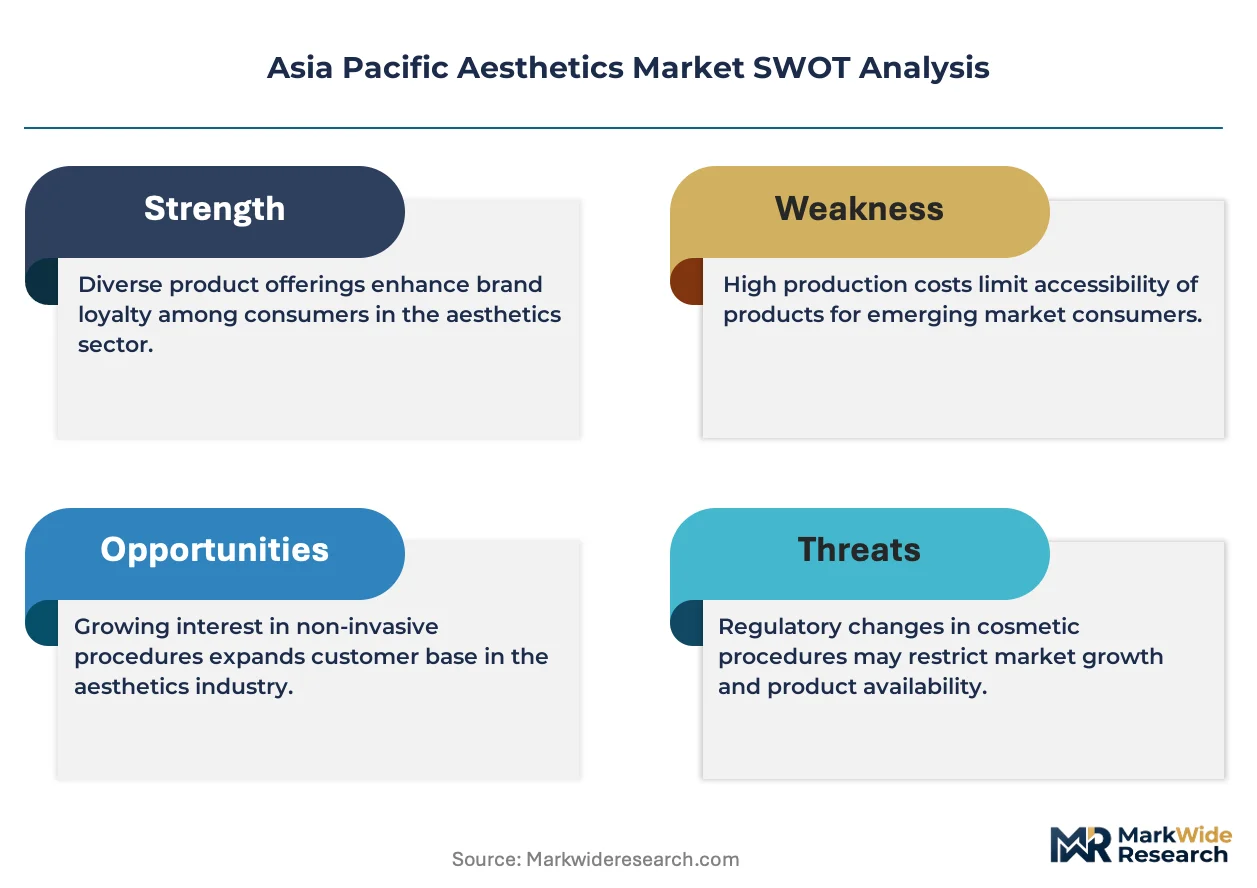
Hyaluronic acid formulations are restructuring cost structures across the Asia Pacific Aesthetics Market by displacing collagen-based alternatives in wrinkle reduction protocols. Allergan Aesthetics leverages its portfolio breadth to sustain premium positioning in China's tier-one aesthetic clinics. Hugel Inc. anchors Korean manufacturing scale for botulinum toxin exports across Southeast Asian dermatology networks. Merz Aesthetics differentiates through radiofrequency technology leadership in skin tightening applications.
Asia Pacific aesthetics encompasses minimally invasive and non-invasive procedures, devices, and topical formulations designed to alter facial and body appearance, with laser devices operating at specific wavelengths between 532 nm and 10,600 nm depending on target chromophore and clinical indication. The commercial purpose centers on elective cosmetic enhancement, scar revision, and age-related tissue restoration for outpatient settings. Injectables command mature margin pools in established markets like Japan and South Korea, while body contouring devices represent the fastest-growing product category as cryotherapy and radiofrequency platforms penetrate China's expanding clinic base. Laser technology sustains the widest application span across skin tightening and acne scarring protocols, though chemical peels retain cost advantages in India's price-sensitive consumer segments.
MFDS in South Korea, CDSCO in India, and NMPA in China each enforce distinct biologics registration pathways that fragment product launch timelines and compliance costs across the region. REACH-aligned substance restrictions in imported European devices additionally shape raw material sourcing for laser and radiofrequency equipment manufacturers. Stakeholders must monitor regulatory divergence between national biologics frameworks and emerging AI-driven diagnostic tools that promise to reshape treatment planning workflows.
Market Dynamics
Energy-based body contouring platforms are compressing treatment timelines and clinic square footage requirements across Southeast Asian dermatology networks, restructuring capital deployment patterns for aesthetic service providers.
Growth Catalysts
- MFDS Biologics Pathways:South Korea's tightened hyaluronic acid licensing requirements are accelerating domestic manufacturer compliance investments and raising quality barriers that favor established Korean producers.
- Metropolitan China Demand Concentration:Tier-one cities absorb premium injectable and laser device volumes, creating density economies that support specialized clinic formats and device financing models.
- Laser Wavelength Expansion:Devices operating between 532 nm and 10,600 nm now address multiple chromophores, broadening treatable indications without requiring separate capital equipment purchases.
Market Restraints
- Regulatory Fragmentation:Divergent biologics registration pathways between MFDS, CDSCO, and NMPA fragment product launch timelines and multiply compliance costs for multi-country portfolios.
- REACH-Aligned Substance Restrictions:European raw material constraints on imported laser and radiofrequency equipment shape sourcing flexibility for Asia Pacific device manufacturers.
- Chemical Peel Substitution:Low-cost acid formulations retain cost advantages in India's price-sensitive consumer segments, limiting premium device penetration outside metropolitan centers.
Strategic Opportunities
- AI-Driven Diagnostic Integration:Treatment planning workflows incorporating machine learning analysis of facial topography promise to standardize outcomes and reduce practitioner training curves.
- Southeast Asia Clinic Network Expansion:Dermatology centers across Thailand, Vietnam, and Indonesia are expanding service menus to include energy-based protocols previously concentrated in North Asian markets.
- Radiofrequency-Cryotherapy Convergence:Combined modality platforms addressing both fat reduction and skin tightening in single sessions are capturing China's expanding mid-tier clinic base.
Industry Challenges
- Practitioner Certification Bottlenecks:Safe operation of multi-wavelength laser systems requires specialized training that outpaces availability of qualified instructors across emerging Southeast Asian markets.
- Biologics Cold Chain Integrity:Botulinum toxin and hyaluronic acid formulations demand temperature-controlled logistics that strain distribution infrastructure in Indonesia's archipelago geography and India's hinterland states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Aesthetics Market |
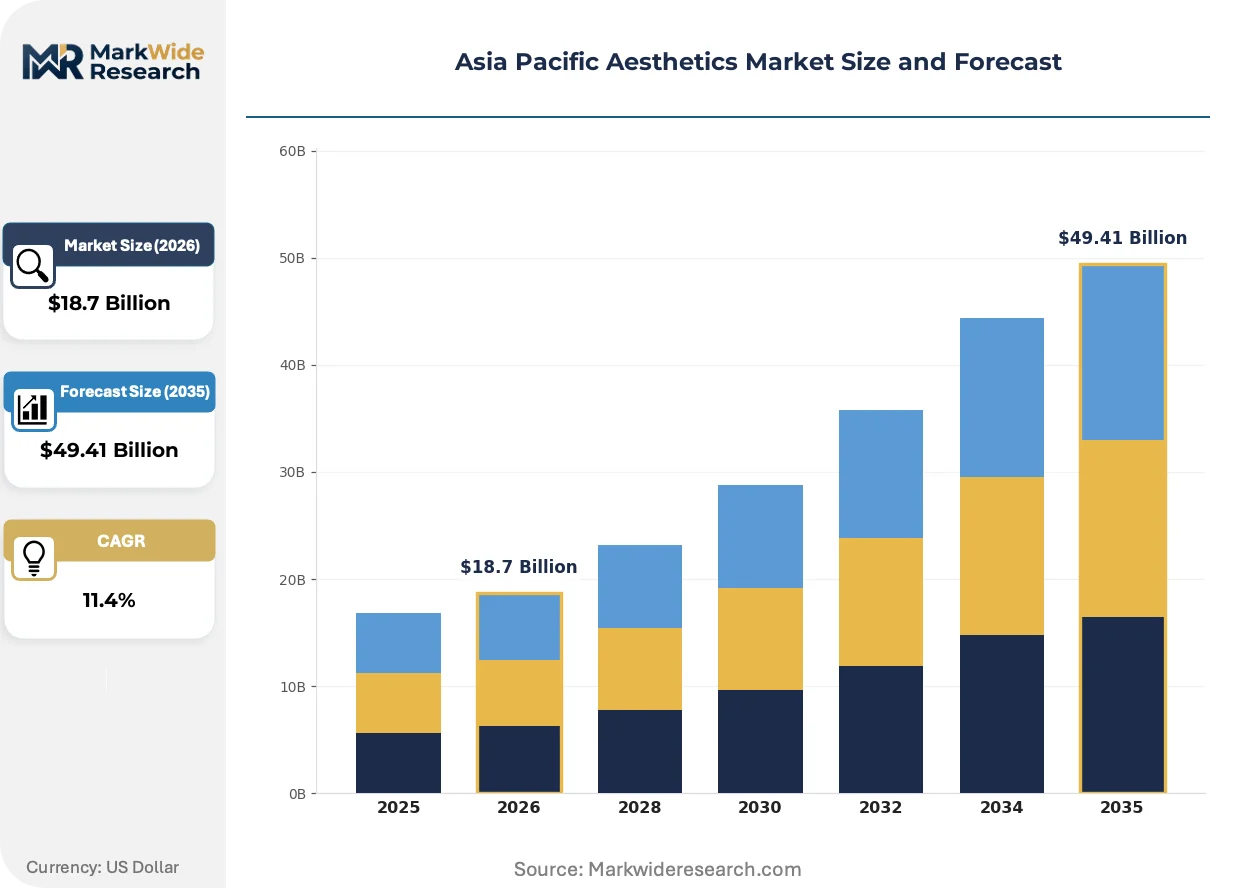
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Devices, Skin Care Products, Body Contouring Devices Customer Type: Consumers, Healthcare Professionals, Aesthetic Clinics, Dermatology Centers Technology: Radiofrequency, Cryotherapy, Laser Technology, Chemical Peels Application: Wrinkle Reduction, Skin Tightening, Acne Scarring, Body Shaping |
| Companies Covered | Medytox, Lumenis, Allergan Aesthetics, Ipsen, Cutera Inc., Merz Aesthetics, Hugel Inc., Revance Therapeutics, Galderma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Aesthetics Market Emerging Trajectories
Platform convergence and intelligent diagnostics are compressing the gap between clinical assessment and treatment execution, altering how aesthetic providers configure service delivery and capital allocation.
Radiofrequency-assisted lipolysis is modularizing treatment protocols across Asia Pacific aesthetic clinics. Devices combining thermal energy delivery with real-time tissue impedance monitoring enable practitioners to address multiple body zones without switching equipment. Chinese tier-one clinics are adopting these platforms at accelerated rates, compressing the traditional separation between surgical and non-surgical body contouring service lines.
NMPA's evolving biologics classification framework for combination devices is reshaping registration strategies for manufacturers importing laser-energy systems with integrated cooling mechanisms. The industrial consequence extends approval timelines for novel platforms and favors domestic Chinese producers with established regulatory relationships. Injectable-device combination products face the most pronounced compliance burden, with several international portfolios delayed pending additional clinical data submissions.
After-sales service unbundling is disrupting traditional device procurement relationships across South Korean and Japanese aesthetic chains. Clinics are separating hardware acquisition from maintenance contracts and software upgrade commitments, pressuring original equipment manufacturers to demonstrate discrete value for each revenue stream. This pattern concentrates in high-volume metropolitan markets where buyer concentration supports dedicated in-house technical staffing.
Asia Pacific Aesthetics Market Segmentation
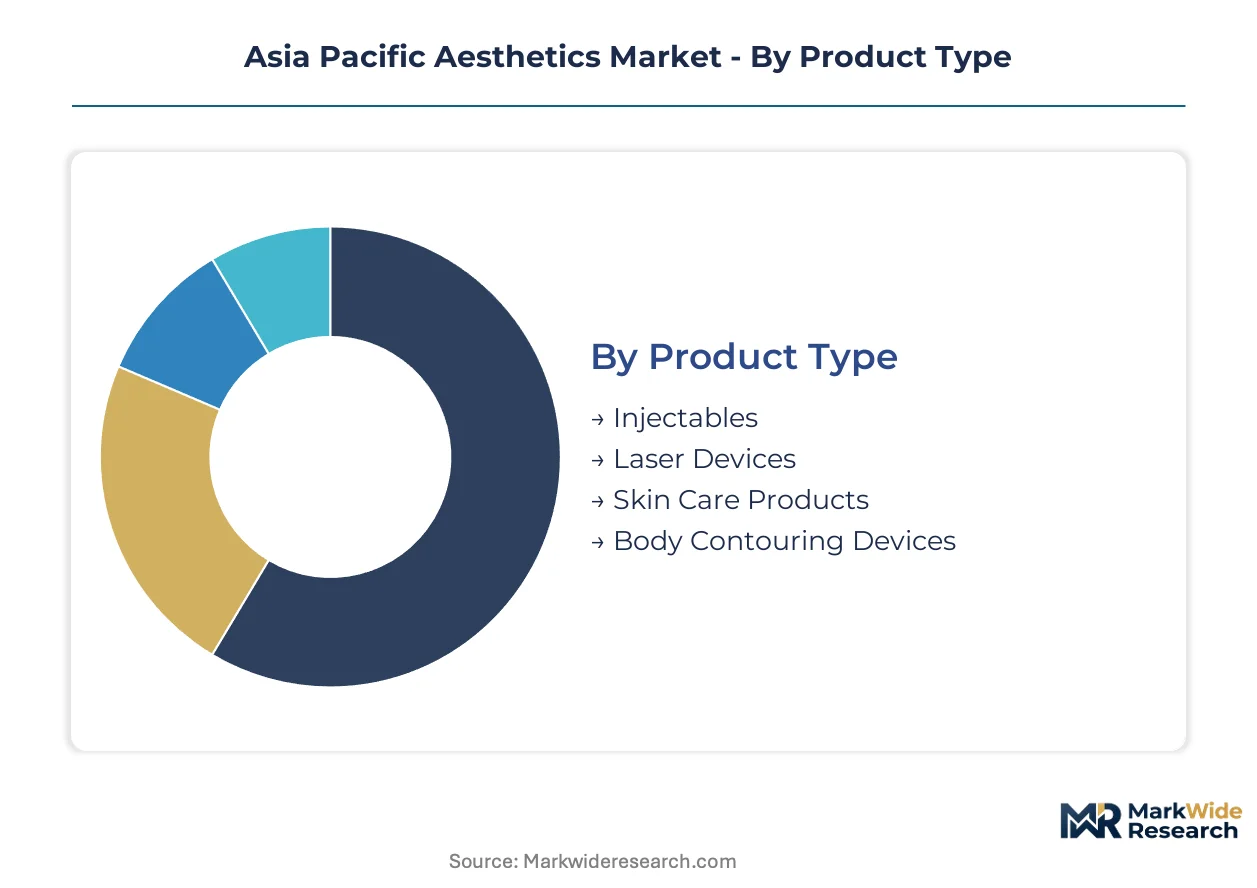
Segmentation in the Asia Pacific Aesthetics Market reveals divergent capital deployment patterns and margin profiles across product categories. Treatment modality selection directly shapes clinic infrastructure requirements, regulatory compliance burdens, and customer acquisition economics in this heterogeneous regional landscape.
Product Type:
Capital intensity varies sharply across product categories, with energy-based platforms demanding the heaviest upfront equipment investment while consumable formulations operate on lighter fixed-asset models.
- Injectables:Botulinum toxin and hyaluronic acid formulations dominate revenue pools in Japan and South Korea. MFDS licensing requirements in Seoul have raised quality barriers that favor established domestic manufacturers with compliant cold-chain infrastructure.
- Laser Devices:Multi-wavelength systems operating between 532 nm and 10,600 nm command premium pricing in China's tier-one cities. NMPA registration timelines for imported platforms with integrated cooling mechanisms extend approval cycles and favor domestic producers with established regulatory relationships.
- Skin Care Products:Topical retinoids and antioxidant formulations serve India's price-sensitive consumer segments with minimal capital requirements.
- Body Contouring Devices:Cryotherapy and radiofrequency platforms are penetrating China's expanding mid-tier clinic base fastest.
Most installed capacity flows through Injectables. Expansion is steepest in Body Contouring Devices.
Customer Type:
Procurement sophistication and volume scale separate customer tiers, with high-volume chains extracting pricing concessions unavailable to independent operators.
- Aesthetic Clinics:China's tier-one metropolitan chains absorb premium device volumes and negotiate unbundled after-sales service contracts. These buyers separate hardware acquisition from maintenance commitments, pressuring original equipment manufacturers to demonstrate discrete value for each revenue stream.
- Dermatology Centers:Southeast Asian networks in Thailand, Vietnam, and Indonesia are expanding service menus to include energy-based protocols previously concentrated in North Asian markets. Practitioner certification bottlenecks constrain safe operation of multi-wavelength systems across these emerging markets.
- Healthcare Professionals:Individual practitioners in South Korea and Japan drive demand for portable, lower-capital devices.
- Consumers:Direct-to-patient skin care sales concentrate in India's online retail channels.
Revenue concentration sits with Aesthetic Clinics. Customer acquisition investment is climbing fastest for Dermatology Centers.
Technology:
Platform convergence is blurring traditional modality boundaries, with combination systems capturing share from single-purpose equipment.
- Laser Technology:Wavelength-tunable systems address multiple chromophores without requiring separate capital equipment purchases. REACH-aligned substance restrictions on imported European devices shape raw material sourcing flexibility for Asia Pacific manufacturers.
- Radiofrequency:Thermal energy delivery with real-time tissue impedance monitoring enables practitioners to address multiple body zones without switching equipment. Chinese tier-one clinics are adopting these platforms at accelerated rates.
- Cryotherapy:Fat-freezing protocols are gaining traction in China's mid-tier clinic base as standalone and combination offerings.
- Chemical Peels:Low-cost acid formulations retain cost advantages in India's price-sensitive consumer segments, limiting premium device penetration outside metropolitan centers.
Technology deployment concentrates in Laser Technology. Platform development is accelerating most quickly in Radiofrequency.
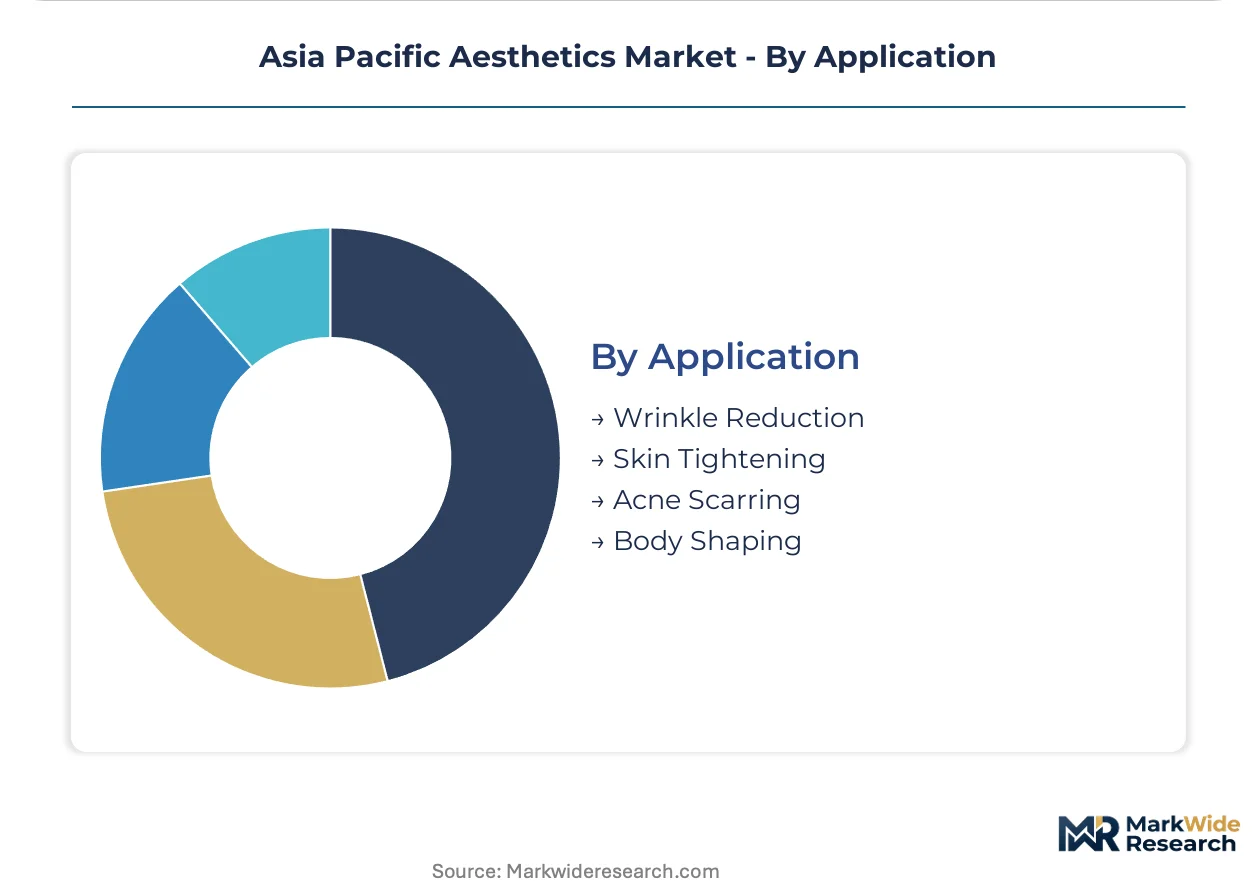
Application:
Clinical indication breadth determines device utilization rates and amortization timelines across installed equipment bases.
- Wrinkle Reduction:Hyaluronic acid formulations are restructuring cost structures by displacing collagen-based alternatives. Allergan Aesthetics leverages portfolio breadth to sustain premium positioning in China's tier-one aesthetic clinics.
- Skin Tightening:Radiofrequency-assisted lipolysis is modularizing treatment protocols across Asia Pacific aesthetic clinics, compressing the traditional separation between surgical and non-surgical body contouring service lines.
- Acne Scarring:Laser technology sustains the widest application span across this indication, though treatment complexity requires specialized practitioner training.
- Body Shaping:Combined radiofrequency-cryotherapy platforms addressing both fat reduction and skin tightening in single sessions are capturing China's expanding mid-tier clinic base.
Treatment volume concentrates in Wrinkle Reduction. Procedure growth is expanding most steeply in Body Shaping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district anchors the Asia Pacific aesthetic services ecosystem, hosting the densest concentration of dermatology clinics and device training centers worldwide. Tier-one Chinese cities absorb premium injectable volumes at multiples of provincial consumption rates. Southeast Asian markets are expanding energy-based treatment menus previously concentrated in North Asian metropolitan clusters.
China
Beijing and Shanghai absorb disproportionate shares of imported laser devices and premium hyaluronic acid formulations. NMPA's evolving biologics classification framework for combination devices extends approval timelines for novel platforms. The Yangtze River Delta aesthetic clinic chains are unbundling after-sales service contracts from hardware procurement, pressuring original equipment manufacturers to demonstrate discrete value for each revenue stream.
South Korea
Domestic botulinum toxin and filler manufacturers leverage compliant cold-chain infrastructure to serve export demand across Southeast Asia. MFDS tightened licensing requirements for hyaluronic acid fillers, accelerating quality investments among established Seoul-based producers. The Gangnam clinic cluster sustains premium positioning through specialized practitioner training programs and rapid protocol adoption cycles.
Japan
Mature injectable markets in Tokyo and Osaka sustain stable revenue pools for established toxin and filler portfolios. PMDA maintains rigorous biologics registration pathways that favor manufacturers with extensive clinical documentation. The Kansai region's aesthetic chains are adopting radiofrequency-assisted lipolysis platforms at measured rates, compressing traditional separations between surgical and non-surgical service lines.
India
Price-sensitive consumer segments in Mumbai and Delhi retain demand for chemical peels and topical retinoids over premium device protocols. CDSCO enforces distinct biologics registration pathways that fragment product launch timelines relative to North Asian markets. Maharashtra's metropolitan dermatology centers are expanding laser service menus, though practitioner certification bottlenecks constrain safe operation of multi-wavelength systems.
Thailand
Medical tourism flows concentrate demand for body contouring and skin tightening procedures in Bangkok's international-facing clinic networks. The country's national pharmaceutical regulator maintains alignment with ASEAN harmonization initiatives for device registration. Thai dermatology chains are adopting cryotherapy and radiofrequency platforms previously concentrated in South Korean and Chinese tier-one markets.
Asia Pacific Aesthetics Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend across injectable, device, and topical categories. The market structure presents a tiered configuration with premium international portfolios, established regional manufacturers, and emerging domestic specialists competing across overlapping segments. Three archetypes define positioning: multinational aesthetic portfolios with regulatory scale, Korean biologics specialists with manufacturing depth, and Chinese domestic producers with NMPA relationship advantages. M&A activity and technology licensing agreements constitute the dominant competitive moves, with several mid-scale manufacturers seeking device-injectable combination capabilities through partnership structures.
Among Korean biologics specialists, Hugel Inc. and Medytox occupy positions exemplifying manufacturing-scale archetypes, with Seoul-based production infrastructure serving export demand across Southeast Asian dermatology networks. Allergan Aesthetics represents the multinational portfolio tier, leveraging breadth across toxin, filler, and device categories to sustain premium positioning in China's tier-one aesthetic clinics. Merz Aesthetics anchors the European-origin specialist segment, with radiofrequency technology leadership differentiating its positioning in skin tightening applications.
| Leading Market Players |
|---|
| Medytox |
| Lumenis |
| Allergan Aesthetics |
| Ipsen |
| Cutera Inc. |
| Merz Aesthetics |
| Hugel Inc. |
| Revance Therapeutics |
| Galderma |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between MFDS-compliant Korean biologics and non-compliant imports manifests in pricing spreads exceeding threefold for equivalent hyaluronic acid formulations, while cold-chain infrastructure investments lock in supply chain configurations that favor Seoul-based manufacturers with captive distribution networks.
Pricing Analysis
Input-cost pass-through from biologics cold-chain requirements drives premium tier separation, with temperature-controlled logistics adding substantial landed cost differentials between Korean domestic and Southeast Asian export markets. Pricing stratifies across premium, standard, and economy tiers based on MFDS certification status and after-sales service bundling. Cost compression in India's chemical peel segment is intensifying because domestic acid manufacturers bypass import duties on European device alternatives. Dermatology centers in Thailand and Vietnam exhibit highest price sensitivity, while China's tier-one aesthetic clinics absorb premium positioning with minimal volume negotiation.
Supply Chain Analysis
Freight cost volatility across the archipelago geography of Indonesia and India's hinterland states strains botulinum toxin distribution economics, forcing inventory positioning closer to terminal demand points. Manufacturing concentrates in South Korea, China, and Japan for device assembly and biologics fill-finish operations. Raw material sourcing draws from German laser component suppliers, Japanese radiofrequency subassemblies, and domestic Chinese cooling mechanism fabrication. Single-source vulnerability runs through European REACH-aligned substance restrictions on imported optical materials. Distribution runs through specialized medical device distributors with temperature-controlled warehousing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiofrequency-cryotherapy platform convergence enables margin expansion through reduced per-session equipment turnover and higher clinic utilization rates, compressing capital recovery timelines for aesthetic service providers.
For Market Incumbents: Deploy after-sales service unbundling as a pricing lever to defend margin position against Chinese domestic producers with NMPA relationship advantages. Incumbents should consolidate practitioner certification programs in Southeast Asian markets to preempt emerging Korean biologics specialists from capturing dermatology center loyalty. Channel control through exclusive device financing partnerships with Thailand's medical tourism clinics represents a critical defensive perimeter. For New Entrants and Emerging Players: Tier-two Chinese cities present the most penetrable geography for mid-market radiofrequency platforms, with clinic density rising faster than established device financing relationships. New entrants should pursue white-space targeting of India's metropolitan dermatology centers through portable lower-capital laser systems that bypass chemical peel substitution economics. A direct-to-clinic technical training partnership model offers the strongest go-to-market angle against incumbent distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where NMPA registration timelines fragment multi-country portfolios and compliance costs outscale standalone revenue bases. Long-term viability in this market hinges on capturing combination device-injectable capabilities through technology licensing rather than organic development. Investors should monitor MFDS biologics pathway harmonization signals as the critical inflection indicator for Korean manufacturer valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Investment | Seoul-based manufacturers leverage compliant infrastructure to capture Southeast Asian export demand. |
| AI-Driven Diagnostic Integration | Machine learning treatment planning reduces practitioner training curves and standardizes outcomes. |
| After-Sales Service Unbundling | Chinese tier-one clinics separate hardware procurement from maintenance contracts, pressuring OEM pricing. |
| Radiofrequency-Cryotherapy Convergence | Combined modality platforms capture China's mid-tier clinic base with single-session fat reduction and skin tightening. |
| Southeast Asia Clinic Network Expansion | Thai and Vietnamese dermatology centers adopt energy-based protocols previously concentrated in North Asian markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aesthetic clinic operators, dermatology center procurement managers, biomedical engineers at device manufacturers, and regulatory affairs specialists at Korean and Chinese biologics firms. Secondary validation drew from NMPA device registration databases, MFDS biologics licensing records, hospital procurement contract filings, and customs trade data on laser and radiofrequency equipment imports. Bottom-up clinic density modeling and top-down regional market sizing provided cross-check triangulation.
Comparable-period anchoring linked projection assumptions to historical adoption curves across China's tier-one city rollout patterns and South Korea's Gangnam district clinic expansion cycles. Segmentation modeling captured product type, customer tier, technology platform, and clinical application dimensions across the analysis window. CAGRs derived from equipment replacement cycles, consumable attach rates, and regulatory approval velocity assumptions specific to aesthetic device and biologics markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA biologics reclassification decisions and ASEAN regulatory harmonization progress. Forecasts reflect documented assumptions about cold-chain infrastructure buildout rates and practitioner certification pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Services Market