
 Global Cellulite Treatment Market | 2026-2036
Global Cellulite Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cellulite Treatment Market Foresight
The gap between premium energy-based systems and commodity mechanical massage devices is expanding as physician-dispensed protocols separate from over-the-counter wellness offerings. Merz Pharma leverages its injectable portfolio to anchor physician office positioning against lower-tier alternatives. Hologic competes through integrated platform ecosystems that bundle diagnostic imaging with treatment delivery. Alma Lasers specializes in multi-wavelength laser systems that dominate premium clinic segments across Latin America and the Middle East.
Cellulite treatment encompasses non-invasive and minimally invasive procedures that target subcutaneous fat lobules and connective tissue septae through thermal, mechanical, or chemical mechanisms, typically operating at radiofrequency ranges of 1-40 MHz or acoustic wave pressures of 0.1-0.4 MPa to induce collagen remodeling and lymphatic drainage. Laser therapy and radiofrequency segments command premium pricing due to capital equipment intensity and repeat session economics, while acoustic wave therapy represents the fastest-growing modality as clinics adopt lower-cost entry points. Injectable fillers occupy a concentrated margin pool where hyaluronic acid and collagenase formulations require prescriber certification, limiting channel proliferation compared to device-based alternatives.
FDA clearance pathways under 510(k) and de novo classifications shape device commercialization timelines, while the EU Medical Device Regulation mandates notified body involvement for energy-based systems above certain risk thresholds. ISO 13485 quality management standards govern manufacturing consistency across export-oriented suppliers from Israel, Germany, and the United States. Stakeholders must monitor evolving reimbursement categorizations for aesthetic procedures as private insurers in Brazil and South Korea experiment with limited coverage for medically indicated cases.
Market Dynamics
EU Medical Device Regulation premarket clinical requirements are compressing commercialization timelines for radiofrequency and acoustic wave systems, forcing manufacturers to front-load clinical evidence generation before notified body submissions.
Growth Catalysts
- Combination protocol adoption:Brazilian medical spas are integrating radiofrequency with acoustic wave therapies into standardized treatment menus, creating repeatable revenue streams that justify capital equipment investments.
- MFDS fast-track pathways:South Korea's pharmaceutical and medical device regulator has streamlined 510(k)-equivalent clearances for energy-based aesthetic devices, accelerating technology turnover in Seoul's Gangnam aesthetic cluster.
- Collagenase enzyme advancement:Injectable cellulite treatments utilizing collagenase formulations are expanding prescriber-certified service lines in physician offices, anchoring premium positioning against device-only competitors.
Market Restraints
- Notified body bottlenecks:EU MDR risk-classification upgrades for energy-based systems above 1 MHz are extending conformity assessment timelines by 12-18 months for German and Israeli manufacturers.
- Capital intensity barriers:Multi-wavelength laser platforms require $150,000-$400,000 upfront investment, limiting clinic penetration outside premium urban aesthetic clusters.
- Mechanical massage substitution:Lower-cost vacuum-roller devices for home use are capturing price-sensitive consumers who would otherwise seek professional radiofrequency sessions.
Strategic Opportunities
- Middle East clinic expansion:Dubai and Riyadh medical tourism corridors are underpenetrated for combination acoustic-radiotherapy protocols, presenting first-mover positioning for equipment suppliers.
- Reimbursement experimentation:Private insurers in Brazil are piloting limited coverage for cellulite treatments medically indicated for lipedema, creating precedent for indication expansion.
- AI-guided parameter optimization:Machine learning integration with radiofrequency devices is enabling real-time tissue impedance feedback, differentiating premium platforms from fixed-protocol competitors.
Industry Challenges
- Practitioner certification gaps:Safe administration of collagenase injectables requires dermatology or plastic surgery credentials that remain scarce outside major metropolitan markets.
- ISO 13485 audit backlogs:Manufacturing quality recertification delays are disrupting supply chains for Israeli and German export-oriented device suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cellulite Treatment Market |
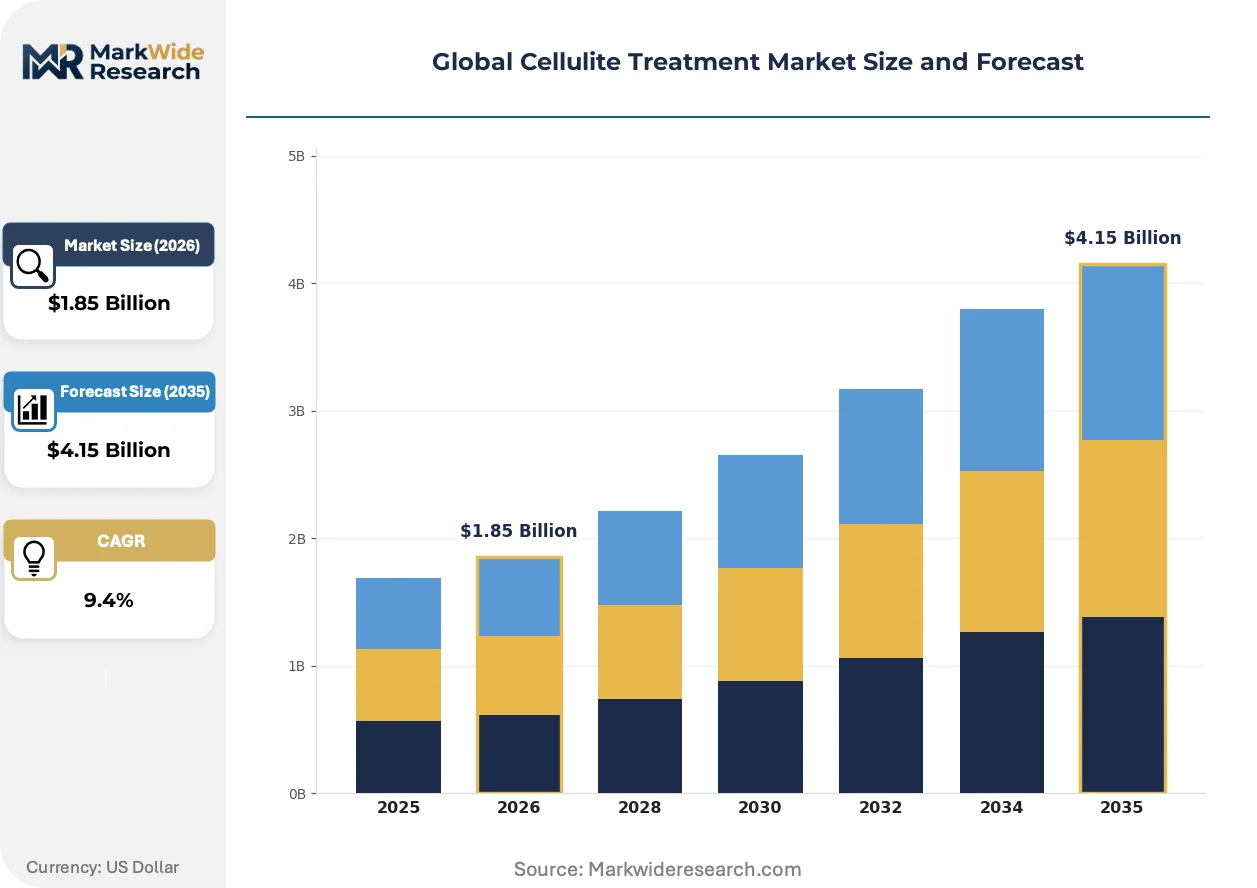
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Liposuction, Laser Therapy, Radiofrequency, Acoustic Wave Therapy, Injectable Fillers Application Area: Thighs, Buttocks, Abdomen, Arms, Hips End User: Dermatology Clinics, Medical Spas, Plastic Surgery Centers, Wellness Centers, Beauty Salons Technology: Ultrasound, Mechanical Massage, Vacuum Therapy, Cryolipolysis, Infrared Light |
| Companies Covered | Merz Pharma, Hologic, Cutera, Candela Corporation, Zimmer Aesthetics, Alma Lasers, Inceler Medikal Co Ltd, Cynosure, Syneron Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cellulite Treatment Market Shifts & Advancements
Device architecture is fragmenting into interoperable subsystems that clinics can configure across treatment modalities, while regulatory evidence requirements and procurement sophistication are simultaneously elevating.
Radiofrequency generators are modularizing into detachable handpiece ecosystems that accommodate interchangeable acoustic wave, laser, and cooling attachments. Premium clinics in São Paulo and Seoul are adopting these flexible platforms to maximize equipment utilization across multiple service lines. This architecture is compressing replacement cycles as manufacturers release firmware-upgradable base units rather than complete system overhauls.
EU MDR technical documentation requirements for energy-based aesthetic devices are mandating clinical performance data that exceeds prior Medical Device Directive standards. Manufacturers must now submit post-market surveillance protocols alongside premarket applications, increasing regulatory affairs headcount. German notified bodies are prioritizing submissions from firms with established ISO 13485 quality management systems, advantaging incumbent suppliers.
Clinic procurement is consolidating vendor relationships around integrated platform providers who bundle training, maintenance, and consumable supply. Independent aesthetic practices in Brazil are shifting from single-modality purchases to multi-year service agreements with Hologic and Alma Lasers. This concentration is most visible in South Korea's Gangnam district, where clinic density enables collective purchasing power that extracts preferential pricing and priority technical support.
Global Cellulite Treatment Market Segmentation
Segmentation in the cellulite treatment market determines equipment procurement patterns, practitioner certification requirements, and reimbursement pathways. Treatment modality and application site drive capital allocation decisions across clinic types, while technology architecture shapes competitive positioning between integrated platform suppliers and single-modality vendors.
Treatment Type:
Supply concentration in energy-based systems creates tiered competitive dynamics between capital-intensive laser platforms and accessible acoustic wave entry points.
- Laser Therapy:Multi-wavelength systems operating at 1440nm and 1064nm wavelengths target subcutaneous septae through controlled thermal injury. Demand clusters in São Paulo and Dubai premium clinics where $200,000-plus equipment investments align with medical tourism revenue models. FDA 510(k) clearance requirements and EU MDR clinical evidence mandates favor established manufacturers with regulatory affairs infrastructure.
- Radiofrequency:Devices generating electromagnetic fields at 1-40 MHz induce collagen remodeling through dermal heating. Brazilian medical spas in Rio de Janeiro and Belo Horizonte are standardizing combination protocols pairing radiofrequency with acoustic wave sequences to differentiate service menus from commodity mechanical alternatives.
- Acoustic Wave Therapy:Pressure pulses at 0.1-0.4 MPa stimulate lymphatic drainage and microcirculation. South Korean clinics in Busan and Seoul adopt these systems for lower capital entry.
- Injectable Fillers:Collagenase and hyaluronic acid formulations require prescriber certification. Demand concentrates in US dermatology practices.
- Liposuction:Surgical fat extraction remains confined to plastic surgery centers with operating room infrastructure.
Today's leader: Laser Therapy. Tomorrow's challenger: Acoustic Wave Therapy.
Application Area:
Volume distribution across body sites reflects garment exposure patterns and patient self-perception priorities in target demographics.
- Thighs:The most frequently treated site due to cellulite prevalence in gynoid fat distribution patterns. Clinics in South Korea's Gangnam district report thigh procedures generating 40% of cellulite-specific revenue, with combination radiofrequency-acoustic protocols commanding premium session pricing.
- Buttocks:Treatment demand accelerates through social media visibility trends and swimwear seasonality. Brazilian medical spas structure package pricing around buttock-thigh combination zones.
- Abdomen:Postpartum and weight fluctuation cases drive demand in US wellness centers.
- Arms:Emerging application site as sleeveless fashion norms expand.
- Hips:Often bundled with thigh protocols in European clinic pricing.
Thighs anchor current revenue. Buttocks are climbing the fastest as aesthetic priorities shift.
End User:
Customer type determines procurement sophistication, with dermatology clinics demanding clinical evidence while beauty salons prioritize equipment financing terms.
- Dermatology Clinics:Physician-supervised practices in Germany and Israel require ISO 13485-certified devices with published clinical outcomes. These sites favor collagenase injectables and premium laser platforms that support medical liability positioning.
- Medical Spas:Brazilian and Mexican facilities are expanding service menus fastest, adopting modular radiofrequency systems that accommodate multiple operators and high patient throughput.
- Plastic Surgery Centers:Concentrate on liposuction and combination surgical-non-surgical protocols.
- Wellness Centers:Price-sensitive procurement favors mechanical massage and infrared devices.
- Beauty Salons:Limited to non-invasive technologies in regulated markets.
Dermatology clinics set clinical standards. Medical spas are gaining share fastest through volume expansion.
Technology:
Architecture choices between thermal, mechanical, and acoustic mechanisms determine manufacturing complexity and service revenue potential.
- Cryolipolysis:Controlled cooling at -11°C to -5°C induces adipocyte apoptosis through crystallization. US and Canadian clinics integrate these systems into body contouring service lines, with FDA-cleared devices commanding $150,000-plus price points that limit penetration outside premium urban markets.
- Ultrasound:High-intensity focused ultrasound at 1-3 MHz targets fat lobules non-invasively. South Korean manufacturers dominate this segment, with MFDS fast-track clearances accelerating technology turnover in Seoul's aesthetic cluster.
- Mechanical Massage:Vacuum-roller systems represent the most accessible entry point. Home device substitution threatens professional service demand.
- Vacuum Therapy:Suction-based lymphatic drainage systems prevail in European wellness centers.
- Infrared Light:Lower-cost adjunct technology for circulation enhancement.
Cryolipolysis leads premium positioning. Ultrasound shows steepest expansion trajectory through Asian manufacturing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Practitioner density in aesthetic medicine clusters shapes geographic demand patterns. Dermatology-trained physicians concentrate in metropolitan corridors where clinic networks drive technology procurement cycles. Regulatory divergence between FDA pathways and EU MDR frameworks fragments commercialization timelines across jurisdictions.
United States
FDA 510(k) clearances for radiofrequency devices above 1 MHz compress premarket review periods for energy-based systems. Dermatology practices in Los Angeles and Miami anchor demand for collagenase injectables requiring prescriber certification. Private insurers in Florida are piloting limited coverage for medically indicated cellulite treatments.
Brazil
Medical spa expansion in Rio de Janeiro and Belo Horizonte drives combination protocol adoption pairing radiofrequency with acoustic wave therapies. ANVISA oversight of energy-based aesthetic devices mandates notified body equivalence for imported systems. São Paulo's clinic density enables collective purchasing power that extracts preferential equipment pricing.
Germany
EU MDR risk-classification upgrades for laser systems above 1440nm extend conformity assessment timelines by 12-18 months. ISO 13485-certified manufacturers in Bavaria and Baden-Württemberg face notified body bottlenecks for technical documentation. Berlin aesthetic practices favor physician-dispensed protocols over mechanical massage alternatives.
South Korea
MFDS fast-track pathways accelerate 510(k)-equivalent clearances for ultrasound-based devices. Seoul's Gangnam district aesthetic cluster drives technology turnover through clinic density and practitioner training standards. Busan medical spas adopt lower-cost acoustic wave entry points for price-sensitive segments.
United Arab Emirates
MOHAP medical device registration requirements for energy-based systems mandate clinical evidence submission alongside import licensing. Dubai and Riyadh medical tourism corridors remain underpenetrated for combination acoustic-radiotherapy protocols. Abu Dhabi wellness centers are expanding service menus to capture regional aesthetic tourism flows.
Global Cellulite Treatment Market Competitive Landscape
Top-tier vendors anchor premium platform ecosystems, while mid-tier specialists occupy single-modality niches. The vendor base stratifies across integrated platform providers, injectable-focused pharmaceutical houses, and regional equipment fabricators. German and Israeli manufacturers exemplify regulatory affairs infrastructure archetypes. Brazilian and South Korean clinics favor multi-year service agreements over equipment purchases. Competitive moves concentrate on M&A for technology portfolios and geographic expansion through distributor networks.
Among pharmaceutical-origin competitors, Merz Pharma exemplifies the injectable-anchored archetype through prescriber-certified service line positioning. Hologic and Alma Lasers occupy distinct platform-provider positions, with the former representing integrated diagnostic-treatment bundling and the latter exemplifying multi-wavelength laser specialization for premium clinic segments. These three anchors illustrate how competitive positioning fragments across therapeutic mechanism rather than consolidating around unified technology standards.
| Leading Market Players |
|---|
| Merz Pharma |
| Hologic |
| Cutera |
| Candela Corporation |
| Zimmer Aesthetics |
| Alma Lasers |
| Inceler Medikal Co Ltd |
| Cynosure |
| Syneron Medical |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates gate qualified supply access for premium-tier radiofrequency and laser platforms, compressing margins for manufacturers lacking ISO 13485 certification while elevating pricing power for compliant incumbents serving dermatology clinics and medical spas.
Pricing Analysis
The bundled-vs-unbundled service split separates clinic procurement patterns across the cellulite treatment landscape. Premium-mid-economy pricing differentiation rests on certification grade and after-sales service bundling, with EU MDR-compliant systems commanding substantial premiums over non-certified alternatives. Pricing pressure stems from acoustic wave therapy commoditization as South Korean and Chinese manufacturers flood mid-tier segments. Beauty salons and wellness centers exhibit acute price sensitivity, while Gangnam district aesthetic clusters prioritize clinical evidence over cost.
Supply Chain Analysis
Warehouse-distribution layer configurations favor hub-and-spoke patterns radiating from Frankfurt and Dubai to serve European and Middle Eastern aesthetic markets. Manufacturing concentrates in Israel, Germany, and the United States for radiofrequency generators, while South Korean fabricators dominate ultrasound handpiece assembly. Supply chains draw from gallium arsenide substrates, precision optical components, and medical-grade cooling systems. Single-source vulnerability concentrates in laser diode supply from German and Japanese specialty vendors. Distribution runs through authorized dealer networks with mandatory technician certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellulite treatment market functions as a stable compounder anchored by recurring consumable revenue from injectable enzyme formulations and repeat session economics in energy-based device protocols.
For Market Incumbents: Lock in prescriber-certified service lines through collagenase injectable anchoring against device-only competitors. Deepen backward integration into laser diode supply to mitigate German and Japanese single-source exposure. Prioritize firmware-upgradable platform architectures that compress replacement cycles and extract multi-year service agreements from Brazilian and South Korean clinic networks. For New Entrants and Emerging Players: The premium-economy price-point gap in acoustic wave therapy presents accessible entry into Busan and Belo Horizonte medical spa segments. Target combination protocol adoption in underpenetrated Dubai and Riyadh medical tourism corridors. Pursue MFDS fast-track equivalence to accelerate clearance velocity against entrenched ultrasound competitors. For Investors and Strategic Acquirers: Roll-up economics work for modular platform specialists because clinic procurement consolidation favors integrated vendors bundling training, maintenance, and consumable supply. The five-to-ten year viability window rewards acquisition of ISO 13485-certified manufacturers with established notified body relationships. Monitor EU MDR technical documentation submission volumes as inflection indicator for regulatory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Advancement | Accelerates notified body prioritization for German and Israeli manufacturers with established quality systems. |
| Collagenase Injectable Service Line Expansion | Anchors prescriber-certified positioning against device-only competitors in US dermatology practices. |
| Combination Protocol Standardization | Creates repeatable revenue streams justifying capital equipment investment in Brazilian medical spas. |
| MFDS Fast-Track Pathway Utilization | Compresses clearance timelines for ultrasound devices targeting Seoul's Gangnam aesthetic cluster. |
| AI-Guided Parameter Integration | Differentiates premium radiofrequency platforms through real-time tissue impedance feedback capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic operators, medical spa franchise directors, biomedical equipment procurement managers, and regulatory affairs specialists at notified bodies with secondary validation against FDA 510(k) filings, MFDS clearance databases, EU MDR technical documentation repositories, and hospital procurement contract records. Bottom-up equipment shipment modeling and top-down service revenue estimates were triangulated against practitioner density metrics in identified aesthetic clusters.
Segment-weighting approaches distributed value across treatment modality, application site, end-user type, and technology architecture dimensions throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, session economics modeling, and consumable attach-rate projections. Industry-specific inputs incorporated EU MDR conformity assessment timeline data and private insurer pilot coverage experiment outcomes in Brazil and South Korea.
Caveats apply where EU MDR notified body capacity constraints, collagenase prescriber certification bottlenecks, or acoustic wave therapy commoditization could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market