
 Photorejuvenation Market | 2026-2036
Photorejuvenation Market Size, Share, and Industry Trends Forecast 2026-2036
Photorejuvenation Market Analytics
Diode-pumped solid-state laser technology is consolidating around erbium-doped and Nd:YAG platforms that deliver superior dermal penetration with reduced thermal collateral. Lumenis Ltd. leverages its proprietary Multi-Spot technology to sustain dominance in high-volume dermatology installations across North America. Candela Corporation anchors its position through specialized vascular and pigmentation platforms that compete directly on fluence precision and pulse-width modulation.
Photorejuvenation encompasses controlled delivery of optical or radiofrequency energy to dermal and epidermal tissues, typically operating at wavelengths between 500 nm and 1600 nm with pulse durations from milliseconds to fractional microseconds, to stimulate collagen remodeling or selective photothermolysis of chromophores. Laser Devices and Intense Pulsed Light systems together occupy the largest installed base, though Radiofrequency Devices represent the fastest-growing product category as clinicians seek combination protocols with reduced downtime. Non-ablative technology leads volume shipments while ablative fractional platforms command premium positioning in high-end dermatology clinics where margin pools concentrate on per-treatment consumables and service contracts.
The FDA governs device safety and efficacy through 510(k) premarket notification and de novo classification pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for energy-based aesthetic systems sold in Europe. These frameworks shape demand by lengthening commercialization timelines for novel wavelengths but simultaneously protect incumbent positions for cleared platforms. Stakeholders must monitor evolving reimbursement postures for medically indicated photorejuvenation versus purely cosmetic applications, as this boundary increasingly determines addressable market breadth and pricing authority.
Market Dynamics
Non-ablative laser protocols are displacing chemical peels across premium dermatology installations, compressing treatment recovery windows from weeks to days and redirecting capital toward multi-wavelength platforms with consumable revenue streams.
Growth Catalysts
- MFDS fast-track approvals:South Korea's streamlined 510(k) equivalence pathway for energy-based devices accelerates commercialization timelines for novel fractional laser systems entering Seoul's medical spa chains.
- Collagen remodeling protocols:Combination radiofrequency-IPL treatments now dominate China's tier-one city clinics, pulling device procurement toward multi-modality platforms with integrated cooling systems.
- Er:YAG wavelength refinement:Advances in erbium-doped crystal manufacturing enable sub-ablative thermal injury profiles that dermatology clinics in São Paulo and Dubai actively specify in new equipment tenders.
Market Restraints
- Flashlamp replacement costs:IPL systems require consumable flashlamps priced at 15-20% of initial device capital every 18-24 months, compressing clinic operating margins in price-sensitive secondary markets.
- FDA 510(k) clinical evidence burdens:The tightened clearance pathway now demands comparative effectiveness data against predicate devices, extending premarket timelines for novel wavelength submissions.
- Diode laser component concentration:Military-grade pump diodes for solid-state platforms source primarily from three German and Japanese suppliers, creating input vulnerability for North American device assemblers.
Strategic Opportunities
- Home-use device regulation:The FDA's emerging framework for lower-fluence consumer IPL units creates a compliance pathway for brands targeting the post-professional maintenance segment in US suburban markets.
- Male aesthetic penetration:Underdeveloped clinical protocols for androgenetic alopecia and facial vascularity represent white space as Seoul clinics report 340% procedure volume increases among male patients since 2022.
- EU MDR Notified Body capacity:Bottlenecks in CE marking for energy-based devices delay competitor entry, preserving first-mover margin structures for MDR-certified platforms in German and French dermatology chains.
Industry Challenges
- Laser safety officer certification:Jurisdictions including California and Texas now mandate state-specific operator credentials, creating staffing friction for multi-site clinic chains expanding across state lines.
- Legacy IPL platform obsolescence:First-generation intense pulsed light systems lack software architecture for protocol updates, forcing capital-intensive replacement cycles at independent dermatology practices.
- Handpiece refurbishment complexity:Fractional laser handpieces require factory-authorized recalibration after 50,000-75,000 pulses, straining field service networks in dispersed geographic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photorejuvenation Market |
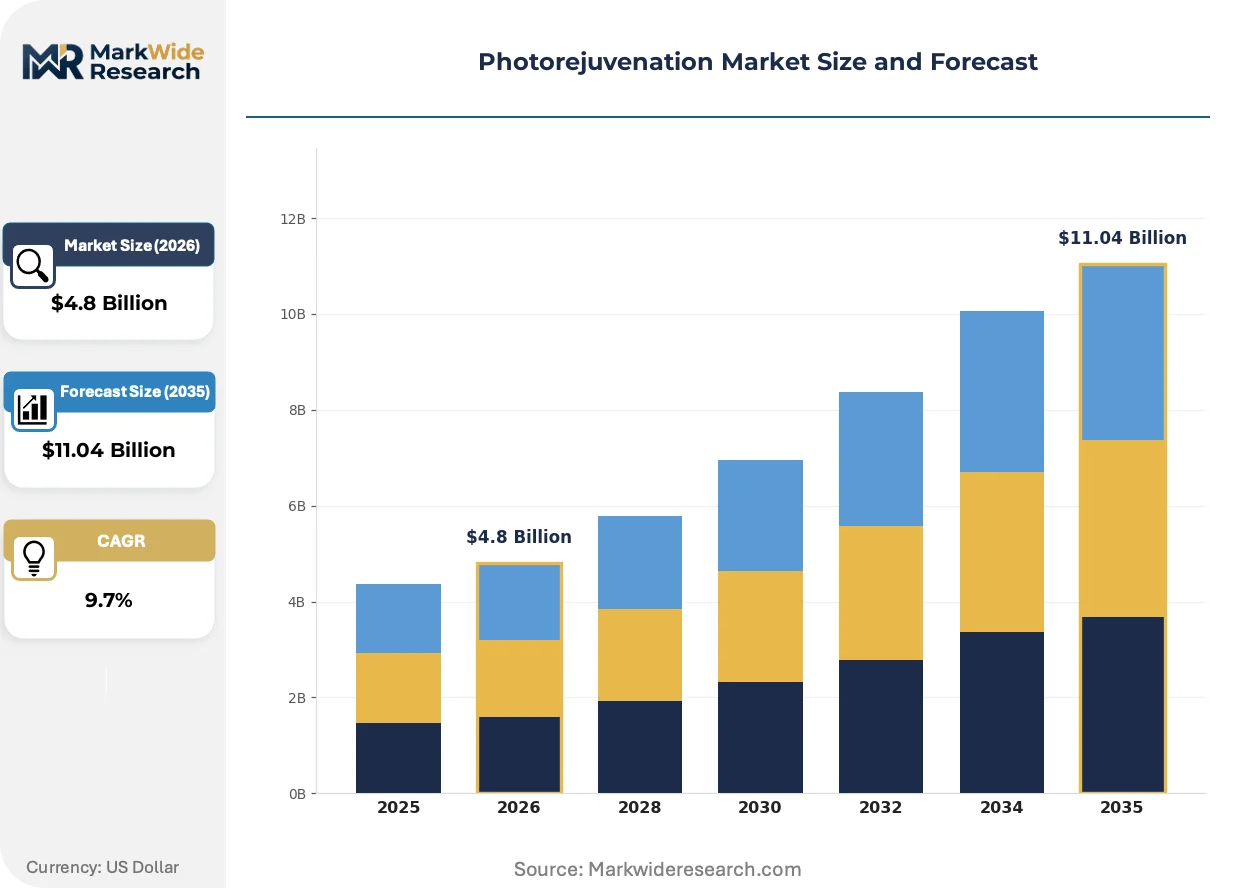
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, LED Devices, Intense Pulsed Light, Radiofrequency Devices Technology: Non-invasive, Minimally Invasive, Ablative, Non-ablative Application: Skin Tightening, Acne Scarring, Pigmentation Removal, Wrinkle Reduction End User: Dermatology Clinics, Beauty Salons, Medical Spa, Home Users |
| Companies Covered | Lumenis Ltd., Candela Corporation, Cynosure Inc., Cutera Inc., Fotona, Lutronic Corporation, Alma Lasers, Sciton, Lynton Lasers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photorejuvenation Market Evolving Landscape
Photorejuvenation technology is converging around intelligent energy delivery systems that adapt pulse parameters in real-time, collapsing the historical trade-off between treatment efficacy and thermal safety margins.
Picosecond-domain Nd:YAG platforms are electrifying pigmentation and tattoo removal applications by shattering chromophores through photomechanical rather than photothermal mechanisms. High-volume dermatology installations in Seoul and São Paulo now specify these systems as standard equipment. The technology is compressing treatment session counts by 40-60% while commanding 25-35% procedure price premiums over nanosecond alternatives.
The EU Medical Device Regulation's Annex XVI expansion now captures energy-based aesthetic devices previously exempt from clinical scrutiny. Manufacturers face mandatory post-market surveillance and periodic safety update reporting. German and French Notified Bodies are prioritizing MDR technical file reviews for combination RF-laser platforms, delaying competitor entry and preserving incumbent positioning for cleared systems.
Chinese medical spa chains are consolidating procurement authority at the corporate level, displacing individual clinic purchasing autonomy. Tier-one city operators now negotiate enterprise service contracts spanning 50-200 locations with standardized device fleets and centralized technician training. This concentration shifts vendor relationships toward multi-year consumable lock-in arrangements with penalty clauses for competitive device trials.
Photorejuvenation Market Segmentation
Photorejuvenation equipment procurement splits sharply between capital-intensive clinical installations and distributed consumer channels. Device specifications, regulatory classification, and consumable economics vary dramatically across these boundaries, forcing vendors to maintain parallel product architectures.
Product Type:
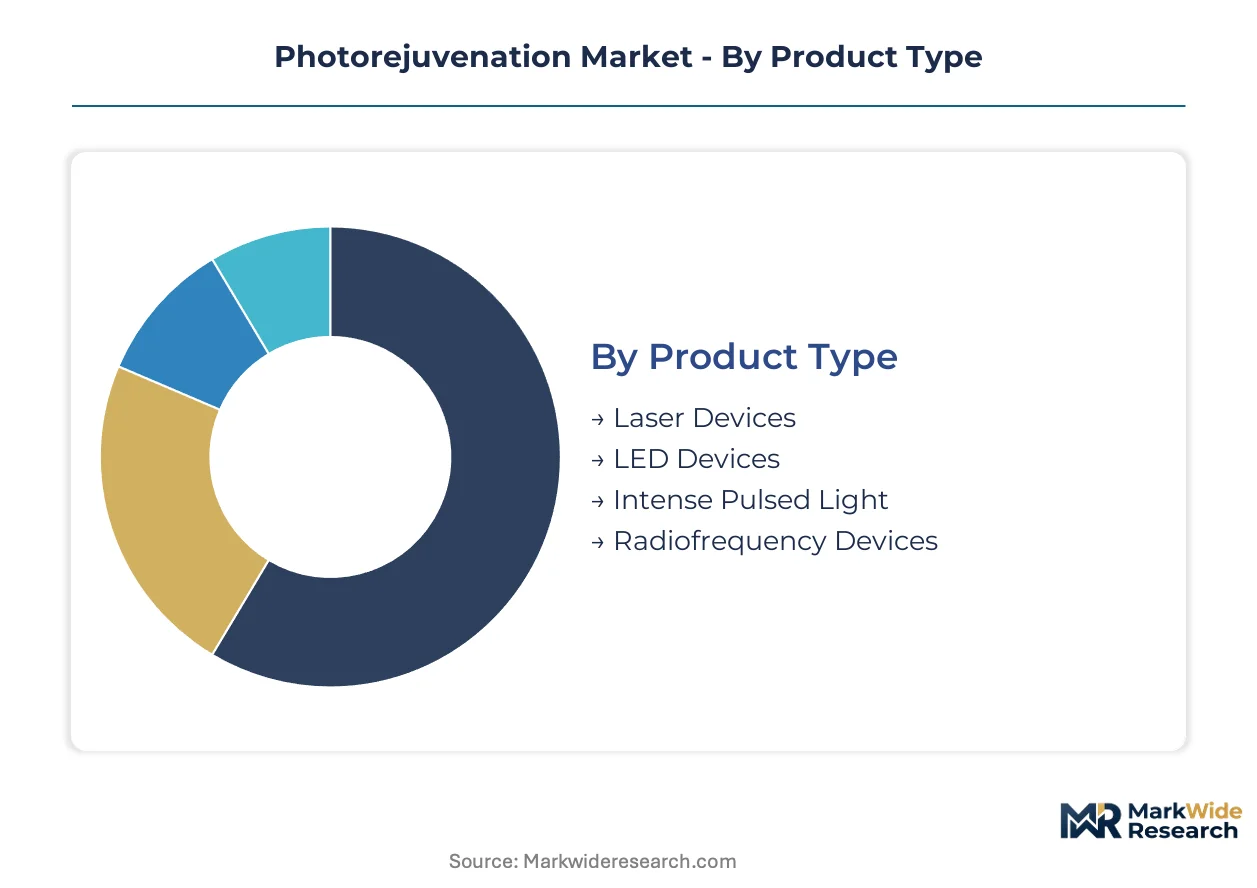
Standalone laser and IPL platforms dominate capital budgets in clinical settings, while embedded RF modules increasingly populate combination systems that bundle multiple energy modalities.
- Laser Devices:Diode-pumped solid-state architectures operating at 1064 nm, 755 nm, and 2940 nm wavelengths deliver precise chromophore targeting with tunable pulse widths. Seoul dermatology chains now specify these as anchor equipment in multi-modality treatment rooms, driven by reimbursement-adjacent indications that justify premium capital outlays.
- Intense Pulsed Light:Broadband flashlamp systems spanning 500-1200 nm enable simultaneous treatment of multiple chromophores through filtered wavelength delivery. China's tier-one medical spas are consolidating procurement around IPL platforms with integrated cooling handpieces, though consumable flashlamp replacement cycles compress operating margins.
- LED Devices:Narrow-band light-emitting diode arrays at therapeutic wavelengths support low-fluence maintenance protocols.
- Radiofrequency Devices:Monopolar and bipolar RF systems generate dermal heating through tissue impedance, increasingly embedded in combination platforms.
Volume placements concentrate in Laser Devices; the faster expansion belongs to Radiofrequency Devices.
Technology:
Technology selection determines regulatory pathway complexity and recovery window positioning, with non-ablative protocols commanding premium placement in time-constrained professional segments.
- Non-ablative:Sub-thermal injury protocols preserve stratum corneum integrity while stimulating neocollagenesis through controlled dermal heating. Dubai and São Paulo dermatology clinics actively tender for these systems as standard-of-care alternatives to ablative resurfacing, driven by patient demand for same-day social return.
- Ablative:Fractional CO2 and Er:YAG platforms deliver controlled epidermal vaporization with subsequent remodeling cascades. High-end German dermatology chains specify these for severe photodamage cases where efficacy thresholds justify extended recovery periods.
- Non-invasive:Surface-energy delivery without epidermal breach supports broad operator delegation.
- Minimally Invasive:Microneedle-assisted RF and fractional delivery systems penetrate barrier tissue with reduced thermal diffusion.
Non-ablative technology captures the dominant installed base; ablative fractional platforms claim the steepest expansion trajectory in premium clinic segments.
Application:
Application targeting determines device wavelength specification and handpiece configuration, with pigmentation and vascular indications driving distinct technology procurement patterns.
- Pigmentation Removal:Melanin-selective wavelengths at 532 nm, 755 nm, and 1064 nm target solar lentigines and post-inflammatory hyperpigmentation across diverse skin phototypes. South Korean clinics report surging male patient volumes for these indications, expanding addressable demographics beyond traditional cosmetic segments.
- Skin Tightening:Deep dermal heating through RF and near-infrared laser energy stimulates collagen contraction and remodeling. Brazilian medical spas specify combination protocols that pair tightening with adjunctive treatments, driving multi-modality platform adoption.
- Acne Scarring:Fractional ablative and non-ablative resurfacing addresses atrophic and hypertrophic scar morphology.
- Wrinkle Reduction:Rhytid treatment spans neuromodulator adjunctive use to standalone energy-based collagen stimulation.
Pigmentation Removal commands the densest procedure volume; Skin Tightening exhibits the most rapid indication expansion in combination protocol settings.
End User:
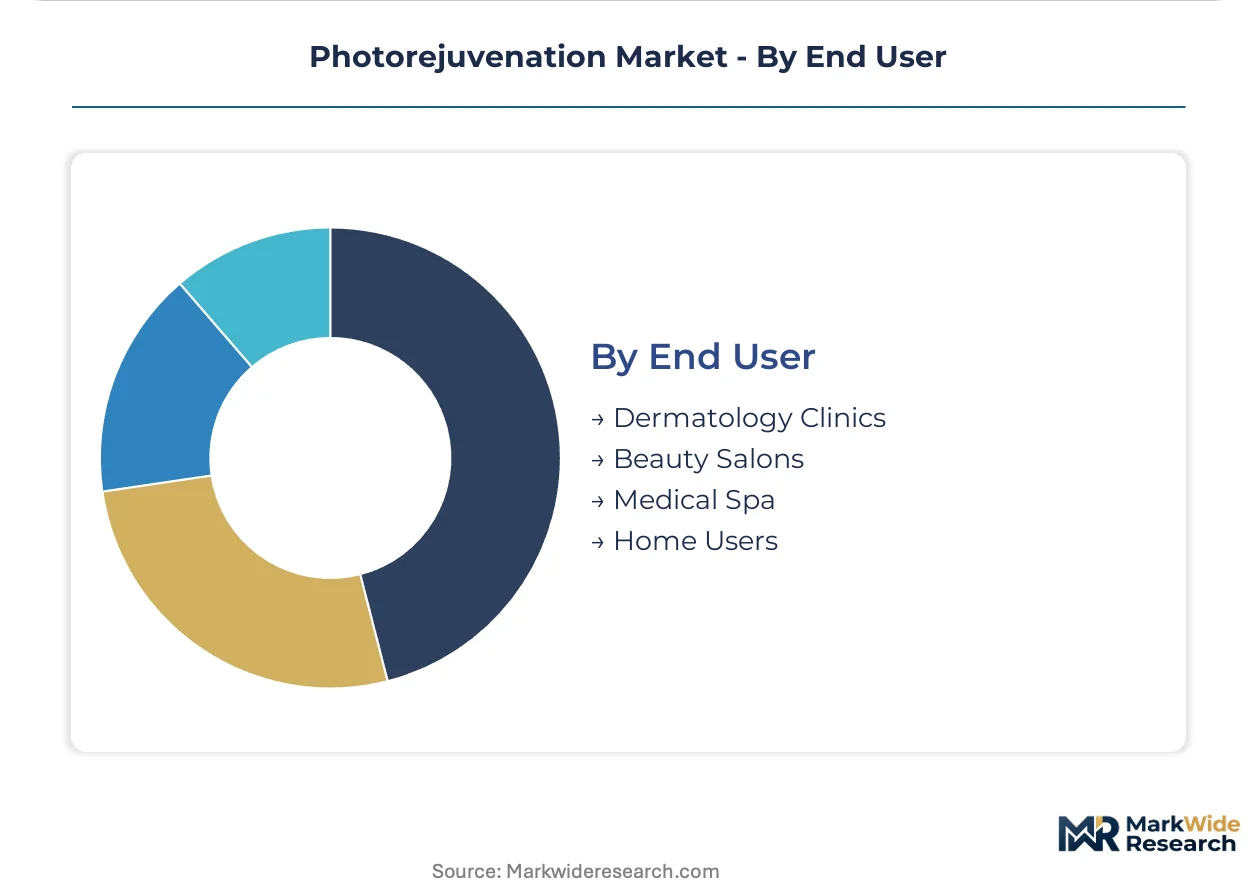
End-user channel structure dictates pricing architecture, with corporate procurement concentration in medical spa chains displacing traditional clinic-by-clinic sales approaches.
- Dermatology Clinics:Physician-supervised installations with delegated operator protocols support the broadest indication range and highest capital intensity per treatment room. These settings anchor demand for FDA 510(k)-cleared and MDR-certified platforms with comprehensive service contracting.
- Medical Spa:Corporate-owned chains with standardized technician training and centralized procurement authority now negotiate enterprise agreements spanning 50-200 locations. China's tier-one city operators are consolidating vendor relationships around multi-year consumable lock-ins with competitive trial penalties.
- Beauty Salons:Non-medical aesthetic venues with limited regulatory oversight concentrate on lower-fluence IPL and LED maintenance protocols.
- Home Users:Consumer-directed devices operating at reduced fluence thresholds target post-professional maintenance and entry-level aesthetic intervention.
Dermatology Clinics retain the largest capital deployment; Medical Spa chains are gaining share fastest through corporate procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam Medical Tourism Zone concentrates photorejuvenation device demand through tax incentives and MFDS fast-track approvals, drawing capital toward South Korean dermatology chains.
United States
FDA 510(k) clearance timelines now demand comparative effectiveness data against predicate devices, extending commercialization windows for novel wavelength submissions. California and Texas mandate state-specific laser safety officer credentials, creating staffing friction for multi-site clinic chains. Miami and Los Angeles dermatology installations anchor North American capital deployment for premium fractional platforms.
South Korea
MFDS streamlined equivalence pathways accelerate novel fractional laser commercialization for Seoul's medical spa chains. The Gangnam Medical Tourism Zone offers VAT rebates on imported capital equipment, concentrating procurement authority. Dermatology clinics in Seoul report 340% procedure volume increases among male patients since 2022, expanding addressable demographics.
Germany
EU MDR Annex XVI expansion captures energy-based aesthetic devices previously exempt from clinical scrutiny, mandating post-market surveillance. German Notified Bodies prioritize MDR technical file reviews for combination RF-laser platforms, delaying competitor entry. Frankfurt and Munich dermatology chains specify MDR-certified systems with comprehensive service contracting.
China
Tier-one city medical spa chains consolidate procurement authority at corporate level, negotiating enterprise agreements spanning 50-200 locations. NMPA regulatory alignment with international standards shapes device import pathways. Shanghai and Beijing operators standardize device fleets with centralized technician training and multi-year consumable lock-ins.
Brazil
ANVISA regulatory frameworks for energy-based devices require clinical evidence submission for novel wavelength platforms. São Paulo dermatology clinics actively tender for sub-ablative thermal injury profiles as standard-of-care alternatives. Brazilian medical spas specify combination protocols pairing skin tightening with adjunctive treatments, driving multi-modality platform adoption.
Photorejuvenation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium clinical installations consolidating around cleared platforms while secondary markets fragment across refurbished equipment channels. The vendor base stratifies into three tiers: integrated energy-device conglomerates with multi-wavelength portfolios, specialized laser OEMs focused on single-modality excellence, and regional assemblers serving price-sensitive markets. Dominant competitive moves include M&A activity targeting complementary wavelength technologies and strategic partnerships for consumable supply chain security.
Within the integrated conglomerate tier, Lumenis Ltd. and Candela Corporation occupy positions defined by proprietary delivery technologies and established service networks. Alma Lasers exemplifies the specialized OEM archetype with focused platform development for specific chromophore applications. These three entities anchor the competitive structure through differentiated approaches to wavelength coverage and geographic certification depth.
| Leading Market Players |
|---|
| Lumenis Ltd. |
| Candela Corporation |
| Cynosure Inc. |
| Cutera Inc. |
| Fotona |
| Lutronic Corporation |
| Alma Lasers |
| Sciton |
| Lynton Lasers Ltd |
| Others |
Value Network & Pricing Analysis
Military-grade pump diodes from German and Japanese suppliers cascade through three distinct pricing tiers as they reach North American device assemblers, Seoul dermatology chains, and Chinese medical spa procurement desks. Flashlamp replacement cycles every 18-24 months compress clinic operating margins and redirect buyer preference toward solid-state laser platforms with longer service intervals.
Pricing Analysis
Short lead-time premiums of 15-25% apply to MFDS fast-track cleared devices serving Seoul's Gangnam Medical Tourism Zone, while spot inventory of refurbished IPL handpieces trades at 30-40% discounts to factory-new equivalents. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified combination RF-laser platforms from single-modality systems and gray-market refurbished equipment. Pricing pressure stems from Chinese medical spa chains consolidating procurement authority and demanding enterprise service contracts with multi-year consumable lock-ins. Independent dermatology practices in secondary markets exhibit highest price sensitivity, whereas Seoul's corporate clinic chains prioritize technology refresh cycles over unit economics.
Supply Chain Analysis
China's NMPA domestic-content mandates for medical device registration are reshaping sourcing patterns for RF module assembly and cooling system fabrication. Component concentration centers on Germany and Japan for military-grade pump diodes, South Korea for MFDS-certified fractional laser handpieces, and China for LED array manufacturing. Raw material dependencies include erbium-doped yttrium aluminum garnet crystals, xenon flashlamps, and gallium arsenide diode substrates. Single-source vulnerability characterizes the pump diode tier where three suppliers control 90% of military-grade output. Distribution runs through authorized service networks for premium clinical installations and direct-to-clinic e-commerce channels for consumables and replacement handpieces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photorejuvenation equipment manufacturing is consolidating around cleared-platform incumbents as FDA 510(k) clinical evidence burdens and EU MDR Annex XVI compliance costs force sub-scale competitors toward exit or acquisition.
For Market Incumbents: Anchor market position through captive supply agreements for military-grade pump diodes, eliminating exposure to German and Japanese supplier concentration. Pursue MDR certification depth across combination RF-laser platforms before Notified Body bottlenecks clear, preserving first-mover margin structures in Frankfurt and Munich dermatology chains. Vertical integration into erbium-doped crystal manufacturing mitigates raw material cost volatility from three-supplier concentration. For New Entrants and Emerging Players: Male aesthetic protocols in Seoul represent the most penetrable buyer archetype, with 340% procedure volume expansion since 2022 and underdeveloped clinical standards for androgenetic alopecia and facial vascularity. Target FDA's emerging home-use device framework for lower-fluence consumer IPL units, leveraging compliance pathway clarity against incumbent hesitation. Go-to-market angle should emphasize post-professional maintenance subscriptions with suburban US demographic targeting. For Investors and Strategic Acquirers: MFDS fast-track approval announcements from Seoul-based device developers are the leading indicator that regional procurement consolidation is accelerating and enterprise service contract economics are stabilizing. Five-to-ten year viability favors specialized laser OEMs with single-modality excellence and established Notified Body relationships over diversified industrial conglomerates with shallow aesthetic device certification. Signal to monitor: Chinese medical spa chain IPO filings revealing standardized fleet procurement values and consumable lock-in penalty structures.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Prioritization | Delays competitor entry into German and French dermatology chains, preserving incumbent pricing authority. |
| Pump Diode Supply Agreement | Eliminates single-source vulnerability for North American device assemblers dependent on German and Japanese suppliers. |
| Home-Use Device FDA Submission | Captures post-professional maintenance segment in US suburban markets before pathway clarity attracts competition. |
| Male Aesthetic Protocol Development | Addresses 340% procedure volume expansion in Seoul clinics with underdeveloped standards for androgenetic alopecia. |
| Enterprise Service Contract Negotiation | Locks Chinese medical spa chains into multi-year consumable arrangements with competitive trial penalties. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR Annex XVI technical file guidance, MFDS equivalence pathway regulations, and NMPA medical device import standards, complemented by interviews with dermatology clinic procurement directors, biomedical equipment service engineers, medical spa chain operations executives, and GPO contracts managers. Secondary validation drew from hospital procurement databases, GPO pricing benchmarks, and customs records for laser and IPL device trade flows. Bottom-up triangulation across equipment installation counts and top-down verification through manufacturer revenue disclosures anchored market size estimates.
Installed base projections and revenue forecasts across the analysis window reflect segmented modeling by product type, technology protocol, application indication, and end-user channel. Segmentation dimensions incorporated wavelength specification, ablative versus non-ablative thermal injury profile, and corporate procurement concentration tier. CAGRs derived from procedure volume growth rates in Seoul, Shanghai, and São Paulo clinic networks, cross-referenced with device replacement cycle data and consumable attach rates.
Revisions become necessary when FDA 510(k) predicate device requirements shift materially, EU MDR Notified Body capacity expands abruptly, or Chinese medical spa chain consolidation reverses toward clinic-level purchasing autonomy. Forecasts reflect assumptions about regulatory pathway stability and procurement authority concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market