
 Global Facial Fat Transfer Market | 2026-2036
Global Facial Fat Transfer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Facial Fat Transfer Market Foresight
Aftermarket consumable revenue from fat harvesting cannulas and filtration kits is reconfiguring margin pools away from capital equipment toward recurring supply streams. Allergan Plc leverages its aesthetic portfolio breadth to cross-sell complementary injectables alongside fat transfer procedures. Alma Lasers anchors its position through integrated laser-assisted lipolysis systems that streamline tissue preparation. Merz Pharma competes via specialized microcannula portfolios designed for precision facial contouring.
Facial fat transfer encompasses the harvest, processing, and reinjection of autologous adipose tissue to restore facial volume or correct contour defects, typically requiring centrifugation at 3000 rpm for three minutes to isolate viable adipocytes for graft survival. The procedure serves both reconstructive applications following trauma or oncologic surgery and elective cosmetic enhancement of malar, periorbital, and mandibular regions. Autologous fat grafting dominates procedure volumes due to its established safety profile and dual benefit of donor-site contouring, while nanofat grafting is gaining traction for superficial dermal rejuvenation where stromal vascular fraction concentration matters more than bulk volume. Plastic surgery clinics capture the largest share of end-user revenue through bundled surgical packages, though medical spas are expanding into microfat transfer for lower-complexity indications.
The FDA regulates fat transfer systems as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates notified body oversight for adipose tissue processing equipment under stricter biocompatibility standards. ISO 13485 certification has become a baseline requirement for suppliers seeking access to institutional procurement channels in both jurisdictions. Stakeholders must monitor evolving reimbursement policies for autologous tissue procedures as payers scrutinize cosmetic versus reconstructive coding distinctions.
Market Dynamics
Recurring consumable revenue from fat harvesting cannulas and filtration kits is reconfiguring margin pools away from capital equipment, forcing manufacturers to build annuity-like supply contracts with high-volume plastic surgery clinics.
Growth Catalysts
- EU MDR compliance deadlines:Stricter biocompatibility standards for adipose tissue processing equipment are accelerating hospital replacement cycles, creating upgrade demand for certified centrifugation systems.
- Autologous graft safety profile:Elimination of foreign-body rejection risk drives preference over synthetic fillers in reconstructive applications following oncologic surgery.
- Nanofat concentration protocols:Stromal vascular fraction isolation for superficial dermal rejuvenation is expanding addressable indications beyond volume restoration.
Market Restraints
- Donor-site morbidity variability:Liposuction harvest complications limit candidacy in patients with insufficient subcutaneous adipose reserves.
- Adipocyte viability inconsistency:Graft survival rates fluctuate with practitioner technique, constraining standardization and predictable outcomes.
- Cosmetic procedure taxation:Select US states impose sales tax on elective aesthetic services, compressing clinic margins and procedure accessibility.
Strategic Opportunities
- Medical spa channel expansion:Lower-complexity microfat transfer indications offer entry into retail aesthetic settings with reduced regulatory burden.
- Laser-assisted lipolysis integration:Converging energy-based tissue preparation with traditional mechanical harvest streamlines operative workflow.
- Reconstructive coding optimization:Distinguishing post-trauma and post-oncologic applications from elective cosmetic procedures unlocks payer reimbursement pathways.
Industry Challenges
- ISO 13485 certification timelines:Institutional procurement channels now mandate quality management system accreditation, extending supplier onboarding to 18-24 months.
- Adipocyte handling protocol standardization:Absence of consensus on centrifugation speed, duration, and filtration mesh size fragments training requirements across clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Facial Fat Transfer Market |
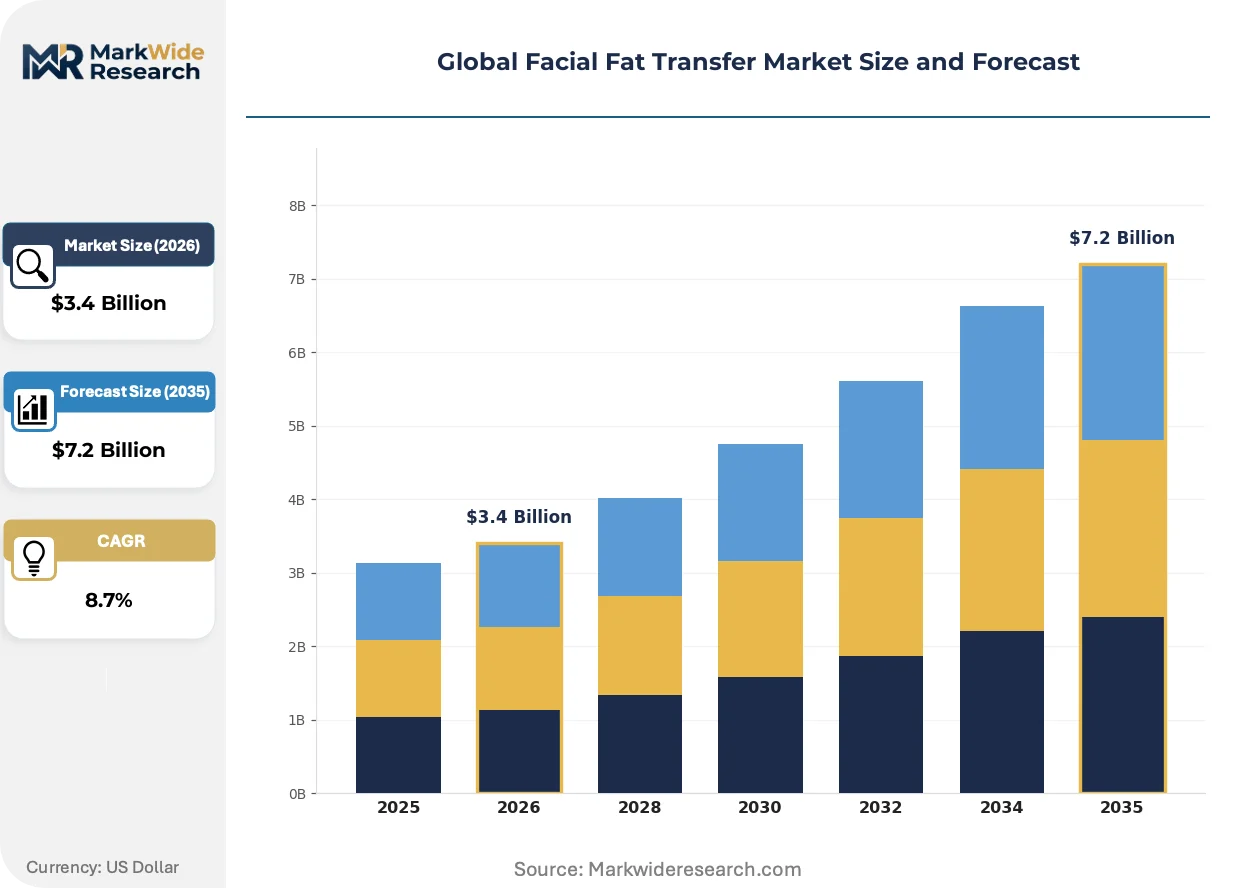
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Autologous Fat Grafting, Structural Fat Grafting, Microfat Transfer, Nanofat Grafting, Macrofat Grafting Indication: Facial Contouring, Volume Augmentation, Scar Correction, Rhinoplasty Enhancement, Reconstructive Surgery End User: Plastic Surgery Clinics, Dermatology Centers, Medical Spas, Cosmetic Surgery Hospitals, Outpatient Surgical Centers Delivery Technique: Manual Injection, Microcannula-Assisted, Ultrasound-Guided, Laser-Assisted, Power-Assisted Liposuction |
| Companies Covered | Allergan Plc, Alma Lasers, Ranfac Corp, Medikan International Inc, Integra LifeSciences Corporation, Galderma Laboratories, Merz Pharma, Tulip Medical Products, Human Med AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Facial Fat Transfer Market Shifts & Advancements
Technology convergence between energy-based tissue preparation and precision reinjection systems is compressing operative time while elevating graft survival predictability. This shift demands new competency profiles from device manufacturers and surgical training programs alike.
Closed-system fat harvesting is migrating from manual syringe-based aspiration to automated, sterile field-contained processing. High-volume cosmetic surgery hospitals in Miami and Los Angeles are adopting these systems to reduce operative room turnover time. The technology is migrating from capital-intensive institutional settings toward portable configurations suitable for ambulatory surgical centers, compressing the addressable market tier structure.
The EU Medical Device Regulation's stricter classification of adipose tissue processing equipment is elevating notified body oversight requirements. Manufacturers must now demonstrate enhanced biocompatibility testing for centrifugation chambers and filtration membranes. European plastic surgery clinics are responding by consolidating supplier relationships toward full-portfolio vendors capable of end-to-end compliance documentation.
Service unbundling is fragmenting traditional surgical package economics. Patients increasingly procure fat harvesting, processing, and reinjection as discrete line items, particularly in medical spa settings where financing options vary by procedure phase. This pattern is most pronounced in the United States, where third-party patient financing platforms dominate elective aesthetic transactions.
Global Facial Fat Transfer Market Segmentation
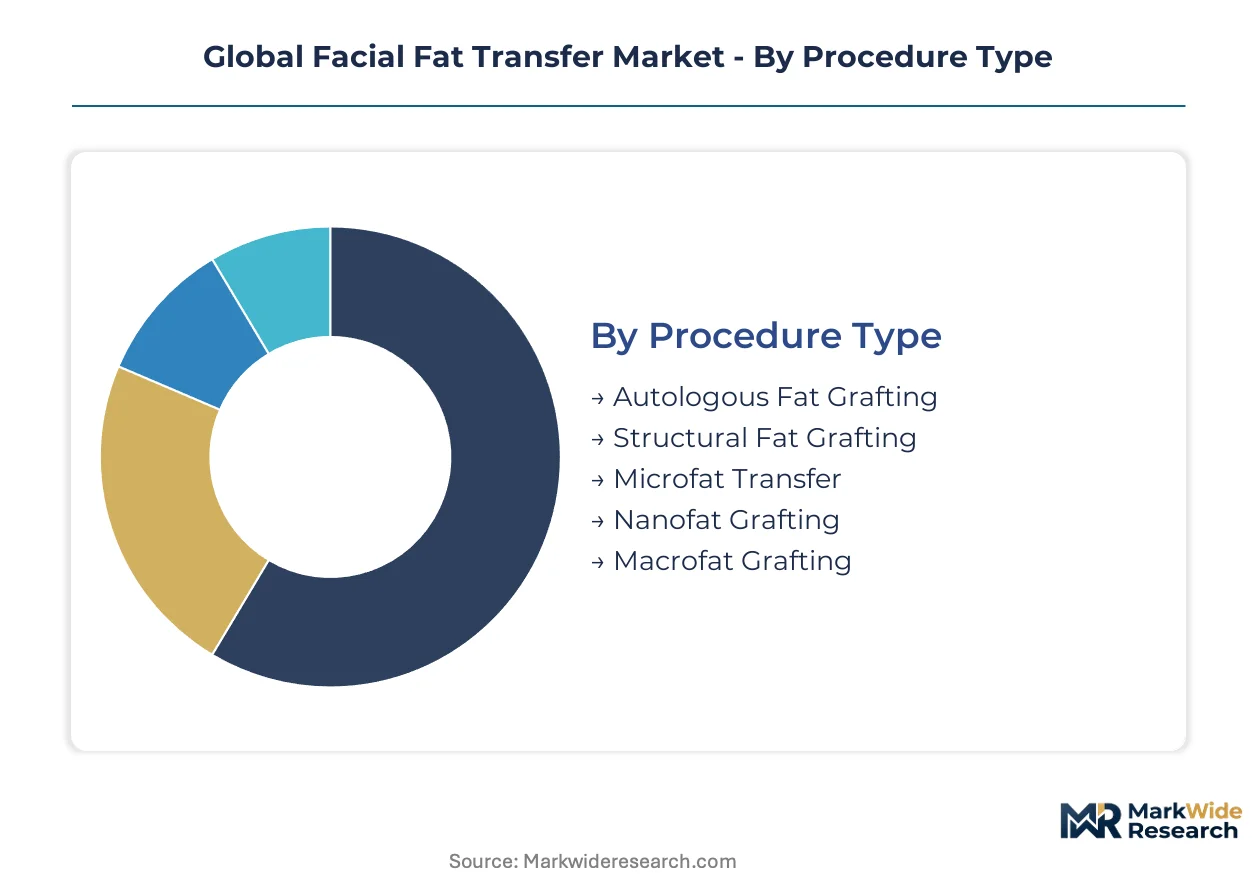
Segmentation in facial fat transfer reveals how procedural complexity, clinical setting, and delivery technology stratify both pricing power and recurring revenue potential. Each dimension exposes distinct margin architectures and vendor lock-in opportunities.
Procedure Type:
After-sales intensity concentrates in processing consumables and practitioner certification programs, with advanced techniques demanding sustained vendor engagement.
- Autologous Fat Grafting:The foundational technique harvests, centrifuges, and reinjects adipose tissue without structural modification. Demand clusters in Miami and Los Angeles cosmetic surgery hospitals where bundled surgical packages dominate procedural economics.
- Structural Fat Grafting:Large-volume lipoaspirate placement for malar and mandibular reconstruction requires specialized harvesting cannulas with larger bore diameters. Reconstructive applications in post-oncologic settings drive preference over synthetic alternatives due to elimination of foreign-body rejection risk.
- Microfat Transfer:Finely processed adipose for periorbital and superficial applications is gaining traction in medical spa channels with reduced regulatory burden.
- Nanofat Grafting:Stromal vascular fraction isolation for dermal rejuvenation expands indications beyond volume restoration into superficial skin quality improvement.
- Macrofat Grafting:Bulk volume transfer for severe facial lipoatrophy serves reconstructive surgery centers managing post-trauma defects.
By volume, Autologous Fat Grafting leads. By growth pace, Nanofat Grafting is ahead.
Indication:
Application-specific reimbursement coding and patient financing eligibility fragment addressable markets across elective versus medically necessary procedures.
- Facial Contouring:Elective enhancement of malar, mandibular, and temporal regions constitutes the largest revenue pool. Plastic surgery clinics in the United States capture premium pricing through bundled aesthetic packages.
- Volume Augmentation:Restoration of age-related lipoatrophy targets an expanding demographic of patients seeking alternatives to hyaluronic acid fillers. The procedure's dual benefit of donor-site contouring drives preference in high-volume aesthetic markets.
- Scar Correction:Post-traumatic and post-surgical defect repair occupies a reconstructive coding category with stronger payer pathways than elective applications.
- Rhinoplasty Enhancement:Adjunctive fat grafting for nasal dorsum and tip refinement requires precision microcannula delivery systems.
- Reconstructive Surgery:Post-oncologic facial restoration following ablative surgery commands institutional procurement contracts with stringent ISO 13485 requirements.
Volume Augmentation generates the highest procedure counts. Reconstructive Surgery commands the steepest expansion trajectory as coding optimization unlocks reimbursement.
End User:
Customer-type concentration determines contract structure, with institutional buyers negotiating annuity-like supply agreements while retail channels favor transactional purchasing.
- Plastic Surgery Clinics:High-volume aesthetic practices in Miami and Los Angeles drive procedural innovation and early adoption of closed-system harvesting technologies. These facilities capture the largest share of end-user revenue through bundled surgical packages.
- Cosmetic Surgery Hospitals:Institutional settings prioritize operative room turnover efficiency and regulatory compliance documentation. EU MDR certification requirements are accelerating replacement cycles for centrifugation systems in European facilities.
- Dermatology Centers:Physician-directed aesthetic practices are expanding into lower-complexity microfat indications with reduced capital equipment requirements.
- Medical Spas:Retail aesthetic settings are penetrating microfat transfer for superficial rejuvenation, leveraging third-party patient financing platforms.
- Outpatient Surgical Centers:Ambulatory settings demand portable processing configurations suitable for reduced infrastructure footprints.
Plastic Surgery Clinics dominate current volume. Medical Spas are climbing the fastest as channel expansion lowers barriers to entry.
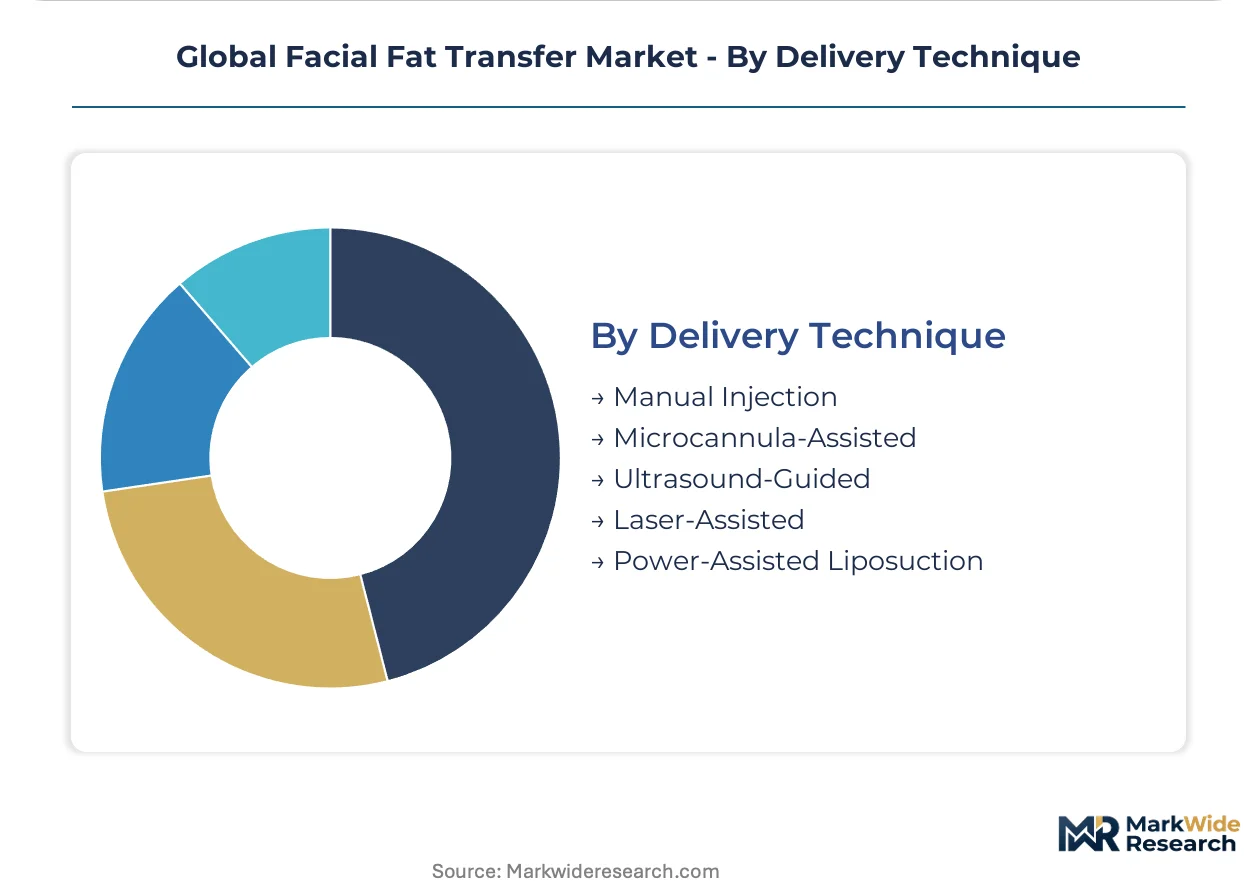
Delivery Technique:
Technology tiering separates premium precision systems from standard mechanical approaches, with energy-based modalities commanding equipment premiums and specialized training revenue.
- Microcannula-Assisted:Precision blunt-tip delivery systems minimize vascular injury risk and enable layered placement for natural contouring. Specialized microcannula portfolios designed for facial applications command premium pricing in precision-focused practices.
- Manual Injection:Syringe-based aspiration remains the baseline technique across cost-sensitive settings and training institutions. The method's minimal capital requirement sustains penetration in emerging markets and small-scale practices.
- Ultrasound-Guided:Real-time visualization for structural graft placement reduces complications in high-risk anatomical zones.
- Laser-Assisted:Energy-based tissue preparation streamlines operative workflow and is converging with traditional mechanical harvest in integrated system offerings.
- Power-Assisted Liposuction:Automated harvest systems reduce operator fatigue and improve lipoaspirate quality consistency in high-volume settings.
Manual Injection retains the largest installed base. Microcannula-Assisted methods are gaining share fastest as safety profiles and outcomes data mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for facial fat transfer procedures diverges sharply across markets. Elective cosmetic patients in the United States absorb premium pricing through third-party financing platforms, while reconstructive cases in Germany and Japan face stringent payer scrutiny that compresses margins.
United States
Miami and Los Angeles cosmetic surgery hospitals drive procedural innovation through bundled aesthetic packages. The FDA regulates fat transfer systems as Class II medical devices under 510(k) premarket notification pathways. Plastic surgery clinics in these coastal metros are consolidating toward closed-system harvesting technologies to reduce operative room turnover time.
Germany
EU MDR compliance deadlines are accelerating replacement cycles for centrifugation systems in reconstructive surgery centers. The country's national medical device regulator mandates enhanced biocompatibility testing for adipose tissue processing equipment. Bavarian plastic surgery clinics are consolidating supplier relationships toward full-portfolio vendors capable of end-to-end compliance documentation.
Japan
Precision-focused aesthetic practices in Tokyo and Osaka command premium positioning for microcannula-assisted delivery techniques. The country's pharmaceutical and medical device agency maintains stringent oversight of adipose tissue processing equipment. Kansai-region cosmetic surgery hospitals are adopting automated harvest systems to improve lipoaspirate quality consistency.
Brazil
São Paulo's medical spa channel is expanding into lower-complexity microfat transfer indications with reduced capital equipment requirements. The national health surveillance agency regulates fat harvesting systems under risk-based classification frameworks. Clinics in the Southeast region are leveraging third-party patient financing platforms to broaden elective aesthetic accessibility.
South Korea
Seoul Capital Area dermatology centers are penetrating nanofat grafting for superficial dermal rejuvenation beyond traditional volume restoration. The Ministry of Food and Drug Safety oversees adipose tissue processing equipment under medical device quality management requirements. Gangnam-based aesthetic practices are driving adoption of laser-assisted lipolysis integration for streamlined operative workflow.
Global Facial Fat Transfer Market Competitive Landscape
Full-portfolio aesthetic conglomerates and specialized precision-device manufacturers split the market along capability depth versus breadth. The vendor base concentrates around three strategic archetypes: diversified medical aesthetics houses with cross-selling infrastructure, dedicated fat transfer technology specialists with concentrated R&D, and energy-based device manufacturers converging into tissue preparation workflows. Dominant competitive moves include portfolio diversification into adjacent injectable categories and vertical integration of consumable supply chains to capture recurring revenue streams.
Within the diversified conglomerate tier, Allergan Plc and Galderma Laboratories exemplify cross-selling infrastructure that bundles fat transfer procedures with complementary aesthetic injectables. Alma Lasers anchors the energy-based convergence archetype through its Israeli-origin positioning in laser-assisted modalities. Among precision-device specialists, Merz Pharma's German GmbH structure represents concentrated expertise in microcannula portfolios designed for facial contouring applications.
| Leading Market Players |
|---|
| Allergan Plc |
| Alma Lasers |
| Ranfac Corp |
| Medikan International Inc |
| Integra LifeSciences Corporation |
| Galderma Laboratories |
| Merz Pharma |
| Tulip Medical Products |
| Human Med AG |
| Others |
Supply & Pricing Matrix
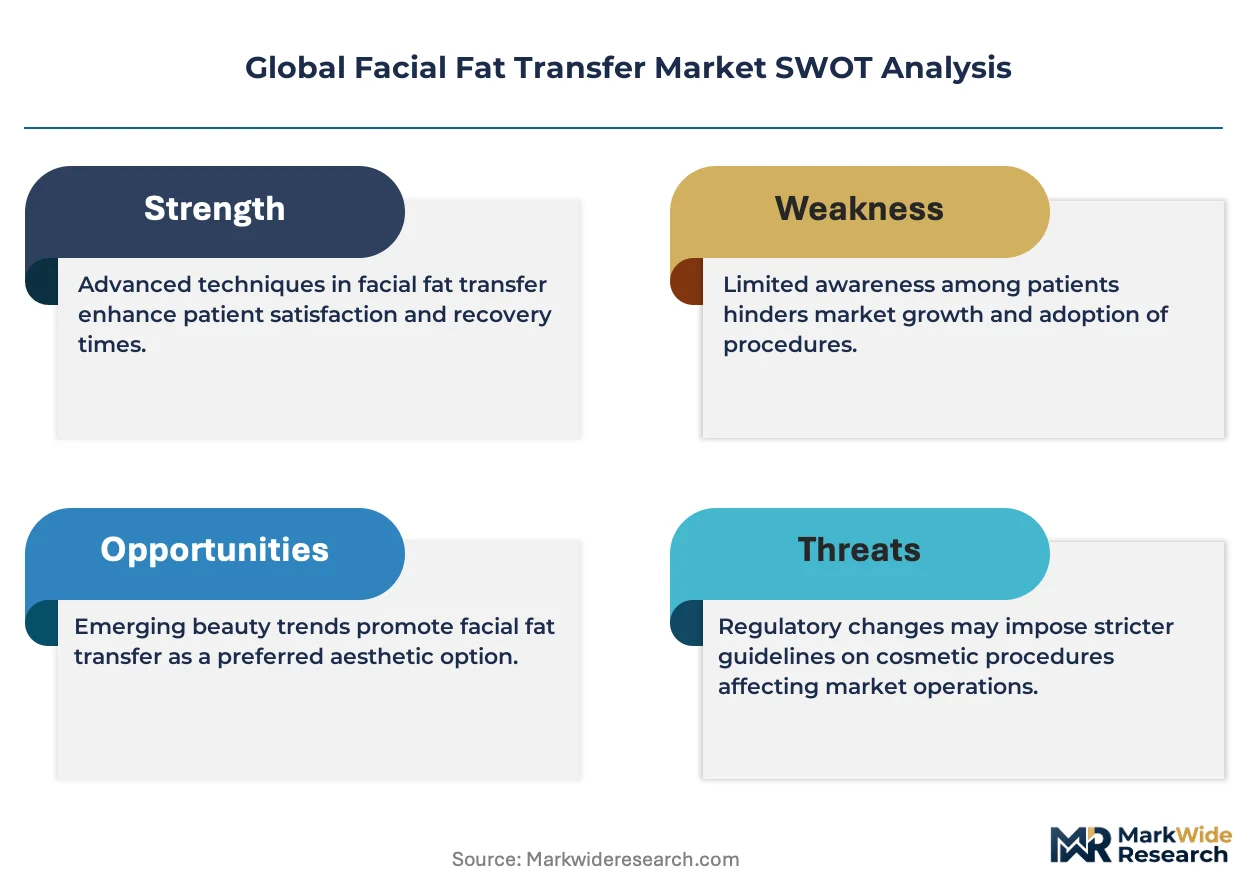
EU MDR compliance chokepoints determine both the spread between certified and non-certified equipment tiers and the consolidation trajectory of supplier relationships toward full-portfolio vendors capable of end-to-end documentation. This regulatory risk vector compresses margins for uncertified manufacturers while elevating pricing power for ISO 13485-accredited suppliers who can navigate notified body oversight timelines.
Pricing Analysis
After-sales consumable revenue from fat harvesting cannulas and filtration kits drives lifetime customer value beyond initial capital equipment sales. Three-tier pricing structure across premium closed-system platforms, standard centrifugation configurations, and economy manual syringe-based kits separates vendor tiers by certification depth and training bundling. Pricing pressure stems from medical spa channel expansion into lower-complexity microfat indications where third-party financing platforms heighten patient price sensitivity. High-volume plastic surgery clinics in Miami and Los Angeles exhibit the least price sensitivity due to bundled surgical package economics and operative room turnover efficiency premiums.
Supply Chain Analysis
Medical-grade stainless steel feedstock for cannula fabrication and biocompatible polymer resins for filtration membranes anchor upstream material flows. Manufacturing concentrates in Germany for precision centrifugation systems, the United States for laser-assisted lipolysis platforms, and South Korea for automated harvest technologies. Single-source vulnerability runs through specialized filtration mesh suppliers serving EU MDR-certified equipment tiers. Distribution runs through institutional procurement channels for cosmetic surgery hospitals and medical device distributors for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against synthetic hyaluronic acid fillers and collagen biostimulators that compete for facial volume restoration indications. Incumbents must articulate autologous tissue advantages while closing the outcomes predictability gap that constrains standardization.
For Market Incumbents: Pre-empt synthetic filler encroachment by investing in adipocyte viability protocol standardization and outcomes databases that demonstrate superior long-term retention rates. Consolidate supplier relationships toward captive supply of filtration consumables to defend margin pools against commoditization. Accelerate ISO 13485 certification investments to capture EU MDR-driven replacement cycles before competitors close compliance gaps.
For New Entrants and Emerging Players: Build out medical spa channel infrastructure for lower-complexity microfat transfer indications where regulatory burden remains reduced and capital equipment requirements are minimal. Target the nanofat grafting segment for superficial dermal rejuvenation applications where stromal vascular fraction concentration protocols create technology differentiation opportunities. Pursue laser-assisted lipolysis integration partnerships to bypass entrenched positions in traditional mechanical harvest equipment.
For Investors and Strategic Acquirers: EU MDR compliance deadlines reshape the acquisition landscape toward targets with notified body relationships and biocompatibility testing capabilities already in place. Long-term viability favors precision-device specialists with concentrated microcannula R&D expertise over diversified conglomerates facing cross-selling integration challenges. Monitor hospital procurement database trends for closed-system harvesting technology adoption rates as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification unlocks institutional procurement channels in Bavarian reconstructive surgery centers. |
| Hospital System Partnership | Miami and Los Angeles cosmetic surgery hospitals prioritize operative room turnover efficiency in vendor selection. |
| Reimbursement Strategy | Post-oncologic reconstructive coding optimization distinguishes medically necessary from elective cosmetic procedures. |
| Software Companion Development | Adipocyte viability tracking applications improve outcomes predictability and practitioner training standardization. |
| FDA Submission | 510(k) premarket notification for Class II fat transfer systems enables US plastic surgery clinic market entry. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare coding records. Bottom-up procedure volume estimates triangulated against top-down equipment installed base analysis.
Forecast inputs span procedure type segmentation across autologous, microfat, and nanofat techniques; end-user concentration between plastic surgery clinics and medical spas; and delivery technology tiering from manual injection to laser-assisted systems. CAGRs derive from modeling equipment replacement cycles, consumable attach rates, and channel expansion trajectories across the projection horizon. Industry-specific inputs include EU MDR compliance timelines and third-party patient financing platform penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by energy-based device manufacturers or accelerated synthetic filler innovation would shift outcomes. Cross-checking against hospital capital expenditure surveys and medical spa franchise development disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market