
 Endoscopy Equipment Market | 2026-2036
Endoscopy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Equipment Market Intelligence
Software-as-a-service platforms for image analysis and data management is rebalancing the value proposition from hardware-centric sales to integrated procedural solutions. Olympus Corporation leverages its dominant position in flexible endoscopes to bundle software with its hardware systems. Karl Storz SE & Co. KG competes by offering specialized rigid endoscope systems for niche surgical applications like urology and ENT. Johnson & Johnson extends its reach through its broad hospital network and integrated surgical device portfolio.
Endoscopy equipment comprises medical devices designed for non-invasive or minimally invasive visualization of internal organs and cavities. These instruments typically incorporate a light source and an imaging system, often utilizing fiber optics or digital CCD/CMOS sensors to transmit images to a monitor. Flexible endoscopes continue to command the largest market share, essential for gastroenterology procedures. However, capsule endoscopes represent the fastest-growing product category, driven by patient comfort and diagnostic efficiency in small bowel examination.
Regulatory frameworks, including the FDA's 510(k) clearance process in the United States and the EU's stringent Medical Device Regulation (MDR), govern market access and product design. In China, the NMPA's registration requirements and GB standards dictate quality and safety protocols for all imported and domestic equipment. Future competitive advantage depends on navigating these diverse regulatory landscapes while investing in AI-driven diagnostic capabilities.
Market Dynamics
The central tension between reusable and single-use endoscopes, intensified by stricter reprocessing guidelines from bodies like the FDA, is fundamentally altering purchasing decisions and product development priorities across the endoscopy equipment market.
Growth Catalysts
- National Healthcare Expansion:China's national policies to expand hospital infrastructure and public health screenings are creating significant demand for a full range of endoscopic equipment, particularly in secondary and tertiary cities.
- Procedural Shift to ASCs:The migration of gastroenterology procedures from hospitals to ambulatory surgery centers (ASCs) in North America and Europe boosts demand for cost-effective, efficient, and compact endoscopy systems.
- Patient Comfort and Efficiency:Capsule endoscopes offer a less invasive alternative for small bowel examination, driving adoption among patients and gastroenterologists seeking improved diagnostic workflows and reduced procedure times.
Market Restraints
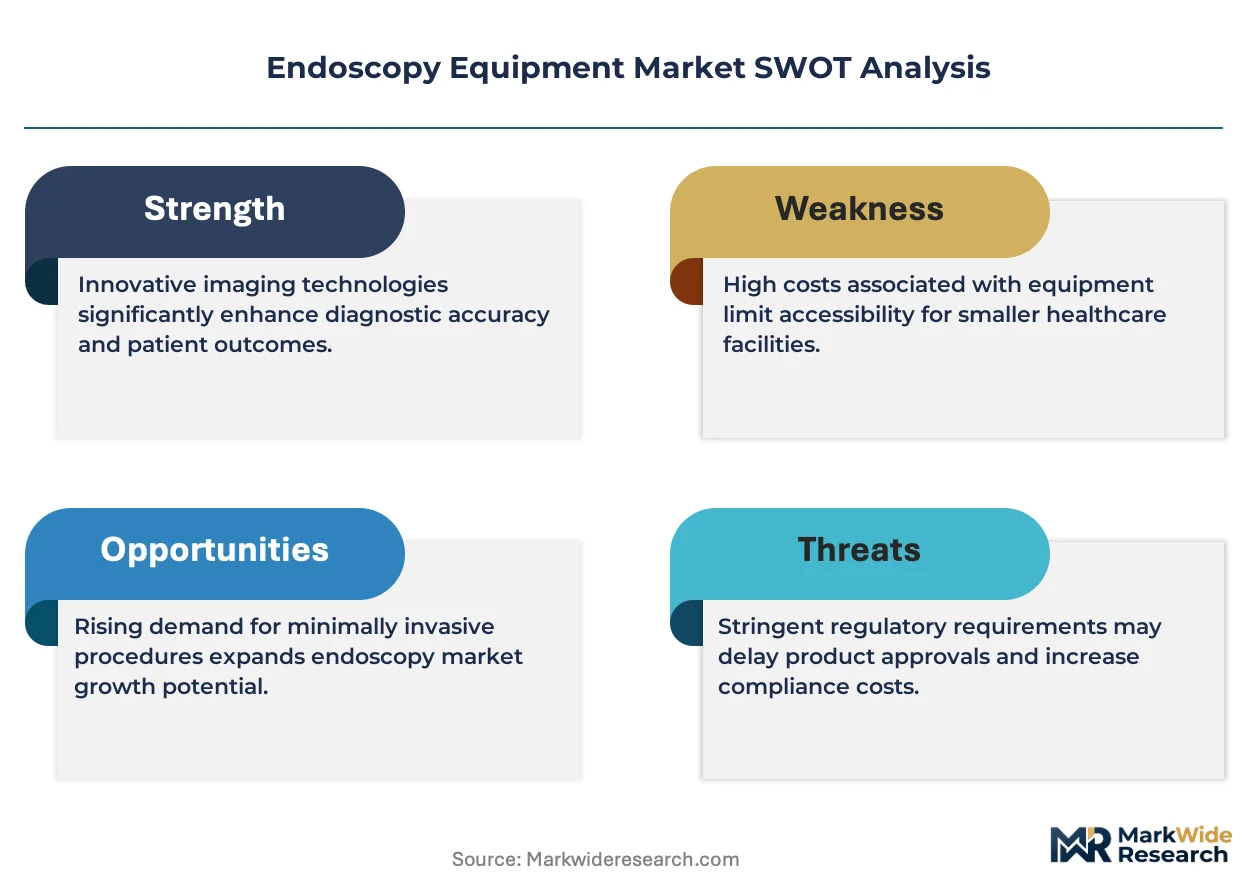
- High Capital Outlay:Advanced endoscopy towers with 4K monitors and processors require substantial investment, limiting adoption in smaller clinics and emerging economies.
- Component Supply Concentration:The supply of critical CMOS image sensors is concentrated among few manufacturers, creating potential bottlenecks and price volatility.
- Reprocessing Complexity:Intricate flexible endoscope designs complicate cleaning, posing infection risks and raising operational costs for healthcare facilities.
Strategic Opportunities
- AI-Powered Diagnostics:Integrating artificial intelligence for real-time image analysis can improve polyp detection rates and reduce diagnostic variability.
- Niche Surgical Applications:Developing specialized endoscopes for emerging surgical fields like fetoscopy and neuroendoscopy presents a growth opportunity.
- Single-Use Device Expansion:Stricter reprocessing regulations from the FDA and EU's MDR accelerate adoption of single-use devices in urology and bronchoscopy.
Industry Challenges
- Skilled Personnel Shortage:A global shortage of trained endoscopists and technicians limits procedural capacity expansion in many regions.
- Navigating Global Regulations:Securing and maintaining approvals across disparate frameworks like the FDA's 510(k), EU's MDR, and China's NMPA is complex and resource-intensive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Equipment Market |
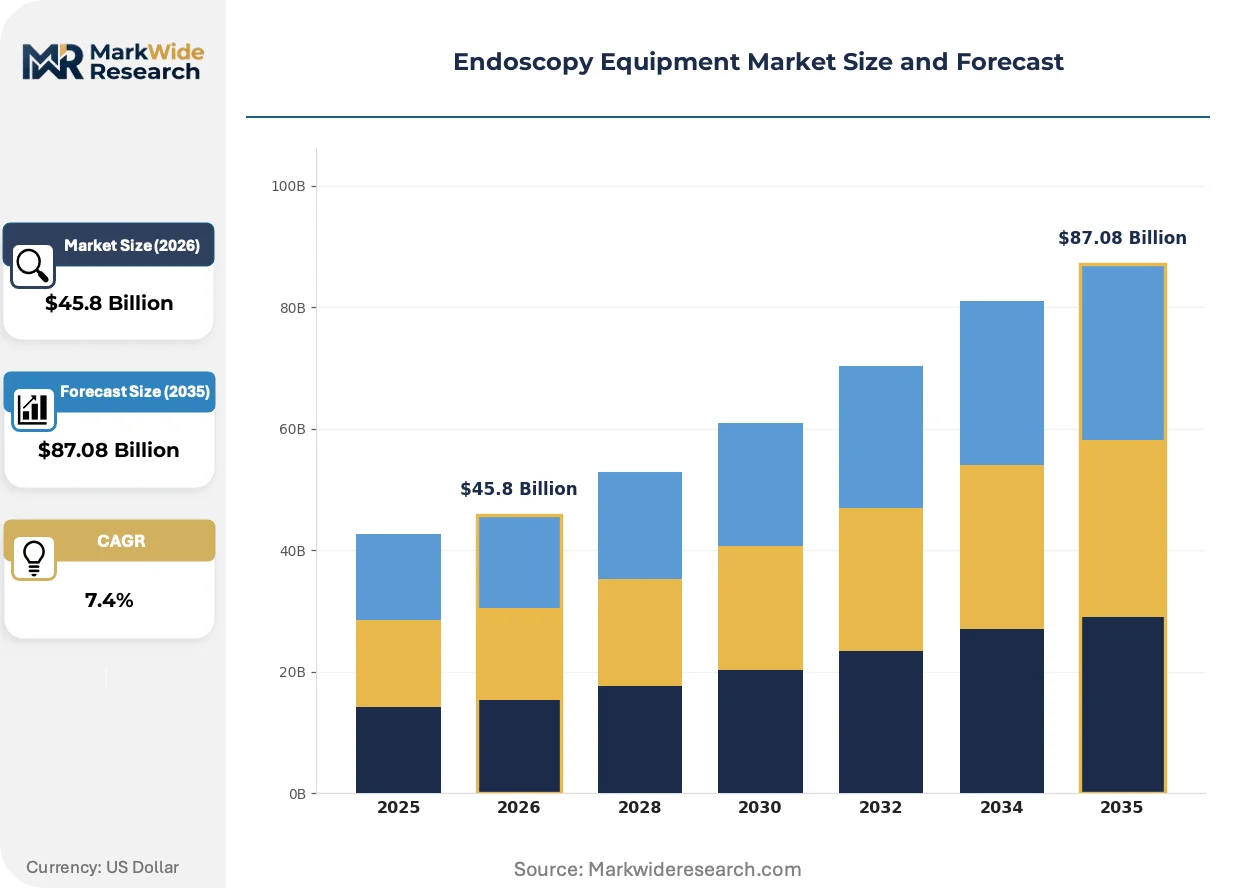
| Market Size in 2026 | $45.8 Billion |
| Market Size in 2035 | $87.08 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Video Endoscopes Technology: Optical, Digital Imaging, High-Definition, Narrow Band Imaging, 3D Visualization Application: Gastroenterology, Pulmonology, Urology, ENT Procedures, Gynecology End User: Hospitals, Outpatient Surgery Centers, Specialized Clinics, Diagnostic Laboratories |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Boston Scientific Corporation, Stryker Corporation, Medtronic, FUJIFILM Corporation, HOYA Corporation, Johnson & Johnson, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Equipment Market Strategic Shifts & Innovations
A convergence of data analytics with advanced imaging hardware is transforming the market. Value is shifting from the physical device to the procedural insights and efficiencies generated by integrated software-driven systems.
Artificial intelligence algorithms provide real-time computer-aided detection (CADe) for identifying suspicious lesions during colonoscopies. Gastroenterology departments are primary adopters, seeking to standardize diagnostic quality and improve outcomes. This software capability is integrating with next-generation processors, transforming the endoscope from a visualization tool into an active diagnostic partner.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance. This elevates compliance costs and extends market access timelines for all device classes. Reusable flexible endoscopes and their reprocessing equipment are most affected, forcing redesigns to meet enhanced safety criteria.
Value-based procurement models, including pay-per-use contracts, are gaining favor over traditional capital sales. This shift disrupts the one-time purchasing cycle common in large hospitals. The trend is most visible in private ambulatory surgery centers in the United States and Europe, which prioritize operational expenditure predictability.
Endoscopy Equipment Market Segmentation
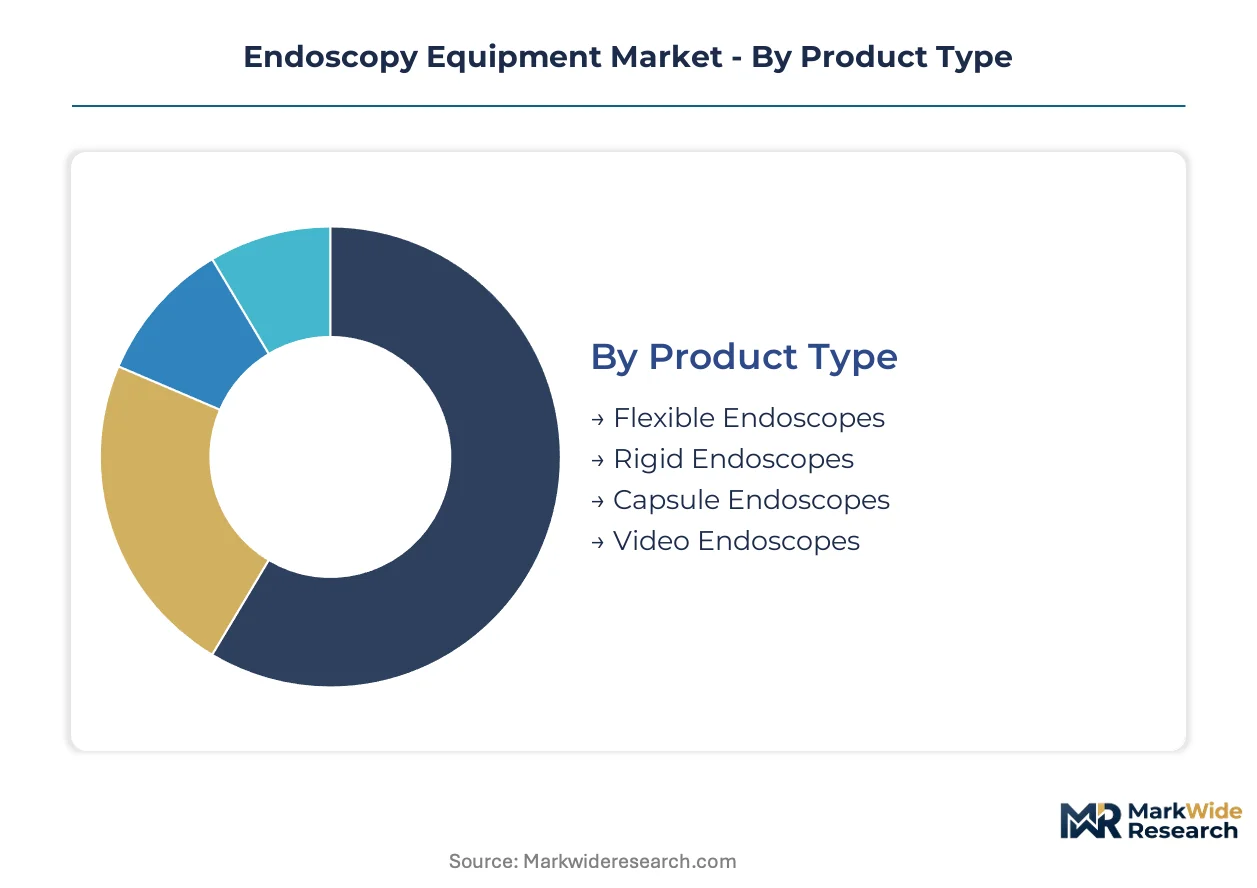
The endoscopy equipment market stratifies across distinct product types, technologies, applications, and end-user categories. Understanding these segments reveals specific demand drivers and competitive landscapes. This granular breakdown aids in identifying high-growth areas and strategic entry points for market participants.
Product Type:
The product type segment illustrates the customization-versus-standardization spectrum across endoscopic devices, reflecting diverse procedural requirements and patient comfort considerations.
- Flexible Endoscopes:These instruments feature a steerable tip and a flexible insertion tube, allowing navigation through tortuous anatomical pathways. Demand concentrates in gastroenterology procedures, driven by their essential role in colonoscopies and gastroscopies.
- Rigid Endoscopes:Comprising a fixed-angle lens and a straight, unbending shaft, these devices offer superior optical clarity and precise manipulation. Specialized rigid endoscope systems find significant demand in urology and ENT applications, where direct line-of-sight access is feasible.
- Capsule Endoscopes:These ingestible, pill-sized devices contain a miniature camera that captures images as it passes through the digestive tract. Patient comfort and non-invasiveness drive their adoption for small bowel examinations, particularly in diagnostic settings.
- Video Endoscopes:Integrating digital sensors directly into the tip, these devices transmit high-resolution images to an external monitor. Their adoption is significant in advanced diagnostic and therapeutic procedures, offering enhanced visualization capabilities.
Leading the category by volume: Flexible Endoscopes. Growing fastest: Capsule Endoscopes.
Technology:
The technology segment highlights the evolving capabilities embedded within endoscopy systems, influencing diagnostic accuracy and procedural efficiency.
- Optical:These traditional systems rely on fiber optics to transmit light and images through the endoscope's length. Optical technology provides foundational visualization for many routine endoscopic examinations.
- Digital Imaging:Incorporating CCD or CMOS sensors at the endoscope tip, digital imaging systems convert optical signals into electronic data for display. Demand for digital imaging concentrates in hospitals and outpatient centers, driven by needs for image archiving and enhanced clarity.
- High-Definition:Offering superior resolution and color fidelity, high-definition technology provides detailed visualization of mucosal surfaces and subtle tissue changes. Endoscopists in specialized clinics prioritize high-definition systems for improved diagnostic precision.
- Narrow Band Imaging:This advanced technique uses specific wavelengths of light to enhance the visualization of vascular patterns and mucosal structures. It finds application in early cancer detection during gastroenterology procedures.
- 3D Visualization:Providing depth perception, 3D visualization technology aids surgeons in complex minimally invasive procedures. Neuroendoscopy and certain gynecological surgeries benefit from this enhanced spatial awareness.
The most widely adopted technology is Digital Imaging. High-Definition technology exhibits the steepest expansion trajectory.
Application:
The application segment delineates the primary medical fields where endoscopy equipment is routinely deployed, reflecting varying procedural volumes and specific clinical needs.
- Gastroenterology:This segment includes procedures like colonoscopy, gastroscopy, and ERCP for diagnosing and treating digestive system conditions. Gastroenterology procedures represent the largest share of endoscopic applications, driven by high incidence rates of digestive disorders.
- Pulmonology:Involving bronchoscopy and thoracoscopy, this application focuses on the diagnosis and treatment of lung and airway diseases. Pulmonology departments in hospitals frequently utilize specialized endoscopes for biopsies and foreign body removal.
- Urology:Procedures such as cystoscopy and ureteroscopy are performed to examine and treat conditions of the urinary tract. Urological applications demand rigid and flexible endoscopes designed for navigating the urinary system.
- ENT Procedures:Endoscopes are used for examining the ear, nose, and throat, including rhinolaryngoscopy and otoscopy. ENT specialists rely on compact and precise endoscopes for diagnostic and minor surgical interventions.
- Gynecology:Hysteroscopy and laparoscopy are endoscopic procedures used for diagnosing and treating female reproductive system conditions. Gynecological applications require specialized endoscopes for minimally invasive surgical access.
Gastroenterology procedures command the largest volume within the market. Pulmonology applications are gaining share fastest.
End User:
The end user segment categorizes the types of healthcare facilities procuring and utilizing endoscopy equipment, reflecting diverse operational models and patient care settings.
- Hospitals:These large, multi-specialty institutions provide a comprehensive range of endoscopic services, including complex diagnostic and therapeutic procedures. Hospitals represent the primary end-user segment due to their extensive patient base and critical care capabilities.
- Outpatient Surgery Centers:Specialized facilities focusing on same-day surgical procedures, often for gastroenterology and urology. Outpatient surgery centers are experiencing significant demand, driven by a shift towards cost-effective, minimally invasive interventions.
- Specialized Clinics:These include private practices and diagnostic centers focusing on specific medical disciplines like ENT or urology. Specialized clinics procure equipment tailored to their niche procedural requirements.
- Diagnostic Laboratories:Facilities primarily focused on diagnostic testing, which may include processing samples obtained via endoscopic procedures or performing capsule endoscopy readings. Diagnostic laboratories require specific imaging and data management solutions.
Hospitals maintain the largest purchasing power in the market. Outpatient Surgery Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Endoscopy Equipment Market exhibits a distinct divide between concentrated production hubs and diverse consumption patterns. Demand for advanced systems is driven by healthcare infrastructure expansion in emerging economies, while established markets prioritize minimally invasive procedures. This global dynamic shapes regional investment and regulatory adherence.
United States
Demand for cost-effective systems in ambulatory surgery centers drives equipment procurement. The FDA's stringent reprocessing guidelines accelerate single-use device adoption. Medical device clusters in California and Massachusetts foster innovation in AI-driven diagnostics.
China
National healthcare expansion policies stimulate significant demand across all equipment types. The NMPA's registration requirements and GB standards dictate quality for both domestic and imported devices. Beijing and Shanghai serve as major hubs for medical device manufacturing and distribution.
Germany
High-definition and 3D visualization technologies see strong demand in specialized clinics. The EU's MDR imposes strict clinical evidence requirements for market access. The MedTech cluster in Tuttlingen remains a global center for surgical instrument production.
Japan
Patient comfort and diagnostic efficiency drive adoption of capsule endoscopes. PMDA regulations ensure device safety and efficacy within the domestic market. Tokyo and Osaka host significant R&D centers for advanced imaging systems.
India
Expanding hospital infrastructure and public health screenings create demand for basic and advanced endoscopy equipment. The CDSCO governs medical device approvals and quality standards. Bangalore and Hyderabad are emerging as centers for medical technology development.
Endoscopy Equipment Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers target niche applications. The market structure exhibits a tiered consolidation, with a few dominant players alongside numerous smaller innovators. Strategic archetypes include integrated solution providers, specialized instrument manufacturers, and broad portfolio suppliers. Companies primarily engage in strategic partnerships and portfolio diversification to maintain market relevance.
Integrated solution providers, exemplified by Olympus Corporation, often bundle advanced software with their hardware systems. Karl Storz SE & Co. KG represents a specialized instrument manufacturer, focusing on rigid endoscope systems for specific surgical fields like urology and ENT. Johnson & Johnson occupies a position as a broad portfolio supplier, leveraging its extensive hospital network for market penetration.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Boston Scientific Corporation |
| Stryker Corporation |
| Medtronic |
| FUJIFILM Corporation |
| HOYA Corporation |
| Johnson & Johnson |
| Ambu A/S |
| Others |
Cost & Logistics Intelligence
The accelerating shift towards single-use devices and advanced digital imaging is simultaneously reshaping cost economics and concentrating the supply chain for critical components in the endoscopy equipment market.
Pricing Analysis
Cost-down pressure across standard-tier endoscopy systems accelerates as procurement shifts to outpatient surgery centers prioritizing operational expenditure predictability. The dominant pricing model remains per-unit transactional, though value-based procurement models are emerging. Price differentiation stems from certification level and after-sales service bundles. Hospitals exhibit lower price sensitivity for advanced systems, unlike smaller clinics and ambulatory surgery centers.
Supply Chain Analysis
Regulatory qualification for medical device components acts as a significant gating factor, concentrating supply for critical CMOS image sensors. Geographic supply of these sensors concentrates in Japan, South Korea, and Taiwan. Key dependencies include specialized optical fibers and micro-electronics. Single-source vulnerability for advanced sensors presents a structural risk. Distribution runs through established medical device distributors and direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Endoscopy Equipment Market is increasingly a consolidation play, driven by stricter regulatory compliance costs that disproportionately burden smaller manufacturers.
For Market Incumbents:Anticipate continued pressure from single-use device adoption, requiring strategic investment in next-generation materials and manufacturing processes. Consolidate market share through targeted acquisitions of specialized software firms, leveraging existing hospital networks. Develop integrated AI-driven diagnostic platforms to counter emerging niche technology threats. Control of intellectual property for advanced imaging sensors serves as a critical lever.
For New Entrants and Emerging Players:Group purchasing organizations represent a key channel partner for new entrants seeking market access in North America and Europe. Target underpenetrated segments like remote diagnostic services or specialized pediatric endoscopy applications with cost-effective, modular systems. A go-to-market angle involves offering subscription-based models for software-as-a-service platforms, appealing to budget-conscious clinics.
For Investors and Strategic Acquirers:Exit pathways concentrate in strategic acquisitions by large medical device conglomerates seeking portfolio diversification or technology integration. The market offers long-term viability, supported by an aging global population and rising diagnostic screening volumes. A signal to watch involves the rate of AI algorithm approval by major regulatory bodies, indicating readiness for widespread adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-integrated diagnostic software | Enhances diagnostic accuracy and standardizes procedural outcomes across diverse clinical settings. |
| Expand single-use device manufacturing capacity | Addresses evolving regulatory demands and reduces infection risks in high-volume procedures. |
| Form hospital system partnerships | Secures long-term procurement contracts and facilitates broader technology adoption in critical care. |
| Invest in micro-optics and sensor R&D | Drives miniaturization and improves visualization capabilities for complex anatomical access. |
| Acquire specialized niche application firms | Broadens product portfolio into high-growth surgical fields like neuroendoscopy and fetoscopy. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, providing foundational market sizing and trend identification. Primary research involved in-depth interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. This comprehensive approach ensured a robust triangulation of market insights, combining bottom-up and top-down validation.
Data-stream reconciliation across various inputs formed the basis of the analytical framework, projecting market evolution over the forecast period. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs included global healthcare spending growth and minimally invasive procedure adoption rates.
Caveats apply where new reprocessing guidelines, AI diagnostic accuracy advancements, or significant supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Video Laryngoscope Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Colonic Stents Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Endorectal Balloon Market