
 Global Bronchoscopes Market | 2026-2036
Global Bronchoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bronchoscopes Market Analysis
The hospital procurement channel is narrowing as group purchasing organizations consolidate contract awards for flexible bronchoscope systems. Olympus Corporation leverages its endoscopy service infrastructure to sustain replacement demand across tertiary centers. Ambu A/S competes through single-use platforms that eliminate reprocessing liability for infection control officers. FUJIFILM Holdings Corporation anchors its position in video bronchoscopes through imaging sensor integration.
Bronchoscopes are elongated tubular instruments with fiberoptic or digital imaging channels, typically 2.8–6.0 mm in outer diameter, designed for direct visualization and instrument passage through the tracheobronchial tree during diagnostic and therapeutic procedures. Flexible bronchoscopes dominate installed base volumes in hospitals, while robotic-assisted technology commands premium positioning amid procedural precision requirements. Video bronchoscopes are displacing fiberoptic legacy systems as CMOS sensor costs decline and high-definition output becomes standard for biopsy navigation.
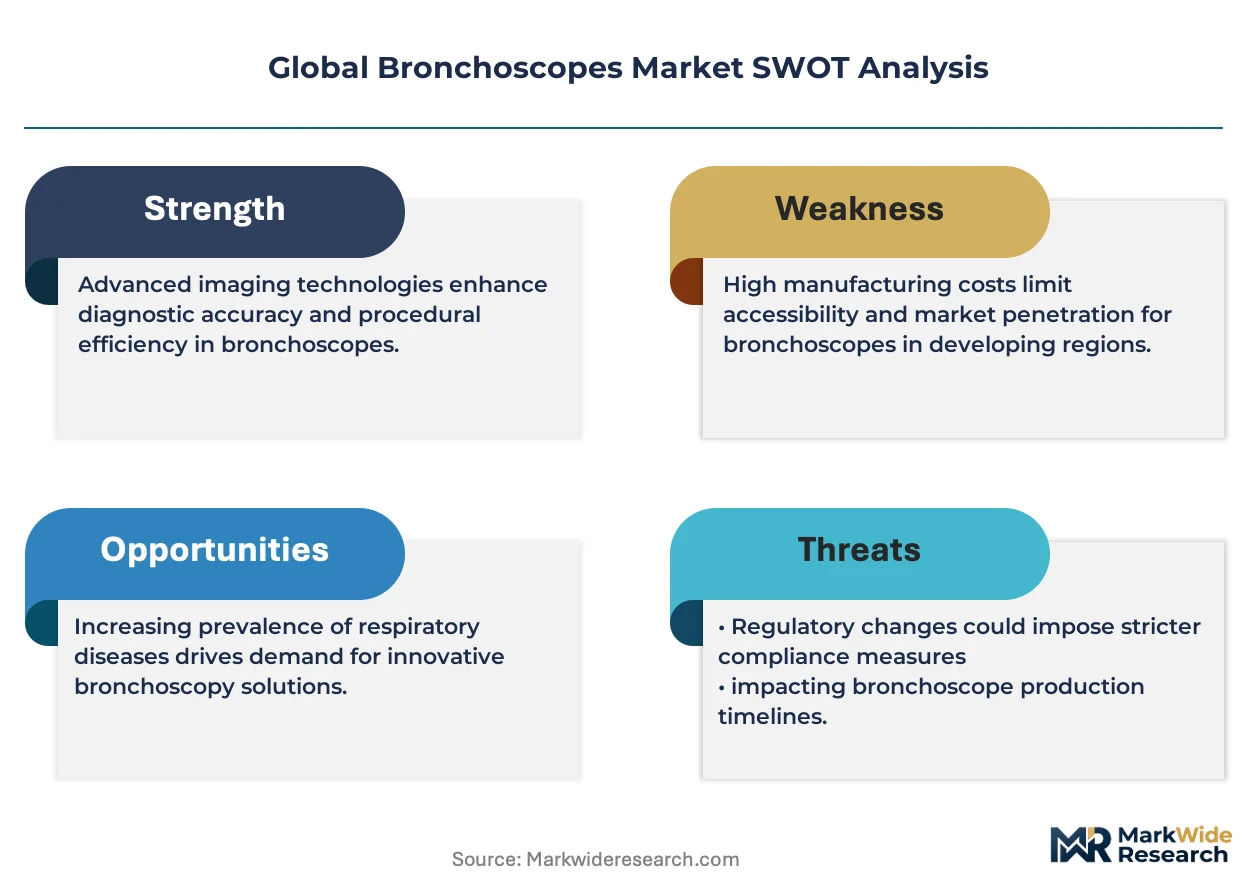
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity assessments shape product launch timelines and clinical evidence requirements for manufacturers seeking market access. ISO 13485 quality management systems and IEC 60601 electrical safety standards govern manufacturing consistency across production facilities in Japan, Germany, and the United States. Stakeholders must monitor reimbursement coding revisions for robotic-assisted bronchoscopy and single-use disposable categories as payers recalibrate coverage policies.
Market Dynamics
Single-use bronchoscope platforms are compressing replacement cycles for reusable fiberoptic systems as FDA sterility mandates and hospital infection control protocols harden procurement specifications across tertiary centers.
Growth Catalysts
- Lung Cancer Screening Expansion:National screening protocols in the United States, China, and Germany are widening eligible patient populations and driving diagnostic procedure volumes through pulmonology departments.
- EMA MDR Conformity Assessments:Stricter European device regulations are accelerating hospital transitions from legacy reusable systems to validated single-use alternatives that eliminate reprocessing documentation burdens.
- CMOS Sensor Cost Decline:High-definition video bronchoscopes are capturing installed base share as digital imaging component costs fall and biopsy navigation precision requirements intensify.
Market Restraints
- Supply Concentration in Japanese Optics:Precision lens and fiberoptic component manufacturing clusters heavily in Japanese industrial zones, creating vulnerability to regional logistics disruptions.
- Reprocessing Liability Costs:Reusable system operators face escalating insurance and compliance expenditures tied to FDA infection control warning letters and hospital-acquired pneumonia litigation.
- Robotic System Price Floors:Capital equipment thresholds for robotic-assisted platforms exceed standard flexible bronchoscope budgets, limiting penetration outside academic medical centers.
Strategic Opportunities
- Interventional Pulmonology Program Expansion:Tertiary hospitals in Germany and Japan are building dedicated suites that bundle bronchoscopy with electromagnetic navigation and cryobiopsy capabilities.
- Disposable Category Reimbursement Recalibration:Payers in the United States are revising procedural coding to recognize single-use device value, potentially unlocking coverage parity with reusable alternatives.
- AI-Integrated Navigation Convergence:Real-time image analysis algorithms are merging with video bronchoscope platforms to reduce operator-dependent sampling error in peripheral lesion targeting.
Industry Challenges
- Interventional Pulmonologist Training Pipeline:Fellowship program slots lag behind procedural demand growth, constraining throughput for advanced diagnostic and therapeutic bronchoscopy services.
- ISO 13485 Certification Timelines:Quality management system audits for single-use manufacturing facilities are extending product launch windows amid notified body capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bronchoscopes Market |
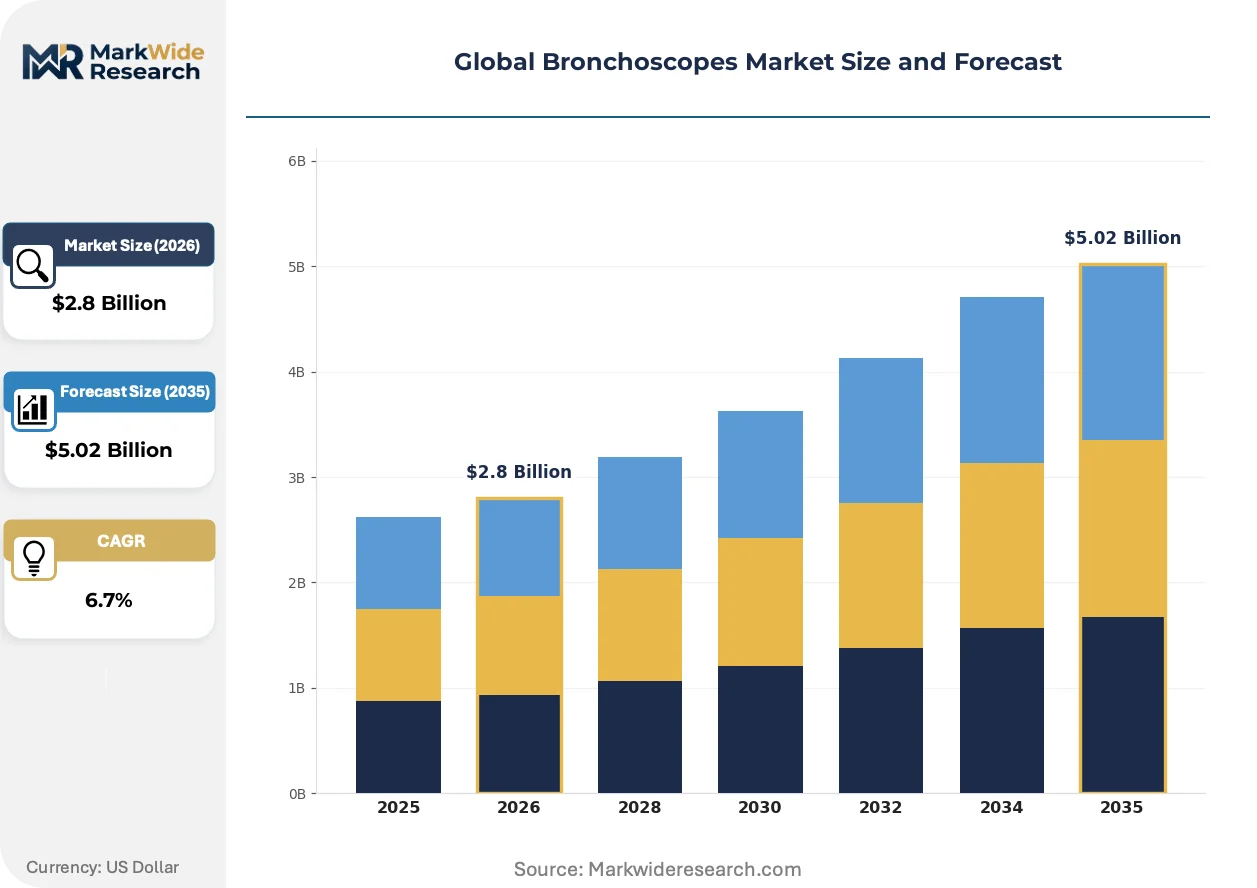
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bronchoscopes, Rigid Bronchoscopes, Ultra-thin Bronchoscopes, Video Bronchoscopes Application: Diagnostics, Therapeutic Procedures, Surgical Procedures, Biopsy End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Endobronchial Ultrasound, Optical Coherence Tomography, Fluorescence Imaging, Robotic-assisted |
| Companies Covered | Olympus Corporation, Ambu A/S, FUJIFILM Holdings Corporation, KARL STORZ SE & Co. KG, Boston Scientific Corporation, Teleflex Incorporated, Richard Wolf GmbH, Pentax Medical, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bronchoscopes Market Emerging Trajectories
Digital imaging sensor integration and disposable platform economics are restructuring capital expenditure patterns across hospital procurement channels while regulatory sterility mandates accelerate technology turnover.
CMOS-based video bronchoscopes are rendering obsolete fiberoptic legacy systems in high-volume diagnostic centers. Academic medical centers in the United States and Germany are standardizing on high-definition platforms for biopsy navigation. The transition is compressing secondary market values for refurbished fiberoptic equipment and redirecting service contract revenue toward disposable supply agreements.
FDA 510(k) clearance pathways for single-use devices are tightening clinical evidence requirements compared to predicate device equivalency standards. Manufacturers must now submit sterility validation data and human factors testing for disposable platforms. European manufacturers are responding by front-loading regulatory affairs resources and establishing dedicated MDR submission teams.
Group purchasing organizations are consolidating flexible bronchoscope contract awards into multi-year sole-source agreements that bundle devices, accessories, and training. Hospital systems are replacing fragmented departmental purchasing with centralized supply chain oversight. This concentration is most visible in the United States, where Catholic health networks and for-profit chains are extracting volume discounts from device manufacturers.
Global Bronchoscopes Market Segmentation
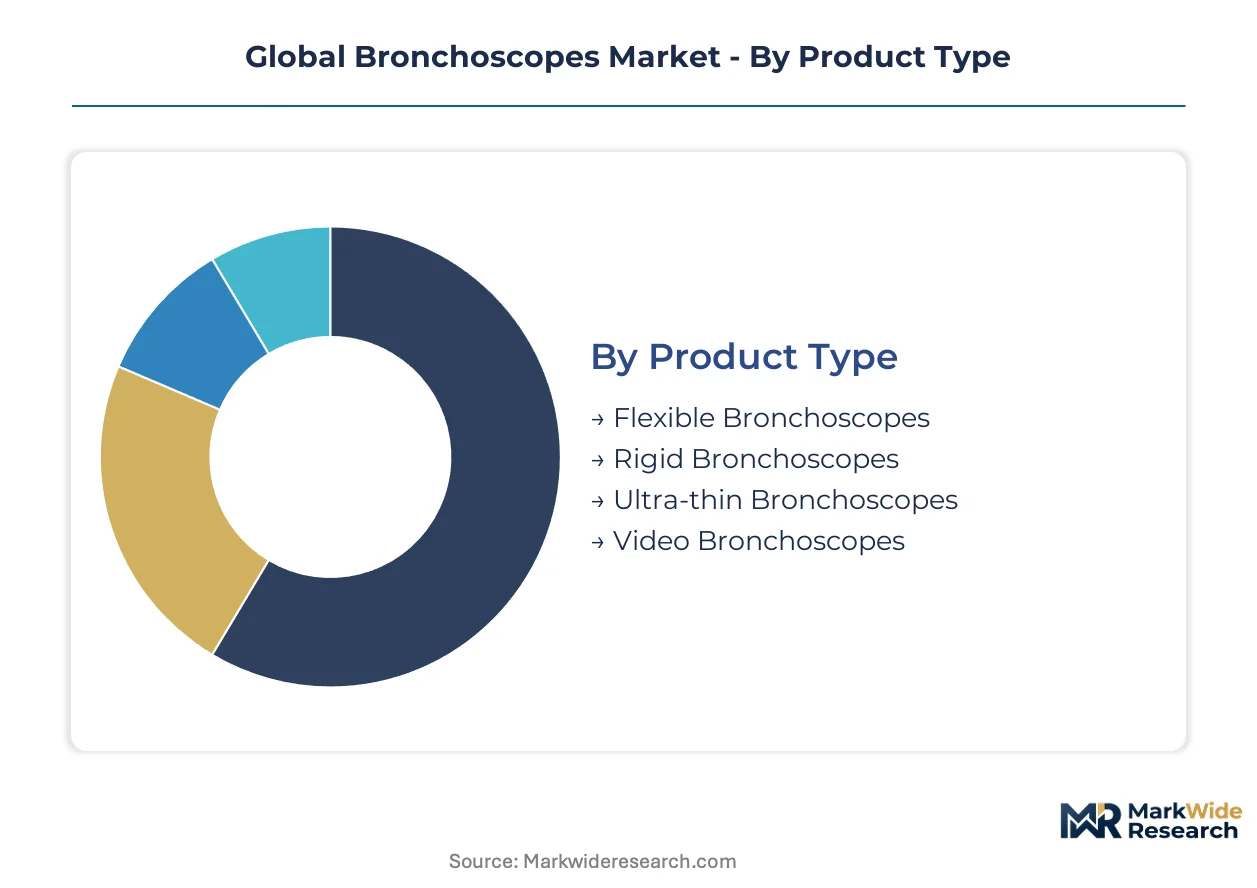
Bronchoscope procurement decisions cascade across multiple technical and operational dimensions. Product specifications, procedural applications, and technology integration each create distinct commercial segments with divergent margin profiles and replacement cycles.
Product Type:
Flexible systems dominate airway navigation procedures while rigid platforms anchor surgical interventions; ultra-thin and video variants are capturing share through minimally invasive and high-definition capabilities.
- Flexible Bronchoscopes:Fiberoptic or digital systems with steerable distal tips navigate tortuous bronchial anatomy for diagnostic and therapeutic access. Demand concentrates in tertiary hospitals across the United States and Germany where interventional pulmonology programs are expanding procedural volumes.
- Video Bronchoscopes:CMOS sensor-based platforms deliver high-definition visualization for biopsy navigation and electromagnetic tracking integration. Chinese and Japanese hospitals are standardizing on these systems as component costs decline and image quality requirements intensify.
- Rigid Bronchoscopes:Metal tubular instruments enable large-bore instrument passage and airway control during therapeutic interventions.
- Ultra-thin Bronchoscopes:Sub-3.0 mm outer diameter systems access peripheral pulmonary lesions beyond standard flexible reach.
The dominant share belongs to Flexible Bronchoscopes, while Video Bronchoscopes is closing the gap fastest.
Application:
Diagnostic procedures generate baseline procedure volumes while therapeutic and surgical applications command premium device specifications and reimbursement rates.
- Diagnostics:Visual inspection, lavage collection, and cytological sampling for lung cancer screening and infection workup. United States hospitals are driving volume through expanded lung cancer screening protocols and incidental nodule management pathways.
- Biopsy:Tissue acquisition for histopathological diagnosis via forceps, needles, or brush cytology. German academic centers are integrating electromagnetic navigation with biopsy platforms to improve peripheral lesion yield rates.
- Therapeutic Procedures:Foreign body removal, stent placement, and tumor debulking interventions.
- Surgical Procedures:Video-assisted thoracic surgery coordination and preoperative mapping.
Diagnostics captures the largest procedure volume, though Biopsy is expanding most quickly through navigation technology adoption.
End User:
Capital intensity and regulatory compliance requirements stratify procurement authority across institutional settings.
- Hospitals:Tertiary and community facilities with dedicated pulmonology departments and infection control infrastructure. Japanese hospital systems are consolidating flexible bronchoscope contracts through group purchasing organizations to extract volume discounts.
- Diagnostic Centers:Outpatient facilities specializing in cancer screening and pulmonary function testing. Chinese diagnostic chains are deploying single-use platforms to avoid reprocessing capital investment and regulatory documentation burdens.
- Clinics:Smaller pulmonary practices with limited procedure volumes.
- Research Institutions:Academic centers developing novel interventional techniques and device validation studies.
Hospitals maintain the dominant procurement share, while Diagnostic Centers is gaining share fastest through screening program decentralization.
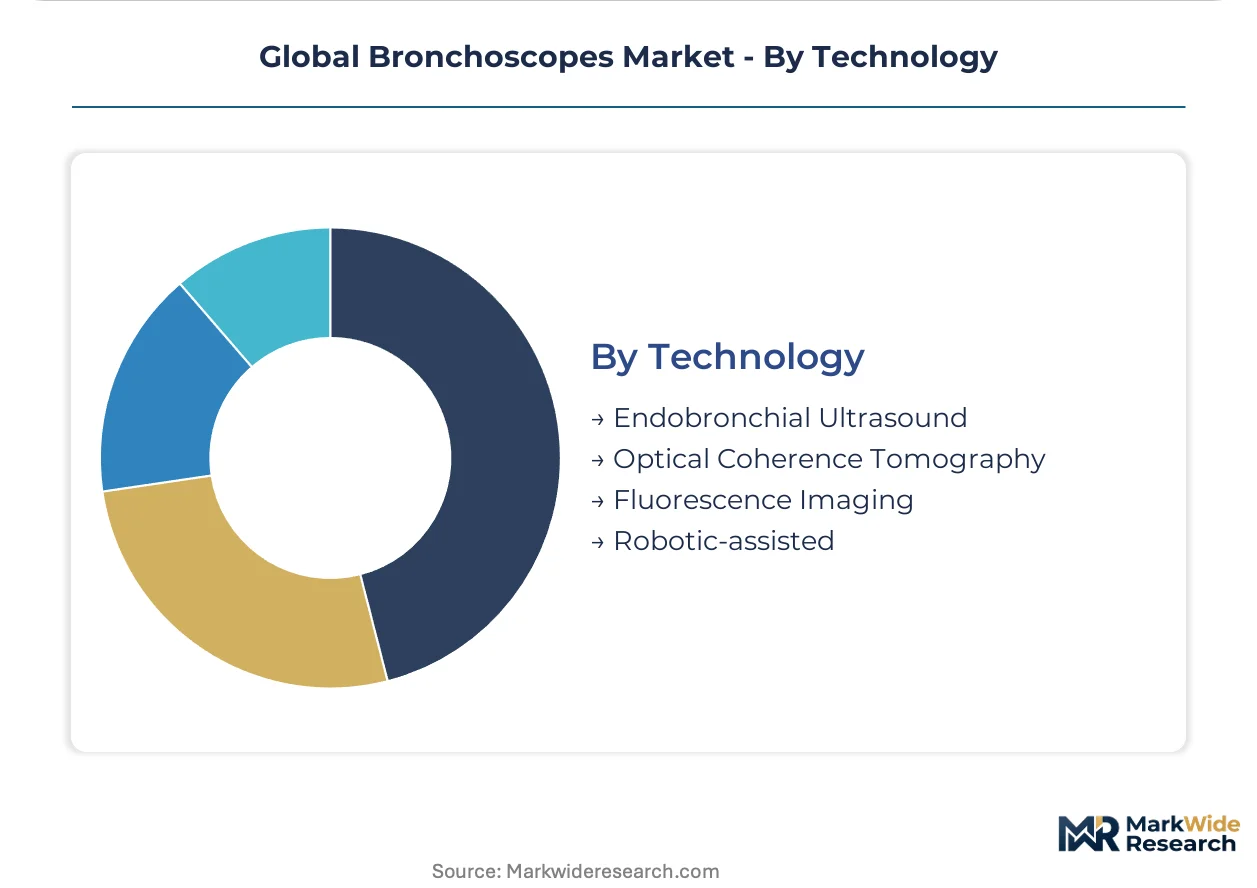
Technology:
Imaging modality and mechanical assistance layers determine procedural precision and operator training requirements.
- Endobronchial Ultrasound:Radial and linear probe integration enables real-time mediastinal lymph node assessment and transbronchial needle aspiration. United States academic medical centers are standardizing EBUS-TBNA platforms for lung cancer staging protocols.
- Robotic-assisted:Electromagnetic navigation and articulated catheter systems for peripheral lesion access. German hospitals are piloting these platforms to reduce operator-dependent sampling variability in small nodule targeting.
- Fluorescence Imaging:Autofluorescence and narrow-band imaging enhance dysplasia detection during bronchial surveillance.
- Optical Coherence Tomography:Microstructural tissue imaging for in vivo histology approximation.
Endobronchial Ultrasound holds the dominant technology share, while Robotic-assisted is climbing the fastest through precision targeting requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for precision optical components, while the Trans-Siberian Railway corridor links East Asian manufacturing clusters to Central Asian diagnostic networks. These infrastructure assets underpin regional procurement patterns for bronchoscope systems.
United States
Expanded lung cancer screening protocols and incidental pulmonary nodule management drive diagnostic procedure volumes. FDA 510(k) clearance pathways tighten sterility validation requirements for single-use platforms. Cleveland Clinic and Mayo Clinic anchor interventional pulmonology training networks across the Midwest.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia build dedicated interventional suites with electromagnetic navigation capabilities. EMA MDR conformity assessments accelerate transitions from reusable to validated single-use alternatives. The Munich-Stuttgart medical technology corridor concentrates video bronchoscope manufacturing and service infrastructure.
Japan
Aging demographics and national lung cancer screening programs expand eligible patient populations. PMDA regulatory frameworks govern quality management system certifications for domestic manufacturers. The Tokyo-Osaka industrial belt hosts precision lens and CMOS sensor production clusters.
China
Diagnostic center chains decentralize screening services to reduce tertiary hospital congestion. NMPA medical device registration pathways shape product launch timelines for domestic and imported platforms. The Yangtze River Delta anchors flexible bronchoscope assembly operations and regional distribution hubs.
Global Bronchoscopes Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified medical technology conglomerates with endoscopy service infrastructure, single-use disposable specialists with infection control positioning, and regional optical manufacturers with component integration capabilities. Competitive moves center on group purchasing organization contract consolidation and M&A activity targeting electromagnetic navigation technology.
Within the diversified conglomerate tier, Olympus Corporation and FUJIFILM Holdings Corporation exemplify integrated imaging and service platform strategies. Ambu A/S occupies a distinct position among disposable specialists, while KARL STORZ SE & Co. KG represents German precision engineering heritage in rigid and flexible system architectures.
| Leading Market Players |
|---|
| Olympus Corporation |
| Ambu A/S |
| FUJIFILM Holdings Corporation |
| KARL STORZ SE & Co. KG |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Richard Wolf GmbH |
| Pentax Medical |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
The Trans-Siberian Railway corridor's freight cost volatility directly shapes procurement economics for CMOS sensor shipments from Japanese precision optics clusters to European assembly facilities, concentrating margin pressure on mid-tier manufacturers while enabling premium-tier suppliers to sustain price differentiation through captive logistics contracts.
Pricing Analysis
Volume-discount tiering separates academic medical center consortia from individual hospital purchasers, with three-tier pricing structure across premium, standard, and economy levels anchored by ISO 13485 certification grade and bundled service intensity. Price differentiation hinges on electromagnetic navigation integration and single-use sterility validation documentation. Pricing pressure stems from group purchasing organization consolidation extracting annual concessions from manufacturers. Diagnostic center chains exhibit highest price sensitivity, whereas tertiary hospitals with dedicated interventional suites prioritize performance specifications over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for flexible bronchoscope manufacturers sourcing CMOS sensors and precision lens assemblies. Component manufacturing concentrates in Japan, Germany, and China, with raw material dependencies spanning optical glass substrates, medical-grade polymers, and semiconductor imaging sensors. Single-source vulnerability persists for sub-2.8 mm distal tip articulation mechanisms. Distribution runs through hospital procurement departments and group purchasing organization contract vehicles, with regional service hubs anchoring aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use platform economics and regulatory sterility mandates are driving a cyclical recovery in replacement demand as hospitals accelerate transitions from legacy reusable systems.
For Market Incumbents: Entrench service infrastructure advantages by expanding electromagnetic navigation training networks across German and Japanese tertiary centers. Deepen backward integration into CMOS sensor sourcing to insulate margins from Japanese optics cluster pricing volatility. Counter Ambu's single-use positioning by bundling reprocessing liability insurance with reusable system contracts. For New Entrants and Emerging Players: Chinese diagnostic center chains represent the most penetrable entry point, bypassing consolidated hospital procurement channels through direct disposable platform sales. Target mid-tier European hospitals facing EMA MDR documentation burdens with validated single-use alternatives. Pursue software companion development partnerships with electromagnetic navigation vendors to differentiate on biopsy yield metrics. For Investors and Strategic Acquirers: Electromagnetic navigation technology specialists with FDA 510(k) clearance pathways command premium acquisition multiples given procedural precision requirements. Long-term viability rests on reimbursement coding parity between single-use and reusable categories. Monitor CMS procedural valuation updates as the critical inflection signal for disposable category economics.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Submission Team Expansion | EMA conformity assessment acceleration unlocks European hospital transition budgets. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic training networks anchor interventional pulmonology adoption. |
| Software Companion Development | AI-integrated navigation algorithms reduce operator-dependent sampling error in peripheral targeting. |
| Reimbursement Strategy | CMS coding revisions for single-use devices determine category economics parity. |
| CE Marking Pathway | European sterility validation requirements compress launch timelines for disposable platforms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Calibration against historical replacement cycles and regulatory milestone timing informed the analytical framework across the projection horizon. Segmentation dimensions spanned product type, application, end user, and technology integration intensity. CAGRs derived from installed base turnover rates and single-use platform penetration curves, with lung cancer screening protocol expansion and sterility mandate compliance timelines as key forecast inputs.
Practitioners should monitor FDA warning letter patterns and EMA notified body capacity constraints for early signals of supply-side disruption. Forecasts reflect assumptions about reimbursement coding stability and single-use manufacturing scale-up feasibility. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
United States Endoscopy Devices Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Esophageal Stents Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Bronchoscopy Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Global Endoscope Leak Detection Device Market