
 Colonic Stents Market | 2026-2036
Colonic Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Colonic Stents Market Analysis
Modular stent kits bundled with delivery systems and retrieval accessories is hardening as the default procurement format across hospital systems. Boston Scientific Corporation leverages its integrated gastrointestinal portfolio to anchor premium positioning in bundled contracts. Medtronic sustains manufacturing scale across nitinol self-expanding platforms. Cook Medical differentiates through specialized percutaneous delivery configurations.
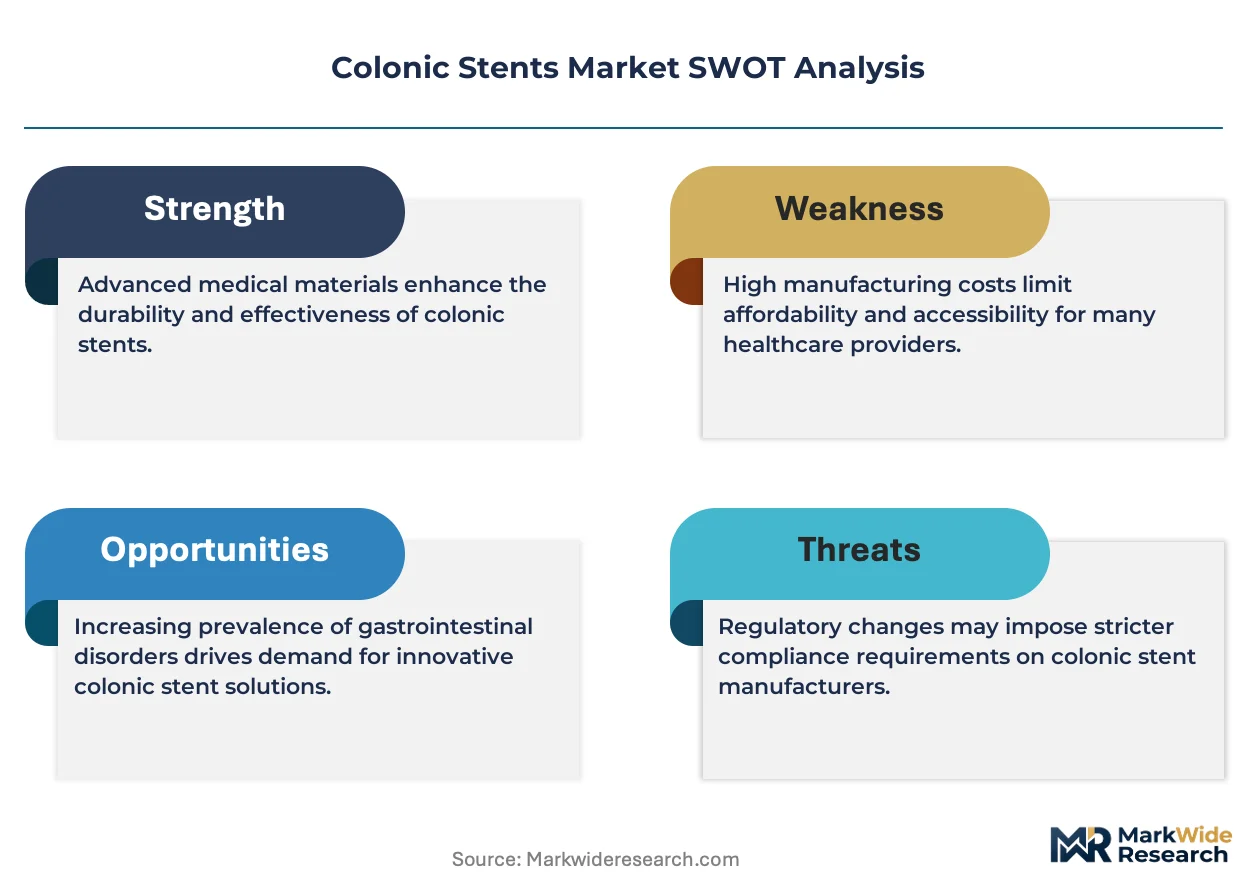
Colonic stents are tubular prosthetic devices, typically constructed from nitinol or stainless steel alloys with polymer coatings, designed to restore luminal patency in malignant or benign large-bowel obstructions through endoscopic or fluoroscopic deployment. Self-expandable metal stents dominate commercial volume due to superior conformability and tissue apposition in tortuous anatomy. Ambulatory surgical centers represent the fastest-growing end-user channel as same-day stenting protocols expand. Plastic stents retain niche utility in benign strictures where temporary palliation or preoperative decompression is indicated.
The FDA's 510(k) clearance framework and the EU MDR's clinical evidence requirements govern market access, while Japan's PMDA enforces stringent biocompatibility testing for nitinol implants. Stakeholders must monitor evolving reimbursement thresholds for outpatient stenting and the pace of MDR notified body capacity expansion across Europe.
Market Dynamics
The transition toward same-day stenting protocols in ambulatory settings is compressing hospital purchasing cycles and forcing manufacturers to reconfigure kit packaging for point-of-care inventory.
Growth Catalysts
- Aging demographics in Japan and Germany:Population cohorts over 65 are driving procedural volumes for malignant large-bowel obstruction management. Endoscopic infrastructure expansion in these markets supports case throughput.
- FDA 510(k) clearance pathway:The premarket notification framework accelerates nitinol self-expanding stent introductions compared with PMA requirements. Device sponsors leverage predicate device strategies to compress regulatory timelines.
- Polymer coating advances:Hydrophilic and drug-eluting surface technologies are reducing tissue ingrowth and extending stent patency durations. Coated platforms command preference in tortuous anatomies.
Market Restraints
- Nitinol price volatility:Nickel-titanium alloy feedstock costs fluctuate with mining output from Southeast Asian suppliers. Smaller manufacturers lack forward-contracting scale to buffer input spikes.
- EU MDR clinical evidence requirements:The Medical Device Regulation mandates expanded biocompatibility documentation for permanent implants. Notified body capacity constraints are extending certification timelines.
- Plastic stent substitution in benign strictures:Temporary palliation cases favor lower-cost polyethylene platforms. Metal stent penetration stalls in preoperative decompression segments.
Strategic Opportunities
- ASC channel expansion in the United States:Ambulatory surgical centers are adopting same-day stenting protocols faster than hospital outpatient departments. Manufacturers can unbundle retrieval accessories for leaner ASC inventory models.
- Japan PMDA biocompatibility harmonization:Streamlined testing pathways for nitinol implants reduce redundant validation costs. Early movers capture procedural share in metropolitan Tokyo and Osaka clusters.
- Fluoroscopy-integrated delivery systems:Convergence of endoscopic visualization with real-time imaging is enabling percutaneous placement in non-operating-room settings. Hybrid platforms open interventional radiology suites as deployment sites.
Industry Challenges
- Interventional gastroenterologist training pipelines:Complex malignant obstruction cases require advanced endoscopic submucosal dissection skills. Fellowship programs are not producing specialists at pace with procedural demand.
- EU MDR notified body reauthorization delays:Certificate expiration cascades are forcing manufacturers to suspend European shipments. Supply continuity planning must account for 12-18 month recertification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colonic Stents Market |
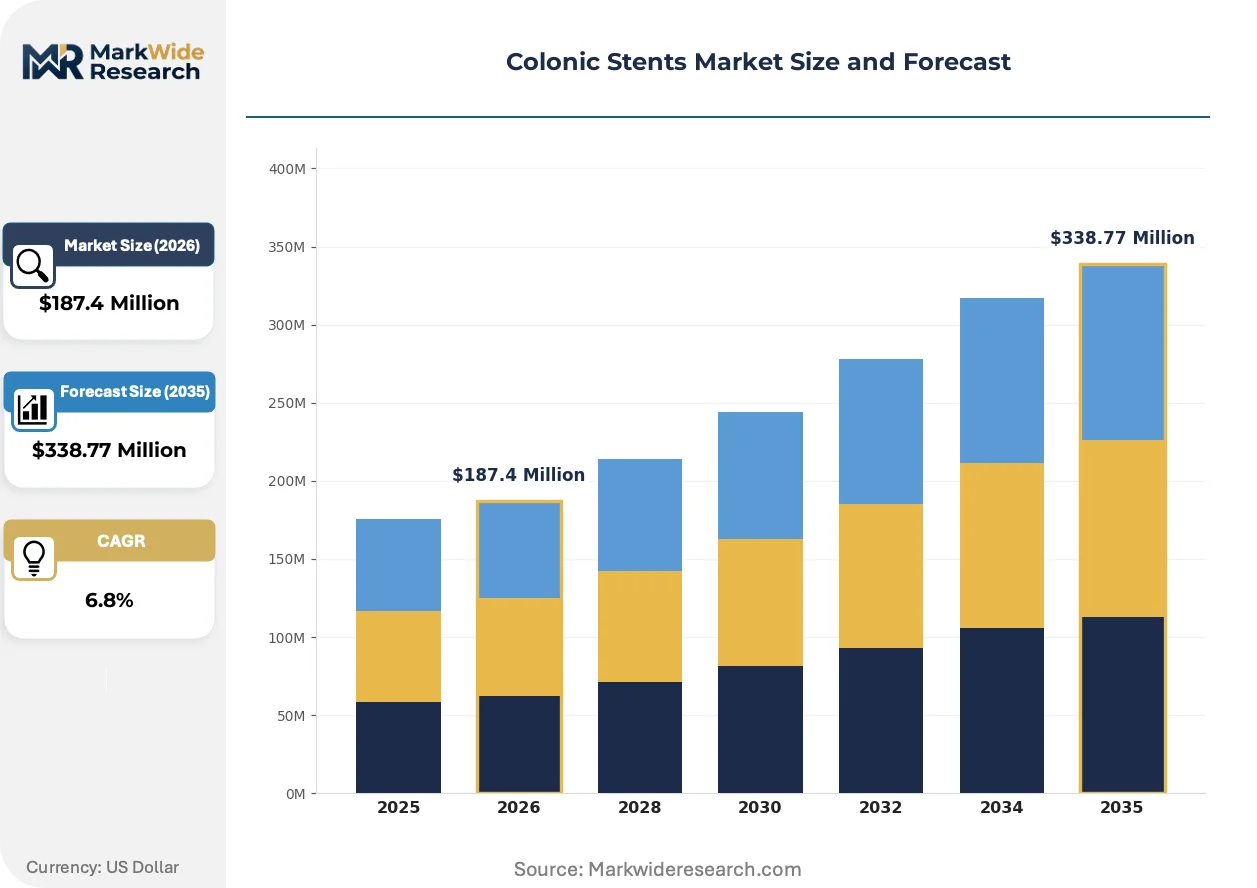
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
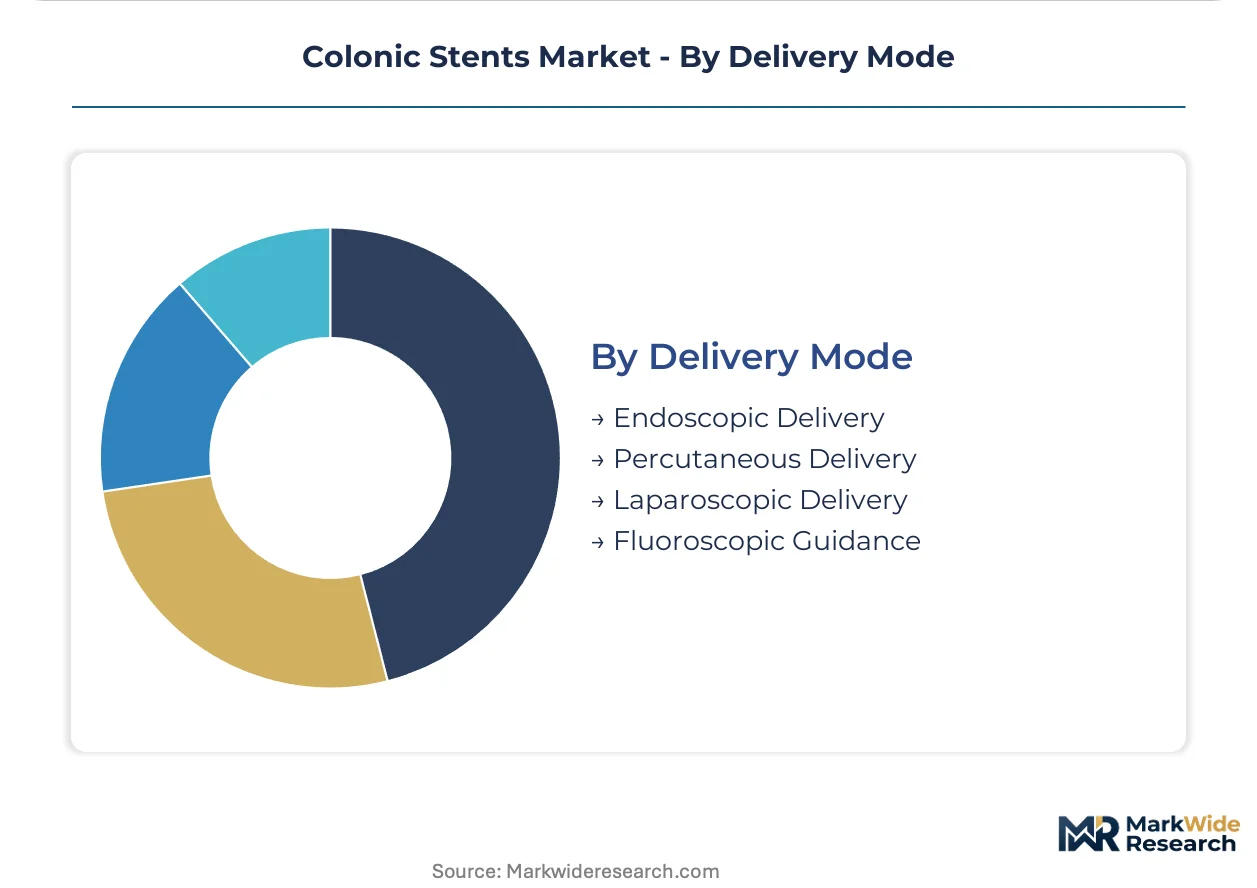
| Segmentation | Product Type: Self-Expandable Stents, Balloon-Expandable Stents, Metal Stents, Plastic Stents End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Application: Colorectal Obstruction, Colonic Cancer, Diverticulitis, Inflammatory Bowel Disease Delivery Mode: Endoscopic Delivery, Percutaneous Delivery, Laparoscopic Delivery, Fluoroscopic Guidance |
| Companies Covered | Boston Scientific Corporation, Medtronic, Cook Medical, Olympus Corporation, Merit Medical Systems, CONMED Corporation, ELLA-CS, Taewoong Medical, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colonic Stents Market Emerging Trajectories
Modular kit configurations and surface engineering advances are redefining how colonic stents are procured, deployed, and retrieved across care settings.
Biodegradable polymer coatings are expanding into temporary stent applications where surgical resection follows palliative decompression. Gastroenterology departments in German university hospitals are piloting coated platforms for bridge-to-surgery protocols. The technology is expanding into cases previously reserved for uncovered metal stents.
The EU MDR's post-market surveillance requirements are mandating extended follow-up registries for permanent implants. Manufacturers must now submit periodic safety update reports beyond initial certification. Self-expanding metal stent categories face the steepest documentation burden as legacy devices transition to renewed conformity assessments.
Hospital procurement departments are consolidating vendor contracts around bundled stent-delivery-retrieval packages. Group purchasing organizations are displacing individual facility negotiations in the United States. This concentration is most visible in integrated delivery networks across Texas and Florida, where standardization committees mandate single-source agreements.
Colonic Stents Market Segmentation
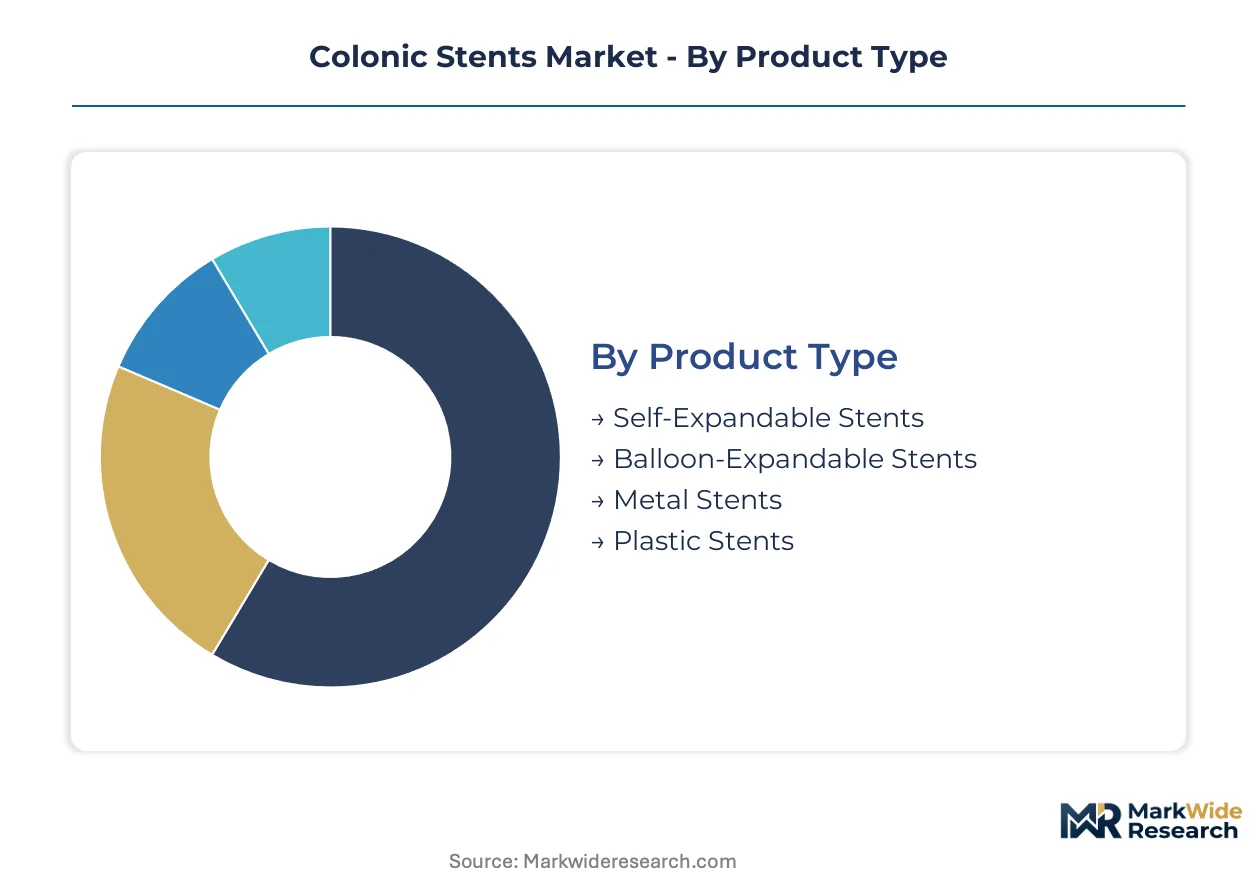
Colonic stent procurement decisions pivot on procedural setting, obstruction etiology, and deployment modality. Manufacturers configure kit specifications and pricing tiers around these intersecting variables to secure hospital system contracts.
Product Type:
Hospital purchasing committees weight conformability against retrieval complexity when selecting stent platforms for their formularies.
- Self-Expandable Stents:Nitinol alloy construction delivers radial force for patency restoration in tortuous colonic anatomy. Demand concentrates in malignant obstruction cases across United States integrated delivery networks, where same-day discharge protocols favor reliable radial expansion without balloon assistance.
- Metal Stents:Stainless steel and nitinol platforms with polymer coatings dominate permanent implant applications. German university hospitals prefer coated variants for bridge-to-surgery protocols, balancing tissue ingrowth resistance against mechanical durability.
- Balloon-Expandable Stents:Controlled diameter adjustment suits benign strictures requiring precise sizing. These platforms occupy niche positioning in preoperative decompression segments.
- Plastic Stents:Polyethylene construction enables temporary palliation at lower unit cost. Japanese clinics deploy these for diverticular strictures where definitive surgical resection follows stenting.
Metal stents lead on scale; self-expandable platforms lead on momentum.
End User:
Reimbursement differentials and facility accreditation standards determine channel-specific kit configurations.
- Hospitals:Inpatient departments manage complex malignant obstructions requiring multidisciplinary coordination. These facilities anchor procurement volume through bundled contracts covering stent, delivery system, and retrieval accessories.
- Ambulatory Surgical Centers:Same-day stenting protocols are expanding fastest in Texas and Florida ASC networks, where streamlined inventory models favor modular kit unbundling.
- Specialty Clinics:Gastroenterology-focused practices in metropolitan Tokyo and Osaka clusters concentrate elective benign stricture cases.
- Research Laboratories:Academic medical centers in Germany pilot biodegradable coating technologies under controlled protocols.
Hospitals retain volume dominance; ASCs are climbing the fastest.
Application:
Obstruction etiology dictates stent duration, coating requirements, and retrieval planning.
- Colorectal Obstruction:Acute large-bowel blockage from any cause represents the core procedural indication. United States emergency departments drive throughput for this segment.
- Colonic Cancer:Malignant strictures require durable patency with minimal tissue ingrowth. German and Japanese oncology centers specify drug-eluting coatings for these cases.
- Diverticulitis:Inflammatory strictures favor temporary stenting ahead of elective resection. Plastic platforms retain utility here.
- Inflammatory Bowel Disease:Crohn's-related strictures in younger patients demand biocompatible materials with retrieval compatibility.
Colorectal obstruction leads on scale; colonic cancer applications show steepest expansion trajectory.
Delivery Mode:
Visualization technology integration shapes deployment site selection and operator training requirements.
- Endoscopic Delivery:Direct luminal visualization via colonoscope remains the standard deployment method. Gastroenterology suites across United States hospital systems standardize on this approach.
- Fluoroscopic Guidance:Real-time radiographic imaging enables percutaneous placement in interventional radiology suites. Japanese facilities are expanding hybrid endoscopy-fluoroscopy capabilities.
- Percutaneous Delivery:Radiologist-directed placement accesses obstructed segments without endoscopic intubation. German interventional radiology departments favor this for proximal obstructions.
- Laparoscopic Delivery:Surgical-assisted deployment applies to failed endoscopic cases or combined procedures.
Endoscopic delivery leads on scale; fluoroscopic guidance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colonic stent technology originated in German university hospitals during the 1990s, where interventional gastroenterology pioneers refined self-expanding metal platforms for malignant obstruction management. Japanese manufacturers subsequently scaled nitinol production capabilities, while United States integrated delivery networks standardized procurement protocols. Today procedural volume concentrates in aging metropolitan clusters across these three foundational markets.
United States
Medicare reimbursement expansion for outpatient stenting drives ambulatory surgical center adoption in Texas and Florida networks. FDA 510(k) clearance pathways compress nitinol device introduction timelines relative to PMA requirements. Integrated delivery networks in Houston and Miami standardize bundled procurement contracts covering stent-delivery-retrieval packages.
Germany
Bridge-to-surgery protocols at university hospitals in Munich and Heidelberg generate sustained demand for coated metal platforms. EU MDR clinical evidence requirements mandate extended biocompatibility documentation for permanent implants. The Baden-Württemberg medical device cluster anchors European manufacturing of fluoroscopy-integrated delivery systems.
Japan
Metropolitan Tokyo and Osaka gastroenterology practices concentrate elective benign stricture cases requiring PMDA-certified nitinol biocompatibility. Japan's national health insurance system reimburses stenting procedures for colorectal cancer palliation. The Kansai region hosts specialized manufacturers supplying retrieval accessories for temporary plastic stent applications.
United Kingdom
NHS England cancer pathway targets compress time-to-treatment intervals for malignant large-bowel obstructions. MHRA post-Brexit regulatory alignment with EU MDR extends certification timelines for legacy devices. London teaching hospitals pilot biodegradable coating technologies under controlled academic protocols.
South Korea
MFDS accelerated review pathways for nitinol implants support domestic manufacturer expansion into export markets. Seoul metropolitan area endoscopy centers adopt same-day discharge protocols for palliative stenting. The Songdo medical cluster attracts foreign device sponsors seeking Asia-Pacific regulatory harmonization.
Colonic Stents Market Vendor Landscape
The competitive structure tilts toward diversified medtech conglomerates with integrated gastrointestinal portfolios. Hospital procurement consolidation favors vendors offering bundled stent-delivery-retrieval packages over component specialists. Three archetypes dominate: nitinol alloy fabricators with captive metallurgy capabilities, endoscopy platform integrators leveraging visualization synergies, and retrieval accessory specialists unbundling for ambulatory inventory models. Scale-driven manufacturers pursue vertical integration into nitinol feedstock contracting, while mid-tier players seek technology licensing partnerships to compress EU MDR compliance costs.
Among United States-based diversified medtech conglomerates, Boston Scientific Corporation and Medtronic exemplify the integrated portfolio archetype, anchoring premium positioning in hospital system contracts. Cook Medical represents the specialized delivery configuration tier, with its Indiana origins reflecting a regional concentration of interventional device manufacturing expertise. These three entities collectively illustrate how competitive positioning stratifies across bundled contract scale, manufacturing integration depth, and clinical application specialization.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Cook Medical |
| Olympus Corporation |
| Merit Medical Systems |
| CONMED Corporation |
| ELLA-CS |
| Taewoong Medical |
| BD |
| Others |
Supply Flow & Price Mechanics
EU MDR post-market surveillance mandates gate access to premium-tier hospital contracts, forcing manufacturers to absorb extended biocompatibility documentation costs before pricing power materializes. Nitinol alloy feedstock volatility and notified body capacity constraints compress margins for unprepared suppliers while rewarding backward-integrated incumbents with captive metallurgy capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by coating technology sophistication and retrieval accessory bundling. FDA 510(k) clearance tier commands premium positioning against CE-marked equivalents, while uncoated plastic platforms face cost compression from polyethylene spot market softness. Ambulatory surgical centers exhibit highest price sensitivity due to lean inventory models, whereas German university hospitals prioritize drug-eluting specifications over unit cost.
Supply Chain Analysis
Stent retrieval and refurbishment flows remain underdeveloped relative to cardiovascular implant reverse logistics, though Japanese manufacturers pilot nitinol reprocessing for temporary plastic platforms. Raw material sourcing concentrates in Southeast Asian nickel mining corridors and Chinese titanium sponge refining, with German precision wire drawing and United States polymer coating completing value assembly. Single-source vulnerability in nitinol shape-memory alloy feedstock threatens production continuity, while distribution runs through hospital group purchasing organizations and specialized endoscopy distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colonic stents market represents a late-cycle quality story where bridge-to-surgery protocol adoption shifts procurement specifications toward drug-eluting coated platforms with extended patency documentation.
For Market Incumbents: Cement hospital system loyalty through exclusive retrieval accessory supply agreements that lock out competing delivery system vendors. Deepen backward integration into nitinol wire drawing to buffer Southeast Asian feedstock volatility, while accelerating EU MDR technical file preparation ahead of notified body reauthorization cascades. For New Entrants and Emerging Players: Direct-to-ASC digital procurement platforms offer the most penetrable entry vector, bypassing incumbent-dominated GPO contracts. Target Texas and Florida ambulatory networks with unbundled stent-only SKUs, leveraging fluoroscopy-integrated delivery training partnerships with interventional radiology societies as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for retrieval accessory specialists because hospital standardization committees increasingly mandate single-source stent-delivery-retrieval bundles. Five-to-ten year viability hinges on coating technology differentiation; monitor PMDA biocompatibility harmonization progress for nitinol implants as the signal for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Advancement | Notified body capacity constraints extend certification timelines for legacy device renewals. |
| Hospital System Partnership | Integrated delivery networks in Texas standardize bundled procurement contracts covering full procedure kits. |
| Biodegradable Coating Development | German university hospitals pilot temporary stent platforms for bridge-to-surgery protocols. |
| ASC Channel Expansion | Same-day discharge protocols in Florida drive fastest-growing end-user segment adoption. |
| Reimbursement Strategy | Medicare outpatient stenting expansion determines ambulatory surgical center purchasing cycles. |
Methodological Framework
Direct dialogue with interventional gastroenterologists, hospital purchasing committee directors, biomedical engineers specializing in nitinol implants, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body technical file registries, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Bottom-up modeling aggregated procedure volumes by obstruction etiology and deployment modality, while top-down analysis validated manufacturer revenue segmentation across product tiers. The forecast framework incorporated aging demographic projections, endoscopic infrastructure expansion rates, and reimbursement policy trajectories across the analysis window. CAGRs derived from fitted trend extrapolation moderated by regulatory timeline uncertainty.
The model assumes a particular technology adoption path; alternative pathways for biodegradable polymer coatings would alter the outlook if bridge-to-surgery protocols shift toward definitive resection without metal implantation. Practitioners should monitor PMDA biocompatibility testing harmonization and EU notified body reauthorization completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Bronchoscopy Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Endoscopy Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Global Veterinary Endoscopy Market