
 Functional Endoscopic Sinus Surgery Systems Market | 2026-2036
Functional Endoscopic Sinus Surgery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Endoscopic Sinus Surgery Systems Market Foresight
The capital-intensity divergence between integrated navigation suite manufacturers and standalone instrument suppliers is unwinding competitive boundaries in functional endoscopic sinus surgery systems. Medtronic plc leverages its spine and navigation heritage to bundle electromagnetic tracking with powered instrumentation, commanding premium positioning in academic medical centers. Karl Storz SE & Co. KG anchors its position through in-house optical manufacturing, sustaining margins on rigid endoscope glass assemblies that competitors source externally. Smith & Nephew plc competes on disposable blade economics, differentiating its powered instrument portfolio in ambulatory surgery centers where reprocessing costs drive procurement decisions.
Functional endoscopic sinus surgery systems comprise minimally invasive platforms combining high-definition endoscopes, image-guidance navigation, powered tissue-removal handpieces, and integrated smoke evacuation for paranasal sinus and skull base access. Optical coherence tomography-enabled navigation achieves sub-millimeter accuracy by registering preoperative CT datasets to intraoperative anatomy, permitting precise ethmoid and sphenoid dissection near the optic nerve and internal carotid artery. Surgical instruments represent the most mature revenue pool with established replacement cycles, while navigation systems capture the fastest expansion as hospitals prioritize patient safety metrics and liability reduction. ENT clinics concentrate demand for compact, cart-based configurations with lower throughput requirements, whereas academic medical centers absorb multi-modality suites incorporating fluorescence imaging for oncologic margin assessment.
FDA 510(k) premarket notification governs Class II powered surgical instrument clearances in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on reusable endoscope revalidation, extending certification timelines for European market access. Japan's PMDA enforces JIS standards on optical performance and biocompatibility testing, creating incremental compliance burdens for Western manufacturers seeking Ministry of Health, Labour and Welfare approval. Stakeholders must monitor reimbursement divergence between inpatient and ambulatory procedural codes, as site-of-service payment differentials increasingly dictate capital equipment placement decisions.
Market Dynamics
Navigation-enabled surgical platforms are compressing replacement cycles for standalone endoscopes as hospitals prioritize liability reduction and precision metrics over capital preservation.
Growth Catalysts
- Navigation Integration Mandates:Academic medical centers in Germany now specify electromagnetic tracking as standard procurement criteria for skull base procedures, accelerating platform upgrades.
- EU MDR Clinical Evidence Pathways:Stricter reusable endoscope revalidation requirements under the EU Medical Device Regulation are consolidating demand behind manufacturers with captive sterilization validation capabilities.
- Fluorescence-Guided Resection:Near-infrared imaging for oncologic margin assessment is expanding addressable procedure volume in tertiary referral centers performing anterior skull base tumor resections.
Market Restraints
- Optical Glass Supply Concentration:German and Japanese manufacturers control precision rod-lens supply for rigid endoscopes, exposing assemblers to input bottlenecks and price volatility.
- Capital Equipment Replacement Compression:Extended depreciation schedules for navigation suites—now 10-12 years versus 7-9 for standalone instruments—are elongating revenue recognition timelines for integrated system vendors.
- Substitute Technique Resurgence:Balloon sinuplasty catheter systems are recapturing select chronic rhinosinusitis cases in ambulatory settings where tissue preservation outweighs radical dissection requirements.
Strategic Opportunities
- India Ambulatory Surgery Center Expansion:Government PLI scheme incentives for medical device manufacturing are lowering landed costs for cart-based navigation systems targeting tier-2 city ENT clinics.
- Optical Coherence Tomography Convergence:Integration of intraoperative OCT with existing electromagnetic tracking platforms enables real-time mucosal assessment without additional capital footprint.
- Disposable Blade Economics:Single-use powered instrument adoption in US ambulatory surgery centers bypasses reprocessing validation burdens and captures procedure volume migrating from inpatient settings.
Industry Challenges
- Navigation Calibration Expertise Gap:Biomedical engineering departments lack personnel trained on electromagnetic field distortion compensation in hybrid operating rooms with multiple metallic implants.
- 510(k) Predicate Device Drift:FDA's narrowing acceptance of substantial equivalence for next-generation optical tracking algorithms is extending premarket notification preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Endoscopic Sinus Surgery Systems Market |
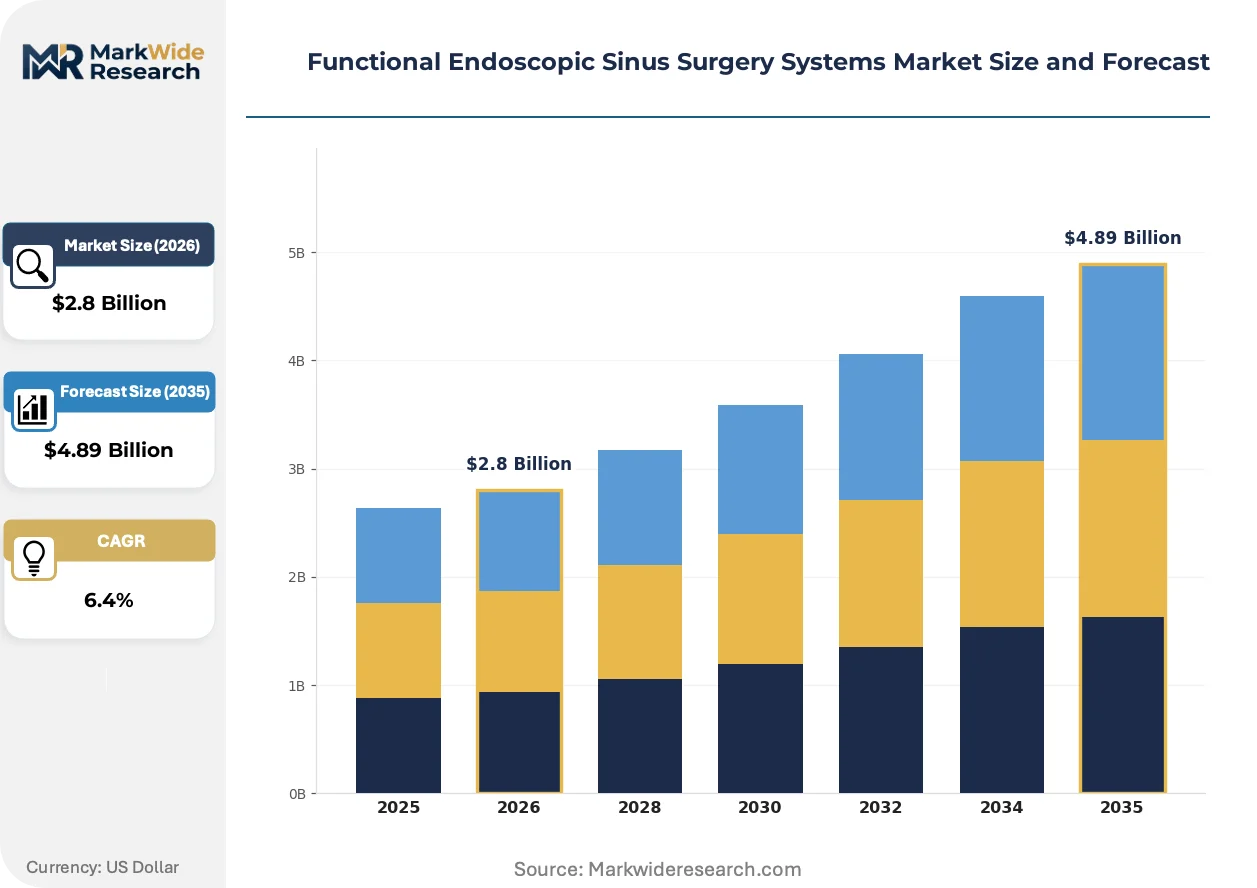
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Imaging Systems, Surgical Instruments, Smoke Evacuators Technology: Optical Coherence Tomography, 3D Endoscopy, Fluorescence Imaging, Cold Light Source Application: Chronic Sinusitis Treatment, Nasal Polyps Removal, Skull Base Surgery, Orbital Decompression End User: ENT Clinics, Ambulatory Surgery Centers, Academic Medical Centers, Specialized Surgical Units |
| Companies Covered | Johnson & Johnson, Karl Storz SE & Co. KG, Medtronic plc, Richard Wolf GmbH, B. Braun Melsungen AG, Olympus Corporation, Smith & Nephew plc, ConMed Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Endoscopic Sinus Surgery Systems Market Shifts & Advancements
Digital surgical workflows are redefining capital allocation priorities as hardware margins compress and software-enabled procedure documentation becomes a differentiated purchasing criterion.
4K three-chip camera heads are supplanting single-chip alternatives in academic medical center procurement specifications, with institutions in Japan and Germany now requiring native 4K resolution for fellowship training accreditation. The technology is compressing secondary market values for 1080p systems and forcing mid-tier manufacturers to accelerate sensor partnerships or exit the premium rigid endoscope segment entirely.
Japan's PMDA has tightened JIS T 0601-1 electrical safety standards for powered surgical instruments, compelling Western manufacturers to redesign handpiece insulation architectures and resubmit existing 510(k) cleared products for Ministry of Health, Labour and Welfare approval. The regulation most affects high-speed microdebrider portfolios, where motor housing miniaturization conflicts with enhanced creepage distance requirements.
Hospital purchasing consortia are consolidating vendor relationships for sinus surgery platforms, with integrated navigation-instrument bundles displacing discrete procurement of endoscopes, cameras, and powered handpieces from separate suppliers. This concentration is most pronounced in US multi-hospital systems where standardization across 15-plus facilities generates volume-based pricing leverage and reduces spare parts inventory complexity.
Functional Endoscopic Sinus Surgery Systems Market Segmentation
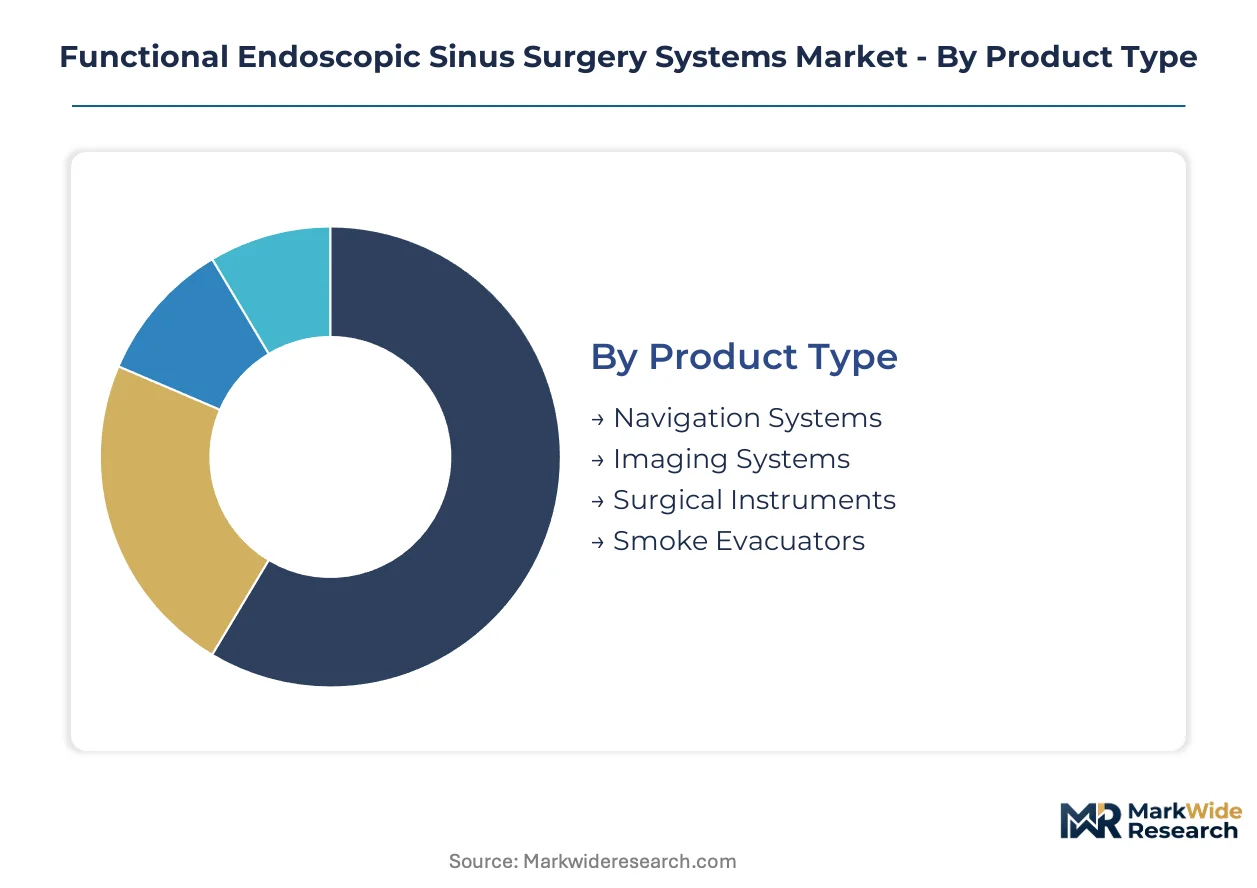
Segmentation in functional endoscopic sinus surgery systems reveals how procurement criteria diverge between liability-sensitive academic centers and cost-conscious ambulatory settings. Each dimension—product, technology, application, and end user—carries distinct regulatory, reimbursement, and workflow implications that reshape vendor positioning.
Product Type:
FDA 510(k) clearance timelines vary substantially across this category, with Class II powered instruments facing shorter review cycles than software-dependent navigation platforms requiring algorithm validation.
- Surgical Instruments:Powered microdebriders and manual forceps constitute the most mature revenue pool with established replacement cycles driven by wear on cutting edges and insulation integrity. Academic medical centers in Germany specify Karl Storz and Richard Wolf instrumentation for fellowship training accreditation, creating procurement stickiness despite premium pricing.
- Navigation Systems:Electromagnetic and optical tracking platforms integrate preoperative CT registration with intraoperative instrument localization, achieving sub-millimeter accuracy for skull base approaches near critical neurovascular structures. Demand concentrates in US academic medical centers where liability reduction metrics justify capital expenditure despite 10-12 year depreciation schedules.
- Imaging Systems:4K three-chip camera heads and xenon or LED light sources provide visualization backbone for endoscopic procedures.
- Smoke Evacuators:Integrated suction and filtration units address surgical plume hazards in high-volume settings.
Surgical Instruments handles the majority of throughput; Navigation Systems is the fastest mover on share.
Technology:
Cost tier differentiation separates premium imaging modalities from foundational visualization infrastructure, with reimbursement codes increasingly favoring technologies that demonstrate measurable outcome improvements.
- Optical Coherence Tomography:Intraoperative OCT enables real-time mucosal assessment and subsurface tissue characterization without additional capital footprint when integrated with existing navigation platforms. Japan's PMDA has established dedicated review pathways for OCT-enabled surgical devices, accelerating market access for manufacturers with JIS T 0601-1 electrical safety compliance.
- Fluorescence Imaging:Near-infrared systems utilizing indocyanine green contrast permit oncologic margin assessment during anterior skull base tumor resections, expanding addressable procedure volume in tertiary referral centers. US academic medical centers absorb these systems despite limited dedicated reimbursement, prioritizing publication opportunities and fellowship recruitment.
- 3D Endoscopy:Stereoscopic visualization reduces surgeon fatigue in extended procedures through depth perception enhancement.
- Cold Light Source:LED and xenon illumination systems represent the foundational technology tier with compressed margins and replacement-driven demand.
Fluorescence Imaging captures premium placement in skull base oncology; Optical Coherence Tomography is climbing the fastest as platform integration costs decline.
Application:
Volume concentration aligns with chronic disease prevalence and procedural reimbursement differentials between inpatient and ambulatory settings.
- Chronic Sinusitis Treatment:Functional endoscopic sinus surgery for medically refractory chronic rhinosinusitis constitutes the highest-volume indication, with balloon sinuplasty catheters competing for select cases in ambulatory settings. Germany's statutory health insurance system maintains favorable reimbursement for conventional dissection techniques in hospital-based ENT departments.
- Skull Base Surgery:Anterior and lateral skull base approaches for CSF leak repair, pituitary adenoma resection, and sinonasal malignancy excision demand navigation integration and specialized instrumentation. Academic medical centers in the United States concentrate this volume, with fellowship programs requiring minimum case exposure for accreditation.
- Nasal Polyps Removal:Polypectomy procedures in recurrent or severe cases drive repeat intervention demand.
- Orbital Decompression:Thyroid eye disease surgical management represents a lower-volume, higher-complexity application.
Chronic Sinusitis Treatment dominates procedure volume; Skull Base Surgery is expanding most quickly as navigation adoption broadens.
End User:
Customer type determines capital intensity tolerance, with integrated suite procurement reserved for high-throughput institutions and compact configurations serving lower-volume settings.
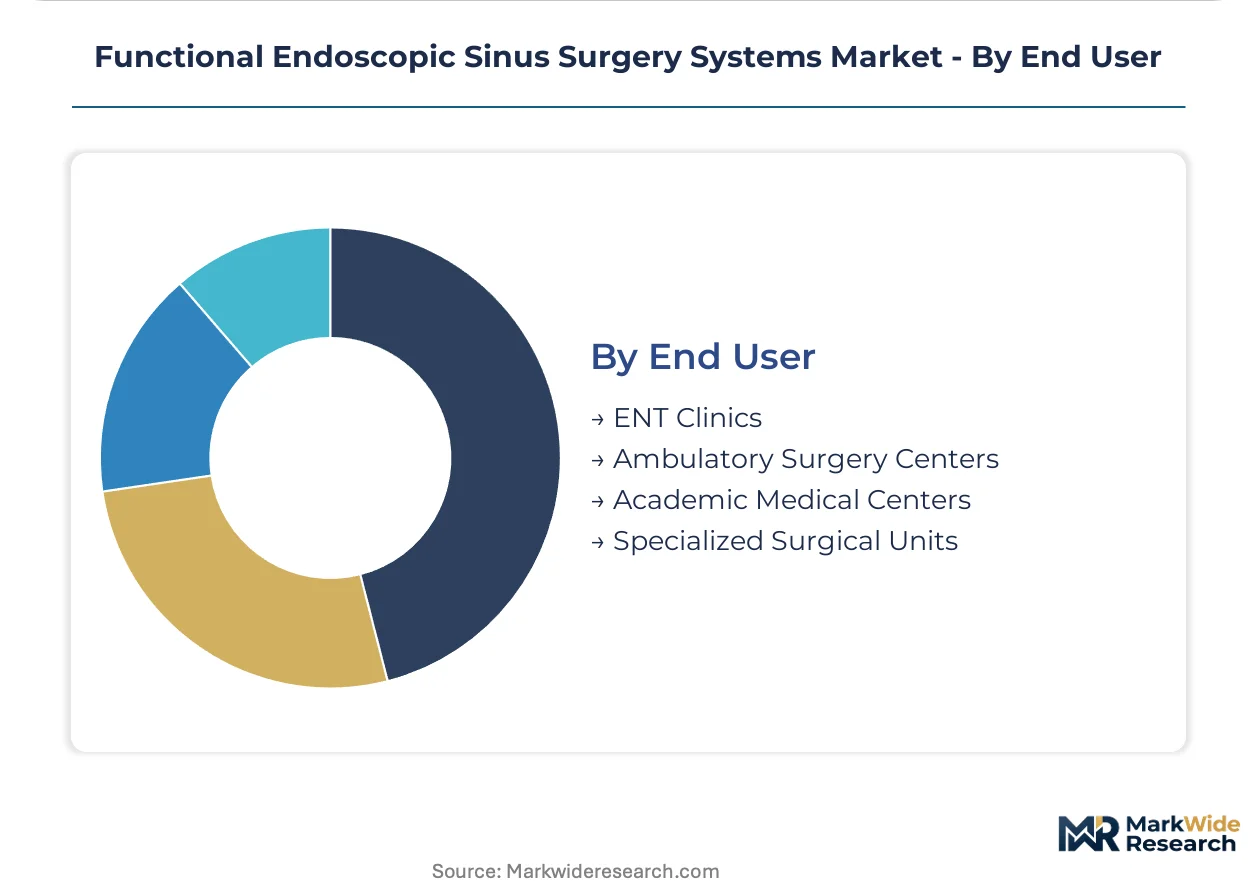
- Academic Medical Centers:Multi-modality suites incorporating fluorescence imaging, 4K visualization, and electromagnetic navigation serve fellowship training, research productivity, and complex referral case requirements. US multi-hospital systems leverage purchasing consortia to standardize across 15-plus facilities, consolidating vendor relationships and reducing spare parts inventory complexity.
- Ambulatory Surgery Centers:Cart-based configurations with disposable blade economics prioritize reprocessing cost avoidance and rapid turnover. US site-of-service payment differentials increasingly favor ASC placement for routine chronic sinusitis cases, driving demand for compact, lower-capital systems.
- ENT Clinics:Office-based settings absorb diagnostic and minor procedural volume with reduced throughput requirements.
- Specialized Surgical Units:Dedicated skull base or oncologic centers within larger institutions concentrate premium technology adoption.
Academic Medical Centers absorb the highest capital per site; Ambulatory Surgery Centers are gaining share fastest as procedural migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by a substantial margin, reflecting divergent reimbursement structures and capital equipment procurement sophistication. Academic medical centers in Germany absorb premium navigation suites with 10-12 year depreciation schedules, while Indian tier-2 cities prioritize cart-based configurations under government manufacturing incentives.
United States
FDA 510(k) premarket notification governs Class II powered surgical instrument clearances, with narrowing acceptance of substantial equivalence for optical tracking algorithms extending preparation timelines. Academic medical centers concentrate demand for multi-modality suites incorporating fluorescence imaging and electromagnetic navigation. Hospital purchasing consortia across multi-hospital systems with 15-plus facilities consolidate vendor relationships and reduce spare parts inventory complexity.
Germany
EU Medical Device Regulation imposes stricter clinical evidence requirements on reusable endoscope revalidation, extending certification timelines for market access. Statutory health insurance maintains favorable reimbursement for conventional dissection techniques in hospital-based ENT departments. Tuttlingen and Berlin anchor advanced manufacturing clusters for precision endoscopic instrumentation, with Karl Storz and Richard Wolf sustaining captive optical glass assembly capabilities.
Japan
PMDA enforces JIS T 0601-1 electrical safety standards for powered surgical instruments, compelling redesign of handpiece insulation architectures and resubmission of existing products for Ministry of Health, Labour and Welfare approval. Fellowship training accreditation now requires native 4K resolution specifications. Tokyo and Osaka metropolitan areas concentrate demand for integrated navigation platforms with OCT-enabled surgical device pathways.
India
Government PLI scheme incentives for medical device manufacturing lower landed costs for cart-based navigation systems. Site-of-service payment differentials increasingly favor ambulatory surgery center placement for routine chronic sinusitis cases. Tier-2 cities in Maharashtra and Karnataka expand ENT clinic infrastructure, absorbing compact configurations with disposable blade economics.
United Kingdom
NHS procurement frameworks standardize sinus surgery platform specifications across regional hospital networks, prioritizing interoperability and training pathway continuity. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UK-specific approval pathways. London and the Southeast concentrate academic medical center demand for skull base navigation suites, with fellowship programs requiring minimum case exposure for accreditation.
Functional Endoscopic Sinus Surgery Systems Market Competitive Landscape
Concentration sits with integrated navigation suite manufacturers leveraging electromagnetic tracking heritage to bundle premium instrumentation, while standalone optical specialists defend margin positions through in-house glass assembly. The vendor base stratifies across three tiers: diversified medical technology conglomerates with spine and navigation synergies; captive optical manufacturers with rigid endoscope glass capabilities; and disposable instrument specialists competing on reprocessing cost avoidance. Dominant competitive moves include strategic bundling of navigation-instrument suites and geographic expansion into government-incentivized manufacturing jurisdictions.
Among diversified medical technology conglomerates, Medtronic plc and Stryker Corporation occupy positions leveraging cross-divisional navigation expertise to anchor integrated platform offerings. Karl Storz SE & Co. KG exemplifies the captive optical manufacturing archetype, with German GmbH structure indicating family-controlled precision instrumentation heritage. Johnson & Johnson and B. Braun Melsungen AG represent scale-driven diversified players with broad surgical portfolio reach. Olympus Corporation and Smith & Nephew plc sit within distinct specialization vectors—Japanese optical imaging heritage and British disposable economics respectively—while Richard Wolf GmbH and ConMed Corporation anchor mid-tier positions in German and US markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Karl Storz SE & Co. KG |
| Medtronic plc |
| Richard Wolf GmbH |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Smith & Nephew plc |
| ConMed Corporation |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
LED illumination modules replacing xenon light sources are redrawing procurement geography and compressing price premiums across visualization tiers. German optical assemblers absorbing captive glass rod-lens production retain margin leverage against Asian competitors sourcing precision optics externally, while Indian manufacturing incentives under the PLI scheme erode landed cost differentials for cart-based configurations.
Pricing Analysis
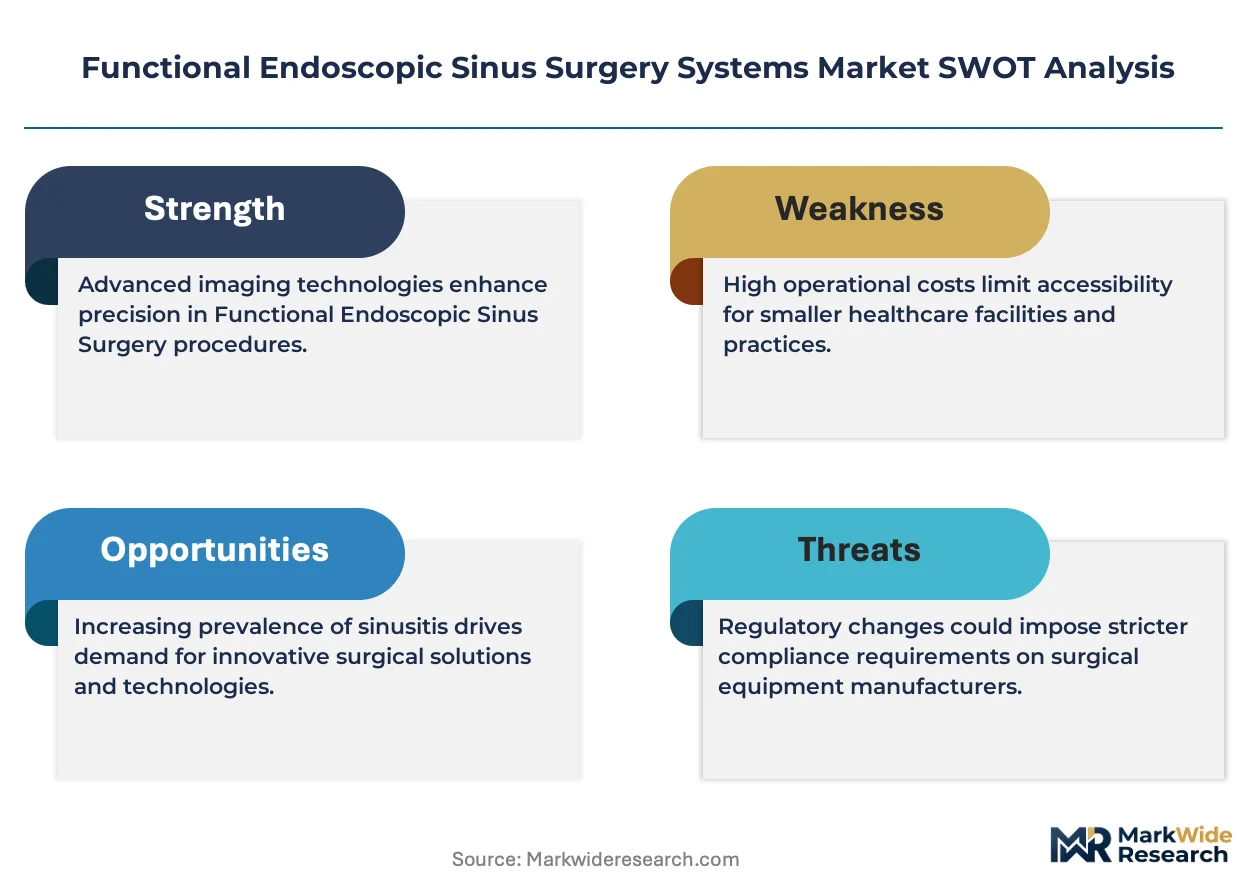
The customization-premium spread separates academic medical center configurations from ambulatory surgery center bundles by a substantial margin. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, optical resolution specification, and bundled navigation integration. Cost compression in the standard tier is intensifying because balloon sinuplasty catheters recapture select chronic rhinosinusitis cases. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers absorbing multi-modality suites demonstrate lowest.
Supply Chain Analysis
Inventory lead times for precision rod-lens assemblies extend substantially longer than powered handpiece components due to optical glass supply concentration. German and Japanese manufacturers control rigid endoscope glass fabrication, while handpiece motor and insulation components draw from Chinese and Mexican assembly operations. Single-source vulnerability concentrates in Tuttlingen-area optical glass melting capacity. Distribution runs through hospital purchasing consortia and specialized surgical device distributors serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) predicate device drift and EU MDR clinical evidence requirements create multi-year certification barriers that protect incumbent positions.
For Market Incumbents: Compound switching cost advantages by deepening electromagnetic tracking algorithm patent estates and bundling disposable blade economics with navigation platform leases. Balloon sinuplasty catheter resurgence in ambulatory settings threatens standalone instrument replacement cycles. Prioritize backward integration into optical glass rod-lens production to defend margin positions against Asian cost competitors.
For New Entrants and Emerging Players: Japan's PMDA dedicated review pathways for OCT-enabled surgical devices offer certification fast-track opportunities absent in saturated US and EU pathways. Target tier-2 Indian cities expanding ENT clinic infrastructure under government manufacturing incentives. Deploy disposable-powered instrument economics to bypass incumbent reprocessing validation advantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical navigation specialists lacking optical manufacturing depth. Long-term viability hinges on platform integration density rather than standalone instrument share. Monitor US site-of-service payment differential expansion as the signal indicating ambulatory surgery center capital equipment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Electromagnetic tracking algorithm clearances anchor multi-modality suite bundling in US academic centers. |
| EU MDR Clinical Evidence Investment | Reusable endoscope revalidation capabilities consolidate demand behind manufacturers with captive sterilization infrastructure. |
| Hospital System Partnership | Multi-hospital purchasing consortia standardization across 15-plus facilities generates volume-based pricing leverage. |
| Software Companion Development | Digital surgical workflow documentation differentiates capital allocation priorities as hardware margins compress. |
| Reimbursement Strategy | Site-of-service payment differential optimization dictates ambulatory surgery center equipment placement decisions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ENT surgeons, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciled instrument replacement cycle estimates with navigation platform depreciation schedules.
Across the projection horizon, the analytical framework modeled product type, technology tier, application indication, and end-user capital intensity. CAGRs derived from procedure volume migration patterns between inpatient and ambulatory settings, navigation adoption curves in skull base surgery, and optical resolution upgrade cycles. Forecast inputs incorporated PLI scheme incentive phase-ins and JIS T 0601-1 electrical safety compliance redesign timelines.
Decision-makers should treat outputs as directional under stable reimbursement and regulatory clearance assumptions; material deviation in FDA predicate acceptance or EU MDR enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Endoscopy Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Global Colonoscopes Market
Endoscopy
AI in Endoscopy Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Industrial Endoscope Market