
 North America Endoscopy Devices Market | 2026-2036
North America Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Endoscopy Devices Market Analytics
Recurring service and software-defined visualization layers is restructuring how endoscopy vendors monetize hardware deployments. Olympus Corporation sustains its installed base through proprietary image-processing subscriptions that lock in hospital customers. Boston Scientific Corporation leverages dedicated technical field teams to control replacement-part revenue streams across ambulatory surgical centers.
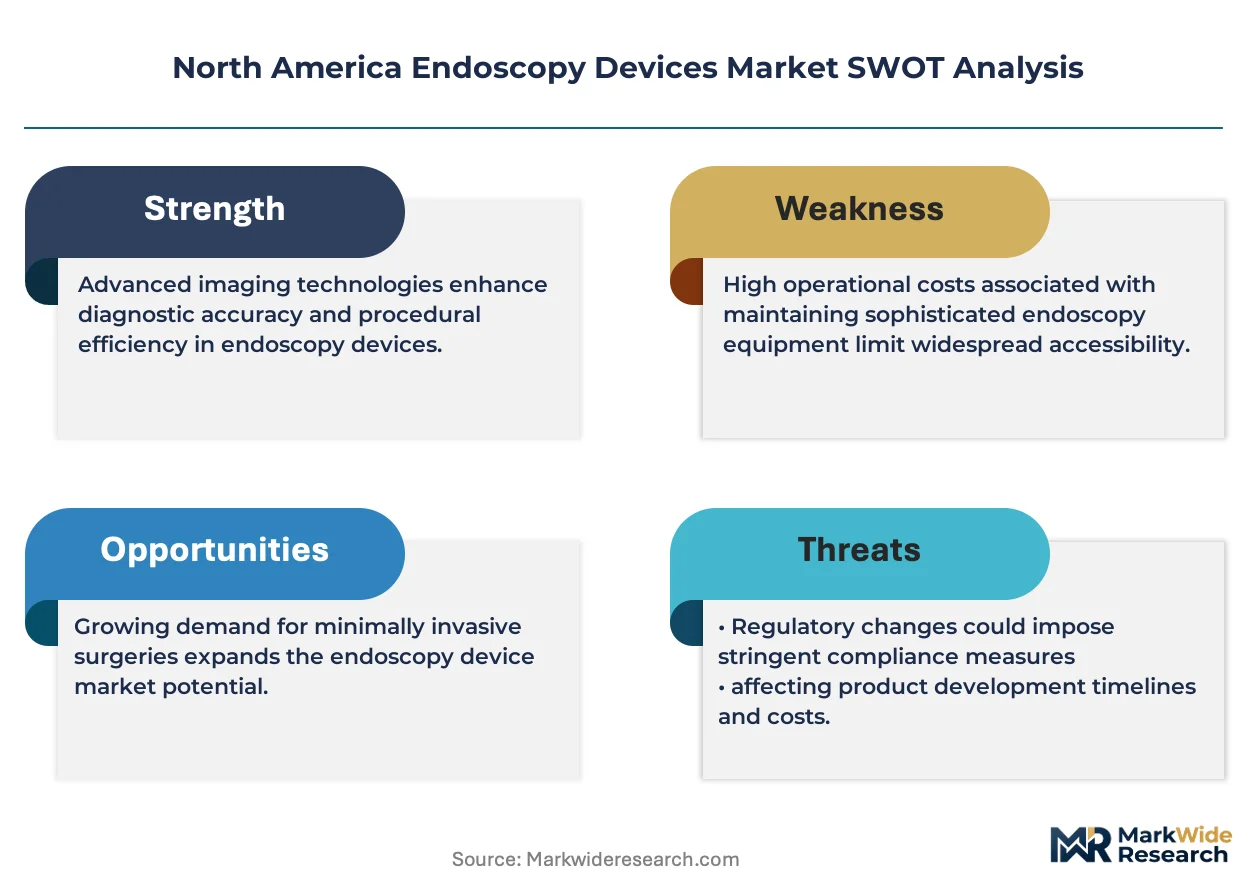
Endoscopy devices are instrument systems incorporating fiber-optic or digital image sensors, illumination channels, and working ports for biopsy or therapeutic intervention, typically manufactured with medical-grade stainless steel and polymer sheaths rated for repeated sterilization cycles. Their primary purpose is enabling minimally invasive internal examination and intervention without open surgery. Flexible endoscopes occupy the largest revenue pool due to gastroenterology volume, while robot-assisted endoscopy represents the fastest-expanding technology segment as health systems pursue procedural standardization. Capsule endoscopes command premium positioning in small-bowel diagnostics where conventional scope access remains constrained.
The FDA governs 510(k) clearance pathways and reprocessing validation requirements for reusable devices, while Health Canada and Mexico's national pharmaceutical regulator enforce parallel safety standards that shape cross-border product specifications. The Centers for Medicare and Medicaid Services reimbursement policies directly influence hospital capital allocation toward video and image-enhanced endoscopy platforms. Stakeholders must monitor evolving sterilization mandates and reimbursement tiering for outpatient procedures to anticipate capital cycle timing.
Market Dynamics
Reprocessing validation mandates from the FDA are compressing replacement cycles for flexible endoscopes while elevating capital requirements for sterilization infrastructure across United States hospital systems.
Growth Catalysts
- CMS reimbursement tiering:Medicare's expanded coverage for outpatient endoscopic procedures is pulling diagnostic volume into ambulatory surgical centers across the United States.
- Robot-assisted platforms:Health systems are deploying computer-navigated endoscopy systems to standardize procedural outcomes and reduce operator-dependent variability.
- Gastroenterology screening protocols:Population aging in Ontario and Quebec is expanding colonoscopy and esophagogastroduodenoscopy volumes in Canadian provinces.
Market Restraints
- Stainless steel and polymer input volatility:Medical-grade alloy pricing fluctuations are compressing margin structures for device manufacturers serving the United States market.
- Single-use scope substitution:Disposable bronchoscopes and colonoscopes are capturing low-acuity cases previously served by reusable flexible systems.
- FDA reprocessing validation timelines:Extended 510(k) clearance pathways for novel sterilization claims are delaying product launches by eighteen to twenty-four months.
Strategic Opportunities
- Mexico manufacturing expansion:Device assemblers are relocating final production to Baja California and Chihuahua to access United States tariff preferences under USMCA provisions.
- Software-defined visualization:Artificial intelligence-powered polyp detection algorithms are creating subscription revenue layers atop hardware deployments in academic medical centers.
- Capsule endoscopy for small-bowel:Underpenetrated diagnostic applications in Crohn's disease monitoring represent white space in Canadian provincial health systems.
Industry Challenges
- Sterilization technician certification:Shortages of qualified reprocessing staff are forcing United States hospitals to outsource high-level disinfection to third-party service providers.
- Legacy video processor incompatibility:Proprietary connector standards between scope generations are trapping capital in obsolete visualization platforms.
- Supply chain reconfiguration:Relocation of polymer sheath sourcing from Asia to North American suppliers is disrupting component availability for six to nine month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Endoscopy Devices Market |
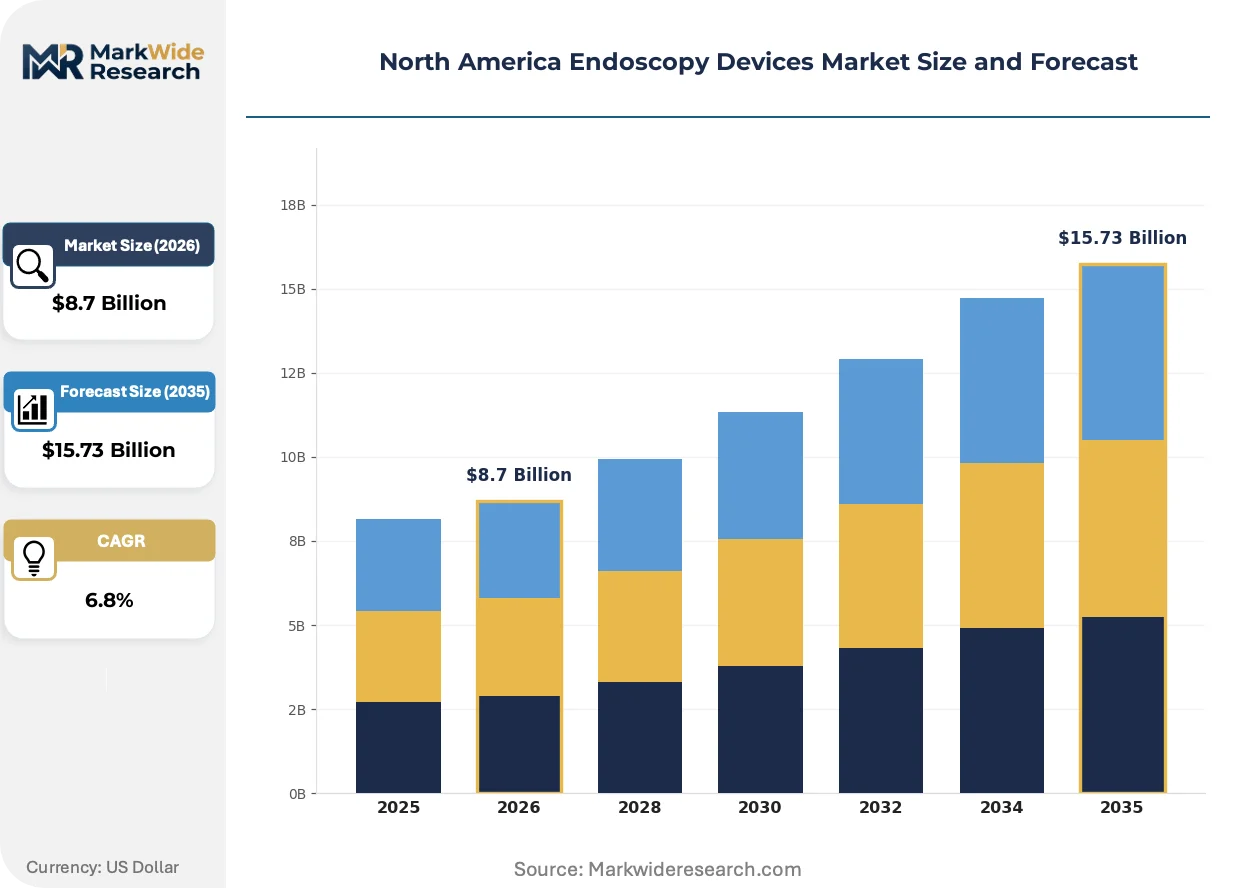
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsule Endoscopes, Flexible Endoscopes, Rigid Endoscopes, Endoscopic Ultrasound Technology: Video Endoscopy, Robot-assisted Endoscopy, Wireless Endoscopy, Image-enhanced Endoscopy End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Gastroenterology, Pulmonology, Urology, Gynecology |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Stryker Corporation, Karl Storz SE & Co. KG, Fujifilm Holdings Corporation, Ethicon Endo-Surgery LLC, Medtronic PLC, Cook Medical Incorporated, Hoya Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Endoscopy Devices Market Evolving Landscape
Digital image sensor migration from fiber-optic bundles is restructuring device architecture while artificial intelligence layers are embedding diagnostic capability directly into capture systems.
Single-use duodenoscopes are integrating disposable elevator mechanisms to eliminate cross-contamination vectors that plagued reusable designs in ERCP procedures. United States tertiary care centers are adopting these devices for high-risk patient populations despite per-procedure cost premiums. The technology is integrating infection prevention protocols into capital procurement criteria previously dominated by imaging resolution specifications.
The FDA's updated guidance on human factors testing for reusable device reprocessing is forcing manufacturers to redesign instruction-for-use documentation and validation protocols. Health Canada is harmonizing with these standards through parallel guidance documents affecting cross-border product submissions. Flexible endoscope vendors are responding by embedding radio-frequency identification chips to track sterilization cycle counts automatically.
Ambulatory surgical centers are consolidating purchasing through group procurement organizations to extract volume discounts from manufacturers previously reserved for integrated delivery networks. United States outpatient facilities are displacing individual hospital negotiations with multi-site contracting arrangements covering scopes, processors, and service contracts. This concentration is most visible in Texas and Florida where freestanding endoscopy center chains control regional procedure volume.
North America Endoscopy Devices Market Segmentation
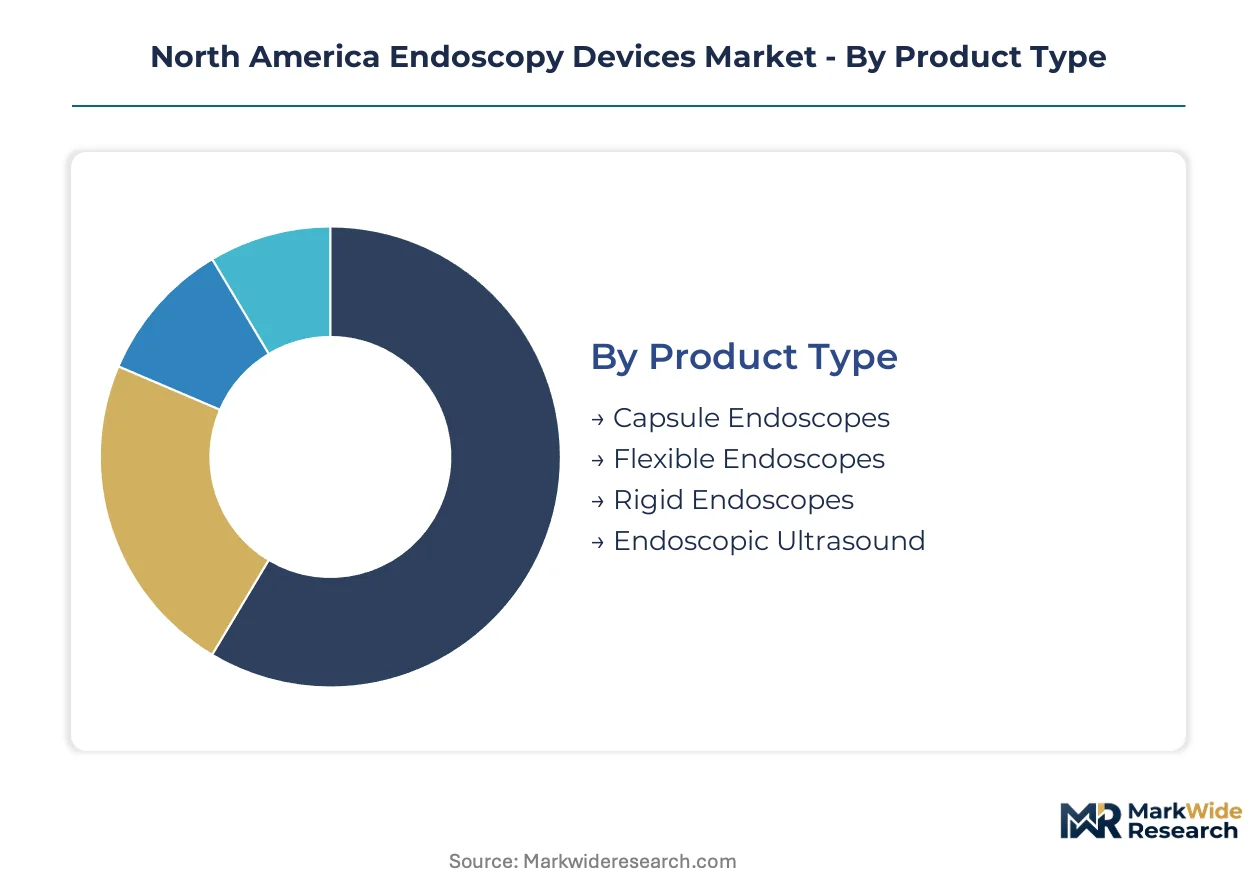
Endoscopy device procurement patterns diverge sharply across clinical settings and procedural requirements. Understanding these fault lines reveals where capital allocation concentrates and which technology layers command premium positioning.
Product Type:
Buyers differentiate primarily by reprocessing burden and procedural access depth, trading capital efficiency against infection risk exposure.
- Flexible Endoscopes:Fiber-optic or digital sensor-based systems with articulating distal tips navigate tortuous anatomical pathways. Demand concentrates in United States hospital systems performing high-volume colonoscopy and ERCP, where CMS reimbursement tiering for outpatient procedures is pulling diagnostic volume into ambulatory settings.
- Capsule Endoscopes:Swallowable wireless imagers with disposable shells eliminate cross-contamination risks entirely. Ontario and Quebec provincial health systems are expanding deployment for Crohn's disease monitoring where conventional scope access remains constrained by patient anatomy.
- Rigid Endoscopes:Stainless steel laparoscopic systems with rod-lens optics serve surgical suites requiring instrument stability.
- Endoscopic Ultrasound:Hybrid platforms combining optical visualization with radial or linear ultrasound probes for fine-needle aspiration.
Flexible endoscopes lead volumes today; capsule endoscopes are gaining share fastest.
Technology:
Procurement decisions pivot on whether institutions prioritize standardized outcomes through automation or maximize capital flexibility through modular upgrades.
- Video Endoscopy:Digital capture systems with CMOS or CCD sensors replacing fiber-optic bundles. United States academic medical centers are embedding artificial intelligence-powered polyp detection algorithms to create subscription revenue layers atop hardware deployments.
- Robot-assisted Endoscopy:Computer-navigated platforms with haptic feedback and tremor filtration. Health systems across Texas and Florida are deploying these systems to reduce operator-dependent variability in complex therapeutic procedures.
- Wireless Endoscopy:Radio-transmission systems enabling untethered patient mobility during prolonged small-bowel examination.
- Image-enhanced Endoscopy:Narrow-band imaging and linked-color imaging modalities for vascular pattern characterization.
Video endoscopy dominates installed base; robot-assisted platforms are expanding most quickly.
End User:
Facility type determines capital cycle timing, with reimbursement environment and procedure volume shaping equipment refresh rates.
- Hospitals:Integrated delivery networks with centralized sterile processing departments. FDA reprocessing validation timelines are compressing replacement cycles as extended 510(k) clearance pathways delay product launches by eighteen to twenty-four months.
- Ambulatory Surgical Centers:Freestanding facilities consolidating purchasing through group procurement organizations. Texas and Florida center chains are displacing individual hospital negotiations with multi-site contracting arrangements covering scopes, processors, and service contracts.
- Specialty Clinics:Gastroenterology and pulmonology focused practices with limited reprocessing infrastructure.
- Research Institutions:Academic centers piloting next-generation visualization protocols and training programs.
Hospitals retain the largest capital footprint; ambulatory surgical centers are climbing the fastest.
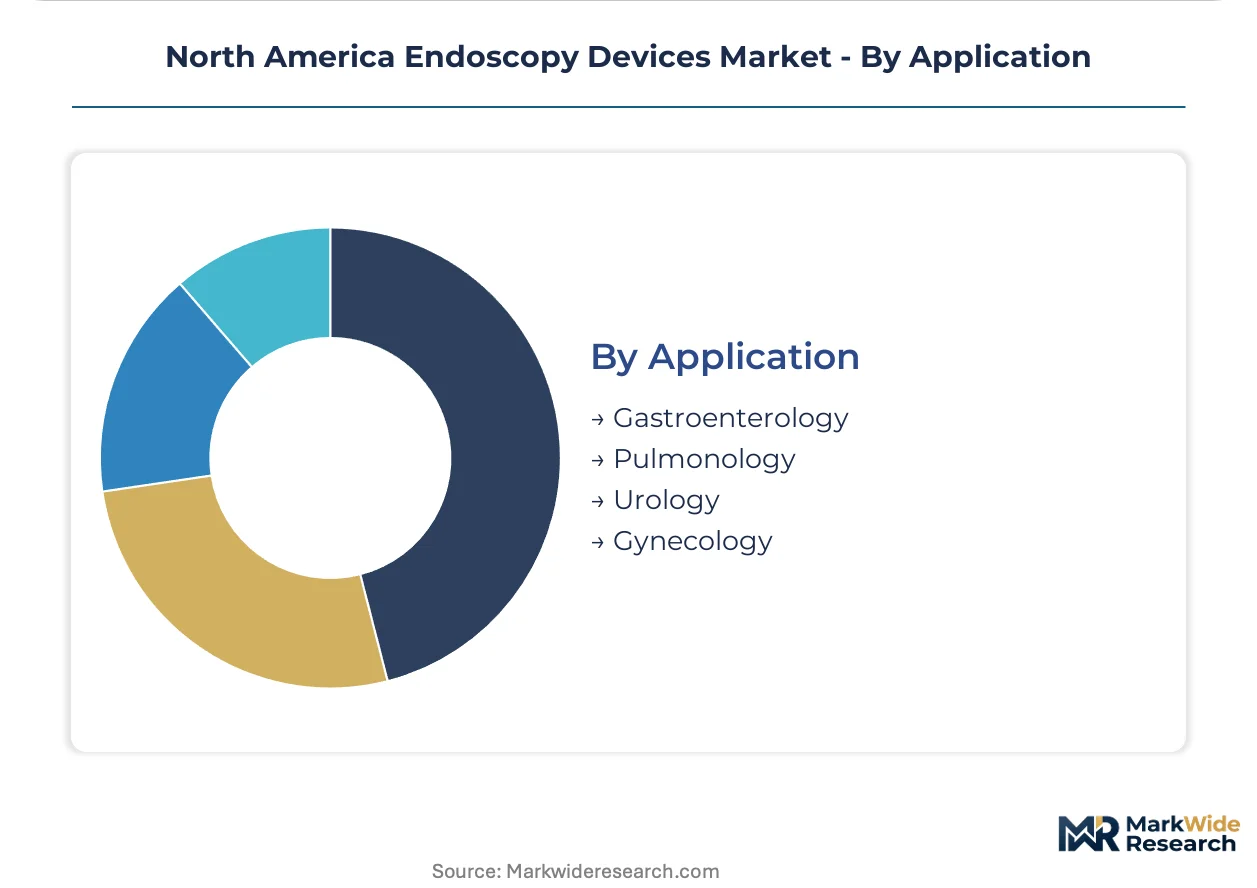
Application:
Clinical specialty dictates device specification, with anatomical access constraints and reimbursement codes driving modality selection.
- Gastroenterology:Upper and lower GI tract examination representing the procedural volume anchor. Population aging in Ontario and Quebec is expanding colonoscopy and esophagogastroduodenoscopy volumes in Canadian provinces.
- Pulmonology:Bronchoscopic airway assessment and intervention. Single-use bronchoscopes are capturing low-acuity cases previously served by reusable flexible systems in United States outpatient settings.
- Urology:Cystoscopic and ureteroscopic procedures for stone and tumor management.
- Gynecology:Hysteroscopic evaluation and operative intervention.
Gastroenterology leads procedural volume; pulmonology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States absorbs the majority of capital deployment in endoscopy devices, while Canadian provincial health systems are expanding screening protocols at a faster clip. Mexico's manufacturing clusters are capturing final assembly work previously concentrated in Asian facilities.
United States
CMS reimbursement tiering for outpatient endoscopic procedures is pulling diagnostic volume into ambulatory surgical centers across Texas and Florida. The FDA's updated reprocessing guidance for flexible endoscopes is elevating product standards and compressing replacement cycles. Boston Scientific Corporation and Olympus Corporation anchor installed base positions through proprietary service contracts in hospital systems.
Canada
Population aging in Ontario and Quebec is expanding colonoscopy and esophagogastroduodenoscopy volumes in provincial health systems. Health Canada is harmonizing with FDA sterilization standards through parallel guidance documents affecting cross-border product submissions. Toronto and Montreal academic medical centers are piloting artificial intelligence-powered polyp detection algorithms.
Mexico
Device assemblers are relocating final production to Baja California and Chihuahua to access United States tariff preferences under USMCA provisions. The national pharmaceutical regulator enforces safety standards that shape cross-border product specifications for re-export markets. Tijuana and Ciudad Juárez industrial parks are absorbing sterilization infrastructure investments from multinational manufacturers.
North America Endoscopy Devices Market Competitive Landscape
Top-tier vendors anchor the premium visualization and robotics segment, while mid-tier specialists compete on reprocessing efficiency and ambulatory surgical center service contracts. The vendor base stratifies across three archetypes: integrated imaging platforms, disposable scope innovators, and dedicated technical field service organizations. Consolidation pressure is intensifying as hospitals outsource sterilization operations to third-party providers. Dominant competitive moves include strategic partnerships for AI algorithm integration and geographic expansion into Mexican manufacturing zones.
Within the integrated platform tier, Olympus Corporation and Boston Scientific Corporation exemplify contrasting approaches to installed base retention. Olympus Corporation sustains hospital customers through proprietary image-processing subscriptions that lock in visualization ecosystem loyalty. Boston Scientific Corporation occupies a position emphasizing dedicated technical field teams to control replacement-part revenue streams across ambulatory surgical centers. Stryker Corporation represents the diversified conglomerate archetype, sitting within a broader surgical instrumentation portfolio that cross-sells endoscopy capabilities.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Stryker Corporation |
| Karl Storz SE & Co. KG |
| Fujifilm Holdings Corporation |
| Ethicon Endo-Surgery LLC |
| Medtronic PLC |
| Cook Medical Incorporated |
| Hoya Corporation |
| Others |
Value Network & Pricing Analysis
Medical-grade stainless steel and polymer sheath pricing volatility travels from raw material spot markets through OEM procurement tiers into hospital capital budgets and ambulatory surgical center leasing rates. Input cost swings compress margin structures for device manufacturers while amplifying price sensitivity among outpatient facilities consolidating through group procurement organizations.
Pricing Analysis
Capacity additions in Mexican manufacturing zones are reshaping price floors for flexible endoscope assemblies bound for United States hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates robot-assisted platforms with AI subscriptions from modular video systems and entry-level fiber-optic bundles. Cost compression in the standard tier is intensifying because single-use scope substitution captures low-acuity cases previously served by reusable systems. Ambulatory surgical centers exhibit highest price sensitivity due to thin reimbursement margins, while academic medical centers prioritize image-enhanced capabilities over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Asian polymer compounders supplying medical-grade sheath materials for flexible endoscope manufacturers. Final assembly draws from Mexico, China, and Japan, with sterilization infrastructure components sourced from Germany and the United States. Tariff exposure under USMCA rules of origin creates compliance friction for cross-border component flows. Distribution runs through group procurement organizations consolidating ambulatory surgical center demand in Texas and Florida, alongside direct hospital system contracts for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA reprocessing validation mandates accelerate replacement cycles and elevate capital requirements across United States hospital systems.
For Market Incumbents: Extend proprietary service contract coverage to lock in visualization ecosystem loyalty against disposable scope substitution threats. Deepen backward integration into sterilization infrastructure to capture recurring revenue from hospitals outsourcing high-level disinfection to third-party providers. Prioritize certification investment for AI-powered polyp detection algorithms creating subscription layers atop hardware deployments. For New Entrants and Emerging Players: Group procurement organizations represent the most penetrable channel for ambulatory surgical center access, bypassing entrenched hospital system relationships. Target capsule endoscopy white space in Canadian provincial health systems for Crohn's disease monitoring where conventional scope access remains constrained. Pursue software-defined visualization partnerships with academic medical centers piloting next-generation diagnostic protocols. For Investors and Strategic Acquirers: Roll-up economics work for technical field service organizations because sterilization technician shortages force United States hospitals to outsource reprocessing operations. Long-term viability centers on platforms with installed base retention mechanisms spanning hardware, software subscriptions, and consumable lock-in. Watch FDA 510(k) clearance velocity as the signal indicating whether extended validation timelines compress or expand replacement cycle opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Accelerates market access for novel sterilization claims in United States hospital systems. |
| Hospital System Partnership | Locks in multi-year service contracts covering scopes, processors, and technical field support. |
| Software Companion Development | Creates recurring subscription revenue atop hardware through AI-powered polyp detection algorithms. |
| Reimbursement Strategy | Aligns product positioning with CMS tiering for outpatient endoscopic procedures in ambulatory settings. |
| CE Marking Pathway | Enables cross-border product submissions into Health Canada harmonized standards. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market cluster combined with secondary validation. Interviews with hospital purchasing committees, GPO contracts managers, biomedical engineers, and sterilization technicians informed demand-side dynamics. Secondary sources include FDA 510(k) filings, Health Canada guidance documents, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up and top-down triangulation reconciled facility-level capital expenditure patterns against manufacturer shipment data.
Granularity-level modeling captured product type, technology layer, end-user facility, and clinical application dimensions across the projection horizon. CAGRs derived from procedure volume trajectories, replacement cycle compression effects, and technology substitution curves. Forecast inputs incorporated FDA reprocessing validation timeline assumptions, CMS reimbursement tiering evolution, and USMCA tariff preference utilization rates for Mexican assembly operations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to single-use scope substitution velocity and sterilization technician labor availability. Projections reflect assumptions about regulatory harmonization between FDA and Health Canada, supply chain reconfiguration timelines, and AI algorithm adoption curves in academic medical centers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Global Endoscope Reprocessing Market