
 Endoscopic Stricture Management Market | 2026-2036
Endoscopic Stricture Management Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Stricture Management Market Foresight
Germany is narrowing its reliance on imported endoscopic stricture devices through expanded domestic catheter manufacturing. Boston Scientific Corporation leverages its integrated balloon dilator production to anchor European supply chains. Olympus Corporation sustains its endoscope-dilator bundling strategy across Japanese hospital systems. Cook Medical differentiates through physician training programs tied to stricture management protocols.
Endoscopic stricture management encompasses minimally invasive techniques to restore luminal patency in narrowed gastrointestinal, biliary, or urological tracts using balloon dilation, stent deployment, or thermal ablation with controlled radial force application. Balloon dilators command the largest product segment due to reusable cost advantages in high-volume centers, while radiofrequency ablation represents the fastest-growing technology segment driven by its efficacy in refractory esophageal strictures. Stents capture concentrated margin pools in malignant stricture applications where covered metal designs reduce reintervention rates.
The FDA regulates these devices under Class II 510(k) premarket notification requirements with predicate-based substantial equivalence determinations, while the EU Medical Device Regulation mandates clinical evaluation reports and notified body conformity assessments for stent and dilator placements. Japan's PMDA enforces QMS inspections and post-market surveillance for endoscopic accessories, creating compliance barriers for non-domestic manufacturers. Stakeholders must monitor evolving reimbursement thresholds for outpatient stricture dilation versus inpatient stent revision across Medicare, NHS England, and Japan's MHLW fee schedules.
Market Dynamics
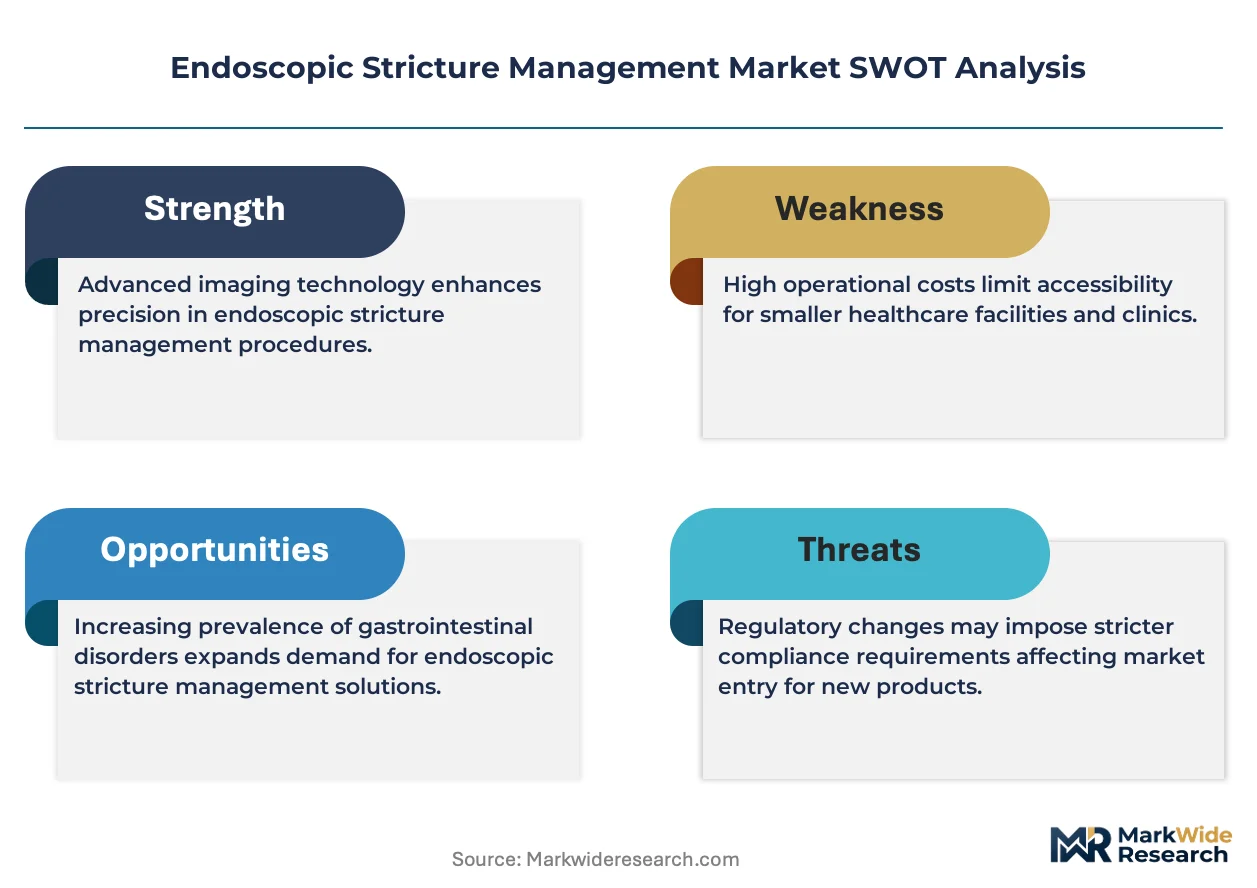
Balloon dilator reusability is compressing per-procedure costs in high-volume centers, while radiofrequency ablation systems are displacing repeat mechanical dilation for refractory strictures. This cost-efficacy tension between capital-intensive thermal platforms and consumable-heavy mechanical tools is reshaping procurement patterns across hospital systems.
Growth Catalysts
- Japan's MHLW reimbursement expansion:Outpatient dilation procedures now carry enhanced fee schedules, accelerating same-day discharge protocols in Tokyo and Osaka metropolitan hospitals.
- Radiofrequency ablation efficacy:Thermal remodeling of fibrotic strictures reduces reintervention frequency by half compared to balloon dilation alone in refractory esophageal cases.
- Interventional gastroenterology department buildouts:German hospital systems are adding dedicated stricture management suites with integrated imaging and dilation capabilities.
Market Restraints
- Reusable balloon degradation:Silicone fatigue limits dilator lifespan to 15-20 procedures, creating unpredictable replacement cycles and sterilization validation costs.
- PMDA QMS inspection barriers:Foreign manufacturers face 18-24 month facility audit queues before Japanese market entry, privileging domestic incumbents.
- Biodegradable stent material costs:Polydioxanone and polylactic acid feedstocks carry 3-4x premium over conventional nitinol, constraining adoption in cost-sensitive settings.
Strategic Opportunities
- India's underserved stricture burden:Corrosive ingestion injuries create substantial untreated demand; CDSCO's streamlined Class B device pathway reduces 510(k)-equivalent timelines.
- Stent-dilator bundling:Single-procedure kits combining diagnostic endoscopy, dilation, and provisional stenting capture margin pools currently fragmented across separate SKUs.
- AI-enabled stricture assessment:Computer vision integration with endoscopic systems automates fibrosis grading and dilation endpoint determination.
Industry Challenges
- Interventional endoscopist training pipelines:Fellowship programs produce insufficient operators for expanding stricture volumes, particularly for advanced thermal ablation techniques.
- EU MDR clinical evaluation requirements:Legacy stent predicates face retrospective data gaps, forcing expensive prospective studies for renewed CE marking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Stricture Management Market |
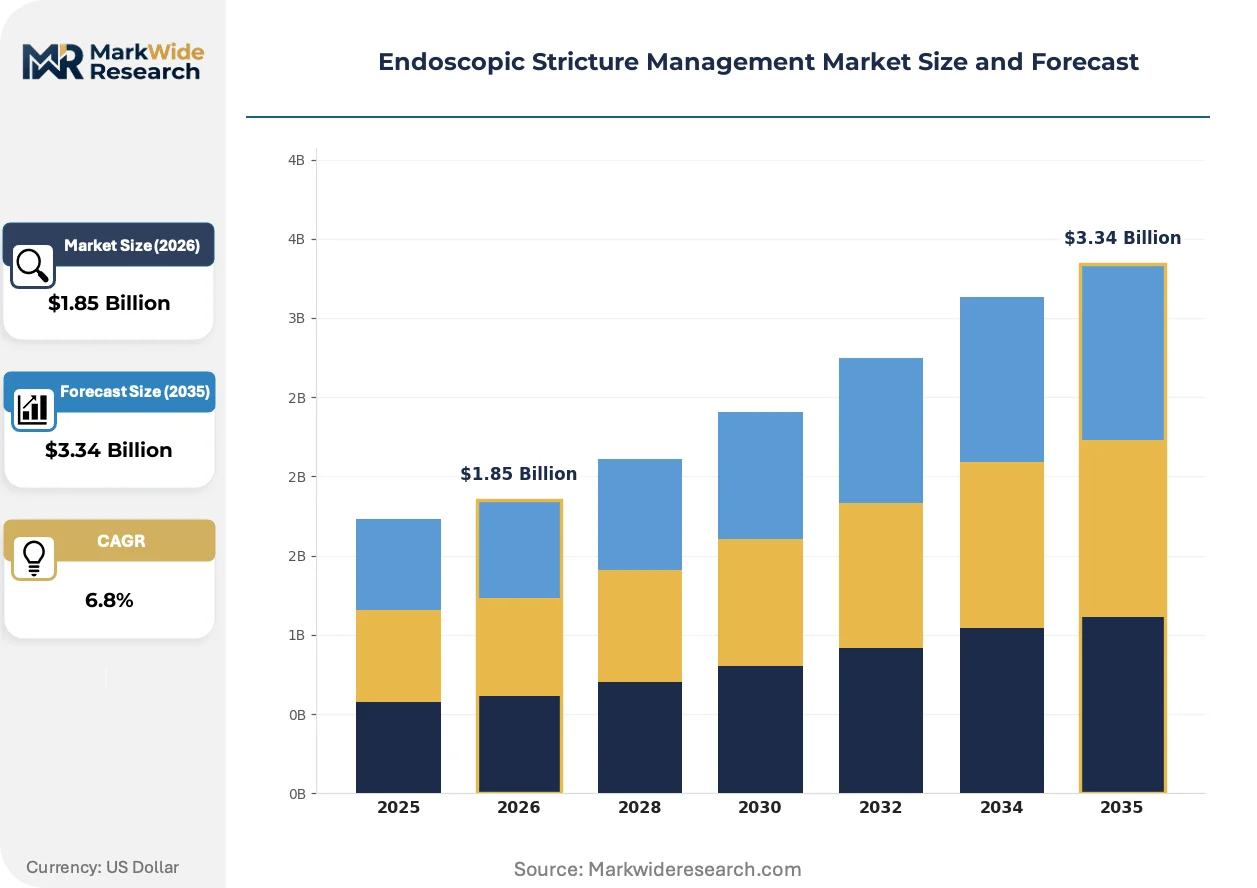
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Dilators, Stents, Electrodes, Accessories End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Endoscopic Ultrasound, Laser Therapy, Radiofrequency Ablation, Imaging Techniques Application: Esophageal Strictures, Gastrointestinal Strictures, Biliary Strictures, Urological Strictures |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Cook Medical, Merit Medical Systems, CONMED Corporation, Becton, Dickinson and Company, Medi-Globe GmbH, Hobbs Medical, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Stricture Management Market Shifts & Advancements
Digital integration is penetrating endoscopic stricture workflows, from AI-assisted stricture characterization to connected dilator systems that log procedural parameters. This shift is compressing variation in clinical outcomes while generating data assets for outcome-based contracting.
Electrosurgical stricturotomy systems equipped with impedance-sensing feedback are digitizing procedural decision-making. Academic medical centers in the US and Germany are piloting these platforms for complex anastomotic strictures. The technology is digitizing the threshold between mechanical dilation and surgical revision, expanding the treatable patient pool.
The EU Medical Device Regulation's post-market surveillance mandates are forcing stent manufacturers to maintain active implant registries. This surveillance burden falls disproportionately on smaller nitinol fabricators without existing quality management infrastructure. Covered metal esophageal stents face the steepest compliance cost escalation.
Japanese hospital procurement committees are consolidating stricture device purchasing through GPO-affiliated tender platforms. This concentration is displacing direct manufacturer relationships that previously enabled premium pricing for bundled endoscope-dilator systems. The shift is most pronounced in Kanto and Kansai regional hospital alliances.
Endoscopic Stricture Management Market Segmentation
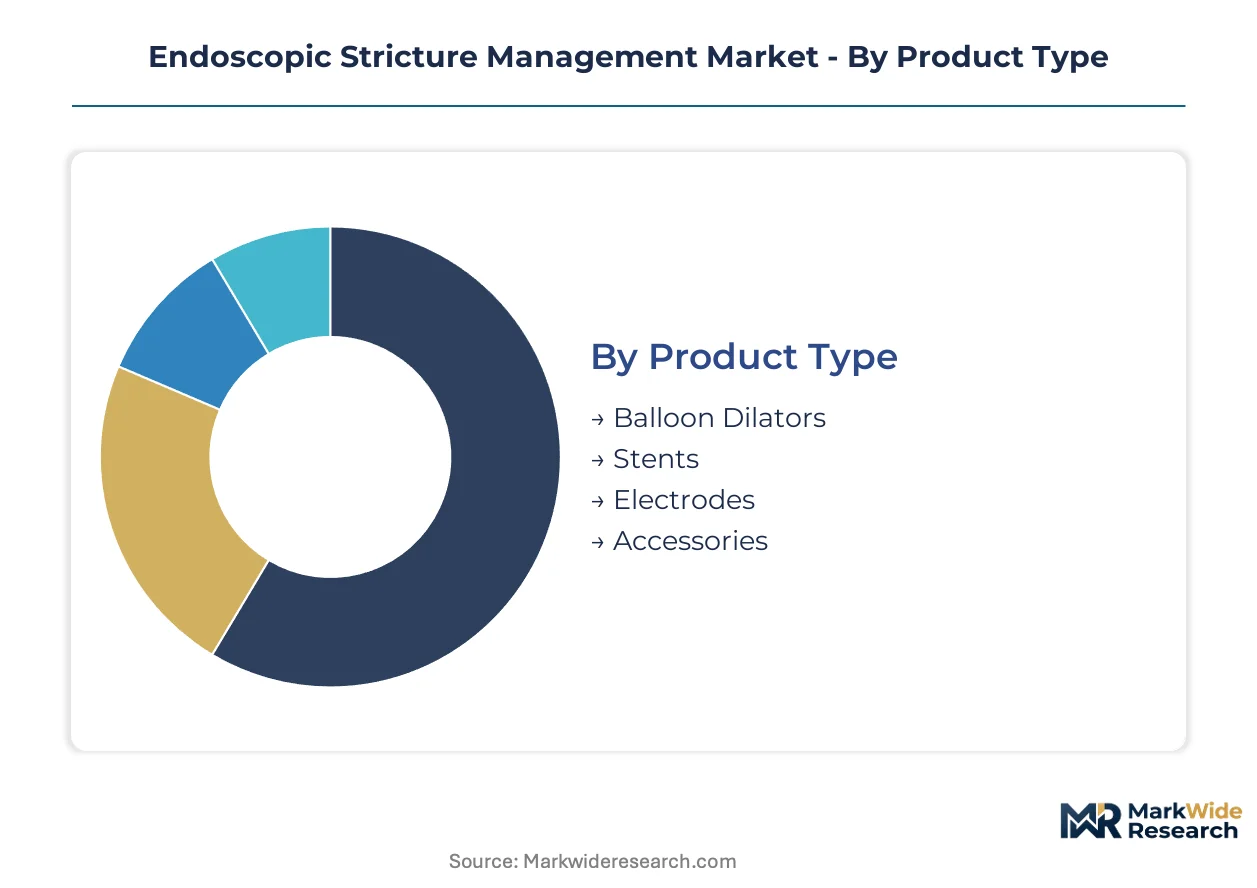
Endoscopic stricture management devices serve distinct clinical workflows ranging from emergency dilation to elective stent revision. Segmentation reveals how procurement patterns split between capital-intensive thermal platforms and high-volume consumable tools across acute and ambulatory settings.
Product Type:
Mature mechanical platforms anchor hospital purchasing while emerging thermal systems capture premium positioning in refractory cases.
- Balloon Dilators:Silicone and polyurethane balloons deliver controlled radial force through endoscopic channels for graded luminal expansion. Demand concentrates in German interventional gastroenterology suites where reusable designs compress per-procedure costs below thermal alternatives. Silicone fatigue limits lifespan to 15-20 procedures, creating unpredictable replacement cycles.
- Stents:Self-expanding metal and plastic designs maintain patency in malignant strictures where covered nitinol reduces tissue ingrowth and reintervention frequency. Japanese hospital procurement committees favor covered esophageal stents for same-day discharge protocols under expanded MHLW reimbursement.
- Electrodes:Impedance-sensing electrosurgical tips enable precision stricturotomy with real-time tissue feedback during complex anastomotic revisions.
- Accessories:Guidewires, retrieval nets, and irrigation pumps complete procedural kits across dilation and stent deployment workflows.
Balloon dilators retain volume leadership across high-throughput centers; radiofrequency ablation electrodes hold the steepest expansion curve in refractory stricture management.
End User:
Facility reimbursement tiers and case complexity stratify device selection across inpatient and outpatient channels.
- Hospitals:Comprehensive interventional gastroenterology departments manage complex malignant strictures and emergency corrosive injury cases requiring multimodal dilation-stent sequences. German hospital systems are adding dedicated stricture management suites with integrated imaging capabilities.
- Ambulatory Surgical Centers:Same-day dilation procedures for benign esophageal strictures operate under streamlined protocols with disposable balloon platforms. Tokyo and Osaka metropolitan ASCs benefit from Japan's MHLW outpatient fee schedule expansion.
- Specialty Clinics:Gastroenterology-focused practices perform diagnostic endoscopy with provisional dilation for early stricture detection.
- Research Laboratories:Academic centers pilot electrosurgical stricturotomy systems and AI-enabled fibrosis grading for complex anastomotic strictures.
Hospitals command the deepest procedure volumes; ambulatory surgical centers are climbing the fastest as reimbursement shifts favor same-day discharge.
Technology:
Imaging modalities and energy delivery systems compete for integration into next-generation endoscopic platforms.
- Radiofrequency Ablation:Thermal remodeling of fibrotic strictures via controlled bipolar energy reduces reintervention frequency by half compared to mechanical dilation alone in refractory esophageal cases. US and German academic centers pilot impedance-sensing feedback systems for complex anastomotic strictures.
- Endoscopic Ultrasound:High-frequency imaging enables transmural stricture characterization and adjacent tissue assessment prior to dilation or stent deployment.
- Laser Therapy:Nd:YAG and diode laser systems recanalize obstructed metal stents and cut refractory fibrotic bands.
- Imaging Techniques:Narrow-band imaging and chromoendoscopy enhance mucosal visualization for stricture margin delineation.
Radiofrequency ablation systems retain the premium positioning; endoscopic ultrasound integration is gaining share fastest through platform bundling strategies.
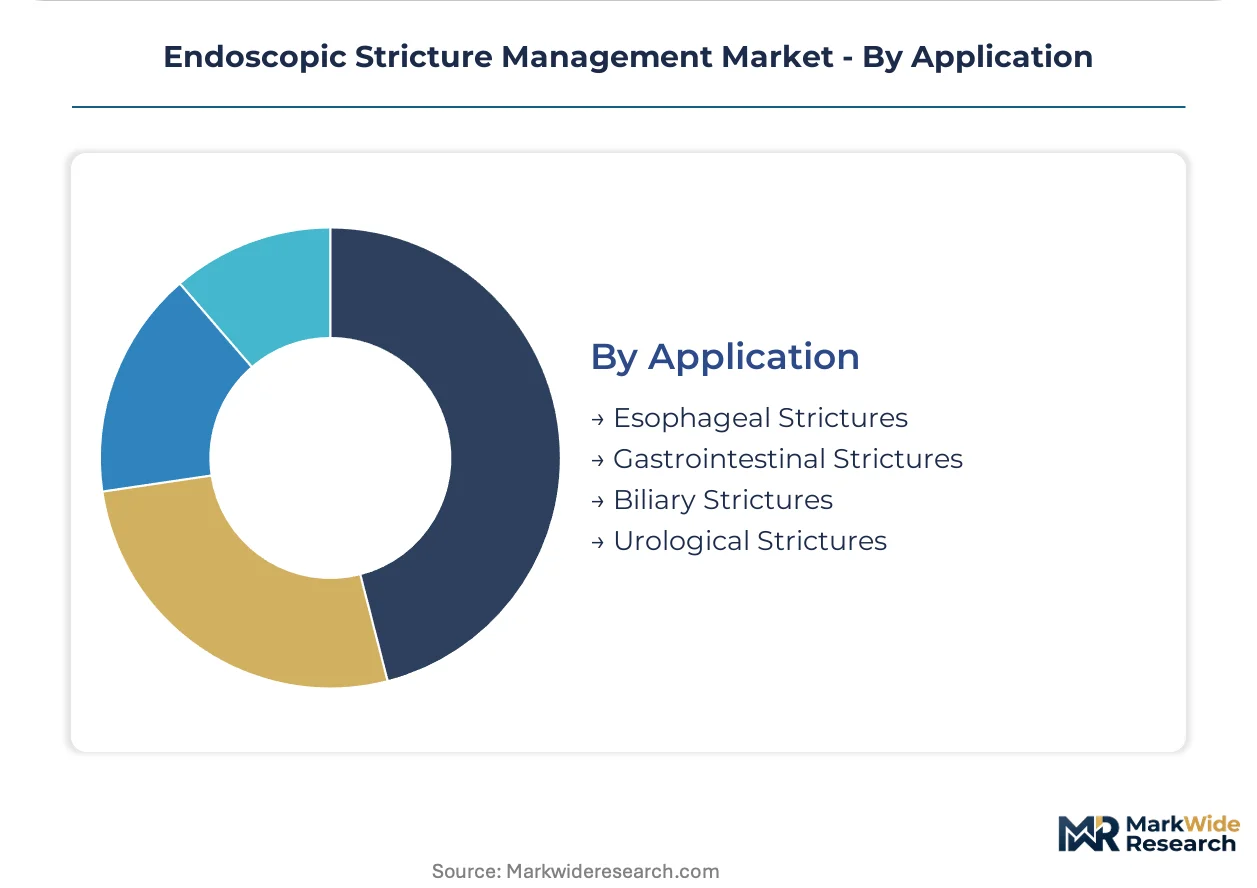
Application:
Anatomical site determines device selection based on stricture etiology, malignant potential, and procedural access difficulty.
- Esophageal Strictures:Peptic, radiation-induced, and anastomotic narrowings constitute the highest procedure volume, with balloon dilation as first-line therapy and covered metal stents for refractory or malignant cases. Japan's aging population drives concentrated demand for corrosive injury and malignancy-related strictures.
- Biliary Strictures:Malignant hilar obstruction and post-surgical anastomotic narrowings require specialized plastic or metal stents with side-hole configurations for ductal drainage.
- Gastrointestinal Strictures:Gastric outlet and duodenal obstructions from malignancy or ulcer disease deploy through-the-scope balloon dilators and enteral stents.
- Urological Strictures:Ureteral and urethral narrowings utilize specialized balloon systems with fluoroscopic guidance distinct from GI endoscopy workflows.
Esophageal applications retain volume leadership; biliary stricture management holds the steepest expansion curve through interventional hepatobiliary program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's QMS inspection protocols create the steepest compliance gradient for foreign manufacturers seeking Japanese market entry. Germany's interventional gastroenterology expansion and India's streamlined CDSCO pathways for Class B devices complete the tripartite regulatory landscape shaping regional access.
United States
FDA's updated 510(k) pathway accelerates predicate-based clearances for balloon dilators and radiofrequency ablation systems. Academic medical centers in Boston and North Carolina pilot impedance-sensing electrosurgical stricturotomy platforms. The outpatient reimbursement differential under Medicare favors ambulatory surgical center dilation protocols.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia add dedicated stricture management suites with integrated imaging capabilities. EU MDR clinical evaluation requirements force retrospective data compilation for legacy stent predicates. Domestic catheter manufacturing narrows import dependence through expanded production in Baden-Württemberg.
Japan
Aging demographics concentrate esophageal stricture demand in Tokyo and Osaka metropolitan hospital alliances. MHLW outpatient fee schedule expansion accelerates same-day discharge protocols. PMDA facility audit queues extend 18-24 months for foreign manufacturers, privileging domestic incumbents in Kanto and Kansai regional tenders.
India
Corrosive ingestion injuries create substantial untreated stricture burden across Maharashtra and Gujarat. CDSCO's streamlined Class B device pathway reduces 510(k)-equivalent timelines for balloon dilator registration. Delhi-NCR and Karnataka hospital networks build interventional gastroenterology capacity for elective stricture management.
United Kingdom
NHS England reimbursement thresholds differentiate outpatient dilation from inpatient stent revision procedures. London and Southeast England academic centers participate in EU MDR transition studies for covered metal esophageal stents. Procurement consolidation across hospital trusts compresses pricing for mechanical dilation platforms.
Endoscopic Stricture Management Market Competitive Landscape
Capability concentration sits with integrated endoscope-dilator bundlers; scale advantage sits with diversified interventional portfolio holders. The vendor base stratifies across three tiers: multinational platform conglomerates with full stricture workflows, mid-cap catheter specialists with regional manufacturing footprints, and niche electrosurgical innovators targeting refractory case segments. Dominant competitive moves include strategic partnerships for AI-enabled stricture assessment and backward integration into nitinol and polymer feedstocks.
Within the integrated platform tier, Boston Scientific Corporation and Olympus Corporation exemplify divergent geographic anchoring strategies. Boston Scientific's Massachusetts-based structure positions it within FDA-cleared 510(k) pathways for balloon dilator production. Olympus Corporation represents Japanese incumbent advantages under PMDA's QMS inspection regime. Cook Medical occupies a specialist position among Indiana-based fabricators with physician training program differentiation.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Cook Medical |
| Merit Medical Systems |
| CONMED Corporation |
| Becton, Dickinson and Company |
| Medi-Globe GmbH |
| Hobbs Medical |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's catheter manufacturing cluster compresses procurement timelines for German hospital systems while amplifying pricing leverage against Asian imports. Nitinol wire and silicone balloon feedstock costs propagate through device pricing tiers, with domestic fabrication commanding premiums against offshore alternatives.
Pricing Analysis
Price spreads between Japanese domestic and European-imported balloon dilators exceed standard freight differentials due to PMDA compliance premiums. Three-tier pricing structure across premium, standard, and economy levels segments by sterilization validation depth and reuse certification. Pricing pressure stems from GPO-affiliated tender consolidation in Kanto and Kansai hospital alliances. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize thermal platform efficacy over unit cost.
Supply Chain Analysis
Tariff exposure between US and Chinese nitinol suppliers dominates supply chain risk calculations for stent fabricators. Manufacturing concentrates in Massachusetts, Tokyo-Osaka corridor, and Baden-Württemberg. Polydimethylsiloxane and polylactic acid feedstocks draw from specialty chemical producers in Germany and Japan. Single-source vulnerability persists for impedance-sensing electrosurgical components. Distribution runs through GPO-contracted medical device distributors and direct hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscopic stricture management is entering a cyclical recovery phase as deferred procedures from supply chain disruptions resume and MHLW reimbursement expansion unlocks pent-up demand in Japanese metropolitan hospitals.
For Market Incumbents: Harden quality management infrastructure against EU MDR post-market surveillance mandates by maintaining active implant registries for covered metal esophageal stents. Deepen backward integration into nitinol and polymer feedstocks to defend margin position against biodegradable material cost premiums. Prioritize physician training program expansion to offset interventional endoscopist pipeline constraints threatening procedure volume growth. For New Entrants and Emerging Players: Build out interventional gastroenterology capacity in Maharashtra and Gujarat hospital networks where corrosive ingestion injuries create substantial untreated stricture burden. India's CDSCO streamlined Class B device pathway offers the most penetrable regulatory entry point. Lead with disposable balloon platforms targeting cost-sensitive ambulatory settings before scaling to thermal ablation systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrosurgical innovators with impedance-sensing feedback capabilities and AI-enabled stricture assessment platforms. Long-term viability rests on outcome-based contracting readiness and data asset generation for hospital system partnerships. Monitor FDA 510(k) clearance velocity for radiofrequency ablation systems as the primary inflection indicator for thermal platform adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled endoscope-dilator procurement contracts with Kanto regional alliances secure volume commitments against GPO displacement. |
| CE Marking Pathway | EU MDR clinical evaluation reports for legacy stent predicates enable continued market access across German hospital networks. |
| Software Companion Development | AI-enabled fibrosis grading integration with Olympus endoscopic platforms automates dilation endpoint determination. |
| Reimbursement Strategy | MHLW outpatient fee schedule positioning accelerates same-day discharge protocols in Tokyo metropolitan ASCs. |
| FDA Submission | Predicate-based 510(k) clearances for radiofrequency ablation systems anchor US academic medical center adoption. |
Research Methodology
Initial hypotheses were tested against primary input from interventional gastroenterologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation. Stakeholder interviews combined with FDA 510(k) filings, PMDA QMS inspection records, MHLW reimbursement schedules, and EU MDR clinical evaluation reports. Bottom-up procedure volume estimates triangulated against top-down device shipment data from Massachusetts, Tokyo-Osaka, and Baden-Württemberg manufacturing clusters.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by balloon dilator, stent, and thermal platform categories alongside end user splits between hospitals and ambulatory surgical centers. CAGRs derived from procedure volume growth rates, device replacement cycles, and technology substitution curves. Forecast inputs included PMDA facility audit queue durations, EU MDR transition timelines, and MHLW fee schedule revision patterns.
Sensitivities concentrate around reimbursement threshold revisions, interventional endoscopist training pipeline expansion rates, and biodegradable stent material cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Global Endoscopes Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Endoscopy Device Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Endotherapy Devices Market
Endoscopy
China Arthroscopy Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Endoscopy Visualization Systems Market