
 Europe Spinal Surgery Devices Market | 2026-2036
Europe Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Spinal Surgery Devices Market Foresight
Hospital procurement networks across Europe is fragmenting as ambulatory surgical centers and specialty clinics gain direct purchasing power for spinal implants and instruments. Medtronic leverages its broad European distribution footprint to sustain implant volume across multiple countries. DePuy Synthes competes through specialized instrument portfolios that anchor surgeon loyalty in key orthopedic centers. Stryker differentiates via navigation and robotic surgery platforms that command premium positioning in high-volume German and French hospitals.
Spinal surgery devices encompass implantable hardware, specialized instruments, neuromodulation systems, and biologic grafts designed to stabilize vertebrae, decompress neural elements, or correct structural deformities, typically manufactured from titanium alloys, polyetheretherketone, or bone graft substitutes with precision tolerances below 50 micrometers. Implants and surgical instruments constitute the mature revenue core where pricing pressure from procurement consortiums compresses margins, while robotic surgery and navigation systems represent the fastest-expanding technology segment as capital investment cycles accelerate. Biologics occupies a concentrated margin pool where synthetic bone graft substitutes and cellular matrices command premium reimbursement in deformity correction and trauma repair applications.
The EU Medical Device Regulation and CE marking framework enforce stricter clinical evidence requirements for spinal implants, extending approval timelines and elevating compliance costs for manufacturers seeking European market access. EMA coordination with notified bodies shapes post-market surveillance obligations that influence product redesign cycles and liability exposure. Germany's Federal Institute for Drugs and Medical Devices operates national reimbursement assessments that directly determine hospital purchasing capacity for premium spinal technologies. Stakeholders must monitor evolving notified body capacity constraints and national health technology appraisal divergence across France, Germany, and Italy to anticipate access bottlenecks and pricing fragmentation.
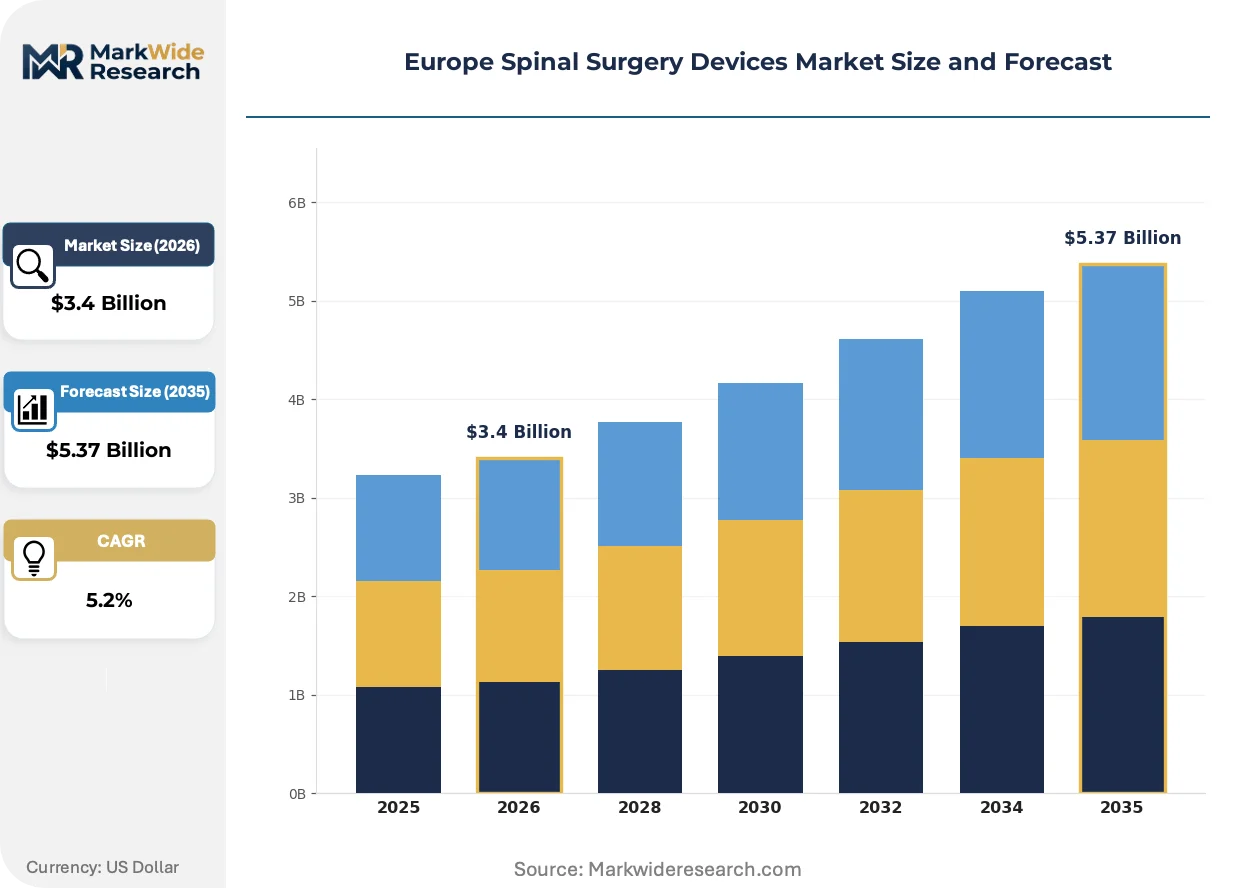
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines and elevating clinical evidence requirements for implantable spinal hardware, forcing manufacturers to redesign product portfolios and consolidate notified body relationships ahead of stricter conformity assessments.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding spine clinics in Germany and France are procuring implants directly, bypassing traditional hospital procurement networks and accelerating procedural volume.
- EU MDR transition:Stricter CE marking pathways for Class III implantable devices are filtering out marginal competitors and concentrating market share among well-capitalized manufacturers with established quality management systems.
- Titanium additive manufacturing:Powder-bed fusion techniques enable patient-specific interbody cages with porous architectures that accelerate osseointegration in deformity correction procedures.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical-grade titanium sponge production clusters in China and Russia expose European device manufacturers to raw material availability shocks and price volatility.
- Notified body capacity scarcity:Only twelve designated bodies currently handle MDR spinal implant certifications, creating application backlogs that delay product launches by eighteen to thirty months.
- Polyetheretherketone substitution limits:Radiolucent PEEK interbody devices face reimbursement skepticism from German statutory health insurers questioning long-term fusion outcomes versus titanium alternatives.
Strategic Opportunities
- Polish and Romanian hospital privatization:Greenfield orthopedic centers in Warsaw and Bucharest lack legacy vendor relationships, creating first-mover access for implant manufacturers with bundled instrument-and-implant offerings.
- Navigation-robotic convergence:Integration of optical tracking with autonomous drilling platforms enables single-position lateral surgery workflows that reduce operative time and anesthesia exposure.
- Biologics reimbursement expansion:Synthetic bone graft substitutes and cellular matrices command premium add-on payments in France's diagnosis-related group system for trauma and tumor reconstruction cases.
Industry Challenges
- Spine surgeon training pipeline constraints:Fellowship positions in complex deformity and minimally invasive techniques remain scarce across German and Italian academic medical centers, limiting adoption of advanced navigation platforms.
- Legacy hospital information system integration:Robotic surgery platforms require real-time data exchange with proprietary electronic health record architectures, forcing costly middleware development for each deployment site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Spinal Surgery Devices Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Neuromodulation Devices, Biologics End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Technology: Minimally Invasive Surgery, Robotic Surgery, Navigation Systems, Imaging Techniques Application: Deformity Correction, Degenerative Disc Disease, Tumor Ablation, Trauma Repair |
| Companies Covered | Medtronic, DePuy Synthes, Stryker, Globus Medical, NuVasive, Zimmer Biomet, Orthofix, Alphatec Spine, ZimVie, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Spinal Surgery Devices Market Shifts & Advancements
Spinal surgery technology is migrating toward integrated ecosystems where hardware, software, and service components lock in surgeon preference and compress standalone implant margins. Three concurrent developments are reshaping competitive positioning across European markets.
Robotic guidance platforms are migrating from capital-intensive hospital installations toward modular, procedure-specific subscriptions that ambulatory surgical centers can amortize per case. German and French high-volume spine centers are piloting these flexible acquisition models to preserve balance sheet capacity for EU MDR compliance investments. The structural consequence is a compression in traditional capital equipment sales cycles and a forced pivot toward recurring revenue architectures among established instrument manufacturers.
CE marking under the EU Medical Device Regulation now demands prospective clinical data for novel implantable spinal devices, elevating post-market surveillance obligations and extending technical documentation requirements. Manufacturers must maintain systematic literature reviews and periodic safety update reports that notify competent authorities of adverse event patterns. Small and mid-sized implant developers without dedicated regulatory affairs infrastructure face exclusion from premium deformity and trauma segments where clinical evidence requirements are most stringent.
Hospital purchasing consortiums in the Netherlands and Belgium are consolidating implant procurement across multiple surgical specialties, extracting volume-based discounts that erode list-price premiums for navigation-enabled procedures. Spine-specific procurement teams are ceding authority to centralized medical device committees that evaluate total cost of ownership across orthopedic, trauma, and neurosurgical applications. This concentration is most visible in Belgian academic hospital networks, where standardized implant menus now cover cervical, thoracic, and lumbar applications from single-source contracts.
Europe Spinal Surgery Devices Market Segmentation
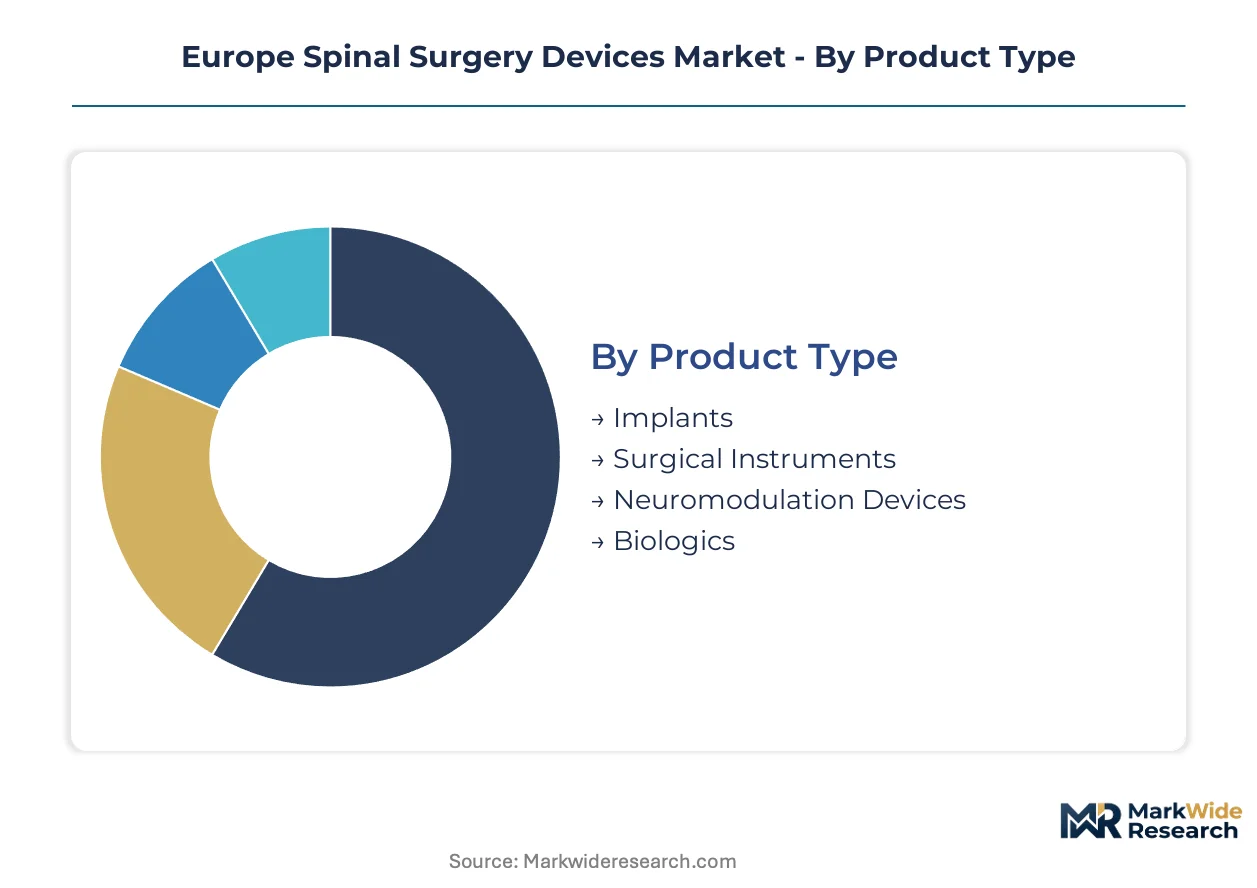
Segmentation in Europe's spinal surgery devices market reveals how procurement authority, technology maturity, and reimbursement pathways fragment purchasing decisions across institutional tiers. Understanding these divides enables manufacturers to align product portfolios with specific capital cycles and clinical evidence requirements.
Product Type:
Implantable hardware dominates procurement budgets across German and French hospital networks, while capital-intensive navigation platforms concentrate in high-volume academic centers.
- Implants:Titanium alloy and polyetheretherketone interbody cages, pedicle screws, and rod systems manufactured to sub-50-micrometer tolerances anchor procedural economics. German statutory health insurers maintain favorable reimbursement for titanium constructs in deformity correction, cementing volume concentration in Rhineland and Bavarian hospital clusters.
- Surgical Instruments:Specialized retractors, drills, and rod-bending tools anchor surgeon loyalty through ergonomic design and proprietary compatibility. French orthopedic centers prioritize instrument durability under repeated sterilization cycles, driving preference for cobalt-chrome alloys over stainless alternatives.
- Neuromodulation Devices:Spinal cord stimulators and dorsal root ganglion systems for chronic pain management.
- Biologics:Synthetic bone graft substitutes and cellular matrices commanding premium add-on payments in trauma reconstruction.
Established volume favors Implants; emerging adoption favors Biologics.
End User:
Procurement authority is fragmenting as direct purchasing power migrates from centralized hospital networks toward freestanding surgical facilities.
- Hospitals:Academic medical centers and general hospitals with integrated spine departments wield consolidated procurement budgets and capital equipment cycles. Belgian hospital networks now mandate standardized implant menus across cervical, thoracic, and lumbar applications from single-source contracts.
- Ambulatory Surgical Centers:Freestanding spine clinics in Germany and France bypass traditional procurement hierarchies. These facilities favor disposable instrument kits and modular robotic subscriptions over capital-intensive platform purchases.
- Specialty Clinics:Dedicated orthopedic and neurosurgical practices with focused procedural volumes.
- Rehabilitation Centers:Post-acute facilities integrating neuromodulation programming and recovery monitoring.
Procurement concentration remains with Hospitals; volume expansion is climbing fastest among Ambulatory Surgical Centers.
Technology:
Technology adoption curves diverge sharply between established minimally invasive techniques and capital-intensive robotic platforms.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement dominate lumbar decompression volumes. Italian spine centers report reduced length-of-stay metrics that satisfy regional health authority outcome benchmarks.
- Robotic Surgery:Autonomous drilling and screw placement platforms command seven-figure capital commitments. German high-volume centers pilot subscription-based acquisition models to preserve balance sheet capacity for EU MDR compliance investments.
- Navigation Systems:Optical and electromagnetic tracking for real-time instrument guidance.
- Imaging Techniques:Intraoperative CT and fluoroscopy integration with surgical workflows.
Minimally Invasive Surgery captures current procedural volume; Robotic Surgery represents the steepest expansion trajectory.
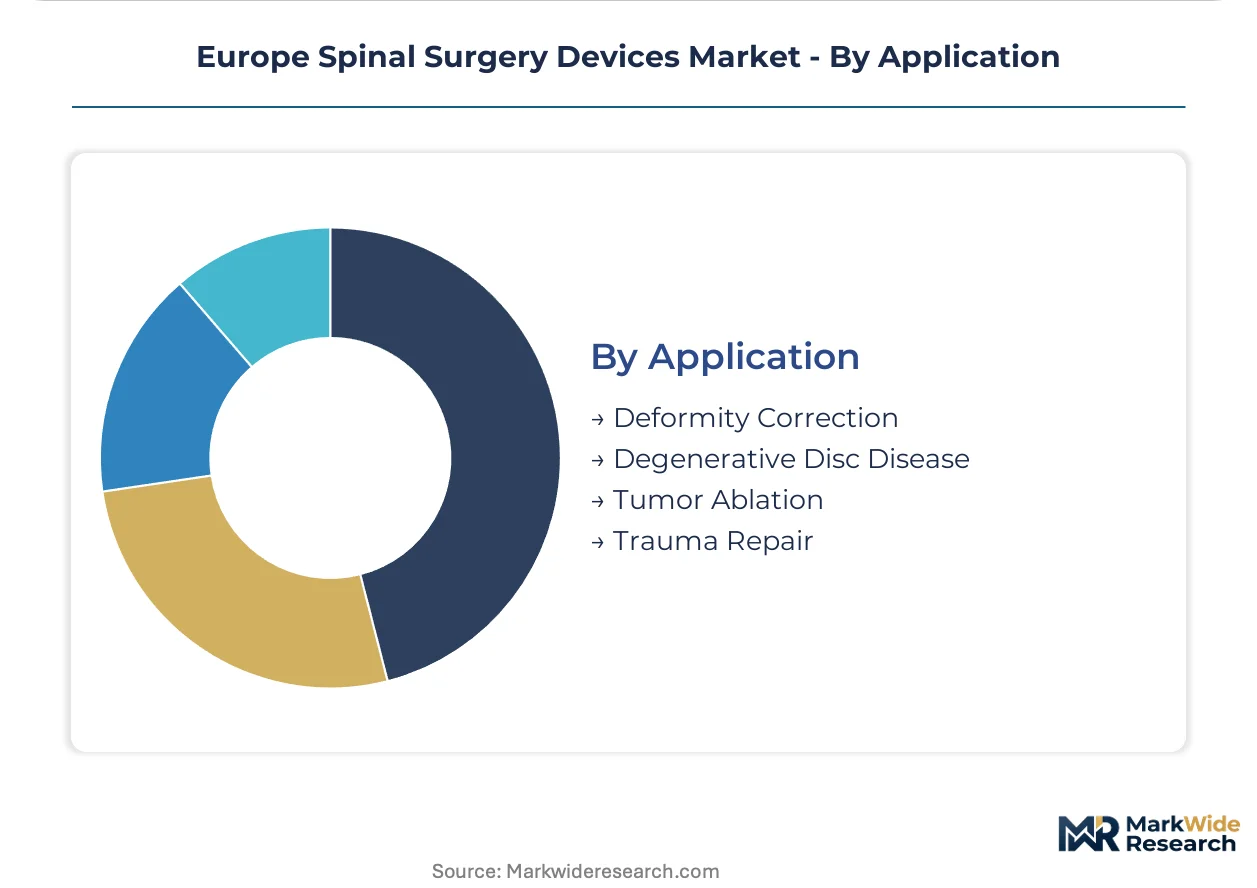
Application:
Clinical indication severity determines reimbursement tiering and technology selection across European markets.
- Deformity Correction:Complex scoliosis and kyphosis procedures requiring multi-level fusion with custom implant configurations. French diagnosis-related group system awards premium add-on payments for tumor and trauma reconstruction using synthetic biologics.
- Degenerative Disc Disease:Lumbar and cervical discectomy with interbody fusion constitutes the highest procedural frequency. German ambulatory surgical centers are expanding direct procurement for single-level cases previously routed to inpatient settings.
- Tumor Ablation:Vertebral column resection and stabilization for metastatic disease.
- Trauma Repair:Fracture fixation and stabilization following vertebral compression injuries.
Degenerative Disc Disease anchors current revenue; Deformity Correction is gaining share fastest on biologics premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network connects Rotterdam to Genoa, underwriting continental distribution of precision-manufactured spinal implants and capital equipment across core European markets.
Germany
Bavarian university hospitals in Munich and Erlangen drive adoption of navigation-integrated workflows for complex deformity correction. The Federal Institute for Drugs and Medical Devices (BfArM) operates national reimbursement assessments that determine hospital purchasing capacity for premium spinal technologies. Manufacturing clusters in Baden-Württemberg produce titanium alloy components with sub-50-micrometer tolerances for export throughout the EU.
France
The diagnosis-related group (DRG) system awards premium add-on payments for tumor and trauma reconstruction using synthetic biologics, concentrating demand in Parisian academic centers. ANSM coordinates with notified bodies on post-market surveillance obligations for implantable spinal hardware. Lyon and Marseille hospital networks are consolidating procurement across orthopedic and neurosurgical specialties.
United Kingdom
NHS England's specialized commissioning framework routes complex spinal deformity cases to designated supra-regional centers in London and Birmingham. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces UKCA marking requirements that diverged from EU MDR following Brexit. Scottish health boards are piloting value-based procurement models for lumbar fusion implants.
Italy
Lombardy regional health authorities track length-of-stay metrics for minimally invasive lumbar procedures, driving preference for tubular retractor systems. The Italian Medicines Agency (AIFA) manages reimbursement negotiations that vary by region, creating pricing fragmentation between northern and southern hospital networks. Milan and Bologna orthopedic centers anchor instrument procurement for trauma stabilization.
Netherlands
Hospital purchasing consortiums consolidate implant procurement across academic networks in Amsterdam and Utrecht, extracting volume-based discounts through single-source contracts. The Health and Youth Care Inspectorate (IGJ) enforces CE marking compliance for imported spinal devices. Rotterdam's port infrastructure enables just-in-time delivery of titanium sponge raw materials from non-EU suppliers.
Europe Spinal Surgery Devices Market Competitive Landscape
On the supply side, the industry is consolidating around well-capitalized manufacturers with established quality management systems capable of navigating extended EU MDR approval timelines. The vendor base fragments across three strategic tiers: diversified orthopedic conglomerates with broad implant portfolios, specialized spine-focused developers with concentrated innovation pipelines, and emerging navigation-robotic platform vendors. Dominant competitive moves include M&A activity to acquire notified body relationships and strategic partnerships to secure titanium alloy supply chains.
Within the diversified orthopedic tier, Medtronic, DePuy Synthes, and Stryker occupy positions that exemplify scale-driven competitive advantages. Medtronic leverages its broad European distribution footprint to sustain implant volume across multiple countries. DePuy Synthes competes through specialized instrument portfolios that anchor surgeon loyalty in key orthopedic centers. Stryker differentiates via navigation and robotic surgery platforms that command premium positioning in high-volume German and French hospitals.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker |
| Globus Medical |
| NuVasive |
| Zimmer Biomet |
| Orthofix |
| Alphatec Spine |
| ZimVie |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's titanium alloy manufacturing clusters anchor European spinal implant production, with sub-50-micrometer precision tolerance capacity translating directly into premium pricing power for deformity correction hardware. Aerospace-grade titanium sponge allocation shocks from Russian and Chinese suppliers compress margins on standard interbody cages while concentrating margin capture in patient-specific additive manufactured constructs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by CE marking tier and surgical volume commitment. Premium navigation-enabled robotic procedures command list-price premiums in German academic centers, while Belgian hospital consortiums extract volume discounts that erode standard-tier implant margins. Cost compression in economy-tier pedicle screw systems intensifies as Polish and Romanian privatized hospitals prioritize bundled instrument-and-implant offerings. Ambulatory surgical centers exhibit highest price sensitivity due to per-case reimbursement constraints, whereas complex deformity centers maintain lowest sensitivity given DRG add-on payments for biologics.
Supply Chain Analysis
Aerospace-grade titanium sponge feedstock concentrates in Chinese and Russian smelters, with medical-grade refinement capacity clustering in Germany, Japan, and the United States. European device manufacturers draw from powder-bed fusion additive manufacturing inputs and polyetheretherketone resin streams anchored in Belgian and Dutch chemical complexes. Single-source vulnerability in titanium alloy supply exposes production schedules to export restriction shocks. Distribution runs through Rotterdam port infrastructure for just-in-time raw material delivery, with finished implants moving via Rhine-Alpine Corridor freight rail to hospital networks and ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe spinal surgery devices market sits in a cyclical recovery phase as EU MDR compliance investments peak and capital equipment refresh cycles accelerate in German and French high-volume centers.
For Market Incumbents: Harden notified body relationships ahead of Class III implant recertification waves, consolidating quality management system infrastructure to absorb eighteen-to-thirty-month application backlogs. Secure captive supply of medical-grade titanium sponge through long-term offtake agreements with non-Russian feedstock sources to defend margin position against raw material volatility. Prioritize backward integration into additive manufacturing powder production to control patient-specific implant cost structures.
For New Entrants and Emerging Players: Pursue navigation-robotic platform subscriptions in German ambulatory surgical centers where legacy vendor relationships remain unformed. Target Warsaw and Bucharest greenfield orthopedic centers with modular instrument kits that bypass capital-intensive hospital procurement hierarchies. Lead with disposable retractor systems and single-use drill kits that align with freestanding clinic cash-flow constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR compliance costs are filtering marginal competitors and concentrating share among well-capitalized manufacturers with established quality systems. Acquisition targets should display dedicated regulatory affairs infrastructure and notified body relationships rather than pure technology differentiation. Monitor notified body designation announcements as the inflection signal for product launch velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class III certification timelines determine competitive access to premium deformity segments. |
| Hospital System Partnership | Single-source contracts with Belgian academic networks lock in multi-specialty procurement volumes. |
| Software Companion Development | Real-time EHR integration middleware reduces robotic platform deployment friction. |
| Reimbursement Strategy | French DRG add-on payment capture for biologics differentiates trauma reconstruction portfolios. |
| Backward Integration | In-house titanium powder production insulates margin from aerospace-medical grade allocation competition. |
Research Methodology
Initial hypotheses were tested against primary input from spine surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and notified body auditors, and refined through secondary validation against EMA coordination documents, BfArM reimbursement assessments, hospital procurement databases, GPO contract filings, and EU MDR technical documentation requirements. Bottom-up implant volume modeling triangulated against top-down capital equipment expenditure tracking across German, French, and Italian hospital networks.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across product type, end user, technology, and application dimensions. CAGRs were derived from procedure volume elasticity to aging demographic penetration and capital investment cycle phasing. Industry-specific forecast inputs incorporated EU MDR transition timeline assumptions and ambulatory surgical center licensing expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare expenditure growth, titanium alloy commodity volatility, or notified body capacity constraints would shift the trajectory. Forecasts reflect documented assumptions regarding reimbursement pathway stability and MDR implementation enforcement intensity. Cross-checking against national health technology appraisal divergence patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoprosthesis Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Implantable Pump Catheter Market