
 Endoscopy Fluid Management Systems Market | 2026-2036
Endoscopy Fluid Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Fluid Management Systems Market Foresight
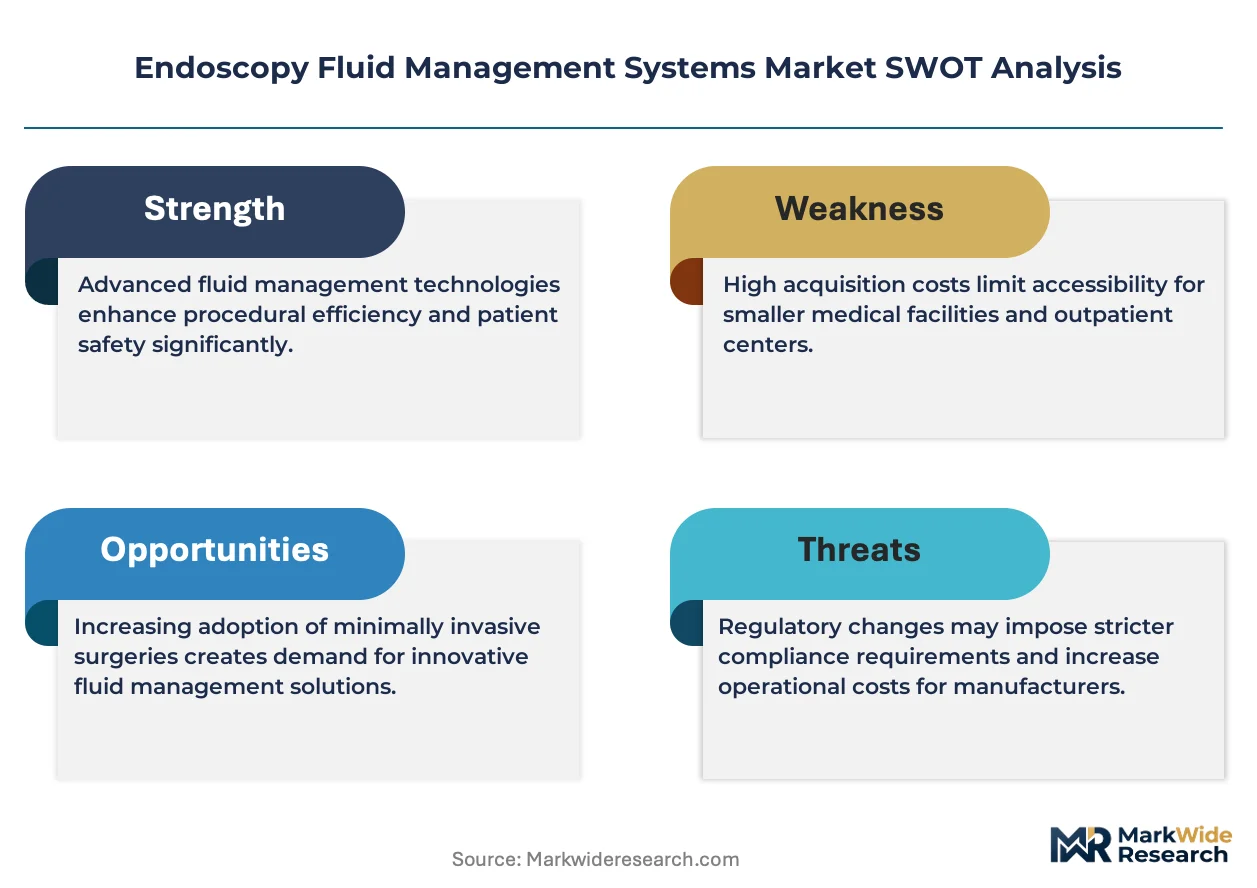
Germany is tilting toward expanded domestic production capacity for endoscopy fluid management equipment. Stryker Corporation leverages its surgical technologies division to sustain integrated pump-and-tubing portfolios across European hospital networks. Olympus Corporation anchors its position through proprietary channel compatibility with its endoscope installed base. KARL STORZ SE & Co. KG differentiates via rigid endoscopy fluid control systems for arthroscopy and laparoscopy suites.
Endoscopy fluid management systems regulate irrigation, suction, and distension fluid dynamics during minimally invasive procedures, typically operating at flow rates between 50 mL/min and 1,500 mL/min with pressure monitoring to prevent patient injury. These systems maintain optical clarity and anatomical workspace for endoscopic visualization across gastrointestinal, urological, and orthopedic interventions. Pumps and integrated management systems capture the dominant share of equipment expenditure as facilities prioritize automated pressure sensing and alarm functionality over basic gravity-fed setups. Ambulatory surgical centers represent the fastest-growing end-user category as same-day procedure volumes shift away from traditional hospital campuses. Mobile and portable installation types are gaining preference in multi-procedure suites where capital equipment must flex across service lines.
The FDA enforces 510(k) premarket notification requirements for powered suction and irrigation devices, while the EU Medical Device Regulation mandates enhanced clinical evidence and post-market surveillance for Class IIa fluid management systems. ISO 13485 quality management certification shapes supplier qualification criteria for original equipment manufacturers sourcing pumps and tubing assemblies. Stakeholders must weigh regulatory compliance investment against the margin compression from expanding ambulatory care price sensitivity.
Market Dynamics
Closed-loop fluid management platforms are displacing gravity-fed irrigation setups across ambulatory surgical networks, driven by automated pressure sensing mandates and same-day procedure volume migration from inpatient campuses.
Growth Catalysts
- EU Medical Device Regulation:Class IIa fluid management systems now require enhanced clinical evidence and post-market surveillance, accelerating hospital replacement cycles for legacy pump-and-tubing assemblies.
- Ambulatory surgical centers:Same-day endoscopy volumes in Germany and surrounding EU markets are pulling automated suction and irrigation platforms into outpatient settings previously served by manual setups.
- ISO 13485 certification:Quality management mandates for pump and tubing suppliers are consolidating procurement toward qualified original equipment manufacturers with certified assembly lines.
Market Restraints
- Silicone tubing supply concentration:Medical-grade extrusion capacity clusters in southern Germany and northern Italy, creating single-source vulnerability for fluid management kit assemblers.
- FDA 510(k) pathway friction:Powered suction and irrigation device notifications face extended review timelines for novel pressure-sensing algorithms, delaying product launches in the US market.
- Gravity-fed substitute persistence:Low-complexity procedures in cost-constrained settings continue using basic irrigation bags, capping premium system penetration in price-sensitive segments.
Strategic Opportunities
- Multi-procedure suite mobility:Portable installation types that flex across gastrointestinal, urological, and orthopedic service lines capture capital equipment budgets in German hospital networks consolidating physical footprints.
- Arthroscopy fluid control:Rigid endoscopy suites for orthopedic intervention remain underpenetrated by integrated management platforms relative to gastrointestinal applications.
- CE marking harmonization:Streamlined conformity assessment routes under the EU MDR reduce time-to-market for pump-and-tubing portfolios targeting cross-border hospital procurement consortia.
Industry Challenges
- Biomedical engineering talent scarcity:Fluid dynamics specialists with ISO 13485 audit experience command premium compensation, constraining mid-tier manufacturers' quality team expansion.
- Legacy endoscope integration:Proprietary channel compatibility requirements from dominant endoscope installed bases complicate third-party fluid management system certification and hospital adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Fluid Management Systems Market |
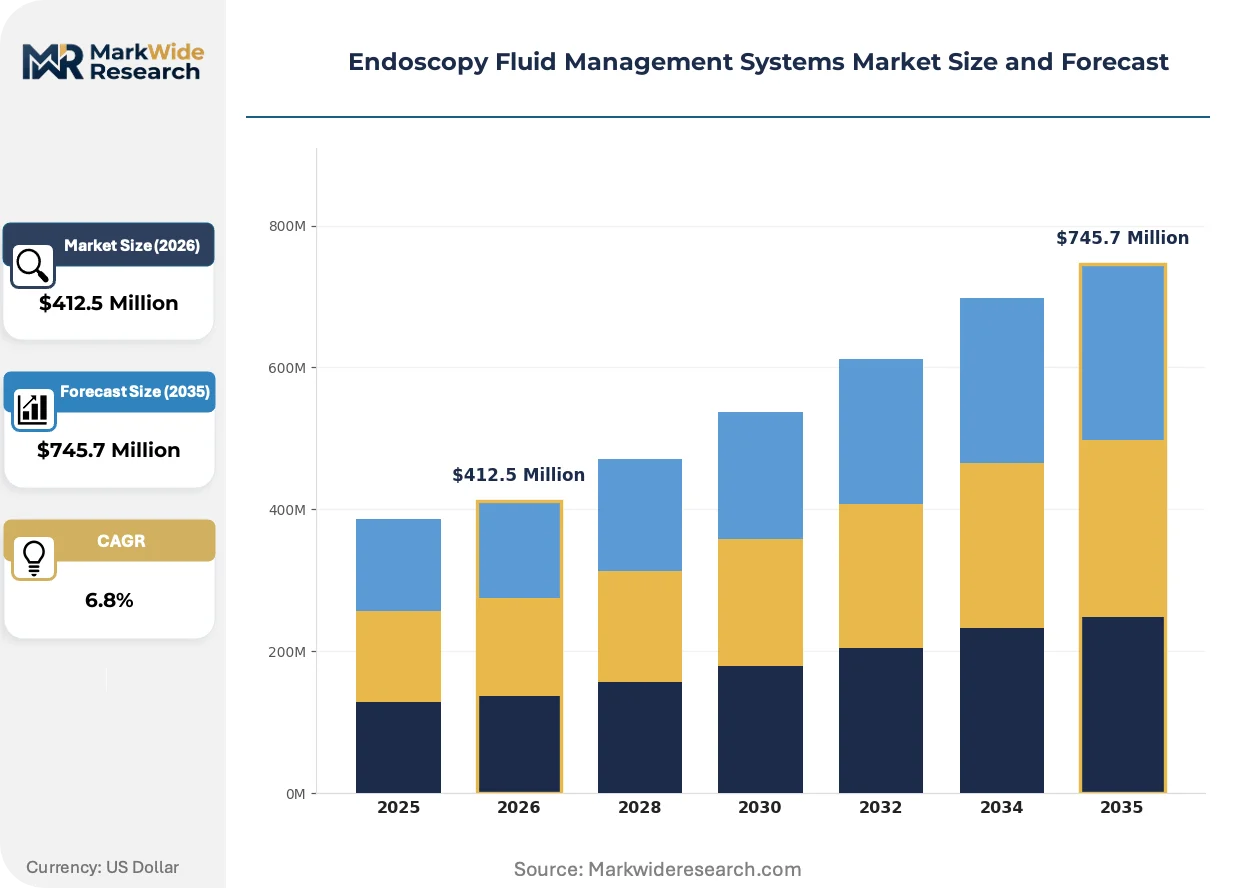
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Tubing, Management Systems, Accessories End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutes Installation Type: Fixed, Mobile, Portable, Semi-portable Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Smith & Nephew Plc, B. Braun Melsungen AG, Stryker Corporation, Hologic Inc., Medtronic Plc, Olympus Corporation, Arthrex Inc., Richard Wolf GmbH, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Fluid Management Systems Market Shifts & Advancements
Sensor-integrated pressure monitoring and disposable tubing assemblies are compressing the traditional divide between capital equipment and consumable revenue models across European endoscopy suites.
Smart pump controllers with real-time flow rate telemetry are digitizing surgical workflow documentation. German hospital networks are piloting these systems in high-volume gastrointestinal units. The technology is digitizing compliance reporting for EU MDR post-market surveillance requirements while reducing manual logging burden.
The EU Medical Device Regulation's Unique Device Identification mandates are forcing fluid management kit assemblers to reconfigure labeling and traceability infrastructure. Component suppliers must now maintain electronic records linking individual pump serial numbers to tubing lot codes. Class IIa system manufacturers serving German and French hospital procurement groups are absorbing the steepest compliance costs.
After-sales service unbundling is fragmenting traditional equipment procurement bundles. Ambulatory surgical centers in Bavaria and Baden-Württemberg are separating pump maintenance contracts from initial capital purchases, pressuring vendors to disclose hourly service rates and spare parts pricing. This shift is most visible among multi-site outpatient endoscopy chains negotiating centralized procurement agreements.
Endoscopy Fluid Management Systems Market Segmentation
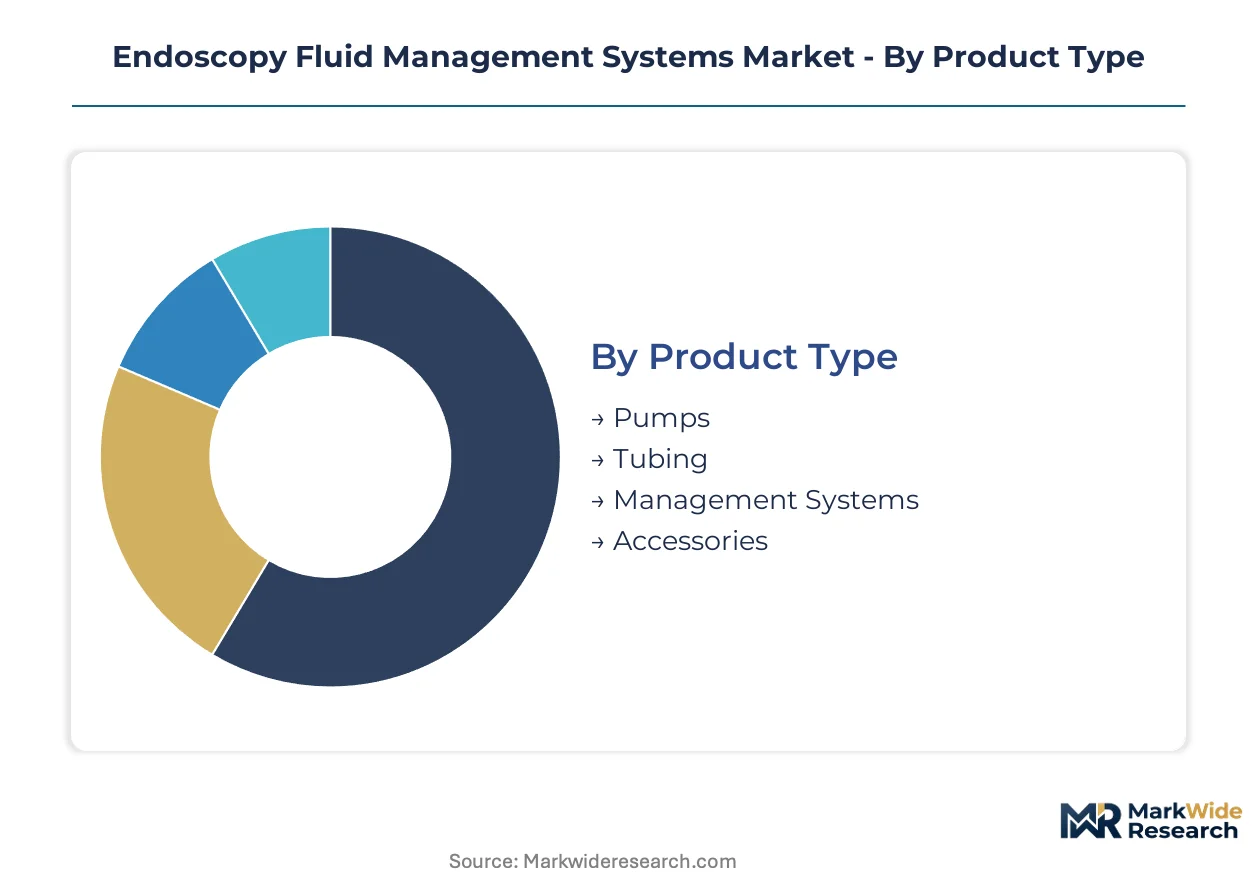
Endoscopy fluid management systems serve distinct clinical workflows across pressure-controlled irrigation, suction optimization, and distension maintenance. Segmentation reveals how procurement priorities diverge between high-volume hospital networks and capital-constrained outpatient settings.
Product Type:
Equipment portfolios span standalone components through integrated platforms, reflecting varying automation requirements across procedural complexity tiers.
- Pumps:Automated pressure-sensing units deliver flow rates from 50 mL/min to 1,500 mL/min with real-time alarm functionality. German ambulatory surgical centers favor these for same-day gastrointestinal procedures where manual gravity-fed setups previously dominated.
- Management Systems:Integrated pump-and-tubing platforms with centralized control interfaces capture capital budgets in multi-procedure suites. Bavarian hospital networks prioritize these for service line flexibility across gastrointestinal, urological, and orthopedic interventions.
- Tubing:Medical-grade silicone and PVC assemblies with sterile packaging configurations serve kit-based procurement models.
- Accessories:Connectors, filters, and disposable manifolds complete fluid circuit assemblies for specific endoscope channel geometries.
Established volume favors pumps; emerging adoption favors management systems.
End User:
Procurement authority concentrates differently across inpatient campuses, outpatient chains, and research settings with varying reimbursement and capital allocation timelines.
- Hospitals:Integrated delivery networks in Germany maintain centralized purchasing for pump-and-tubing portfolios with multi-year service contracts. EU MDR compliance documentation requirements extend replacement cycles for legacy Class IIa systems.
- Ambulatory Surgical Centers:Same-day procedure volume migration from inpatient campuses drives demand for portable platforms with rapid setup protocols. These facilities represent the steepest expansion trajectory among end-user categories.
- Clinics:Single-specialty gastrointestinal practices in Baden-Württemberg prioritize budget-tier gravity-fed alternatives for low-complexity diagnostic procedures.
- Research Institutes:Academic medical centers pilot sensor-integrated platforms with telemetry documentation for post-market surveillance compliance.
Capital deployment tilts toward ambulatory surgical centers; regulatory documentation burdens concentrate in hospitals.
Installation Type:
Physical configuration determines capital efficiency across consolidated footprints and multi-site outpatient networks.
- Fixed:Permanent wall-mounted units with dedicated plumbing infrastructure serve high-volume endoscopy suites in tertiary hospitals. Frankfurt and Munich medical centers favor these for dedicated gastrointestinal wings.
- Portable:Battery-powered or cart-based systems with rapid deployment protocols capture preference in multi-procedure suites where equipment must flex across service lines. These configurations gain share fastest among installation types.
- Mobile:Wheeled platforms with standardized electrical connections serve intermediate-volume settings requiring room-to-room relocation.
- Semi-portable:Hybrid configurations with detachable components balance fixed installation stability with limited repositioning capability.
Fixed installations anchor hospital infrastructure; portable configurations penetrate outpatient expansion.
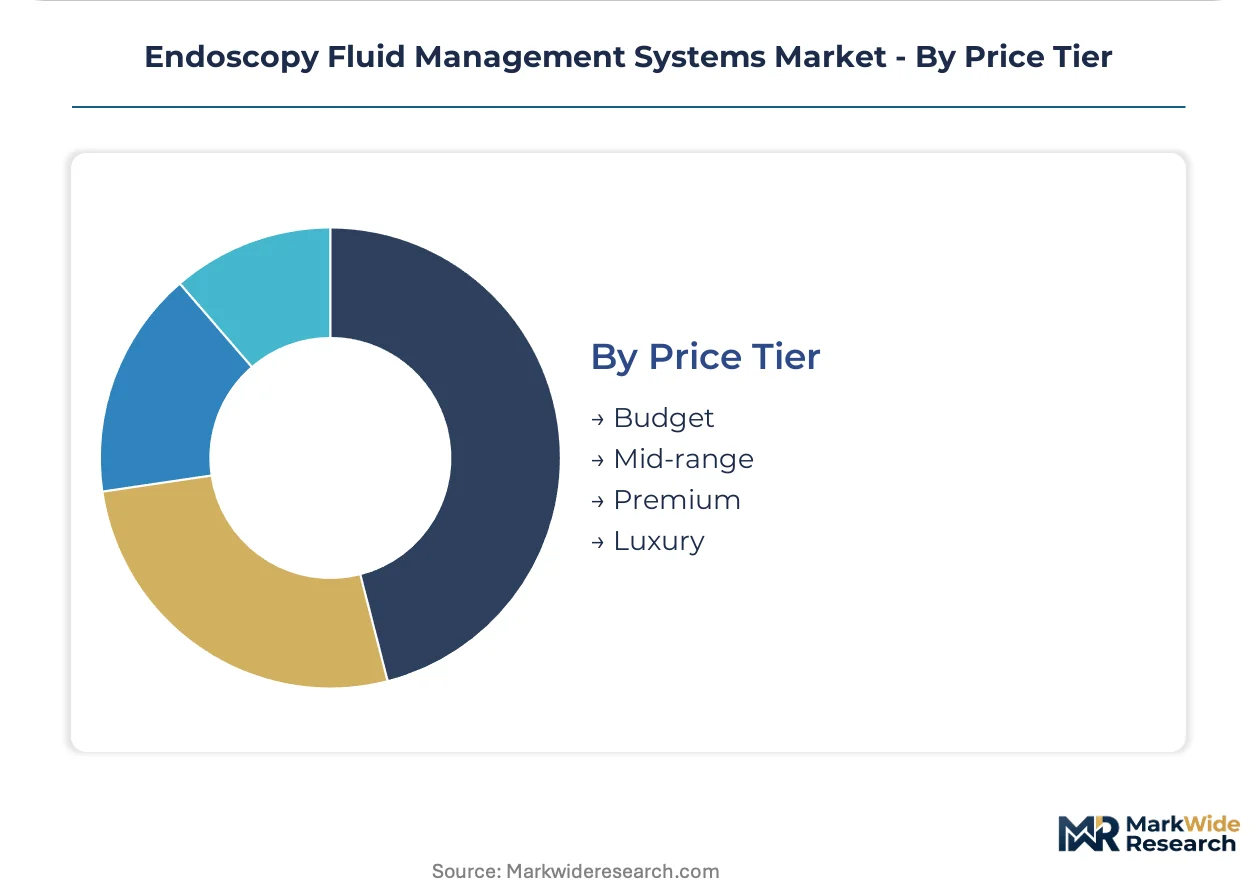
Price Tier:
Procurement budgets stratify across reimbursement environment, procedure volume, and compliance risk tolerance.
- Premium:Sensor-integrated platforms with automated pressure monitoring, real-time telemetry, and EU MDR-compliant traceability infrastructure. German hospital procurement consortia absorb these for high-liability therapeutic procedures.
- Mid-range:Electromechanical pumps with basic alarm functionality and standardized tubing compatibility serve mainstream clinical demand. These units balance automation benefits against capital constraints in regional hospital networks.
- Budget:Gravity-fed irrigation setups with manual pressure control persist in cost-constrained settings and low-complexity diagnostic applications.
- Luxury:Custom-configured platforms with proprietary endoscope channel optimization and dedicated biomedical engineering support contracts.
Premium tier captures compliance-driven replacement; mid-range tier absorbs volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone extrusion capacity clusters in southern Germany and northern Italy, creating single-source vulnerability for fluid management kit assemblers serving European hospital networks. This concentration shapes procurement patterns and compliance investment across the continent.
Germany
Outpatient endoscopy volumes in Bavaria and Baden-Württemberg drive demand for portable pump-and-tubing platforms. The EU Medical Device Regulation mandates enhanced clinical evidence for Class IIa systems, accelerating replacement cycles in Frankfurt and Munich medical centers. Stuttgart-based tubing suppliers expand certified assembly lines to meet ISO 13485 procurement requirements.
United States
FDA 510(k) premarket notifications for powered suction and irrigation devices face extended review timelines, delaying novel pressure-sensing algorithm launches. Ambulatory surgical centers in Texas and Florida pull automated platforms into same-day procedure settings. Boston academic medical centers pilot sensor-integrated systems with telemetry documentation for post-market surveillance compliance.
France
ANSM oversight of Class IIa fluid management systems enforces sterility documentation standards exceeding baseline EU MDR requirements. Hospital procurement consortia in Île-de-France absorb premium-tier compliance costs for high-liability therapeutic procedures. Lyon-area distributors reconfigure labeling infrastructure to meet Unique Device Identification mandates.
Italy
Northern Italian extrusion facilities supply medical-grade tubing assemblies to German kit manufacturers, creating cross-border supply dependencies. Arthroscopy fluid control platforms remain underpenetrated relative to gastrointestinal applications in Milan and Turin surgical suites. Bologna-based research institutes validate smart pump controllers for EU MDR post-market surveillance digitization.
United Kingdom
MHRA transitional arrangements for legacy CE-marked devices create regulatory uncertainty for fluid management system importers. London hospital networks consolidate procurement across gastrointestinal and urological service lines. Cambridge-area biomedical engineering clusters face talent scarcity for ISO 13485 audit-qualified fluid dynamics specialists.
Endoscopy Fluid Management Systems Market Competitive Landscape
Integrated surgical technology conglomerates and specialized endoscopy equipment manufacturers split the market between bundled pump-and-tubing portfolios and proprietary channel-compatible systems. Tiered competitive dynamics separate premium sensor-integrated platforms from mid-range electromechanical alternatives. Three archetypes dominate: diversified medtech giants with surgical divisions, pure-play endoscopy specialists with installed base leverage, and regional tubing component suppliers with certified extrusion capabilities. Capacity expansion in southern Germany and strategic partnerships for FDA pathway navigation represent the dominant competitive moves.
Among diversified surgical technology providers, Stryker Corporation and Medtronic Plc occupy positions anchoring integrated pump-and-tubing portfolios across European and North American hospital networks. Olympus Corporation exemplifies the endoscopy-specialist archetype, leveraging proprietary channel compatibility with its installed base of visualization systems. KARL STORZ SE & Co. KG represents rigid endoscopy fluid control specialization, serving arthroscopy and laparoscopy suites with differentiated pressure-management configurations. Richard Wolf GmbH and B. Braun Melsungen AG sit within the German-engineered equipment tier, supplying regional hospital procurement consortia with ISO 13485-certified assembly lines.
| Leading Market Players |
|---|
| Smith & Nephew Plc |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Hologic Inc. |
| Medtronic Plc |
| Olympus Corporation |
| Arthrex Inc. |
| Richard Wolf GmbH |
| KARL STORZ SE & Co. KG |
| Others |
Supply & Pricing Matrix
Medical-grade silicone extrusion capacity in southern Germany and northern Italy anchors margin capture for fluid management kit assemblers, concentrating pricing power with certified component suppliers serving EU hospital procurement networks. This upstream concentration funnels downstream into tiered equipment pricing that reflects ISO 13485 compliance investment and after-sales service unbundling pressures.
Pricing Analysis
The EU Medical Device Regulation dictates the pricing tier structure across the endoscopy fluid management market, separating premium sensor-integrated platforms with automated pressure monitoring and telemetry documentation from mid-range electromechanical pumps and budget gravity-fed alternatives. Price differentiation rests on certification grade and after-sales service bundling, with Bavarian hospital procurement consortia absorbing premium tiers for high-liability therapeutic procedures while ambulatory surgical centers in Baden-Württemberg drive cost compression through unbundled maintenance contracts. Pricing pressure stems from same-day procedure volume migration pulling automated platforms into outpatient settings previously served by manual setups. Ambulatory surgical centers exhibit the steepest price sensitivity; tertiary hospital networks in Frankfurt and Munich demonstrate the least.
Supply Chain Analysis
Extended payment terms from German hospital procurement consortia are compressing working capital for tubing kit assemblers, forcing supply-chain finance facilities into component supplier relationships. Geographic supply concentration centers on Germany, Italy, and Switzerland for medical-grade silicone extrusion and pump assembly. Raw material dependencies include medical-grade silicone polymers, precision-machined pump housings, and sterile packaging films. Single-source vulnerability runs through southern German extrusion facilities serving cross-border kit manufacturers. Distribution runs through regional hospital procurement consortia and specialized medical device distributors with ISO 13485-certified warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the endoscopy fluid management market as ambulatory surgical center expansion creates discrete demand niches for portable, rapid-deployment platforms outside traditional hospital procurement hierarchies.
For Market Incumbents: Harden proprietary channel compatibility positions against third-party fluid management system encroachment by deepening integration with dominant endoscope installed bases. Expand ISO 13485-certified assembly capacity in Stuttgart and surrounding southern German clusters to capture tubing supply concentration leverage. Defensive consolidation should prioritize sensor-integrated platform R&D to outpace gravity-fed substitute persistence in cost-constrained segments. For New Entrants and Emerging Players: Build out arthroscopy fluid control specialization for rigid endoscopy suites, the most penetrable white-space target relative to saturated gastrointestinal applications. Target Bavarian and Baden-Württemberg ambulatory surgical center chains with portable installation types featuring rapid setup protocols and unbundled service pricing. Go-to-market execution should leverage direct procurement relationships with multi-site outpatient endoscopy chains bypassing traditional hospital GPO structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German-engineered equipment tier manufacturers possessing ISO 13485-certified assembly lines but limited sensor-integrated platform portfolios. Long-term viability over the medium-term horizon rests on regulatory compliance infrastructure amortization across EU MDR and FDA 510(k) pathways. Acquisition screening should prioritize tubing component suppliers with certified extrusion capabilities. The signal to watch is FDA review timeline compression for novel pressure-sensing algorithms, which would accelerate product launch velocity and valuation multiples for algorithm-enabled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Streamlined EU MDR conformity assessment reduces time-to-market for pump-and-tubing portfolios targeting German hospital consortia. |
| Hospital System Partnership | Centralized procurement agreements with Bavarian integrated delivery networks anchor multi-year service contract revenue visibility. |
| Software Companion Development | Smart pump controllers with real-time telemetry digitize compliance reporting for ANSM and FDA post-market surveillance mandates. |
| Backward Integration into Tubing | In-house production of medical-grade silicone assemblies mitigates single-source vulnerability from southern German extrusion concentration. |
| Reimbursement Strategy | Same-day procedure coding alignment with German outpatient endoscopy reimbursement schedules accelerates ambulatory surgical center adoption. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, ambulatory surgical center operations managers, and GPO contracts specialists, and refined through secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up equipment shipment analysis and top-down healthcare expenditure allocation models were triangulated to converge on volume and value estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling spanning product type, end-user category, installation configuration, and price tier dimensions. CAGRs were derived from fitted growth curves calibrated to procedural volume trajectories and capital equipment replacement cycles. Industry-specific forecast inputs included German outpatient endoscopy migration rates and FDA review timeline assumptions for powered suction and irrigation devices.
Practitioners should monitor regulatory pathway friction, silicone supply concentration disruptions, and ambulatory care reimbursement shifts for early signals of forecast deviation. The analysis reflects documented assumptions regarding EU MDR implementation pace and same-day procedure volume trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
US Colonic Stents Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Global Endoscopes Market