
 Airway Management Tubes Market | 2026-2036
Airway Management Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Airway Management Tubes Market Analysis
Malaysia is reshaping supply chain geography for airway management tubes through new cleanroom manufacturing investments aimed at Southeast Asian hospital procurement. Medtronic leverages its vertically integrated catheter production network to sustain cost advantages across endotracheal and tracheostomy tube portfolios. Teleflex Incorporated anchors North American distribution through dedicated critical care sales channels, while Smiths Medical competes on material science differentiation in reinforced airway designs.
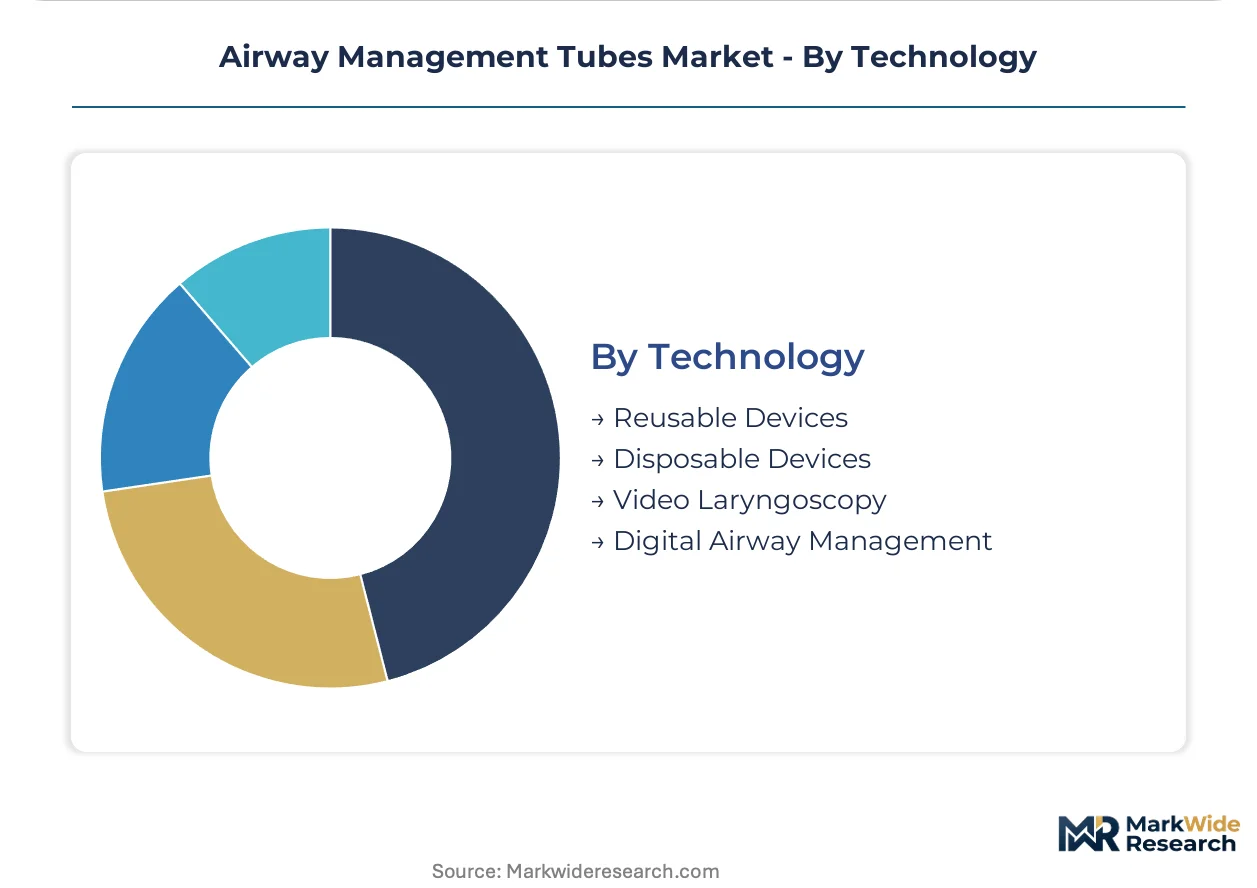
Airway management tubes constitute polymer-based or silicone conduits engineered to secure patent airways during mechanical ventilation, anesthesia induction, or emergency resuscitation, with inner diameters typically ranging from 2.0 mm to 10.0 mm and cuff pressures maintained below 30 cm H₂O to prevent tracheal injury. Endotracheal tubes dominate hospital purchasing volumes due to their ubiquity in operative and critical care settings, whereas laryngeal masks represent the fastest-expanding category as ambulatory surgical centers prioritize supraglottic airway alternatives that reduce intubation trauma and accelerate turnover. Disposable devices command the technology segment's value pool given infection control mandates, though video laryngoscopy integration is creating hybrid procurement patterns where visualization-enabled tube placement commands premium positioning.
The FDA's 510(k) clearance pathway and ISO 10993 biocompatibility standards govern material selection and clinical validation requirements for US market entry, while the EU MDR has extended conformity assessment timelines for European manufacturers. Health Canada and TGA alignment with ISO standards creates streamlined approval reciprocity for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as digital airway management technologies with embedded sensors trigger novel classification debates that could fragment compliance strategies.
Market Dynamics
The FDA's tightened 510(k) premarket notification requirements for Class II medical devices are forcing manufacturers to absorb extended validation timelines and elevated compliance costs, while hospital systems simultaneously pivot procurement toward disposable portfolios to satisfy infection control mandates.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient facilities in the United States are scaling supraglottic airway device procurement to accelerate patient turnover and reduce intubation-related complications.
- EU MDR Implementation:Extended conformity assessment timelines under the European Medical Device Regulation are consolidating supplier bases around established manufacturers with robust quality management systems.
- Silicone Material Advances:Enhanced biocompatibility profiles per ISO 10993 standards are enabling thinner-walled tube designs that reduce tracheal trauma incidence in prolonged ventilation cases.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade PVC and silicone resin prices fluctuate with petrochemical supply chains, compressing margin buffers for disposable tube manufacturers.
- Cleanroom Manufacturing Concentration:Southeast Asian production clusters face bottleneck risks from single-source sterilization facility dependencies.
- Reusable Device Substitution:Metal laryngoscopes and autoclavable airway adjuncts retain footholds in cost-constrained public hospital systems.
Strategic Opportunities
- Malaysian Manufacturing Investment:New cleanroom facilities in Penang and Selangor offer tariff-advantaged export platforms for ASEAN hospital procurement networks.
- Sensor-Embedded Tube Convergence:Integration of pressure transducers and CO2 detection elements with standard endotracheal designs creates premium positioning in intensive care segments.
- Health Canada-TGA Reciprocity:Streamlined approval alignment between Canadian and Australian regulators accelerates multinational product launch timelines.
Industry Challenges
- Anesthesiologist Training Gaps:Video laryngoscopy competency requirements outpace residency program curriculum updates, slowing adoption of visualization-enabled placement systems.
- Legacy EMR Integration Friction:Digital airway devices with embedded monitoring generate data streams that lack standardized interoperability with existing hospital information architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airway Management Tubes Market |
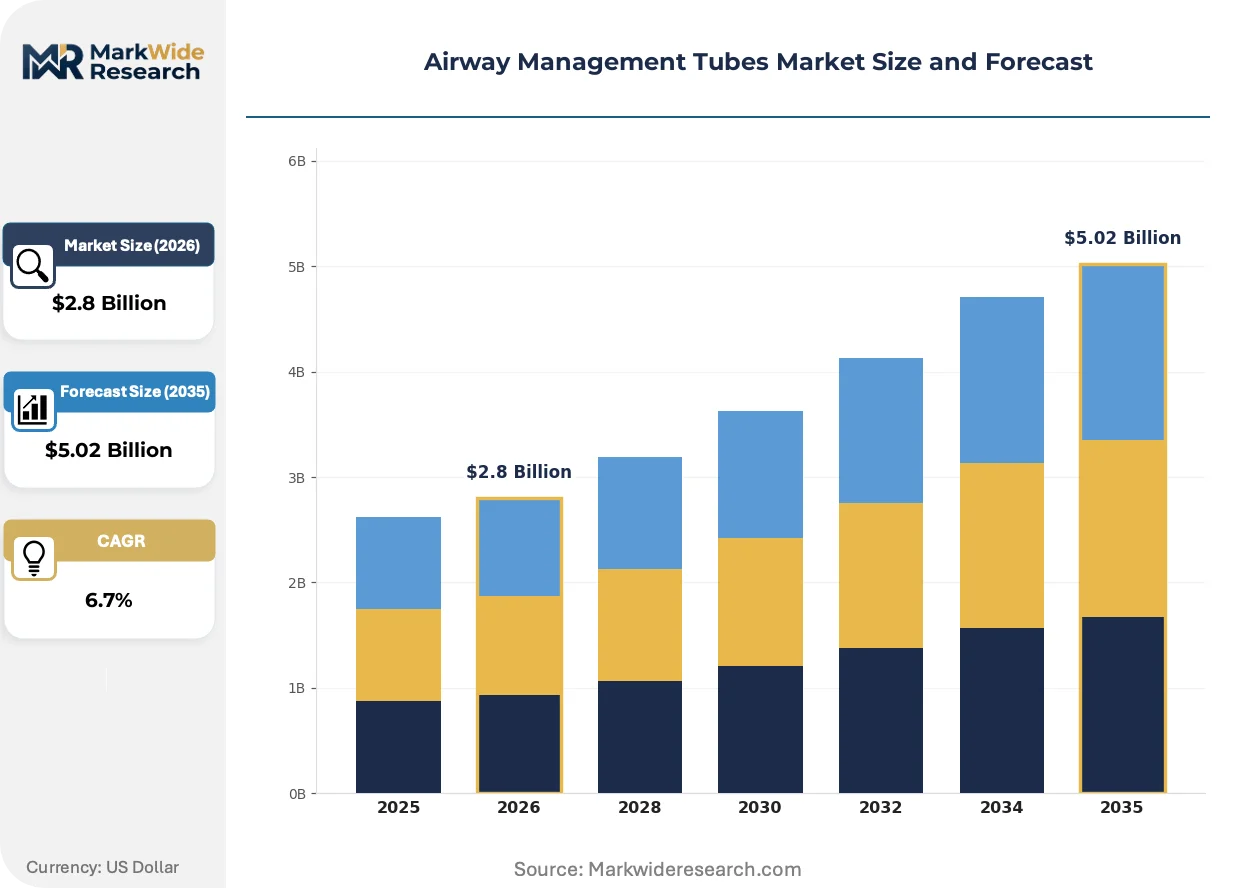
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Laryngeal Masks, Oro-Pharyngeal Airways, Nasal Airways Application: Emergency Care, Anesthesia, Surgery, Intensive Care End User: Hospitals, Ambulance Services, Clinics, Home Care Technology: Reusable Devices, Disposable Devices, Video Laryngoscopy, Digital Airway Management |
| Companies Covered | Medtronic, Teleflex Incorporated, Smiths Medical, Ambu A/S, ConvaTec Group Plc, Cook Group Inc., Intersurgical Ltd., Fisher and Paykel Healthcare Corp. Ltd., Flexicare Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airway Management Tubes Market Emerging Trajectories
Digital sensing technologies and material science advances are compressing the traditional boundary between airway devices and patient monitoring systems, while regulatory frameworks struggle to classify hybrid products.
Subglottic secretion drainage endotracheal tubes with integrated suction lumens are virtualizing the separate oral care protocols previously required to reduce ventilator-associated pneumonia incidence. Intensive care units in the United States are adopting these designs at accelerated rates compared to standard cuffed tubes. The technology is virtualing standalone suction catheter procurement into bundled airway management contracts.
The EU MDR's extended clinical evidence requirements for Class IIa devices are forcing manufacturers to maintain parallel technical documentation for European and non-European market variants. This regulatory friction is compressing European product launch timelines relative to FDA-cleared equivalents. Reinforced silicone tracheostomy tubes with extended implantation indications face the steepest conformity assessment delays.
Hospital procurement departments are consolidating airway device purchasing into multi-year framework agreements with single-source suppliers to secure volume discounts and standardize clinician training. Group purchasing organizations are displacing individual hospital contracting autonomy in the United States. This concentration is most visible in integrated delivery networks spanning multiple states.
Airway Management Tubes Market Segmentation
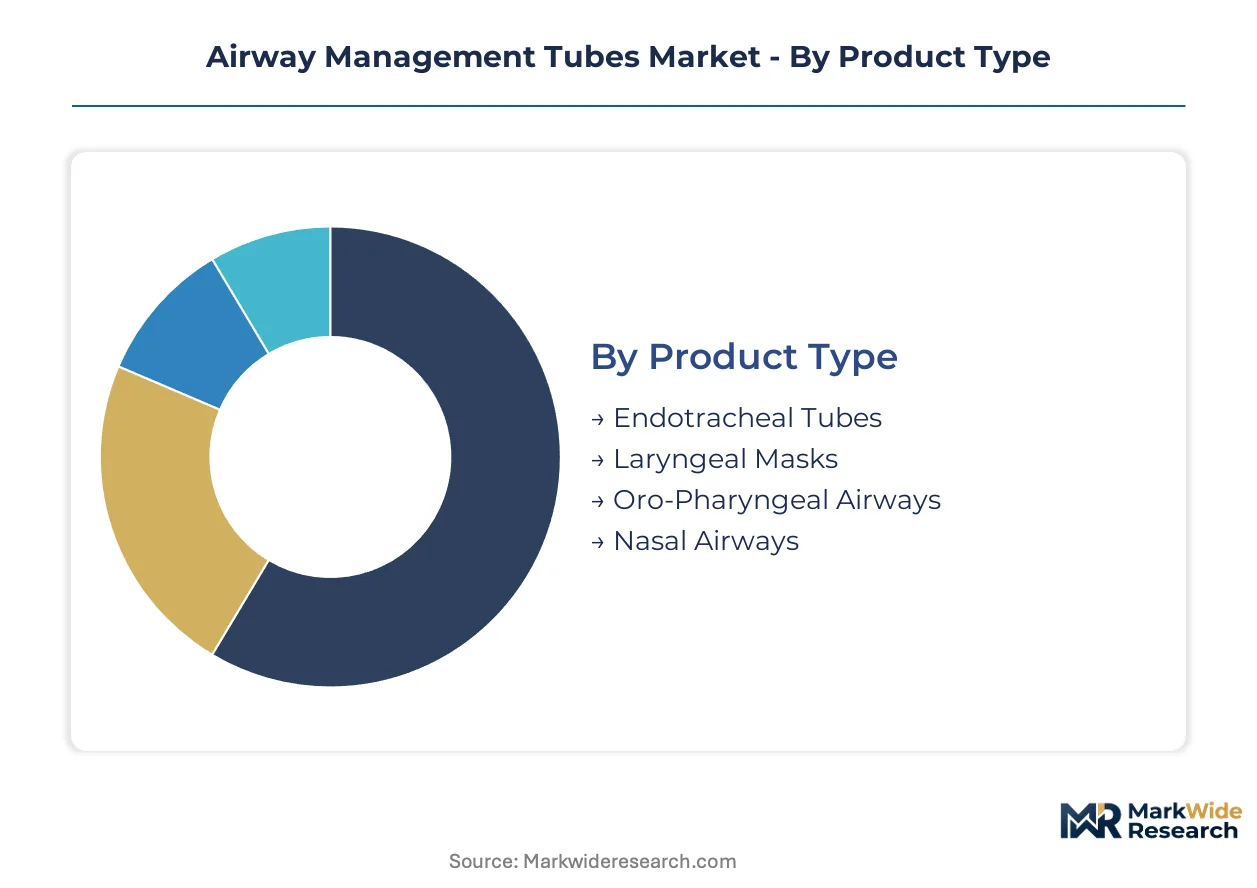
Airway management tubes fragment across four distinct taxonomies that reshape procurement patterns. Product type determines clinical utility and reimbursement tiers, while technology choice increasingly governs capital versus operating expenditure trade-offs in hospital budgets.
Product Type:
Cycle times vary dramatically across this category, with single-use devices in high-turnover surgical settings refreshing inventory weekly while implantable tracheostomy tubes sustain multi-year utilization horizons.
- Endotracheal Tubes:Polymer-based conduits with inflatable cuffs designed for trans-laryngeal mechanical ventilation, typically sized 2.0-10.0 mm inner diameter. United States hospital systems drive procurement volumes through aging surgical caseloads and trauma center expansion mandates.
- Laryngeal Masks:Supraglottic airway devices featuring silicone or PVC cuffs that seal perilaryngeal structures without tracheal intubation. Ambulatory surgical centers in the United States are scaling procurement fastest to accelerate patient turnover and reduce postoperative airway complications.
- Oro-Pharyngeal Airways:Curved plastic channels maintaining tongue displacement in unconscious patients during emergency resuscitation protocols.
- Nasal Airways:Soft rubber or polymer tubes traversing the nasopharynx to secure patent airways when oral placement is contraindicated.
Endotracheal tubes dominate installed base. Laryngeal masks are where expansion concentrates.
Application:
Cost tier stratification separates high-acuity settings with bundled reimbursement from outpatient environments where device economics directly impact facility margins.
- Emergency Care:Rapid-deployment airway protocols in trauma bays and prehospital settings demand disposable, pre-lubricated designs with standardized sizing. United States EMS systems are consolidating procurement around color-coded, single-use portfolios to reduce field decision latency.
- Anesthesia:Elective surgical airway management requiring precise cuff pressure control and subglottic suction capability. Ambulatory surgery centers prioritize laryngeal masks to minimize intubation trauma and accelerate PACU discharge timelines.
- Surgery:Intraoperative ventilation support across open and laparoscopic procedures with varying airway access constraints.
- Intensive Care:Prolonged mechanical ventilation scenarios where tracheal injury prevention and ventilator-associated pneumonia reduction drive specification requirements.
Anesthesia commands the premium price tier. Emergency care is climbing the fastest on volume.
End User:
Customer type fragmentation creates divergent specification demands, with institutional purchasers negotiating framework agreements while dispersed home care settings require simplified, caregiver-friendly designs.
- Hospitals:Integrated delivery networks with centralized procurement functions driving standardization across multi-facility systems. Group purchasing organizations in the United States are displacing individual hospital contracting autonomy through multi-year, single-source agreements.
- Ambulance Services:Mobile emergency medical services requiring compact, field-sterile packaging and rapid-deployment configurations. Prehospital systems face budget constraints that favor disposable over reusable portfolios despite higher per-unit costs.
- Clinics:Outpatient procedural facilities with intermediate acuity levels and limited overnight ventilation capabilities.
- Home Care:Long-term tracheostomy patients and ventilator-dependent individuals requiring caregiver-training-compatible devices with extended wear intervals.
Hospitals anchor procurement value. Ambulance services are gaining share fastest on prehospital system expansion.
Technology:
Supply concentration in cleanroom manufacturing clusters shapes technology accessibility, with disposable device producers leveraging Southeast Asian production scale while digital airway platforms remain concentrated among vertically integrated multinationals.
- Reusable Devices:Autoclavable metal laryngoscopes and silicone airway adjuncts retaining footholds in cost-constrained public hospital systems. Metal laryngoscopes with fiber-optic illumination persist in European and emerging market installations where sterilization infrastructure supports circular economics.
- Disposable Devices:Single-use polymer tubes and supraglottic devices commanding technology segment value pools given infection control mandates. FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern material selection for United States market entry.
- Video Laryngoscopy:Camera-enabled airway visualization systems with disposable blade sheaths creating hybrid procurement patterns. Anesthesiologist training gaps outpace residency curriculum updates, slowing adoption despite clinical evidence of first-pass success improvements.
- Digital Airway Management:Sensor-embedded tubes with pressure transducers and CO2 detection elements generating novel regulatory classification debates. EU MDR extended conformity assessment timelines are compressing European launch schedules relative to FDA-cleared equivalents.
Disposable devices dominate procurement volumes. Digital airway management is where R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems deploy endotracheal tubes for prolonged ventilation at rates exceeding other developed markets, while Southeast Asian procurement networks favor laryngeal masks for ambulatory turnover acceleration.
United States
Aging surgical caseloads and trauma center expansion mandates sustain elevated endotracheal tube utilization. FDA 510(k) premarket notifications for Class II devices enforce rigorous quality benchmarks. Texas and Florida hospital networks are consolidating procurement through multi-year framework agreements with integrated delivery systems.
Germany
Reinforced silicone tracheostomy tubes with extended implantation indications face steep EU MDR conformity assessment delays. The national pharmaceutical regulator enforces extended clinical evidence requirements for Class IIa devices. Bavarian medical device clusters are absorbing compliance cost inflation through quality management system investments.
China
Domestic production of disposable polymer tubes scales to meet hospital procurement volume expansion. NMPA biocompatibility standards per GB regulations govern material selection for market entry. Yangtze River Delta cleanroom manufacturing investments are displacing import dependency for standard airway devices.
Japan
Metal laryngoscopes with fiber-optic illumination retain installed base in cost-conscious public hospital systems. METI industrial standards and PMDA quality benchmarks shape procurement specifications. Kansai region medical device distributors are negotiating exclusive territorial agreements for video laryngoscopy platforms.
Malaysia
New cleanroom facilities target tariff-advantaged export positioning for ASEAN hospital networks. The national medical device authority aligns with ISO 13485 quality management standards. Penang and Selangor manufacturing zones are attracting multinational tube producers seeking Southeast Asian supply chain diversification.
Airway Management Tubes Market Vendor Landscape
Capability concentration sits with vertically integrated multinationals commanding catheter production networks; scale advantage sits with disposable device specialists leveraging Southeast Asian manufacturing clusters. The vendor base organizes around three strategic archetypes: polymer science innovators, critical care distribution anchors, and ambulatory-focused supraglottic specialists. Competitive moves concentrate on backward integration into medical-grade resin supply and captive sterilization facility construction.
Among vertically integrated multinationals, Medtronic and Teleflex Incorporated occupy positions spanning endotracheal and tracheostomy tube portfolios. Smiths Medical exemplifies material science differentiation through reinforced airway designs. These three entities anchor the premium tier where regulatory compliance depth and clinical validation breadth create separation from regional disposable manufacturers.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| Smiths Medical |
| Ambu A/S |
| ConvaTec Group Plc |
| Cook Group Inc. |
| Intersurgical Ltd. |
| Fisher and Paykel Healthcare Corp. Ltd. |
| Flexicare Group Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Malaysian cleanroom facilities is compressing supplier margins while simultaneously accelerating pricing aggression for ASEAN export contracts. Medical-grade PVC and silicone resin feedstock volatility feeds back into procurement behavior, with hospital systems locking multi-year framework agreements to buffer polymer cost swings.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement, with integrated delivery networks negotiating multi-year framework agreements that bundle endotracheal tubes, laryngeal masks, and suction accessories into single-source arrangements. Price differentiation separates FDA-cleared Class II devices from ISO-certified economy tiers, with volume scale and subglottic suction capability commanding premium positioning. Cost compression in standard cuffed tubes is intensifying because Yangtze River Delta manufacturers are scaling disposable polymer output. Ambulance services exhibit highest price sensitivity due to municipal budget constraints, while intensive care units prioritize clinical performance over unit economics.
Supply Chain Analysis
Export-control regimes on medical-grade silicone formulations limit technology transfer to non-ASEAN manufacturing zones, constraining cleanroom capacity expansion outside Malaysia, China, and Germany. Raw material sourcing draws from petrochemical complexes in the US Gulf Coast, Singapore's Jurong Island, and Rotterdam's chemical hub. Single-source sterilization facility dependencies in Penang and Selangor create bottleneck vulnerability for Southeast Asian production clusters. Distribution runs through group purchasing organizations in the United States and hospital procurement consortiums in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in digital airway management, where sensor-embedded tube convergence creates specialized niches beyond incumbent polymer science dominance. Ambulatory surgical center procurement decentralization is multiplying addressable customer accounts.
For Market Incumbents: Build regulatory compliance moats through parallel FDA 510(k) and EU MDR technical documentation investments that emerging manufacturers cannot replicate. Backward integration into medical-grade resin compounding secures margin buffers against petrochemical volatility. Threat substitution from video laryngoscopy platforms demands software companion development to maintain placement procedure influence. For New Entrants and Emerging Players: Pursue ASEAN hospital procurement networks through tariff-advantaged Malaysian manufacturing platforms that bypass incumbent distribution lock-in. Prehospital emergency care segments offer lowest penetration resistance due to municipal tender fragmentation. Go-to-market leverage rests on color-coded rapid-deployment packaging that reduces EMS field decision latency. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among disposable device specialists with GPO contract visibility and sterilization facility ownership. Five-to-ten year viability favors manufacturers with dual FDA-CE marking pathways and silicone material science differentiation. Acquisition targets should demonstrate sensor-integration R&D pipelines. Watch for EU MDR conformity assessment timeline compression as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR extended timelines favor established quality management systems in Bavarian clusters. |
| Hospital System Partnership | Multi-year framework agreements with Texas and Florida IDNs lock out competing suppliers. |
| Software Companion Development | Digital airway platforms with EMR interoperability resolve legacy integration friction for ICU adoption. |
| Backward Integration into Resin | Captive medical-grade PVC supply insulates margin buffers from petrochemical price swings. |
| Reimbursement Strategy | Ventilator-associated pneumonia reduction claims for subglottic drainage tubes secure bundled payment inclusion. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with critical care anesthesiologists, hospital purchasing committee directors, biomedical engineers specializing in airway devices, and group purchasing organization contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and technology dimensions.
Calibration against historical hospital admission trends and surgical volume projections shaped the analytical framework across the modeling period. Segmentation dimensions modeled include product type, clinical application setting, end-user facility category, and technology tier. CAGRs were derived from elasticity-adjusted demand curves incorporating aging surgical caseloads and trauma center expansion mandates. Forecast inputs included ambulatory surgical center buildout rates and prehospital system procurement consolidation patterns.
Sensitivities concentrate around EU MDR implementation delays, polymer feedstock price volatility, and video laryngoscopy training gap closure rates. Forecasts reflect documented assumptions on regulatory timeline stability and cleanroom manufacturing capacity expansion. Material shifts in FDA classification debates for sensor-embedded devices would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Japan Respiratory Devices Market