
 Endoscopy Equipment and Software Market | 2026-2036
Endoscopy Equipment and Software Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Equipment and Software Market Intelligence
The high-end segment, characterized by 3D visualization and advanced imaging modalities, is consolidating around integrated system providers. Olympus Corporation leverages its extensive portfolio of flexible endoscopes and imaging systems to maintain a dominant market position. Karl Storz SE & Co. KG specializes in rigid endoscopes and integrated operating room solutions. Boston Scientific Corporation competes through its strong presence in therapeutic devices used during gastrointestinal procedures.
Endoscopy equipment comprises medical devices designed for visualizing internal organs and cavities without extensive surgery. These systems typically integrate a flexible or rigid tube with high-resolution CMOS image sensors and fiber optic illumination to transmit images to a display. Software components manage image capture, patient data, and provide diagnostic assistance. Flexible endoscopes continue to command the largest share, driven by their widespread use in gastrointestinal applications, while pulmonology and urology show significant expansion.
Market access is governed by stringent regulatory approvals from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) under its Medical Device Regulation (MDR). In China, the National Medical Products Administration (NMPA) sets rigorous standards for device registration and clinical data requirements, shaping product development timelines. Stakeholders must now decide how to balance investment in AI-driven software features against the rising cost of compliance with evolving global device regulations.
Market Dynamics
The central dynamic shaping the endoscopy market is the tension between rapid innovation in AI-powered diagnostic software and the increasing cost and complexity of navigating stringent global medical device regulations from bodies like the FDA and NMPA.
Growth Catalysts
- Government Investment:China's national policy to modernize hospital diagnostic capabilities provides a significant catalyst, funding the procurement of advanced endoscopy systems and expanding healthcare access in underserved regions.
- Ambulatory Surgical Centers:The expansion of Ambulatory Surgical Centers creates demand for efficient, minimally invasive diagnostic tools, favoring flexible endoscopes and systems with rapid procedural workflows for outpatient settings.
- AI-Powered Diagnostics:The integration of artificial intelligence into endoscopy software enhances procedural accuracy by helping clinicians detect abnormalities, improving diagnostic yields and streamlining workflow efficiency within gastroenterology and pulmonology departments.
Market Restraints
- Regulatory Compliance Costs:The high cost and lengthy timelines associated with achieving compliance under regulations like the European Union's Medical Device Regulation (MDR) act as a significant barrier to market entry and product updates.
- System Interoperability:A lack of standardization creates technical challenges in integrating new endoscopy software from one vendor with a hospital's existing electronic health record (EHR) and picture archiving systems from another.
- Component Supply Concentration:The market's reliance on a limited number of suppliers for critical components like high-resolution CMOS image sensors creates potential supply chain vulnerabilities and pricing pressures for equipment manufacturers.
Strategic Opportunities
- Emerging Clinical Applications:While gastrointestinal procedures remain dominant, significant white space exists in expanding the use of specialized endoscopes in high-growth fields such as pulmonology, urology, and gynecology.
- AI-Enhanced Visualization:There is a clear opportunity to combine 3D visualization with AI-driven software, creating next-generation platforms that can offer predictive analytics and real-time guidance during complex therapeutic procedures.
- Single-Use Endoscopes:Developing and marketing sterile, single-use endoscopes for specific procedures addresses hospital concerns about cross-contamination and the high cost of reprocessing, opening a new consumables-based revenue stream.
Industry Challenges
- Data Security and Privacy:As endoscopy systems become more connected and reliant on AI software, ensuring compliance with patient data privacy regulations like HIPAA in the US presents a continuous operational challenge for developers.
- Clinician Training Gap:The rapid introduction of advanced features like 3D imaging and AI-assisted diagnostics creates a challenge in training a sufficient number of clinicians to use these new technologies effectively and to their full potential.
- Legacy System Integration:Hospitals face significant operational hurdles and costs when attempting to integrate new, feature-rich endoscopy towers and software platforms with older, legacy IT infrastructure and data management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Equipment and Software Market |
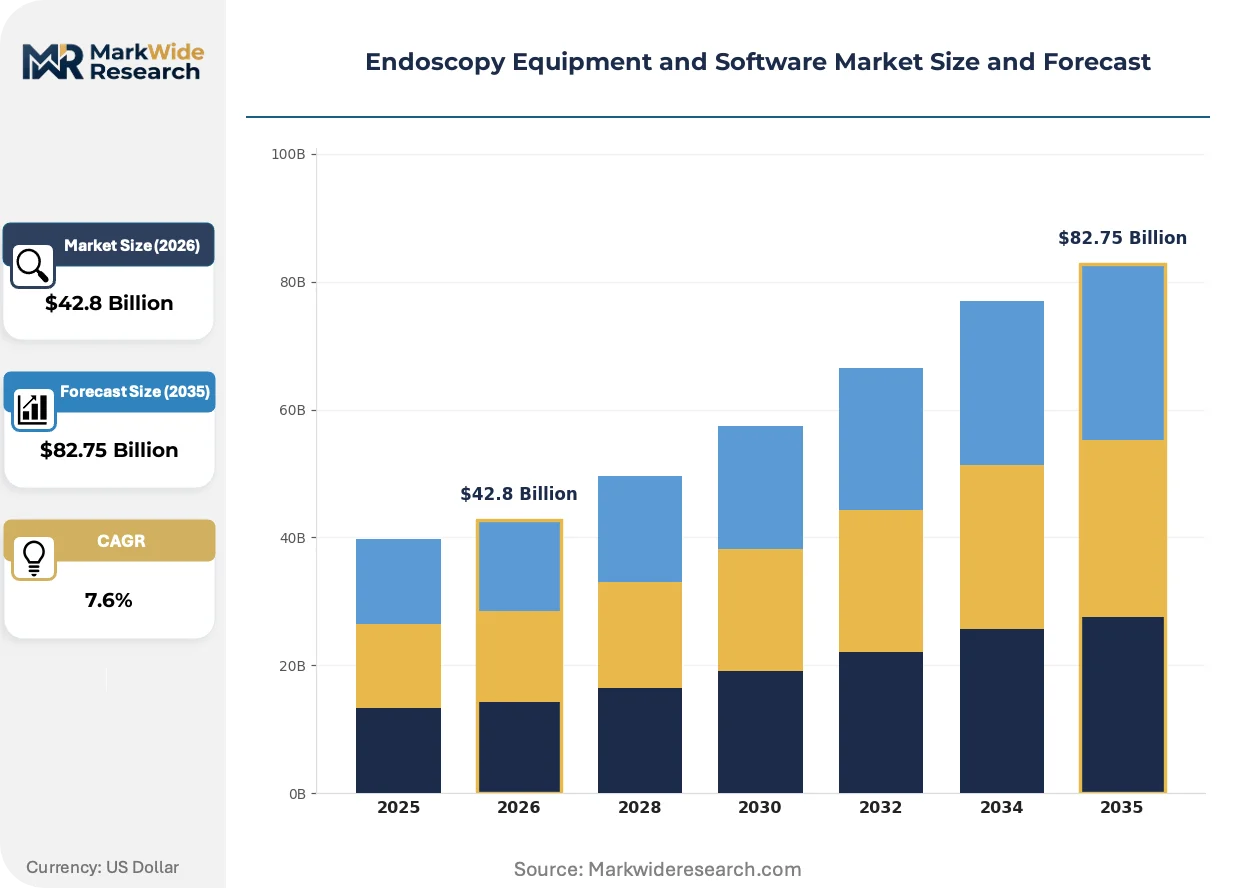
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Endoscopic Cameras, Light Sources Technology: High-Definition Imaging, 3D Visualization, Narrow Band Imaging, Autofluorescence, Digital Enhancement Application: Gastrointestinal, Pulmonology, Urology, Gynecology, Orthopedics End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Centers, Specialty Clinics |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Fujifilm Holdings Corporation, Boston Scientific Corporation, Stryker Corporation, Medtronic plc, HOYA Corporation, Smith & Nephew plc, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Equipment and Software Market Strategic Shifts & Innovations
The evolution of endoscopy is defined by the convergence of device miniaturization with data-driven diagnostics. This development transforms endoscopes from simple visualization tools into integrated platforms that support both diagnosis and therapy, enhancing clinical outcomes.
Disposable, single-use endoscopes leverage miniaturized CMOS sensors and advanced polymers to eliminate cross-contamination risks. Ambulatory Surgical Centers and outpatient clinics are adopting these devices for high-volume, lower-complexity procedures where rapid turnover is critical. This shift towards disposables is electrifying the supply chain, creating demand for high-volume component manufacturing over traditional repair and sterilization logistics.
The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence requirements and post-market surveillance for all medical devices. This regulation increases the time and cost associated with bringing new equipment and software to the European market. Manufacturers of high-end systems with integrated AI are most affected, needing extensive validation data on algorithm performance to secure CE marking.
Hospitals are moving away from purchasing standalone components toward acquiring fully integrated endoscopy suites from a single provider. This trend favors large vendors with comprehensive portfolios spanning scopes, imaging processors, software, and therapeutic instruments, as it simplifies procurement and service. This shift is most prominent in new hospital construction and modernization projects, particularly in China.
Endoscopy Equipment and Software Market Segmentation
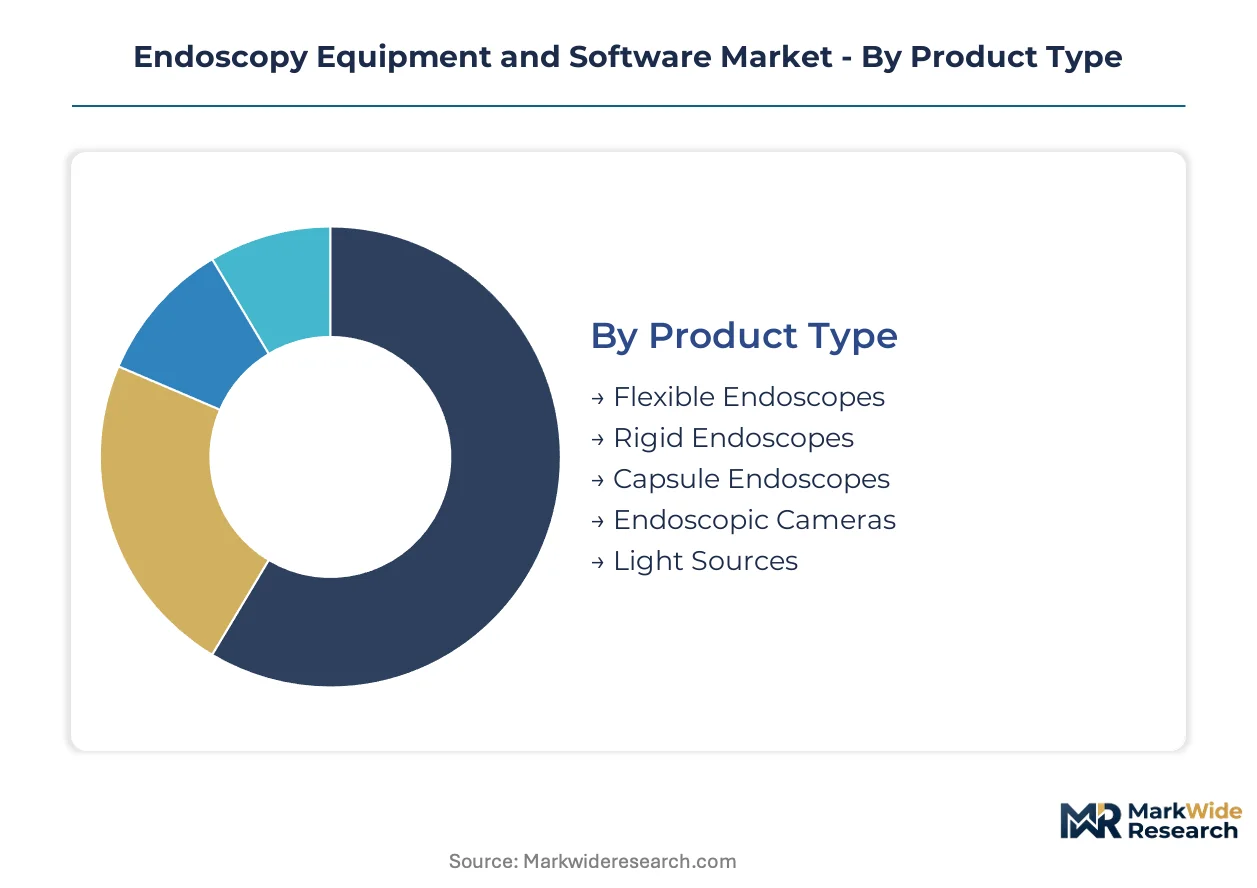
The Endoscopy Equipment and Software Market segments reflect diverse clinical requirements and technological advancements. Understanding these classifications reveals how different product types and technologies address specific diagnostic and therapeutic needs, influencing regulatory pathways and procurement strategies across end-user settings.
Product Type:
Navigating the varied regulatory landscape dictates product development for different endoscopy equipment types, with bodies like the US FDA, European EMA (under MDR), and China's NMPA imposing distinct requirements for market approval.
- Flexible Endoscopes:These devices incorporate a bendable tube with integrated optics and channels for instruments, enabling navigation through complex anatomical structures. Demand concentrates in gastroenterology applications, driven by widespread use in diagnostic and therapeutic procedures like colonoscopy and gastroscopy.
- Endoscopic Cameras:These systems utilize high-resolution CMOS image sensors to capture and transmit real-time video, forming the core visualization component of an endoscopy suite. Hospitals and Ambulatory Surgical Centers prioritize these cameras for their enhanced image clarity and integration with AI-powered diagnostic software.
- Rigid Endoscopes:Characterized by a fixed, non-flexible tube, these are primarily used in surgical procedures requiring a stable line of sight.
- Capsule Endoscopes:Ingestible devices containing a miniature camera, they offer non-invasive visualization of the small bowel.
- Light Sources:These provide illumination for endoscopic procedures, ensuring clear visualization of internal organs and cavities.
Leading the category by volume: Flexible Endoscopes. Growing fastest: Capsule Endoscopes.
Technology:
The cost tiering of endoscopy technologies shapes market adoption, with advanced imaging modalities commanding premium pricing due to their diagnostic superiority and integration complexity.
- 3D Visualization:This technology provides clinicians with a stereoscopic view of the surgical field, enhancing depth perception and spatial orientation during complex procedures. Integrated system providers offer these advanced platforms to high-end surgical centers for precision interventions.
- High-Definition Imaging:Delivering superior resolution and clarity, these systems are foundational for accurate diagnosis and detailed procedural guidance across all endoscopy applications. Hospitals standardize on HD imaging for improved diagnostic yields and clinician confidence.
- Narrow Band Imaging:This optical technique enhances the visualization of mucosal patterns and vascular structures, aiding in the detection of early-stage lesions.
- Autofluorescence:Utilizing specific light wavelengths, this technology helps identify abnormal tissue by detecting changes in natural tissue fluorescence.
- Digital Enhancement:Software-based algorithms improve image quality and highlight subtle abnormalities, streamlining diagnostic workflows.
High-Definition Imaging forms the foundational layer, while 3D Visualization represents significant technological advancement.
Application:
Procedure volume and specific clinical needs define the application segments, driving demand for specialized endoscopic tools tailored to distinct anatomical areas and disease states.
- Gastrointestinal:This segment encompasses diagnostic and therapeutic procedures within the esophagus, stomach, small intestine, and colon. It accounts for the largest share of endoscopic procedures due to the prevalence of digestive disorders.
- Pulmonology:Involving bronchoscopy and related procedures, this application focuses on visualizing the airways and lungs for diagnosis and intervention. This field shows significant expansion driven by lung cancer screening and respiratory disease management.
- Urology:Endoscopic procedures here address conditions of the urinary tract, including the bladder, ureters, and kidneys.
- Gynecology:This application utilizes endoscopes for examining the female reproductive organs, often for diagnostic laparoscopy or hysteroscopy.
- Orthopedics:Arthroscopy is a key orthopedic application, allowing minimally invasive visualization and treatment of joint conditions.
Gastrointestinal procedures consistently generate the largest procedural volume, with Pulmonology applications showing considerable expansion.
End User:
Procurement patterns and infrastructure capabilities differentiate end-user segments, influencing the type and scale of endoscopy equipment acquired.
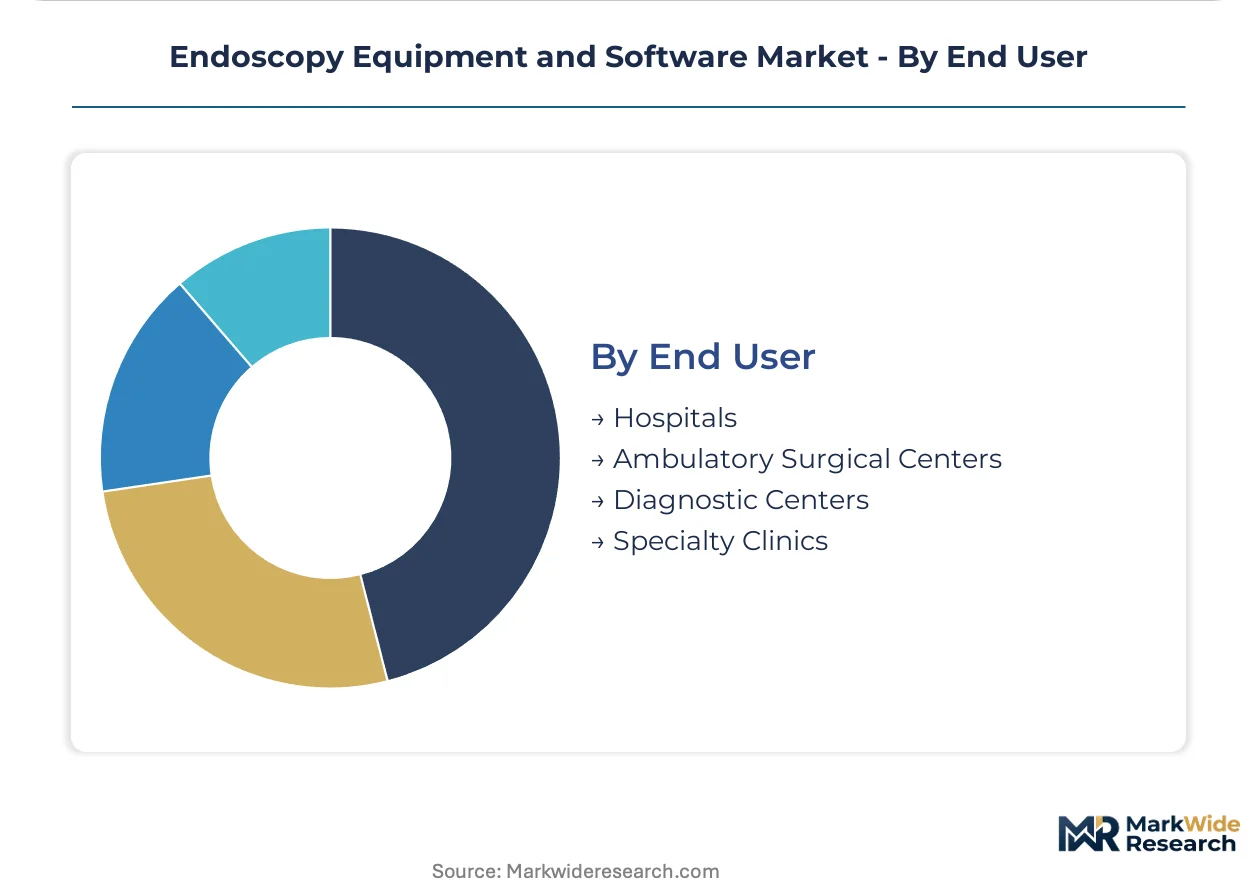
- Hospitals:These facilities represent the largest end-user segment, procuring a wide range of endoscopy equipment and integrated suites for diverse specialties and high patient volumes. Hospitals seek comprehensive solutions that can integrate with existing IT infrastructure.
- Ambulatory Surgical Centers:ASCs focus on outpatient procedures, driving demand for efficient, minimally invasive tools and single-use endoscopes. These centers prioritize rapid patient turnover and cost-effectiveness.
- Diagnostic Centers:These centers specialize in diagnostic imaging and procedures, often requiring advanced visualization and software capabilities.
- Specialty Clinics:Focused on specific medical disciplines, these clinics adopt tailored endoscopic solutions relevant to their area of expertise.
Hospitals remain the primary procurement channel for complex systems, while Ambulatory Surgical Centers are increasingly driving demand for efficient, outpatient solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical technology cluster drives innovation in endoscopy equipment and software. This region benefits from significant venture capital and academic research partnerships. Its influence extends to advanced diagnostic tool development and integrated surgical platforms.
United States
United States demand for endoscopy equipment stems from a high prevalence of chronic digestive diseases and a strong preference for minimally invasive procedures. The US Food and Drug Administration (FDA) approvals significantly shape product development timelines and market entry for new devices. Silicon Valley and Boston are key hubs for medical device innovation, fostering significant AI-powered software development.
Germany
Germany exhibits robust demand for advanced endoscopy systems, supported by its strong healthcare infrastructure and focus on precision diagnostics. European Medical Device Regulation (MDR) compliance significantly impacts market access and product updates for manufacturers operating here. Southern Germany, particularly the Tuttlingen region, is a renowned center for precision medical instrument manufacturing and research.
China
China's market expansion is driven by substantial government investment in healthcare modernization and efforts to expand diagnostic access in underserved regions. The National Medical Products Administration (NMPA) sets rigorous standards for device registration and clinical data requirements. Beijing and Shanghai are key centers for medical device research and development, attracting significant domestic and international investment.
Japan
Japan's market for endoscopy equipment is characterized by an aging population and a high demand for advanced diagnostic imaging and therapeutic endoscopes. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals and post-market surveillance, ensuring high quality standards. Tokyo and Osaka host major medical device manufacturers and research institutions, fostering technological leadership.
United Kingdom
United Kingdom adoption of endoscopy equipment is increasing due to the growing preference for minimally invasive surgery and a focus on early disease detection. Compliance with the European Medical Device Regulation (MDR) remains crucial for market entry for many devices, alongside national health standards. The "Golden Triangle" of London, Oxford, and Cambridge fosters significant medical technology innovation and research collaborations.
Endoscopy Equipment and Software Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and regulatory compliance requirements. The market structure exhibits consolidation within high-end integrated systems, while fragmentation exists in specialized componentry and regional distribution. Strategic archetypes include integrated solution providers, offering comprehensive suites; niche technology specialists, focusing on specific applications; and regional distributors, managing localized market access. Portfolio diversification and strategic partnerships are dominant competitive moves among established participants, alongside targeted mergers and acquisitions to expand geographic reach or technological capabilities.
On the premium-tier vector, Olympus Corporation exemplifies a global leader in flexible endoscopes and integrated imaging systems, maintaining a broad portfolio. Karl Storz SE & Co. KG represents a specialized German manufacturer focusing on rigid endoscopes and comprehensive operating room solutions. Boston Scientific Corporation occupies a significant position as a major American player, particularly in therapeutic devices used during gastrointestinal procedures. These entities anchor innovation in advanced visualization and minimally invasive surgical tools, driving technological advancements across the market. Their focus on high-value segments shapes overall market dynamics.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Fujifilm Holdings Corporation |
| Boston Scientific Corporation |
| Stryker Corporation |
| Medtronic plc |
| HOYA Corporation |
| Smith & Nephew plc |
| Johnson & Johnson |
Cost & Logistics Intelligence
Hospitals, as primary procurement channels for complex systems, influence pricing models towards integrated solutions rather than standalone components. This demand for comprehensive suites allows vendors to bundle premium technologies.
Pricing Analysis
Value-based pricing anchors advanced endoscopy systems to enhanced diagnostic yields and workflow efficiencies. Price differentiation stems from the integration of 3D visualization and the level of AI-powered diagnostic software. Regulatory compliance costs, particularly under EMA MDR, exert upward pricing pressure on manufacturers. Ambulatory Surgical Centers exhibit higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
Workforce availability in Southern Germany supports the production of precision medical instruments, including rigid endoscopes. The supply chain draws from specific countries like Japan and South Korea for high-resolution CMOS image sensors. A structural risk exists in the market's reliance on a limited number of suppliers for these critical components. Downstream distribution is increasingly shifting towards direct sales of integrated suites to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Endoscopy Equipment and Software Market is a supply-constrained story, with limited high-volume component manufacturing for disposable devices propping pricing.
For Market Incumbents: Deploy portfolio diversification across flexible and rigid endoscopes to mitigate risks from evolving regulatory compliance costs. Invest in advanced AI-driven software features for existing platforms, addressing the clinician training gap. Strategic partnerships with therapeutic device specialists can broaden market reach and offer comprehensive solutions.
For New Entrants and Emerging Players: Single-use endoscopes represent a technology-first wedge into the market, addressing hospital concerns about cross-contamination. Target Ambulatory Surgical Centers and high-volume, lower-complexity procedures for rapid market penetration. Focus go-to-market strategies on demonstrating cost-effectiveness and simplified reprocessing logistics.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to capitalize on technological advancements and market consolidation. Look for niche technology specialists in AI-powered diagnostics or high-volume disposable component manufacturing. A key signal to watch is the accelerated adoption rate of single-use endoscopes in outpatient settings.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Development | Enhances diagnostic accuracy and workflow efficiency for clinicians. |
| Single-Use Endoscope Launch | Addresses cross-contamination concerns in Ambulatory Surgical Centers. |
| Regulatory Compliance Investment | Secures market access under stringent EMA MDR and NMPA standards. |
| Integrated Suite Expansion | Simplifies procurement for hospitals seeking comprehensive solutions. |
| Therapeutic Device Partnership | Broadens offerings for gastrointestinal procedures, complementing visualization tools. |
Research Approach
FDA approvals, EMA MDR guidelines, and NMPA device registration data formed the secondary backbone of this analysis. This was complemented by primary interviews with industry stakeholders, including clinicians, hospital purchasing managers, regulatory affairs leads, and R&D directors. A rigorous process of bottom-up and top-down triangulation validated all market data points.
Historical trendline analysis informed the projection of market growth across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical performance and anticipated technological shifts. Key inputs included government investment in healthcare modernization and evolving regulatory pathways for AI-powered diagnostics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or supply chain disruptions. These forecasts reflect current market assumptions regarding technology adoption and healthcare investment. Material deviation in global medical device regulations or critical component availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
China Arthroscopy Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
AI in Endoscopy Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Gastroscopes Market
Endoscopy
Global Endoscopes Market
Endoscopy
Disposable Bronchoscopes Market