
 Global Neuroendoscopy Market | 2026-2036
Global Neuroendoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuroendoscopy Market Foresight
The gap between premium visualization systems and commodity endoscopes is broadening. Karl Storz leverages its rigid endoscope specialization to dominate high-definition surgical suites. Olympus Corporation sustains leadership in flexible platforms through deep channel control across Japanese university hospitals. Medtronic competes by anchoring its portfolio to integrated navigation and image enhancement ecosystems.
Neuroendoscopy refers to the use of specialized endoscopic instruments for visualization and intervention within the ventricular system and subarachnoid spaces of the brain, typically employing rigid rod-lens optics or fiberoptic bundles with working channels of 2-6 millimeters and irrigation ports to enable biopsy, fenestration, or third ventriculostomy. Rigid neuroendoscopes occupy the core revenue pool due to optical clarity and instrument stability during skull base surgery. Flexible neuroendoscopes represent the fastest-expanding category as they navigate tortuous ventricular anatomy during complex hydrocephalus treatment. High-definition visualization technology leads the technology segment because surgeons require pixel resolution sufficient to distinguish vascular structures at submillimeter scale.
FDA 510(k) clearance pathways shape product entry timelines for US manufacturers, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on neuroendoscope reprocessing validations. Japan's PMDA maintains rigorous quality management system audits that filter out lower-tier suppliers from its neurosurgical device market. Stakeholders must monitor how fluorescence-guided endoscopy standards evolve across FDA and EMA frameworks to anticipate which visualization platforms gain preferential reimbursement.
Market Dynamics
Reimbursement compression for open craniotomy procedures is accelerating hospital procurement of minimally invasive visualization platforms across neurosurgical suites. Payers in Germany, Japan, and the United States now structure episode-based payments that favor ventricular endoscopy over traditional approaches.
Growth Catalysts
- EU MDR reprocessing standards:Stricter sterilization validation requirements for reusable neuroendoscopes are filtering out low-quality suppliers and consolidating demand around premium manufacturers with validated reprocessing protocols.
- Japanese university hospital procurement:Centralized purchasing through METI-coordinated medical device frameworks is standardizing flexible neuroendoscope specifications across Tokyo, Osaka, and Kyoto neurosurgical centers.
- Fluorescence-guided tumor delineation:5-aminolevulinic acid visualization protocols are expanding the addressable case volume for neuroendoscopic biopsy beyond traditional anatomical limits.
Market Restraints
- Rod-lens sapphire substrate costs:Price volatility in synthetic sapphire crystal supply from Russian and Ukrainian sources is compressing margins for rigid neuroendoscope manufacturers dependent on high-purity optical components.
- Single-use flexible endoscope substitution:Bronchoscopy and urology markets are demonstrating rapid adoption of disposable flexible platforms, creating precedent pressure on neuroendoscopy reprocessing economics.
- PMDA quality management audits:Japan's six-month minimum audit timelines for foreign manufacturers create structural barriers to market entry independent of clinical evidence requirements.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Recent regulatory harmonization with FDA 510(k) clearance documentation is reducing time-to-market for manufacturers with existing US approvals.
- Augmented reality navigation convergence:Integration of electromagnetic tracking with high-definition visualization is creating premium system bundles that command pricing power in skull base surgery applications.
- Direct hospital system contracting:Bypassing traditional distributor networks through dedicated sales forces targeting IDN procurement committees in the United States and Germany.
Industry Challenges
- Neuroendoscopic fellowship training capacity:The specialized skill set for third ventriculostomy and intraventricular navigation remains concentrated in fewer than 200 global training programs, limiting procedure volume expansion.
- ISO 13485:2016 transition compliance:Medical device quality management system recertification deadlines are consuming engineering resources at mid-tier manufacturers during a critical product development window.
- Legacy navigation system integration:Surgical suites with installed StealthStation or Brainlab platforms require proprietary interface development for new visualization hardware, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuroendoscopy Market |
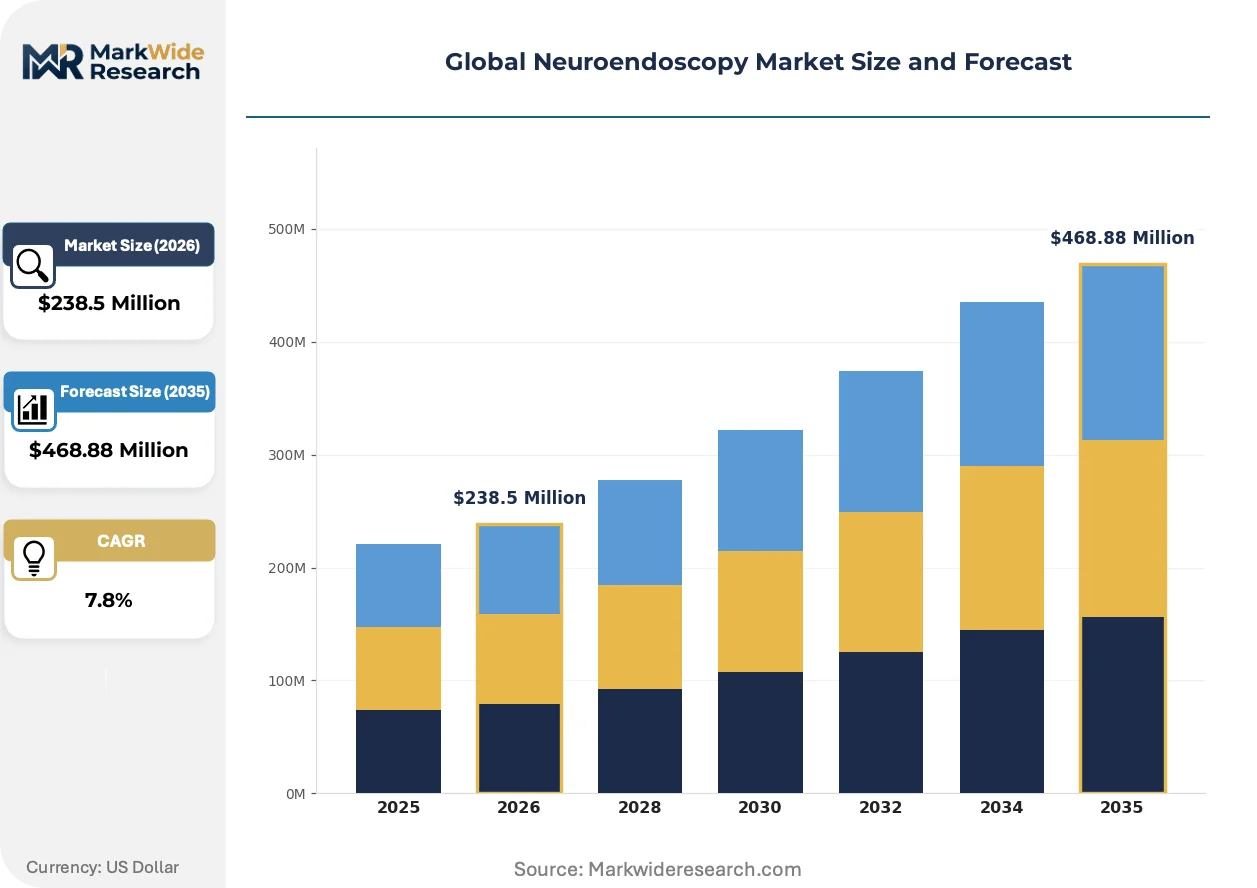
| Market Size in 2026 | $238.5 Million |
| Market Size in 2035 | $468.88 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Neuroendoscopes, Flexible Neuroendoscopes, Ultra-thin Neuroendoscopes, Fiberoptic Neuroendoscopes, Others Technology: High-definition Visualization, 3D Endoscopy, Fluorescence-guided Endoscopy, Wireless Transmission, Image Enhancement Application: Hydrocephalus Treatment, Brain Tumor Biopsy, Cyst Fenestration, Skull Base Surgery, Intracranial Hemorrhage Management End User: Neurosurgical Centers, Specialty Clinics, Research Institutes, University Hospitals, Day-care Surgical Facilities |
| Companies Covered | Karl Storz, B. Braun SE, Olympus Corporation, Medtronic, Stryker, adeor medical AG, Ackermann Instrumente GmbH, Clarus Medical LLC, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuroendoscopy Market Shifts & Advancements
Visualization platforms are converging with surgical navigation and fluorescence detection in ways that redefine hardware procurement specifications. Three forces are compressing the traditional boundaries between standalone device categories.
4K-resolution rod-lens systems with integrated near-infrared fluorescence detection are unifying tumor visualization and vascular mapping into single-procedure workflows. Major neurosurgical centers in Germany and Japan are replacing standalone endoscopes with these hybrid platforms during capital equipment refresh cycles. The technology is unifying what were previously separate capital purchases, compressing vendor relationships and reducing interoperability tolerance.
MDR Article 10 clinical evidence requirements for reusable device reprocessing are forcing manufacturers to sponsor prospective sterilization validation studies. The regulation is extending product development timelines by 12-18 months for rigid neuroendoscope portfolios. European notified bodies are prioritizing submissions from manufacturers with established ISO 17664 reprocessing instruction dossiers, favoring incumbents over new entrants.
Hospital procurement committees are consolidating visualization hardware decisions under single-source vendor agreements that bundle endoscopes, cameras, and navigation. German university hospitals and US integrated delivery networks are leading this concentration, displacing the previous best-of-breed purchasing pattern. The shift is most visible in skull base surgery service lines where capital coordination across ENT and neurosurgery departments has become a strategic priority.
Global Neuroendoscopy Market Segmentation
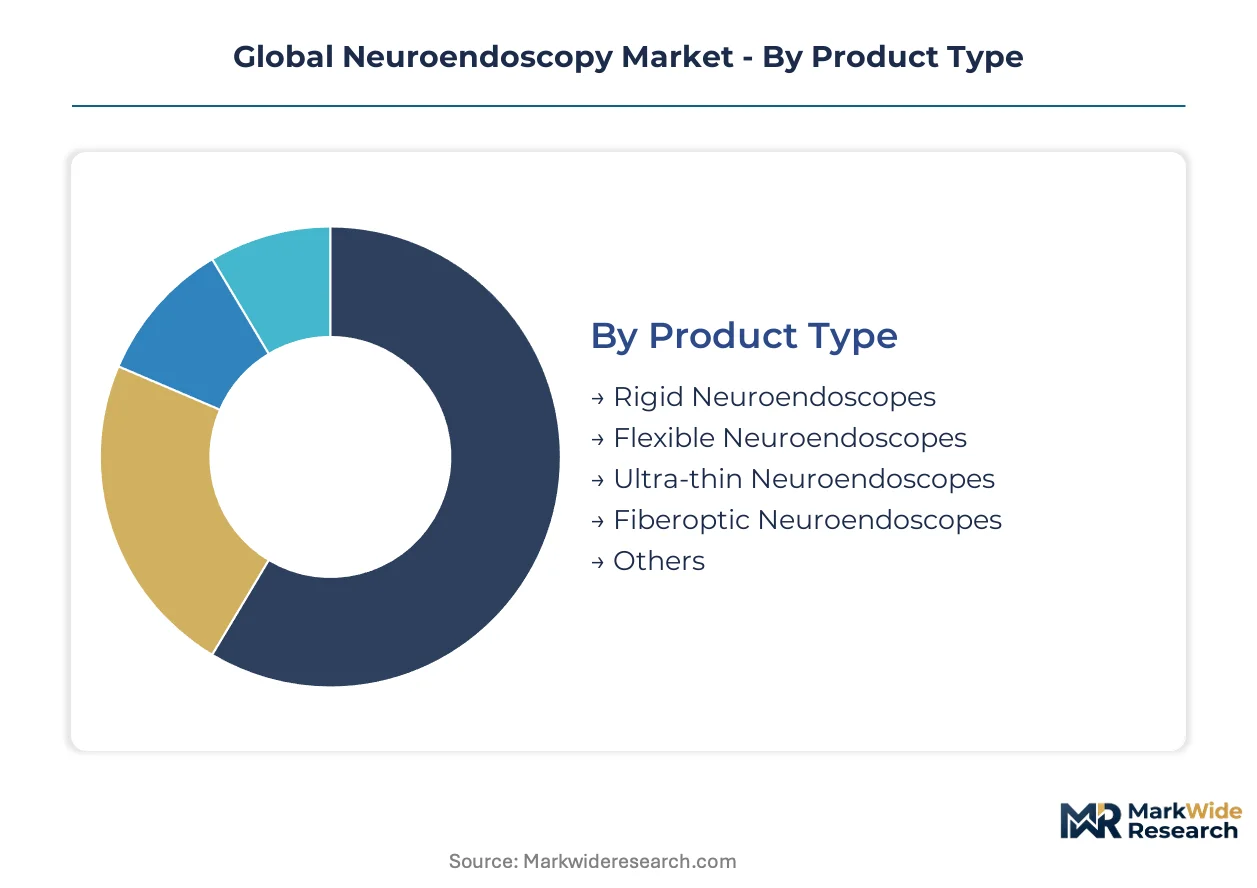
Neuroendoscopy market segmentation reveals how regulatory pathways and reimbursement structures fragment procurement decisions across product categories. Each dimension carries distinct certification burdens that determine which manufacturers can compete in specific clinical settings.
Product Type:
FDA 510(k) clearance timelines vary significantly across optical architectures, with rigid rod-lens systems facing shorter validation cycles than flexible platforms requiring biocompatibility testing for steerable components. EU MDR reprocessing standards impose additional sterilization validation requirements on reusable designs.
- Rigid Neuroendoscopes:Rod-lens optical systems deliver superior image clarity and instrument stability through fixed straight-line geometries. German neurosurgical centers in Munich and Berlin prioritize these platforms for skull base procedures where optical precision outweighs navigation flexibility. Sapphire substrate supply constraints from Eastern European sources are compressing margins for manufacturers dependent on high-purity optical components.
- Flexible Neuroendoscopes:Steerable fiberoptic or electronic platforms navigate tortuous ventricular anatomy during complex hydrocephalus treatment. Japanese university hospitals in Tokyo and Osaka are standardizing procurement specifications through METI-coordinated frameworks. PMDA quality management audits create six-month minimum entry barriers for foreign suppliers seeking access to this high-value segment.
- Ultra-thin Neuroendoscopes:Sub-2mm diameter designs enable minimally invasive access through narrow anatomical corridors.
- Fiberoptic Neuroendoscopes:Bundle-based transmission systems offer durability advantages in high-turnover surgical environments.
- Others:Hybrid and specialty configurations addressing niche anatomical applications.
Leading the category by volume: Rigid Neuroendoscopes. Growing fastest: Flexible Neuroendoscopes.
Technology:
Technology tiering follows capital equipment refresh cycles, with premium visualization platforms commanding integrated procurement bundles while standalone upgrades face longer sales cycles.
- High-definition Visualization:1080p and 4K resolution systems provide pixel density sufficient for submillimeter vascular discrimination. US integrated delivery networks are consolidating camera-head purchases under single-source vendor agreements that bundle endoscopes with navigation ecosystems. Reimbursement compression for open procedures is accelerating hospital procurement of these platforms.
- Fluorescence-guided Endoscopy:Near-infrared detection systems enable 5-aminolevulinic acid tumor delineation beyond traditional anatomical limits. German centers are replacing standalone endoscopes with hybrid platforms during capital refresh cycles. FDA and EMA framework evolution for fluorescence protocols will determine which visualization platforms gain preferential reimbursement.
- 3D Endoscopy:Stereoscopic depth perception systems reduce surgical error rates in complex ventricular navigation.
- Wireless Transmission:Cable-free designs reduce OR setup complexity and contamination risks.
- Image Enhancement:Digital processing algorithms for contrast optimization and noise reduction.
Dominating capital budgets: High-definition Visualization. Expanding most quickly: Fluorescence-guided Endoscopy.
Application:
Procedure volume distribution reflects epidemiological patterns and reimbursement differentials across neurological conditions.
- Hydrocephalus Treatment:Third ventriculostomy and shunt placement constitute the highest-volume neuroendoscopic indication globally. Pediatric neurosurgical units in US children's hospitals maintain dedicated flexible endoscope inventories for CSF diversion procedures. Fellowship training capacity constraints limit procedure volume expansion.
- Brain Tumor Biopsy:Minimally invasive tissue acquisition for histopathological diagnosis. Japanese university hospitals are expanding case volumes through fluorescence-guided protocols that extend anatomical reach.
- Cyst Fenestration:Endoscopic opening of intracranial cystic structures.
- Skull Base Surgery:Transnasal and transcranial approaches to anterior and middle fossa lesions.
- Intracranial Hemorrhage Management:Evacuation of ventricular and parenchymal blood collections.
Highest procedure count: Hydrocephalus Treatment. Steepest volume trajectory: Brain Tumor Biopsy.
End User:
Customer concentration varies by procurement authority, with centralized purchasing systems in Germany and Japan favoring manufacturers with dedicated hospital sales forces.
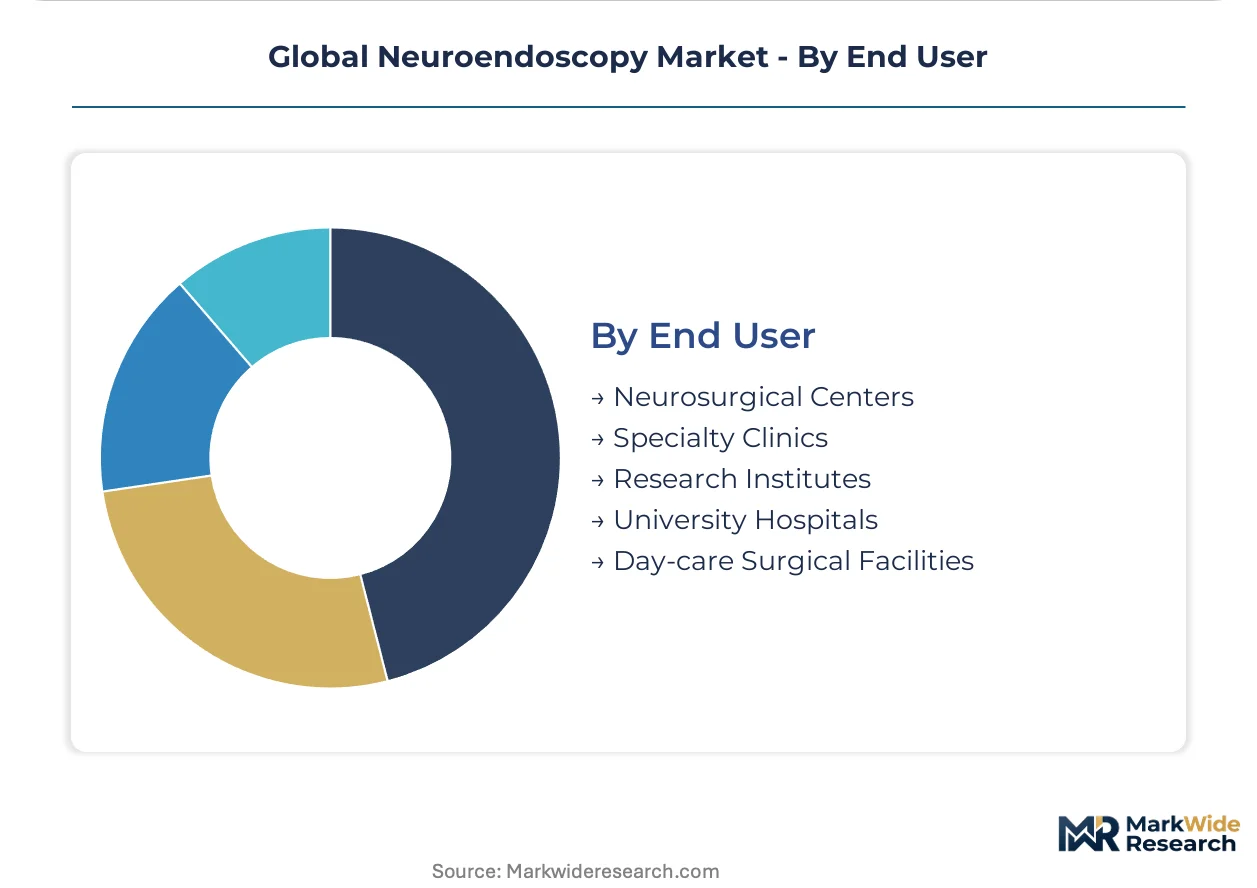
- Neurosurgical Centers:High-volume dedicated facilities with specialized fellowship-trained staff. German centers in Heidelberg and Hamburg anchor European demand for premium rigid platforms with integrated navigation.
- University Hospitals:Academic medical centers combining clinical service with research and training missions. US IDNs and German university hospitals are consolidating visualization hardware decisions under cross-departmental capital committees.
- Specialty Clinics:Focused outpatient and short-stay surgical facilities.
- Research Institutes:Preclinical and translational investigation centers.
- Day-care Surgical Facilities:Ambulatory settings with limited capital equipment budgets.
Primary volume concentration: Neurosurgical Centers. Procurement consolidation advancing fastest: University Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European neuroendoscopy procurement through its concentration of university neurosurgical centers and rigid endoscope manufacturing. Japanese university hospitals in Tokyo and Osaka standardize flexible platform specifications through centralized METI-coordinated frameworks. US integrated delivery networks consolidate visualization hardware decisions under cross-departmental capital committees spanning neurosurgery and ENT departments.
United States
US children's hospitals maintain dedicated flexible endoscope inventories for pediatric hydrocephalus procedures. FDA 510(k) clearance pathways shape product entry timelines for domestic manufacturers. Boston and Philadelphia neurosurgical centers anchor East Coast demand for high-definition visualization platforms with integrated navigation.
Germany
German neurosurgical centers in Heidelberg and Hamburg prioritize rigid rod-lens platforms for skull base surgery. EU MDR Article 10 clinical evidence requirements extend product development timelines by 12-18 months for reusable device reprocessing validations. The Munich-Berlin corridor concentrates procurement authority for premium visualization systems.
Japan
Japanese university hospitals expand fluorescence-guided tumor biopsy volumes beyond traditional anatomical limits. PMDA quality management system audits impose six-month minimum entry barriers for foreign manufacturers. Tokyo and Osaka neurosurgical centers standardize flexible neuroendoscope specifications through METI-coordinated medical device frameworks.
Brazil
Brazilian neurosurgical centers access faster market entry through ANVISA regulatory harmonization with FDA 510(k) documentation. The country's national pharmaceutical regulator reduces clearance timelines for manufacturers with existing US approvals. São Paulo anchors South American demand for minimally invasive intracranial visualization platforms.
United Kingdom
UK neurosurgical centers navigate EU MDR transition requirements for reusable endoscope sterilization validations. The NHS episode-based payment structures favor ventricular endoscopy over open craniotomy approaches. London and Manchester university hospitals consolidate procurement decisions under single-source vendor agreements.
Global Neuroendoscopy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical architecture specialization and reprocessing validation capabilities. The vendor base stratifies between rigid rod-lens specialists, flexible platform manufacturers, and integrated navigation ecosystem providers. Three archetypes dominate: optical component specialists with sapphire substrate supply chains, flexible endoscope manufacturers with Japanese hospital channel control, and diversified medtech conglomerates bundling visualization with surgical navigation. Competitive moves concentrate on M&A for navigation technology integration and direct hospital system contracting bypassing distributor networks.
Among German precision instrument manufacturers, Karl Storz and Ackermann Instrumente GmbH exemplify the rigid endoscope specialization archetype. Olympus Corporation represents the flexible platform leadership position anchored in Japanese university hospital procurement frameworks. Medtronic occupies the diversified ecosystem tier, bundling visualization hardware with navigation and image enhancement systems. B. Braun SE and Stryker sit within the mid-tier integrated surgical device segment, while adeor medical AG and Clarus Medical LLC represent regional specialists with focused neurosurgical portfolios.
| Leading Market Players |
|---|
| Karl Storz |
| B. Braun SE |
| Olympus Corporation |
| Medtronic |
| Stryker |
| adeor medical AG |
| Ackermann Instrumente GmbH |
| Clarus Medical LLC |
| BD |
| Others |
Supply & Pricing Matrix
Fellowship-trained neuroendoscopic surgeons concentrated in Heidelberg, Munich, and Tokyo command wage premiums that propagate through system pricing, widening spreads between premium navigation-integrated platforms and standard visualization tiers.
Pricing Analysis
Outcome-linked reimbursement anchors pricing for hybrid visualization-navigation systems, with German and Japanese episode-based payment structures rewarding throughput gains from integrated platforms. Price differentiation separates FDA-cleared fluorescence-guided systems from standard high-definition tiers, with CE-MDR certification grade and integrated navigation capability as primary drivers. Cost compression in rigid rod-lens segments intensifies as sapphire substrate volatility from Eastern European sources squeezes component economics. Pediatric neurosurgical units in US children's hospitals show highest price sensitivity due to capital budget constraints, while German university hospitals demonstrate lowest sensitivity given consolidated procurement authority.
Supply Chain Analysis
ISO 13485:2016 and EU MDR Article 10 reprocessing validations gate supplier access, filtering subscale manufacturers from European and Japanese procurement channels. Optical component manufacturing concentrates in Germany, Japan, and the United States, with synthetic sapphire crystal drawing from Russian and Ukrainian feedstock. Supply chain vulnerability rests on single-source dependencies for high-purity rod-lens substrates and steerable flexible endoscope actuators. Distribution runs through dedicated hospital sales forces targeting IDN procurement committees in the United States and METI-coordinated frameworks in Japan, bypassing traditional distributor networks for premium system bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, with EU MDR sterilization validation requirements and PMDA audit timelines erecting structural barriers that protect incumbents with established quality management dossiers.
For Market Incumbents: Hedge against single-use flexible endoscope substitution pressure by deepening backward integration into sapphire substrate supply and accelerating ISO 17664 reprocessing instruction development. Anchor market position through direct hospital system contracting in German university hospitals and US integrated delivery networks, displacing distributor-dependent competitors. Prioritize electromagnetic tracking integration to defend premium pricing against navigation-agnostic challengers.
For New Entrants and Emerging Players: ANVISA regulatory harmonization with FDA 510(k) documentation in Brazil opens a window for manufacturers with existing US approvals to establish South American footholds before incumbent direct-sales deployment. Target fluorescence-guided tumor biopsy applications in Japanese university hospitals as the most penetrable segment, leveraging METI procurement framework standardization to bypass six-month PMDA audit barriers. Pursue augmented reality navigation convergence as the primary go-to-market differentiator against established rigid platform specialists.
For Investors and Strategic Acquirers: Re-rating potential sits with flexible platform manufacturers possessing Japanese hospital channel control given fluorescence-guided protocol expansion and METI framework consolidation. Long-term viability favors archetypes with captive navigation technology and validated reprocessing dossiers, as MDR compliance costs concentrate procurement around incumbents. Monitor FDA and EMA fluorescence guidance evolution as the critical inflection signal for hybrid platform reimbursement preferencing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Reprocessing Validation | MDR Article 10 compliance extends development timelines but consolidates demand around validated incumbents. |
| Navigation Ecosystem Integration | Electromagnetic tracking convergence with 4K visualization commands premium pricing in skull base surgery. |
| Direct Hospital System Contracting | Bypassing distributors through dedicated sales forces captures IDN procurement committee decisions. |
| Fluorescence-Guided Protocol Development | 5-aminolevulinic acid visualization standards determine which platforms gain preferential reimbursement. |
| ANVISA Fast-Track Utilization | Brazilian regulatory harmonization with FDA 510(k) documentation accelerates market entry for US-cleared manufacturers. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, neurosurgical device regulatory filings, and GPO contract databases underwrites the qualitative findings in this study. Primary fieldwork engaged biomedical engineers, GPO contracts managers, hospital procurement directors, and fellowship-trained neurosurgeons across German, Japanese, and US centers. Secondary validation drew from FDA 510(k) clearances, PMDA quality management audit records, EU MDR notified body submissions, and hospital capital equipment procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Rate-of-change decomposition across product type, technology tier, application, and end-user concentration dimensions structured the analytical framework. CAGRs derived from weighted procedure volume trajectories and capital equipment refresh cycle timing, with fluorescence-guided protocol adoption and episode-based reimbursement expansion as neuroendoscopy-specific forecast inputs. The model captures substitution elasticity between rigid and flexible platforms and navigation integration penetration curves.
The model assumes a particular technology adoption path; alternative pathways for single-use flexible endoscope substitution would alter the outlook for reusable platform economics. Forecasts reflect assumptions regarding PMDA audit timeline stability and EU MDR reprocessing standard evolution. A model refresh is warranted upon material change in FDA fluorescence guidance or sapphire substrate supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Non-Invasive Colon Cancer Screening Market