
 AI in Endoscopy Market | 2026-2036
AI in Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Endoscopy Market Analysis
Subscription-based software licensing and equipment leasing models is reconfiguring capital deployment across the AI endoscopy sector, lowering barriers for mid-sized hospitals. Medtronic leverages its integrated surgical ecosystem to bundle AI analytics with hardware platforms. Olympus Corporation anchors its position through deep specialization in optical imaging systems paired with real-time detection algorithms. Fujifilm Corporation differentiates via proprietary image-enhancement pipelines that feed directly into AI training datasets.
AI in endoscopy encompasses computer-aided detection and diagnostic systems that analyze real-time video feeds from gastrointestinal scopes, typically processing 30-60 frames per second through convolutional neural networks to flag mucosal abnormalities. These systems primarily serve to augment physician accuracy during screening procedures and reduce interval cancer rates from missed lesions. Machine learning deployments currently dominate commercial installations due to established validation protocols and lower computational overhead than deep learning alternatives. Diagnostic biopsies represent a concentrated margin pool where AI guidance reduces sampling error and repeat procedure rates. Hospitals remain the primary end-user segment, though outpatient clinics are expanding fastest as cloud-based analysis enables decentralized deployment.
FDA premarket notification pathways and the EU MDR conformity assessment framework shape product development timelines and clinical evidence requirements for AI endoscopy developers. Japan's PMDA has introduced streamlined review channels for software-as-medical-device products, creating competitive incentives for algorithm developers to prioritize Tokyo-led regulatory strategies. Stakeholders must monitor evolving reimbursement decisions from CMS and national health technology assessment bodies, as coverage determinations will dictate which AI modalities achieve scalable clinical adoption.
Market Dynamics
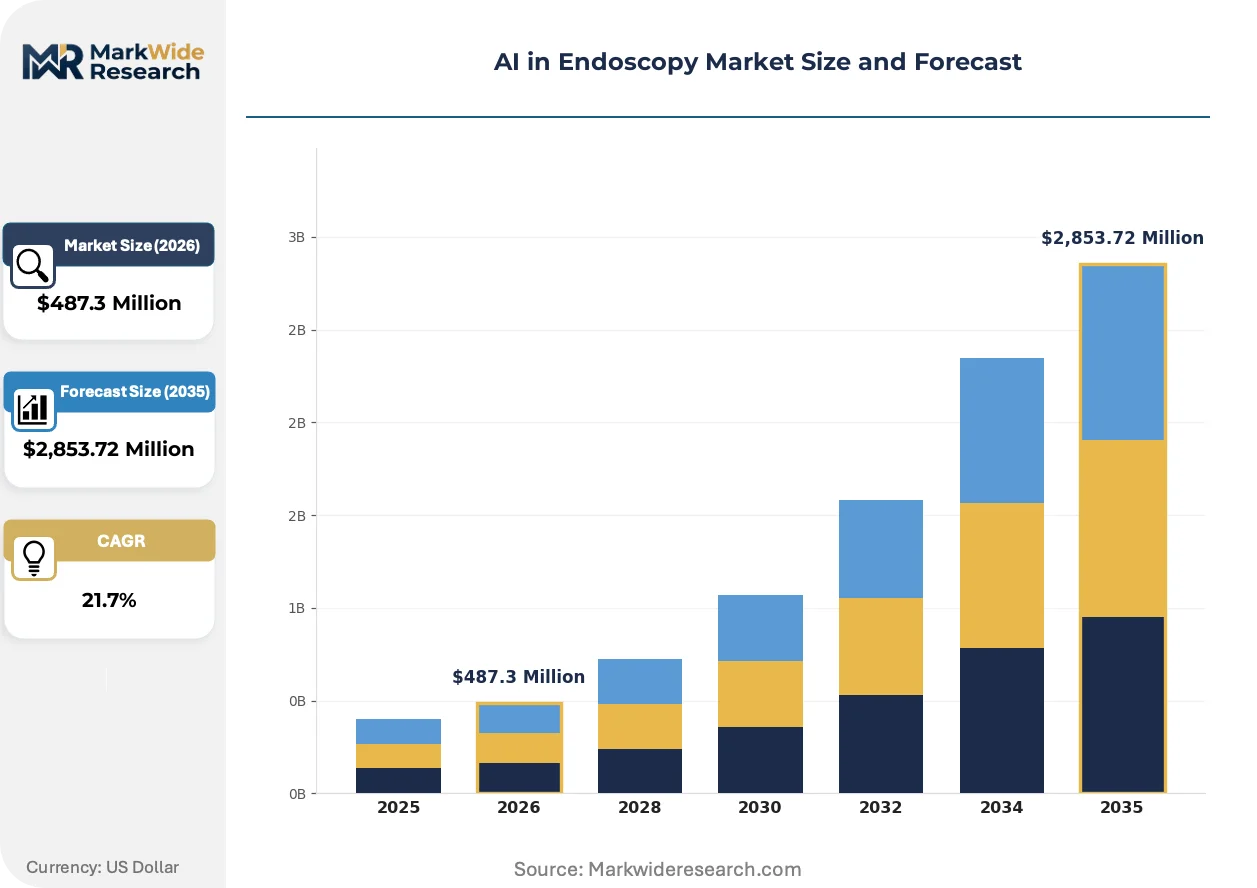
Convolutional neural networks processing real-time endoscopic video feeds are compressing diagnostic cycles and forcing hardware manufacturers to redesign optical systems around algorithmic throughput rather than human visual acuity alone.
Growth Catalysts
- FDA premarket notification pathways:Streamlined 510(k) clearances for computer-aided detection devices accelerate product introductions in the United States, reducing time-to-revenue for algorithm developers.
- Cloud-based analysis infrastructure:Decentralized deployment models enable outpatient clinics to access AI diagnostic capabilities without capital-intensive on-premise installations.
- Polyp detection rate mandates:Quality metrics tied to screening reimbursements in Germany and Japan create institutional pressure to adopt AI-assisted procedures.
Market Restraints
- GPU and specialized AI accelerator costs:Real-time video processing at 30-60 frames per second demands high-performance computing hardware that inflates per-procedure equipment costs.
- EU MDR conformity assessment timelines:Extended clinical evidence requirements for software-as-medical-device products delay European market entry by 18-36 months relative to FDA pathways.
- Conventional white-light endoscopy:Established low-cost screening protocols in resource-constrained health systems present substitution resistance to AI-enhanced alternatives.
Strategic Opportunities
- India's tertiary hospital expansion:Government-funded medical infrastructure programs create first-mover advantages for AI endoscopy vendors establishing training partnerships with gastroenterology residency programs.
- Capsule endoscopy convergence:Integration of wireless ingestible cameras with cloud-based AI analysis opens ambulatory screening markets previously inaccessible to conventional scope-based systems.
- Japan PMDA software-as-medical-device channels:Streamlined review pathways for algorithm-only products incentivize Tokyo-centered regulatory strategies that accelerate Asian market penetration.
Industry Challenges
- Gastroenterologist AI literacy gaps:Practicing physicians require structured training on algorithm confidence thresholds and false-positive interpretation, creating deployment friction in established screening programs.
- Legacy endoscope fleet incompatibility:Hospital-installed base of non-digital imaging systems lacks video output standards necessary for real-time AI feed integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Endoscopy Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,853.72 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AI-Assisted Imaging, Automated Analysis Software, Predictive Analytics Tools, Visualization Solutions End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Clinics Technology: Machine Learning, Computer Vision, Deep Learning, Natural Language Processing Application: Colorectal Screening, Gastric Examination, Diagnostic Biopsies, Surgical Assistance |
| Companies Covered | Hoya Corporation, Magentiq Eye, Medtronic, NEC Corporation, Wision AI, Olympus Corporation, Intuitive Surgical, Odin Vision, Fujifilm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Endoscopy Market Emerging Trajectories
Algorithmic processing of endoscopic imagery is virtualizing diagnostic expertise, enabling centralized AI training on aggregated multi-institutional datasets while distributing inference capabilities to peripheral care settings.
Edge computing architectures embedded directly into endoscope processor units are virtualizing the traditional workstation-based analysis pipeline. Mid-sized hospitals in the United States and Germany are adopting these integrated systems to eliminate latency between image capture and abnormality flagging. This compression of the diagnostic loop is virtualizing the need for dedicated AI computing infrastructure in every procedure room.
The EU Medical Device Regulation's software classification criteria are redefining clinical evidence standards for algorithm updates. Manufacturers must now submit substantial equivalence documentation for each neural network retraining cycle, extending product maintenance timelines. European hospital procurement committees are responding by prioritizing vendors with established MDR technical file portfolios over newer market entrants.
Subscription licensing for AI detection modules is displacing perpetual software purchases in North American hospital systems. Capital-constrained outpatient clinics in Texas and Florida are driving this transition, preferring per-procedure fees aligned with reimbursement cycles. This financial restructuring concentrates vendor relationship value in ongoing service delivery rather than upfront equipment margins.
AI in Endoscopy Market Segmentation
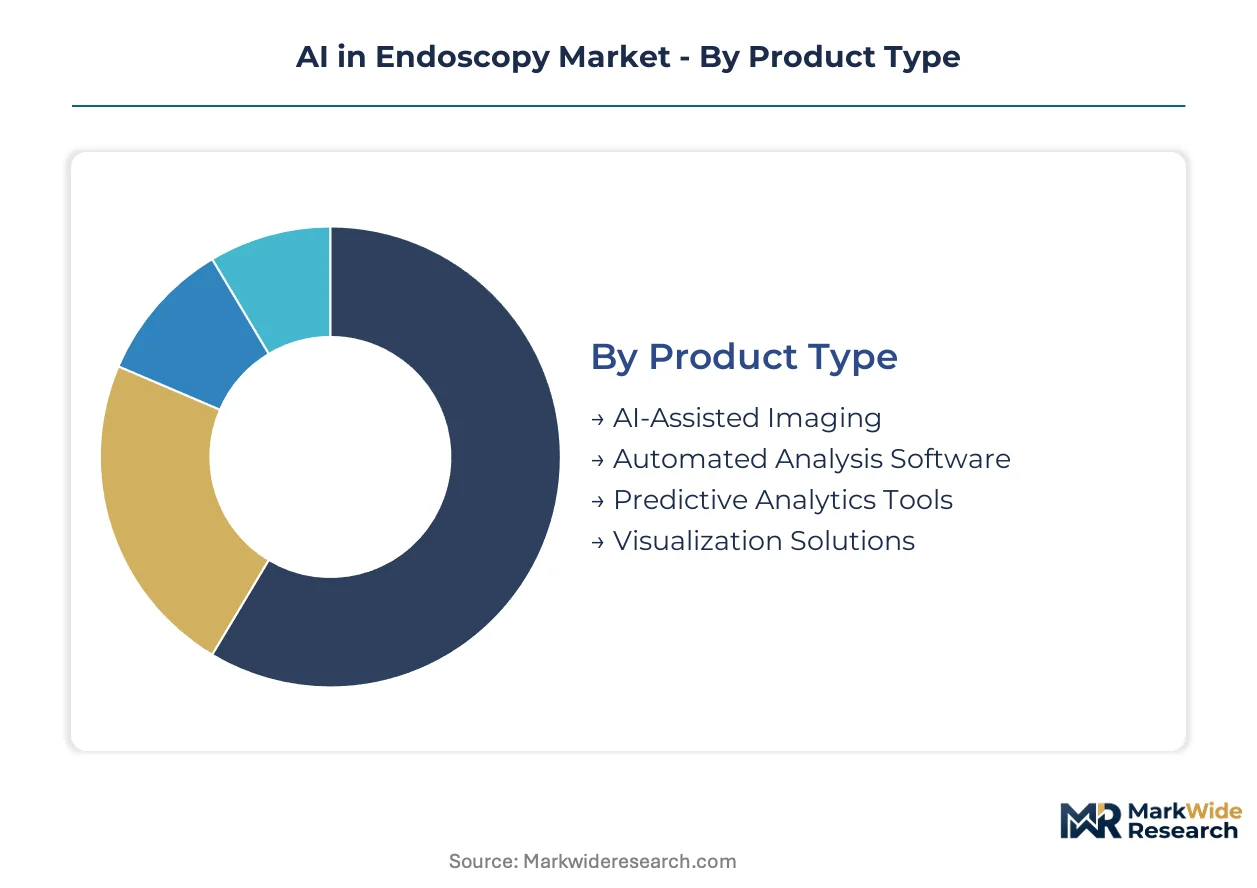
AI endoscopy deployments fragment across hardware-software boundaries, clinical settings, and algorithmic architectures. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and vendor competitive dynamics that shape go-to-market strategies.
Product Type:
The use-case spectrum spans real-time procedural assistance to retrospective data mining, with hardware integration intensity varying sharply across categories.
- AI-Assisted Imaging:Embedded convolutional neural networks process 30-60 frames per second directly within endoscope processor units, flagging mucosal abnormalities during live procedures. Demand concentrates in United States hospital systems where CMS reimbursement for AI-enhanced colonoscopies creates institutional procurement pressure.
- Automated Analysis Software:Cloud-deployed platforms perform post-procedure video review, generating structured reports on polyp characteristics and procedural completeness. Diagnostic centers in Germany favor these systems for quality assurance documentation required under national screening program audits.
- Predictive Analytics Tools:Retrospective patient cohort analysis identifies high-risk individuals for accelerated surveillance intervals.
- Visualization Solutions:Image enhancement pipelines improve mucosal contrast beyond conventional white-light endoscopy.
The dominant share belongs to AI-Assisted Imaging, while Automated Analysis Software is closing the gap fastest.
End User:
Procurement authority and capital availability diverge sharply across institutional settings, with volume concentration shifting toward decentralized delivery models.
- Hospitals:Integrated health systems deploy comprehensive AI suites across gastroenterology departments, leveraging existing IT infrastructure and established vendor relationships with endoscope manufacturers. United States academic medical centers drive premium-tier adoption, bundling AI modules with enterprise-wide electronic health record integration.
- Outpatient Clinics:Ambulatory surgery centers access AI capabilities through subscription-based cloud platforms, avoiding capital-intensive on-premise installations. Texas and Florida facilities are expanding fastest as state-level scope-of-practice regulations enable non-hospital-based screening programs.
- Diagnostic Centers:Specialized imaging facilities prioritize high-throughput analysis tools for volume screening contracts.
- Research Laboratories:Algorithm development and validation studies drive demand for training-dataset management platforms.
Hospitals retain the largest installed base, though Outpatient Clinics are expanding most quickly.
Technology:
Computational architecture choices trade validation rigor against processing throughput, with regulatory pathways favoring established methodologies.
- Machine Learning:Supervised classification algorithms with established clinical validation protocols dominate FDA 510(k) clearances, offering lower computational overhead than neural network alternatives. Commercial installations favor these systems for real-time polyp detection where latency tolerance is minimal.
- Deep Learning:Multi-layer neural networks achieve superior accuracy on complex lesion classification but demand GPU-accelerated hardware that inflates per-procedure costs. Japan's PMDA has streamlined review channels for these products, accelerating Tokyo-centered regulatory strategies.
- Computer Vision:Image preprocessing and feature extraction pipelines standardize input data for downstream classification.
- Natural Language Processing:Automated report generation from procedural video and physician narration streamlines documentation workflows.
Machine Learning holds the dominant clinical footprint, while Deep Learning is gaining share fastest.
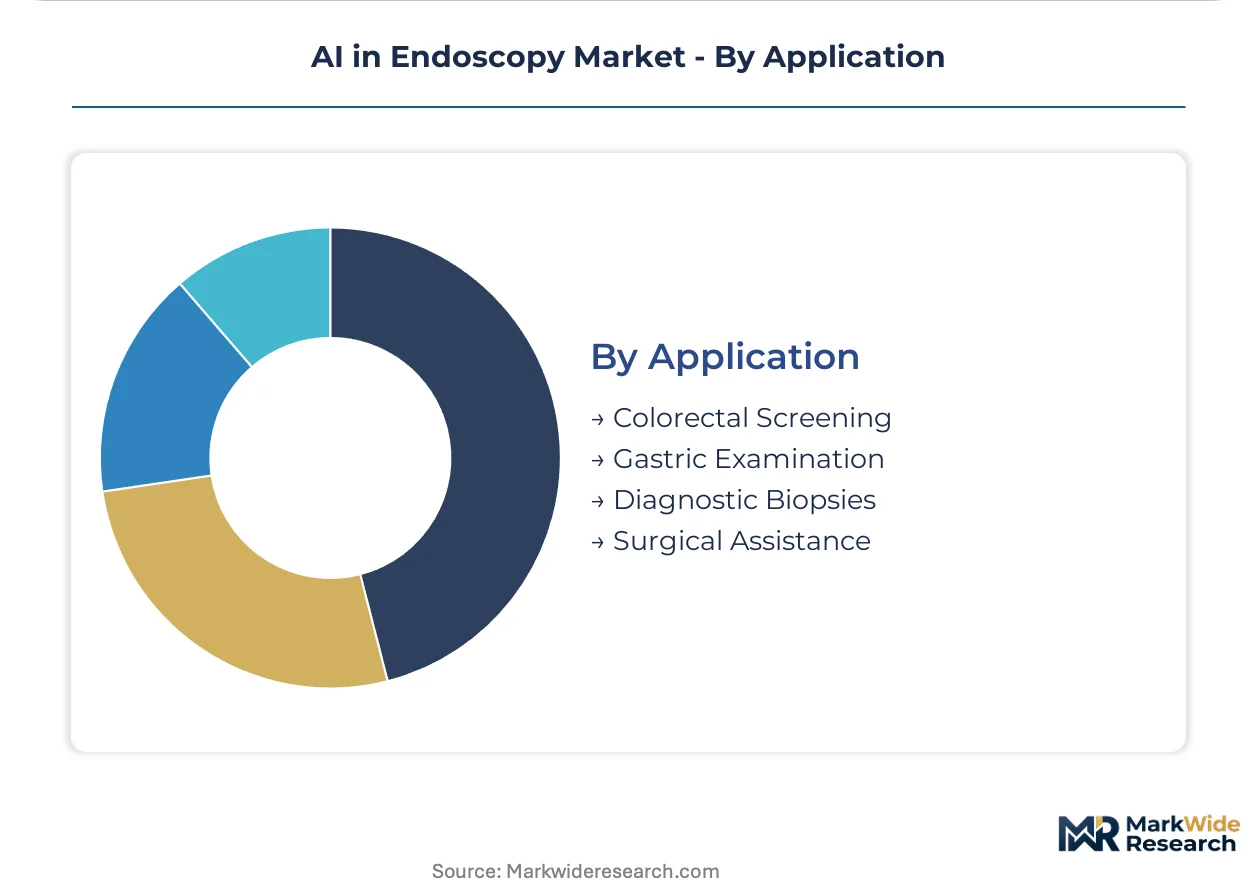
Application:
Reimbursement coding specificity and interval cancer risk profiles concentrate investment in screening applications with established quality metrics.
- Colorectal Screening:Computer-aided detection systems quantify polyp detection rates and adenoma per colonoscopy metrics tied to United States and German reimbursement thresholds. Quality mandates in these markets create institutional pressure for AI adoption to avoid penalty adjustments.
- Diagnostic Biopsies:AI guidance reduces sampling error and repeat procedure rates in gastric lesion characterization, capturing concentrated margin pools where pathology confirmation drives procedural economics. Japanese tertiary hospitals prioritize these capabilities for early gastric cancer detection.
- Gastric Examination:Image-enhanced endoscopy with AI interpretation addresses high gastric cancer incidence in East Asian populations.
- Surgical Assistance:Real-time margin assessment and anatomical landmark identification support therapeutic endoscopic procedures.
Colorectal Screening commands the dominant share, while Diagnostic Biopsies is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI endoscopy equipment flows predominantly from Japanese and German manufacturing clusters toward United States and European hospital systems, with regulatory clearances in destination markets determining effective export capacity. Import demand concentrates in tertiary care centers seeking FDA-cleared or MDR-conforming systems.
United States
Academic medical centers in Boston and Houston drive procurement of integrated AI-assisted imaging platforms. FDA 510(k) pathways for computer-aided detection devices accelerate commercial introductions. Texas ambulatory surgery centers expand fastest as state-level scope-of-practice regulations enable decentralized screening programs.
Germany
Quality metrics tied to national screening reimbursements create institutional pressure for AI adoption in Berlin and Munich hospital networks. EU MDR conformity assessments extend product entry timelines but reward established technical file portfolios. The Baden-Württemberg medical technology corridor anchors manufacturing of optical imaging systems.
Japan
Tertiary hospitals in Tokyo and Osaka prioritize AI guidance for early gastric cancer detection given high population incidence. PMDA streamlined review channels for software-as-medical-device products incentivize domestic algorithm developers. The Kanto region concentrates endoscope manufacturing and AI training dataset aggregation.
India
Government-funded tertiary hospital expansion in Maharashtra and Karnataka creates first-mover opportunities for training partnerships with gastroenterology residency programs. CDSCO medical device regulations are aligning with international standards to accelerate import clearances. Hyderabad's health technology cluster attracts AI diagnostic platform development.
United Kingdom
NHS England bowel cancer screening program quality standards drive London and Manchester hospital systems toward AI-enhanced colonoscopy procurement. MHRA post-Brexit regulatory pathways maintain equivalence with EU MDR requirements. The Oxford-Cambridge health technology arc concentrates algorithm validation studies.
AI in Endoscopy Market Vendor Landscape
On the supply side, the industry is consolidating around integrated surgical ecosystems and specialized optical imaging manufacturers. Tiered competitive positioning separates endoscope-hardware incumbents from pure-play algorithm developers. Three archetypes dominate: diversified medical technology conglomerates bundling AI with installed equipment bases; specialized endoscope manufacturers pairing optical systems with detection software; and venture-backed algorithm developers seeking regulatory clearance for modular deployment. Competitive moves center on strategic partnerships between hardware and software specialists, plus geographic expansion through regulatory-first market entry strategies.
Among diversified medical technology conglomerates, Medtronic and Olympus Corporation exemplify the integrated-ecosystem archetype, leveraging established hospital vendor relationships to bundle AI analytics with procedural platforms. Fujifilm Corporation occupies a position bridging optical manufacturing and proprietary image-enhancement pipelines. These three entities represent distinct strategic postures: equipment-centric bundling, imaging-specialist vertical integration, and film-to-digital transition expertise applied to endoscopic AI training datasets.
| Leading Market Players |
|---|
| Hoya Corporation |
| Magentiq Eye |
| Medtronic |
| NEC Corporation |
| Wision AI |
| Olympus Corporation |
| Intuitive Surgical |
| Odin Vision |
| Fujifilm Corporation |
| Others |
Supply Flow & Price Mechanics
The Kansai-Osaka freight corridor connecting Japanese endoscope manufacturing clusters to North American distribution hubs shapes cost dynamics across AI endoscopy supply chains, concentrating pricing power with optical component suppliers while forcing downstream tiering between integrated system vendors and modular software providers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across the AI endoscopy sector, with three-tier pricing stratification across premium FDA-cleared platforms, standard CE-marked systems, and economy-grade regional variants. Price differentiation hinges on regulatory certification tier and after-sales algorithm update bundling. Pricing pressure intensifies in the outpatient clinic segment as cloud-based deployment models compress per-procedure fees. Academic medical centers exhibit lowest price sensitivity due to bundled enterprise licensing, while ambulatory surgery centers in Texas and Florida drive hardest bargain for per-case SaaS arrangements.
Supply Chain Analysis
CMOS image sensors and GPU accelerators feed from concentrated manufacturing bases in Japan, Taiwan, and the United States, with specialized optical glass drawing from German and Japanese suppliers. Raw material dependencies center on rare-earth phosphors for illumination systems, high-purity sapphire for lens substrates, and advanced packaging substrates for edge-computing modules. Single-source vulnerability around NVIDIA AI accelerators creates procurement risk for real-time processing units. Distribution runs through authorized medical device distributors with GPO contracting access, bypassing direct hospital sales for mid-tier installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI endoscopy market functions as a defensive-moat arena where FDA 510(k) clearance backlogs and MDR technical file portfolios create regulatory entrenchment that protects incumbent positions against algorithm-only challengers.
For Market Incumbents: Pre-empt pure-play algorithm developers by embedding convolutional neural networks directly into next-generation processor units, eliminating workstation dependency that threatens hardware-software bundling. Acquire cloud-analysis capabilities to defend against subscription-based entrants targeting outpatient clinics with capital-light deployment models. Prioritize MDR technical file expansion to extend European procurement committee preference windows.
For New Entrants and Emerging Players: Establish a beachhead in India's government-funded tertiary hospital expansion, where training partnerships with gastroenterology residency programs create reference sites ahead of hardware incumbents. Target capsule endoscopy-AI convergence as the most penetrable white-space segment, leveraging wireless ingestible cameras with cloud-based analysis to bypass conventional scope fleet incompatibility barriers. Pursue PMDA software-as-medical-device clearance as the fastest regulatory pathway to Asian market traction.
For Investors and Strategic Acquirers: Algorithm developers with established FDA 510(k) clearances and hospital pilot contracts represent the priority acquisition archetype, offering regulatory shortcuts and clinical validation assets that compress time-to-revenue for acquiring platforms. Long-term viability hinges on reimbursement coding integration with CMS and national health technology assessment bodies. Watch CMS coverage determinations for AI-enhanced colonoscopy as the critical inflection signal separating scalable clinical adoption from pilot-program stagnation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Streamlined clearance pathways accelerate commercial introductions for computer-aided detection devices in United States hospital systems. |
| EU MDR Conformity Assessment | Extended clinical evidence requirements reward established technical file portfolios with procurement committee preference in Berlin and Munich networks. |
| Hospital System Partnership | Integrated health system deployments bundle AI modules with enterprise EHR integration across academic medical centers. |
| Software Companion Development | Cloud-based analysis platforms enable decentralized deployment to outpatient clinics without capital-intensive on-premise infrastructure. |
| Reimbursement Strategy | CMS coverage determinations and German quality metric mandates dictate which AI modalities achieve scalable clinical adoption. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, gastroenterology department heads, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, EU MDR technical file disclosures, CMS Medicare reimbursement databases, and hospital procurement system records. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital equipment spending flows anchored volume and value outputs.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation modeling across product type, end-user institution, algorithmic technology, and clinical application dimensions. CAGRs were derived from curve-fitting procedures applied to historical adoption trajectories and regulatory clearance timelines. Forecast inputs incorporated polyp detection rate mandate schedules in Germany and Japan, plus CMS reimbursement decision pipelines.
Sensitivities concentrate around FDA review timeline extensions, EU MDR notified body capacity constraints, and CMS non-coverage determinations for AI-enhanced procedures. Cross-checking against hospital capital expenditure surveys and endoscope manufacturer order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Bronchoscopy Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Esophageal Stents Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Gastroscopes Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Global Colonoscopy Devices Market