
 UAE Endoscopy Devices Market | 2026-2036
UAE Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Endoscopy Devices Market Analytics
Single-use polymer endoscopes is decoupling device economics from capital-intensive reprocessing infrastructure. Olympus Corporation leverages its established service networks to sustain recurring revenue streams across UAE hospital systems. Karl Storz SE & Co. KG anchors its position through rigid endoscope specialization in surgical suites. FUJIFILM Holdings Corporation differentiates via integrated imaging platforms that combine endoscopy with diagnostic software.
Endoscopy devices encompass instruments with insertion tubes ranging from 2.8 mm to 14 mm diameter, incorporating fiber optic or digital image sensors for visualizing hollow organs and body cavities during diagnostic or interventional procedures. Flexible endoscopes dominate procedural volume in gastroenterology and pulmonology applications across UAE facilities. Robotic endoscopy represents the fastest-expanding technology segment as hospitals invest in precision-guided platforms for complex interventions. Capsule endoscopes occupy a niche but growing position in outpatient diagnostic workflows where patient compliance and non-invasive examination priorities elevate adoption.
MOHAP and Dubai Health Authority enforce medical device registration and post-market surveillance requirements that determine which manufacturers gain market access. BIS-equivalent conformity assessments and UAE-specific labeling standards add compliance layers that filter supplier participation. Stakeholders must monitor how federal procurement centralization and mandatory health insurance expansions reshape purchasing concentration among hospital groups and ambulatory surgical centers.
Market Dynamics
Single-use polymer endoscopes are severing the historical link between device procurement and capital-intensive reprocessing infrastructure, forcing UAE hospitals to reevaluate total cost-of-ownership models and supplier relationships.
Growth Catalysts
- MOHAP Registration Mandates:Federal medical device registration requirements are standardizing procurement quality thresholds across Emirates hospital networks, filtering out non-compliant suppliers and consolidating purchasing toward certified manufacturers.
- Dubai Healthcare Free Zones:Clustering of specialty surgical centers in Dubai Science Park and Dubai Healthcare City is concentrating demand for advanced endoscopic platforms within integrated medical cities.
- Minimally Invasive Surgery Expansion:Abu Dhabi's specialty hospital clusters are scaling laparoscopic and endoscopic procedure volumes, driving replacement cycles for flexible and rigid endoscope inventories.
Market Restraints
- Polymer Supply Concentration:Medical-grade polymer feedstocks for single-use endoscope housings face supply chain bottlenecks concentrated among Asian petrochemical producers, exposing UAE manufacturers to input cost volatility.
- Capital Equipment Lock-in:Existing investments in Olympus and Karl Storz reprocessing infrastructure create switching costs that delay adoption of disposable alternatives despite lifecycle cost advantages.
- MOHAP Compliance Timelines:Extended registration review periods for novel endoscope technologies create market access delays that compress commercialization windows for innovative entrants.
Strategic Opportunities
- Abu Dhabi Ambulatory Expansion:Mandatory health insurance expansions under Thiqa and broader coverage schemes are redirecting diagnostic endoscopy volumes toward outpatient surgical centers with lower capital barriers.
- Robotic-Assisted Integration:Convergence of flexible endoscopy with precision-guided robotic platforms opens procedural expansion into complex interventional gastroenterology previously reserved for open surgery.
- Capsule Endoscopy Outpatient Workflows:Non-invasive capsule systems align with Dubai Health Authority patient experience mandates, creating channel expansion into employer-sponsored screening programs.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized technicians for endoscope repair and reprocessing are concentrated in Dubai and Abu Dhabi, leaving Northern Emirates facilities dependent on outsourced maintenance contracts.
- Legacy System Integration Complexity:New digital imaging platforms must interface with heterogeneous PACS architectures across MOHAP, DHA, and private hospital networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Endoscopy Devices Market |
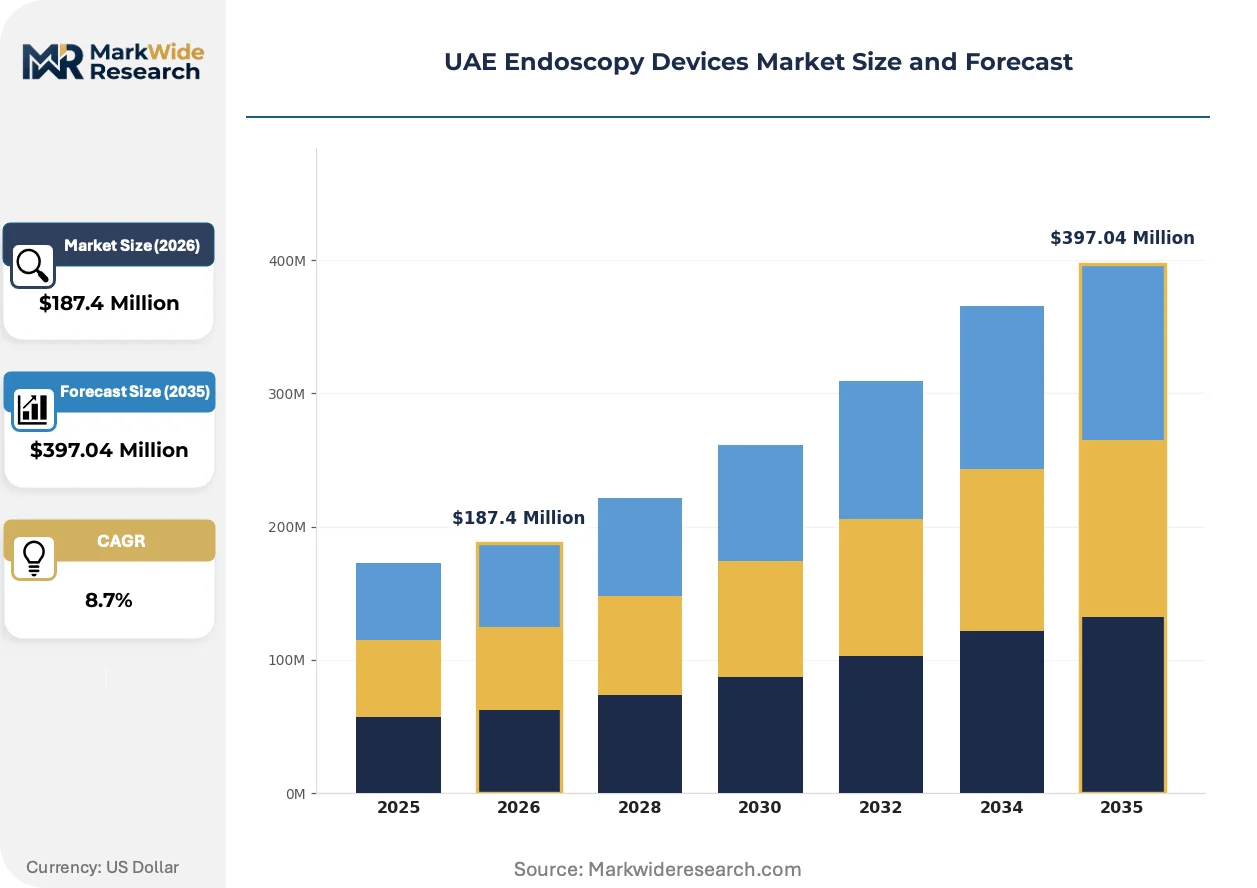
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Capsule Endoscopes, Endoscopic Accessories Technology: Video Endoscopy, Fiber Optic Endoscopy, Ultrasound Endoscopy, Robotic Endoscopy End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Gastroenterology, Pulmonology, Urology, Gynecology |
| Companies Covered | Boston Scientific Corporation, Stryker Corporation, Medtronic PLC, Johnson & Johnson, Olympus Corporation, Karl Storz SE & Co. KG, FUJIFILM Holdings Corporation, Richard Wolf GmbH, Cook Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Endoscopy Devices Market Evolving Landscape
Digital sensor miniaturization and polymer manufacturing advances are collapsing the performance gap between single-use and reusable endoscopes, reshaping procurement economics across UAE healthcare systems.
CMOS image sensors with 4K resolution capabilities are rewriting the technical specifications that define clinical-grade endoscopy. Dubai's tertiary hospitals are adopting these sensors in disposable bronchoscopes and colonoscopes for immunocompromised patient cohorts. The technology is compressing the acceptable trade-off between optical fidelity and infection control, enabling procedure-specific device selection rather than universal reusability.
MOHAP's post-market surveillance requirements are tightening adverse event reporting obligations for endoscope manufacturers operating in the Emirates. Device history record traceability and biocompatibility testing documentation now accompany every registration renewal. Flexible endoscope suppliers with established UAE service networks are adapting quality management systems to meet shortened response timelines for field safety notices.
Hospital procurement committees are unbundling endoscope purchases from long-term service agreements, separating capital acquisition from maintenance and reprocessing contracts. This disintermediation is most visible in Abu Dhabi's SEHA hospital group, where competitive tendering for disposable endoscope supplies now runs independently from imaging platform vendor relationships. The shift enables multi-vendor sourcing strategies that were previously constrained by bundled pricing structures.
UAE Endoscopy Devices Market Segmentation
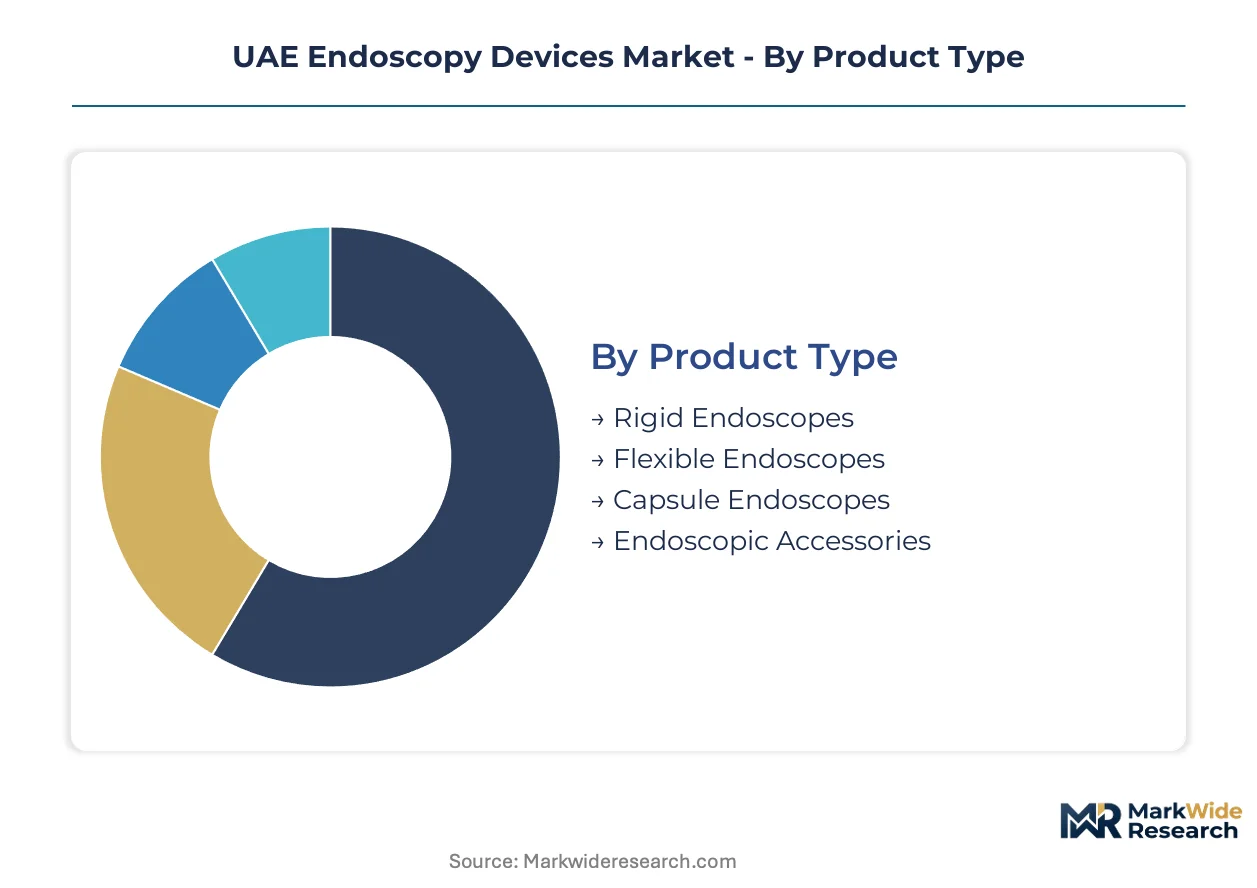
Procurement patterns across UAE healthcare facilities diverge sharply based on capital intensity, reprocessing infrastructure, and patient throughput requirements. Understanding these segment boundaries clarifies where disposable alternatives displace reusable systems and where robotic platforms command premium positioning.
Product Type:
Hospital capital budgets and infection control protocols create distinct purchasing tiers across device categories.
- Rigid Endoscopes:Stainless steel insertion tubes with rod-lens optical systems dominate arthroscopy, laparoscopy, and ENT procedures across SEHA hospital surgical suites. Demand concentrates in Abu Dhabi's specialty clusters where sterilization infrastructure supports high-volume reusable workflows.
- Flexible Endoscopes:Articulating insertion tubes with CCD/CMOS sensors enable gastroenterology and pulmonology visualization through natural body orifices. Dubai Healthcare City facilities are driving replacement demand as older fiber-optic inventories reach end-of-life.
- Capsule Endoscopes:Ingestible imaging platforms with wireless data transmission serve outpatient diagnostic pathways where patient compliance and non-invasive examination priorities elevate adoption.
- Endoscopic Accessories:Biopsy forceps, polypectomy snares, and irrigation channels constitute recurring consumable demand tied to procedure volumes rather than capital cycles.
Volume sits with Flexible Endoscopes; growth tilts toward Capsule Endoscopes.
Technology:
Image fidelity requirements and procedural complexity determine technology migration timelines across Emirates healthcare networks.
- Video Endoscopy:Digital sensor-based platforms with HD or 4K resolution outputs have become the default specification in Dubai's tertiary hospitals. Procurement committees now require DICOM compatibility and PACS integration as baseline technical requirements.
- Fiber Optic Endoscopy:Bundled glass fiber illumination and image transmission systems persist in Northern Emirates facilities with constrained capital renewal budgets. These platforms face accelerated replacement pressure as sensor costs decline.
- Ultrasound Endoscopy:Echoendoscopes combining endoscopic visualization with ultrasonic tissue imaging enable fine-needle aspiration and submucosal lesion assessment in interventional gastroenterology workflows.
- Robotic Endoscopy:Precision-guided platforms with haptic feedback and instrument stability are gaining traction in complex interventional procedures previously requiring open surgical access.
Video Endoscopy dominates installed base; Robotic Endoscopy is climbing the fastest.
End User:
Facility scale and reimbursement structures create divergent device specification requirements across the care continuum.
- Hospitals:Multi-specialty institutions with centralized sterilization departments and 24-hour procedural capacity anchor demand for capital-intensive reusable endoscope platforms across MOHAP-regulated networks.
- Ambulatory Surgical Centers:Day-procedure facilities with lower capital barriers and Thiqa insurance coverage expansion are adopting single-use endoscopes to eliminate reprocessing infrastructure investment.
- Specialty Clinics:Focused gastroenterology and pulmonology practices concentrate procedure volume in outpatient settings with streamlined patient throughput models.
- Research Institutions:Academic medical centers with experimental protocol requirements drive early adoption of novel imaging modalities and prototype device evaluation.
Procurement volume concentrates in Hospitals; Ambulatory Surgical Centers are gaining share fastest.
Application:
Disease prevalence and screening program mandates shape procedure volume distribution across medical specialties.
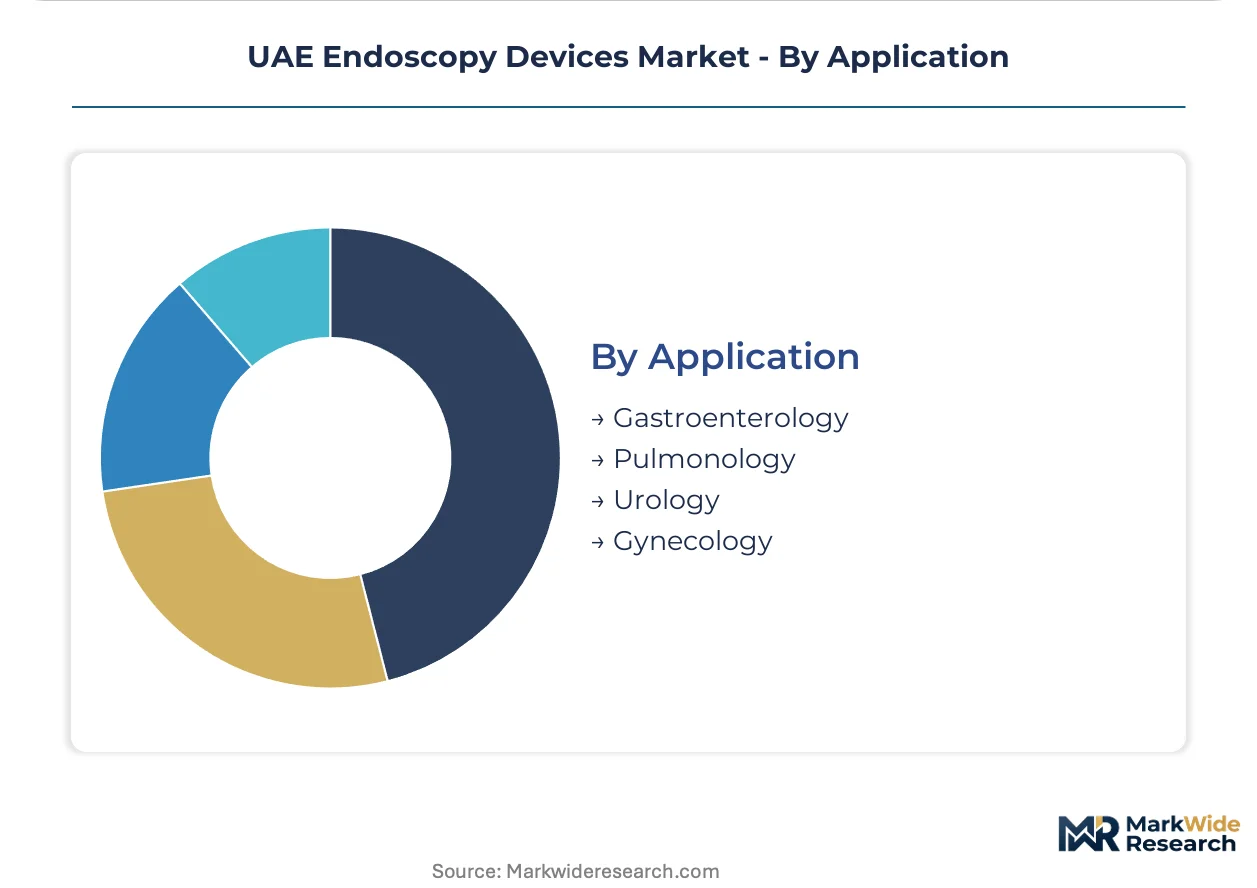
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures constitute the largest addressable volume, driven by colorectal cancer screening initiatives and GERD management across UAE's aging expatriate population.
- Pulmonology:Bronchoscopy applications for lung cancer staging and interventional airway management are expanding as smoking prevalence and occupational respiratory conditions drive diagnostic demand.
- Urology:Cystoscopy and ureteroscopy procedures for hematuria evaluation and stone disease management follow distinct procurement patterns tied to surgical rather than diagnostic reimbursement codes.
- Gynecology:Hysteroscopy and laparoscopy applications in fertility assessment and minimally invasive gynecologic surgery represent specialized sub-segments with dedicated device specifications.
Procedure volume concentrates in Gastroenterology; Pulmonology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endoscopy devices concentrates in Dubai and Abu Dhabi, where hospital infrastructure investments and regulatory centralization create procurement gravity. MOHAP registration mandates and DHA facility licensing determine which manufacturers gain market access. Facility clustering in healthcare free zones amplifies volume concentration within these two Emirates.
Dubai
Dubai Healthcare City and Dubai Science Park host the densest concentration of ambulatory surgical centers and specialty clinics. DHA facility licensing requirements enforce technical standards for endoscopic imaging platforms. Private hospital groups in these free zones are adopting single-use endoscopes to eliminate reprocessing infrastructure costs.
Abu Dhabi
SEHA hospital networks anchor demand for capital-intensive reusable endoscope systems across multi-specialty surgical suites. DOH facility regulations mandate infection control protocols that shape sterilization infrastructure investments. Specialty hospital clusters in Al Ain and the capital city are expanding minimally invasive surgery programs.
Sharjah
University Hospital Sharjah and emerging private medical centers drive procurement for mid-tier flexible endoscope platforms. MOHAP federal registration applies uniformly, though procurement volumes remain below Dubai and Abu Dhabi thresholds. Medical city developments in the emirate are attracting diagnostic clinic investments.
Northern Emirates
Ras Al Khaimah and Fujairah facilities rely on outsourced maintenance contracts due to biomedical engineering talent scarcity. Federal procurement centralization under MOHAP is gradually extending device standardization to these lower-volume markets. Northern Emirates hospitals purchase through group purchasing organizations linked to Dubai-based distributors.
UAE Endoscopy Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance reusable platform maintenance with single-use product development. The vendor base stratifies into three tiers: multinational imaging platform suppliers, specialized rigid endoscope fabricators, and emerging disposable device entrants. Two strategic archetypes prevail: integrated systems vendors leveraging service networks for recurring revenue, and focused specialists capturing procedure-specific niches. M&A activity and technology licensing agreements represent the primary competitive moves reshaping supplier relationships.
Among the multinational tier, Olympus Corporation and Karl Storz SE & Co. KG occupy established positions anchored by decades of UAE hospital system presence. FUJIFILM Holdings Corporation represents the integrated imaging archetype, combining endoscopic hardware with diagnostic software platforms. These three entities exemplify how service infrastructure investments and regulatory compliance capabilities create defensive moats against disposable alternatives.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Stryker Corporation |
| Medtronic PLC |
| Johnson & Johnson |
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| FUJIFILM Holdings Corporation |
| Richard Wolf GmbH |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
Single-use polymer endoscope manufacturing is collapsing the traditional capital-replacement cycle into per-procedure economics, simultaneously redistributing pricing power toward raw material suppliers in Asian petrochemical markets and fragmenting procurement authority across UAE hospital networks. This dual shift forces manufacturers to recalibrate margin structures around disposable unit costs rather than long-term service contracts, while buyers face new volatility in medical-grade polymer feedstock pricing.
Pricing Analysis
Volume sits with reusable endoscope platforms; margins concentrate in single-use alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Olympus and Karl Storz integrated systems from mid-tier FUJIFILM bundles and emerging polymer disposables. Cost compression in the disposable tier is intensifying because Korean and Chinese polymer suppliers are expanding medical-grade resin capacity. Ambulatory surgical centers in Dubai Healthcare City exhibit highest price sensitivity due to Thiqa reimbursement constraints, while SEHA hospital networks in Abu Dhabi prioritize total cost-of-ownership over per-unit pricing.
Supply Chain Analysis
Dual-sourcing requirements from MOHAP-registered manufacturers mandate qualification of at least two polymer resin suppliers, extending procurement timelines but reducing single-source vulnerability. Medical-grade polycarbonate and thermoplastic elastomer feedstocks draw primarily from South Korea, China, and Germany, with secondary compounding operations concentrated in Singapore and India. Tariff exposure on Chinese-sourced resins represents the dominant structural risk, compounded by MOHAP biocompatibility documentation requirements that freeze supplier switches. Distribution runs through Dubai-based medical device distributors with MOHAP import licenses, who maintain inventory buffers for Northern Emirates facilities lacking direct procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital CMOS sensors are displacing fiber-optic illumination systems across UAE gastroenterology suites, compressing the technology transition window for manufacturers still maintaining legacy platform service revenue.
For Market Incumbents: Hedge reusable platform erosion by accelerating single-use product line development while locking hospital systems into imaging software subscriptions that outlast hardware replacement cycles. Defensive consolidation should prioritize backward integration into polymer compounding to capture margin migrating up the supply chain, and preemptive certification of dual resin sources to satisfy MOHAP supplier qualification mandates. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass incumbent distributor relationships and enable rapid penetration of Northern Emirates facilities currently dependent on outsourced maintenance contracts. White-space targets include capsule endoscopy for Dubai employer-sponsored screening programs and disposable bronchoscopes for Abu Dhabi pulmonology expansion. The most penetrable segment is ambulatory surgical centers seeking to eliminate capital-intensive reprocessing infrastructure entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational imaging platform suppliers seeking disposable technology tuck-ins, with IPO viability contingent on demonstrating UAE hospital system reference accounts. Long-term viability favors targets with established MOHAP registration dossiers and proprietary polymer formulations that create raw material switching costs. The signal to watch is SEHA procurement committee unbundling of service contracts from device purchases, which would validate standalone disposable business models.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Fast-Track | Accelerated market access for novel polymer endoscope technologies reduces commercialization delays in UAE hospital networks. |
| Hospital System Partnership | Direct procurement relationships with SEHA or DHA-licensed facilities establish reference accounts for regional expansion. |
| Software Companion Development | Integrated imaging platforms with AI-assisted polyp detection differentiate hardware offerings in Dubai tertiary hospitals. |
| Reimbursement Strategy | Thiqa coding alignment for capsule endoscopy procedures unlocks outpatient volume in employer-sponsored screening programs. |
| CE Marking Pathway | European regulatory approval enables parallel UAE registration under MOHAP's BIS-equivalent conformity recognition framework. |
Research Methodology
MOHAP medical device registration databases, SEHA procurement records, and Dubai Health Authority facility licensing files formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with hospital purchasing committee members, biomedical engineering directors at Dubai Healthcare City facilities, GPO contracts managers, and polymer resin procurement leads at single-use endoscope manufacturers validated secondary estimates and informed segmentation assumptions. Bottom-up unit shipment estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Bottom-up modeling anchored volume projections to procedure frequency data by application and end-user facility type, while top-down validation checked aggregate device expenditure against UAE healthcare infrastructure investment disclosures. Segmentation dimensions modeled include product type, technology tier, end-user facility scale, and application specialty, with regional splits across Dubai, Abu Dhabi, Sharjah, and Northern Emirates. CAGRs were derived from fitted growth curves incorporating MOHAP regulatory timeline assumptions and Thiqa insurance expansion parameters.
Inputs from MOHAP registration filings and hospital procurement databases were available through the study window; gaps in real-time polymer resin pricing and confidential manufacturer cost structures introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding regulatory approval timelines, reimbursement code expansions, and hospital capital budget trajectories. Deviation in MOHAP post-market surveillance enforcement intensity or Thiqa coverage scope revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
AI in Endoscopy Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Bronchoscopy Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Endoscopy Device Market