
 Indian Laparoscopy Devices Market | 2026-2036
Indian Laparoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Indian Laparoscopy Devices Market Insights
Single-port access technology is rewriting surgical workflows across Indian operating theaters. Medtronic leverages its integrated energy platform to dominate advanced vessel sealing applications. Olympus Corporation anchors the visualization layer through its proprietary camera and light source ecosystems. Karl Storz specializes in rigid endoscope craftsmanship that sustains premium positioning among institutional buyers.
Laparoscopy devices encompass trocars, camera systems, light sources, and electrosurgical units engineered for minimally invasive abdominal and pelvic procedures, typically operating through 5-12 mm port diameters with insufflation pressures maintained at 12-15 mmHg for optimal visualization and instrument maneuverability. Electrosurgical units and camera systems command the deepest margin pools due to recurring consumables and upgrade cycles, while robotic-assisted technology represents the fastest-expanding dimension though from a narrow installed base. Hospitals absorb the dominant volume share of device procurement, yet surgical centers are expanding throughput faster as ambulatory laparoscopic procedures gain payer acceptance.
CDSCO regulates device import, clinical investigation, and manufacturing licensing under the Medical Device Rules, while BIS certification mandates electrical safety and electromagnetic compatibility standards for domestically produced equipment. The PLI scheme for medical devices creates fiscal incentives that reshape competitive positioning toward local assembly and component sourcing. Stakeholders must monitor how state-level public procurement policies and Ayushman Bharat reimbursement thresholds evolve to determine capital deployment timing for premium technology tiers.
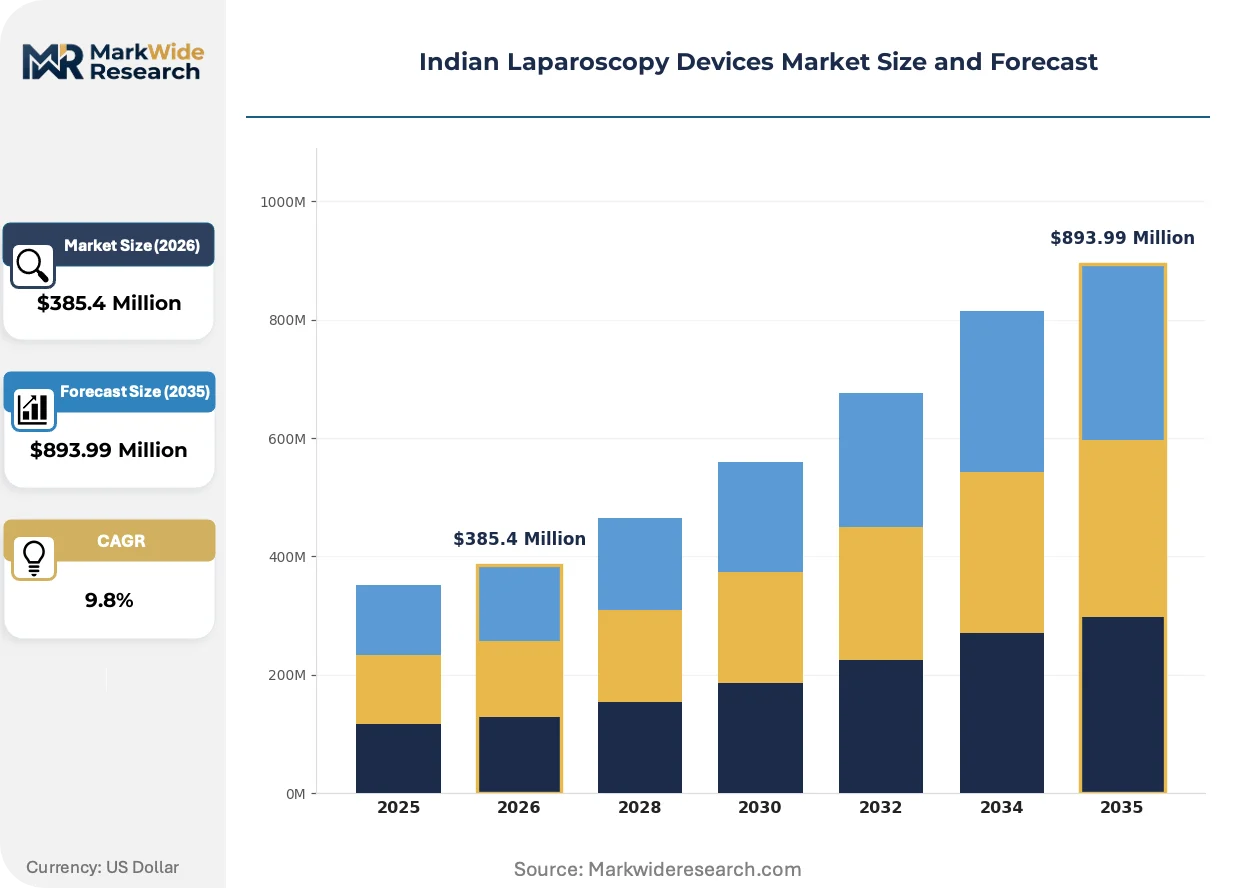
Market Dynamics
The PLI scheme for medical devices is restructuring competitive positioning by tilting procurement preferences toward domestic assembly. CDSCO licensing requirements and BIS electrical safety mandates are simultaneously raising compliance thresholds for imported equipment, creating a bifurcated market where localization capabilities determine contract eligibility.
Growth Catalysts
- Ayushman Bharat reimbursement thresholds:Expanded coverage for minimally invasive procedures is pulling surgical volume into accredited facilities. Tier-2 multispecialty hospitals are scaling laparoscopic capacity to capture this patient flow.
- CDSCO Medical Device Rules:Streamlined import licensing for Class C and D devices is accelerating product registration timelines. Foreign manufacturers are establishing local technical offices to manage regulatory submissions.
- Electrosurgical energy platforms:Integrated vessel sealing systems are reducing operative time and blood loss in bariatric and oncologic procedures. Adoption concentrates in Maharashtra and Karnataka where surgical training infrastructure is deepest.
Market Restraints
- Optical component import dependency:High-definition camera sensors and fiber-optic light guides rely on Chinese and German supply chains. Rupee volatility inflates landed costs for visualization systems.
- Capital intensity of robotic-assisted systems:Da Vinci installations require dedicated infrastructure and service contracts. District hospitals lack balance sheet capacity for these acquisitions.
- BIS electromagnetic compatibility certification:Testing protocols for electrosurgical units create six-to-nine month approval delays. Smaller manufacturers struggle with compliance documentation.
Strategic Opportunities
- Tier-3 city surgical centers:Kerala and Tamil Nadu panchayat-level facilities remain underserved for advanced laparoscopy. Mobile surgical units and equipment leasing models can penetrate these markets.
- Single-port access convergence with 4K visualization:Reduced-port techniques combined with ultra-high-definition imaging are enabling complex procedures through smaller incisions. Training partnerships with medical colleges accelerate adoption.
- PLI scheme component sourcing:Fiscal incentives for domestic manufacturing of trocars and insufflation tubing are attracting component suppliers to Gujarat and Andhra Pradesh special economic zones.
Industry Challenges
- Surgeon training pipeline constraints:Fellowship positions in minimally invasive surgery remain concentrated in Delhi-NCR and Mumbai. Tier-2 cities face persistent skill shortages for advanced laparoscopic oncology.
- Legacy equipment integration friction:New energy platforms must interface with existing Karl Storz and Olympus visualization stacks. Interoperability testing extends deployment timelines.
- CDSCO post-market surveillance compliance:Adverse event reporting and periodic safety update submissions impose administrative burdens on distributors. Resource-constrained regional players struggle with pharmacovigilance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indian Laparoscopy Devices Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $893.99 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Trocar, Camera System, Light Source, Electrosurgical Unit End User: Hospitals, Surgical Centers, Clinics, Research Institutions Application: Gynecology, Urology, General Surgery, Bariatrics Technology: Robotic-Assisted, 3D Imaging, High-Definition, Single-Port |
| Companies Covered | Medtronic, Olympus Corporation, Johnson & Johnson, Karl Storz, Intuitive Surgical, Stryker, B. Braun Melsungen AG, Richard Wolf, BD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indian Laparoscopy Devices Market Trends and Innovations
Digital integration and energy delivery advances are compressing the gap between diagnostic imaging and therapeutic intervention. Surgical workflows are converging around platforms that combine real-time visualization with intelligent tissue management.
4K-3D hybrid camera systems are delivering depth perception and anatomical detail previously unavailable in conventional laparoscopy. Corporate hospital chains in Bengaluru and Chennai are retrofitting operating theaters with these platforms to support complex hepatobiliary procedures. The technology is rendering obsolete standard-definition stacks that dominated Indian installations through the previous decade.
CDSCO's tightened adverse event reporting under the Medical Device Rules is forcing manufacturers to establish local quality management systems. Importers must now maintain vigilance databases and field safety corrective action protocols within Indian jurisdiction. Class C electrosurgical devices face the steepest compliance burden, with several European suppliers establishing wholly-owned subsidiaries to manage regulatory liability directly.
Leasing arrangements for capital equipment are displacing outright purchase in tier-2 hospital procurement. Tamil Nadu and Karnataka-based surgical centers prefer per-procedure fee structures that bundle maintenance and upgrade cycles. This model spreads technology access beyond institutions with dedicated capital budgets, though it compresses supplier margins and extends cash conversion cycles.
Indian Laparoscopy Devices Market Segmentation
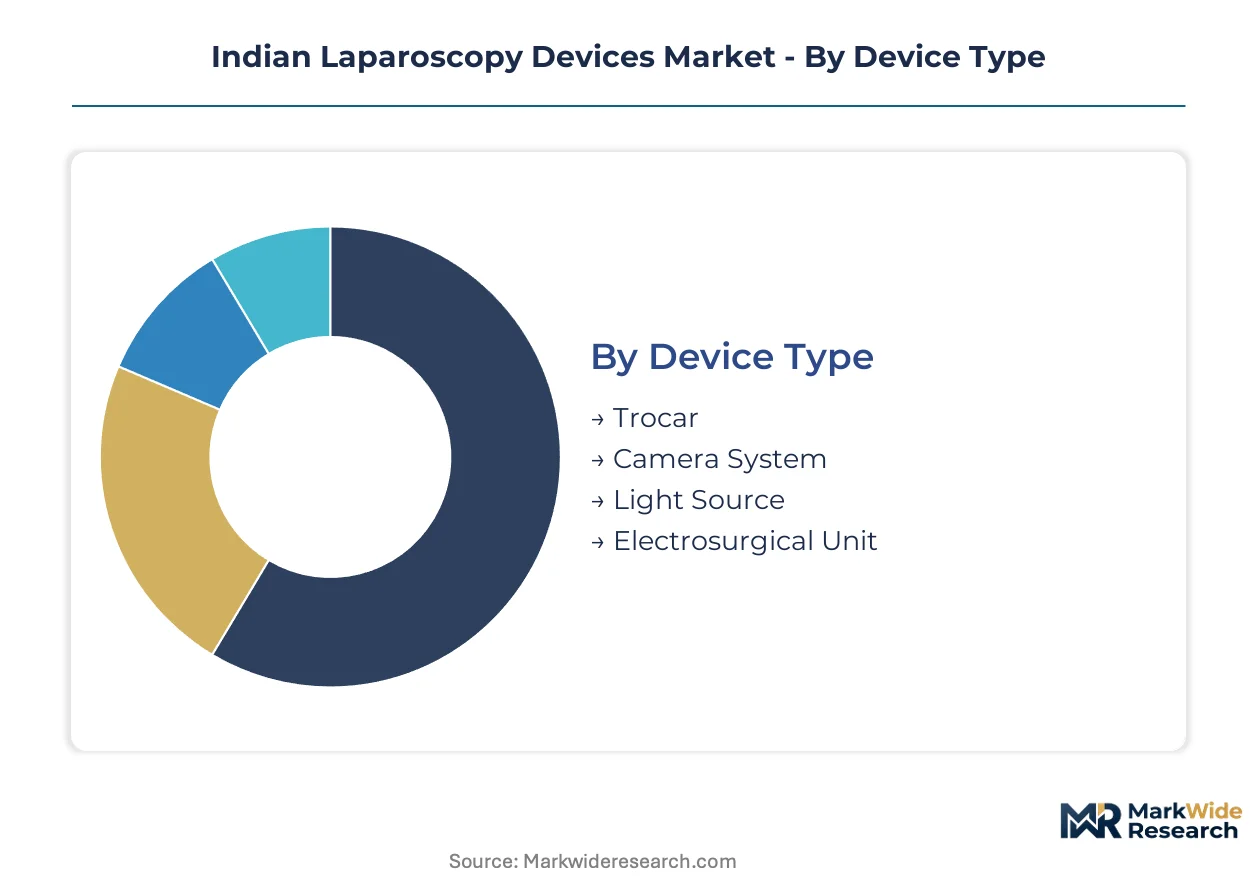
Segmentation reveals how procurement cycles and clinical workflows fragment demand across the Indian laparoscopy landscape. Device type and end-user distinctions matter most for forecasting replacement timelines and capital allocation priorities.
Device Type:
Camera systems and electrosurgical units turn over fastest due to technology refresh cycles and consumable dependencies, while trocars and light sources follow slower replacement rhythms tied to physical wear.
- Camera System:4K-3D hybrid platforms integrate CMOS sensors and proprietary image processing chips. Maharashtra and Karnataka corporate hospital chains are retrofitting operating theaters with these systems to support complex hepatobiliary procedures. The technology is rendering obsolete standard-definition stacks that dominated Indian installations through the previous decade.
- Electrosurgical Unit:Integrated vessel sealing platforms combine RF energy delivery with real-time tissue impedance feedback. Adoption concentrates in bariatric and oncologic centers where operative time reduction drives purchasing decisions. Recurring electrode and blade consumables generate sustained revenue streams for installed base holders.
- Trocar:Disposable polymer and reusable metal variants serve different cost-tier facilities. CDSCO Class C registration requirements favor established suppliers with quality management infrastructure.
- Light Source:LED and xenon systems power fiber-optic illumination for rigid endoscopes. Chinese and German optical component imports create landed cost volatility for domestic assemblers.
Camera systems anchor the volume base while electrosurgical units gain share at the steepest rate.
End User:
Capital intensity and procedure throughput create four distinct procurement profiles, from high-volume surgical centers to grant-dependent research facilities.
- Hospitals:Multispecialty institutions in tier-2 cities absorb the dominant device procurement volume. Ayushman Bharat accreditation requirements are pulling surgical infrastructure investment into Madhya Pradesh and Rajasthan.
- Surgical Centers:Ambulatory facilities in Tamil Nadu and Kerala prefer per-procedure leasing models over capital purchase. Payer acceptance of day-case laparoscopy is expanding throughput faster than hospital settings.
- Clinics:Diagnostic and minor procedure sites require portable, lower-cost visualization stacks. BIS electromagnetic compatibility certification creates compliance barriers for smaller equipment suppliers.
- Research Institutions:Medical colleges in Delhi-NCR and Mumbai anchor training infrastructure for advanced laparoscopic techniques. Fellowship program expansion depends on dedicated research budgets and industry partnerships.
Hospitals anchor the volume base while surgical centers gain share at the steepest rate.
Application:
Procedure complexity and reimbursement levels segment demand across four surgical specialties with distinct technology requirements and training barriers.
- Gynecology:Hysterectomy and myomectomy procedures drive the highest laparoscopic volume in Indian practice. Single-port access systems are reducing postoperative recovery times in Maharashtra fertility centers.
- General Surgery:Cholecystectomy and appendectomy form the foundational training base for minimally invasive technique adoption. Tier-3 city surgeons require sustained mentorship to progress beyond these procedures.
- Bariatrics:Sleeve gastrectomy and gastric bypass demand advanced energy platforms for thick tissue transection. Metabolic surgery centers in Bengaluru and Hyderabad are expanding capacity to address obesity prevalence.
- Urology:Nephrectomy and prostatectomy require 3D visualization for deep pelvic dissection. Robot-assisted technology is penetrating this segment faster than others despite capital constraints.
General surgery anchors the volume base while bariatrics climbs the fastest.
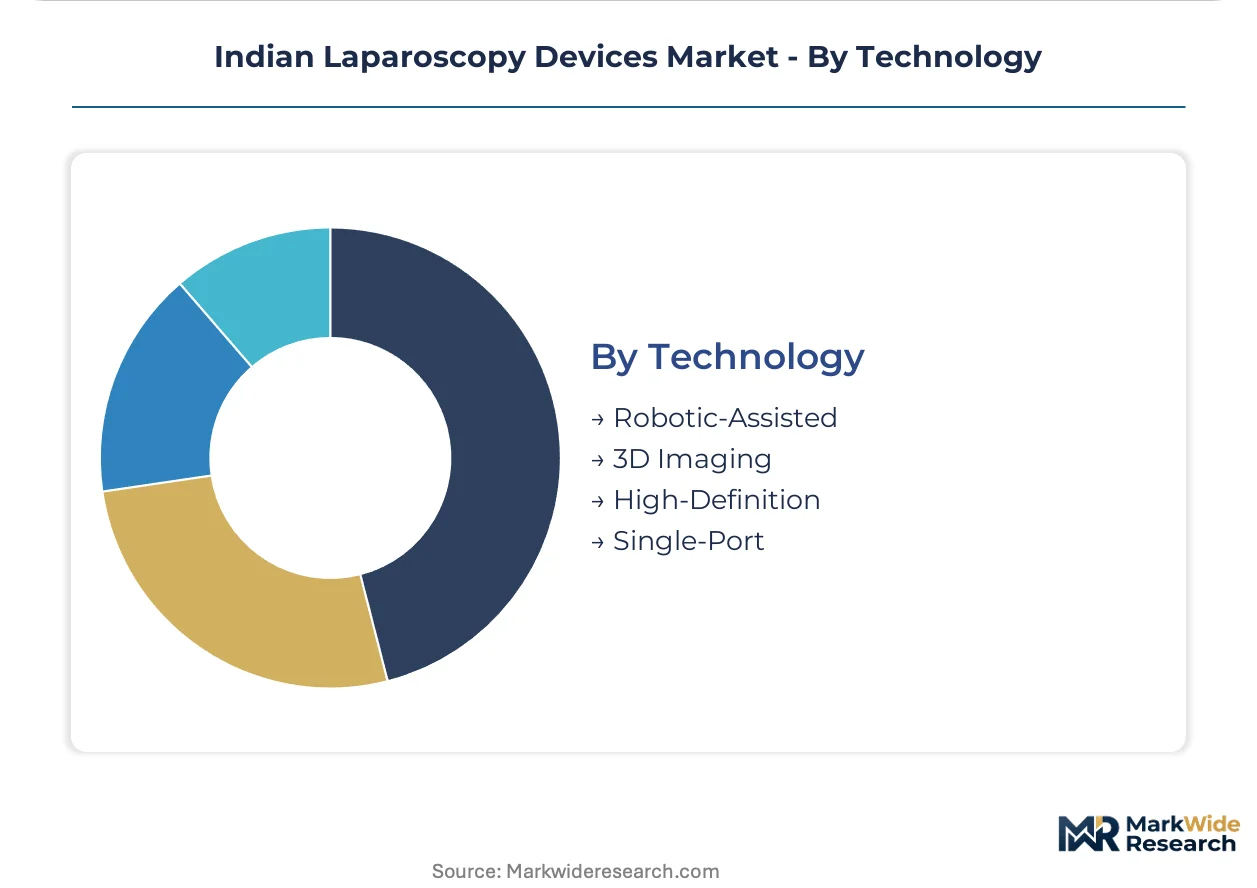
Technology:
Platform maturity and infrastructure requirements stratify adoption across four technology tiers with different learning curves and capital thresholds.
- High-Definition:1080p camera stacks remain the installed base standard across district hospitals. Upgrade cycles to 4K-3D systems are accelerating in corporate hospital chains with dedicated capital budgets.
- Single-Port:Reduced-access techniques combine multiple instruments through one incision site. Training partnerships with Tamil Nadu medical colleges are accelerating surgeon certification for these procedures.
- 3D Imaging:Stereoscopic visualization restores depth perception lost in conventional laparoscopy. Hepatobiliary and oncologic applications in Chennai and Mumbai surgical centers are driving initial deployment.
- Robotic-Assisted:Da Vinci systems require dedicated infrastructure and service contracts. District hospitals lack balance sheet capacity, concentrating installations in tertiary referral centers.
High-definition anchors the volume base while single-port gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India imports the majority of its high-definition camera sensors and fiber-optic components from Germany and China, creating persistent trade deficits in the visualization layer while domestic assembly of trocars and insufflation tubing expands under PLI incentives.
Maharashtra
Mumbai and Pune corporate hospital chains are retrofitting operating theaters with 4K-3D hybrid platforms for complex hepatobiliary procedures. CDSCO's streamlined Class C and D device licensing is accelerating product registrations from European suppliers. The Mumbai-Ahmedabad industrial corridor is attracting electrosurgical unit assemblers seeking proximity to western India surgical centers.
Karnataka
Bengaluru metabolic surgery centers are expanding sleeve gastrectomy capacity to address obesity prevalence. BIS electromagnetic compatibility certification mandates create six-to-nine month approval delays for imported electrosurgical equipment. The Bengaluru-Chennai medical device cluster is deepening domestic manufacturing of insufflation tubing and disposable trocars.
Tamil Nadu
Chennai surgical centers prefer per-procedure leasing models over capital purchase for ambulatory laparoscopy. Ayushman Bharat reimbursement thresholds are pulling surgical infrastructure investment into Madurai and Coimbatore. Medical colleges in Chennai are anchoring training partnerships for single-port access technique certification.
Telangana
Hyderabad bariatric centers are adopting integrated vessel sealing platforms for thick tissue transection. The PLI scheme for medical devices is attracting component suppliers to the Genome Valley special economic zone. Tier-2 cities like Warangal are scaling laparoscopic capacity to capture Ayushman Bharat patient flow.
Kerala
Kochi fertility centers are deploying single-port access systems to reduce postoperative recovery times. Panchayat-level facilities remain underserved for advanced laparoscopy, creating demand for mobile surgical units. Thiruvananthapuram medical colleges are expanding fellowship positions in minimally invasive gynecologic surgery.
Indian Laparoscopy Devices Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated multinational platforms and specialized component suppliers. CDSCO licensing requirements and BIS electrical safety mandates are raising compliance thresholds that favor established players with quality management infrastructure. Two strategic archetypes dominate: visualization-anchored conglomerates with proprietary camera ecosystems, and energy-platform specialists with recurring consumable revenue streams. Competitive moves concentrate on local technical office establishment for regulatory submission management and training partnership formation with medical colleges.
Among visualization-anchored conglomerates, Olympus Corporation and Karl Storz exemplify the premium-tier positioning sustained by rigid endoscope craftsmanship and proprietary light source ecosystems. Medtronic occupies a position representing the integrated energy platform archetype, with vessel sealing applications dominating advanced surgical workflows. These three entities anchor the competitive structure, with domestic assembly initiatives under the PLI scheme creating new positioning opportunities for localized production models.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| Johnson & Johnson |
| Karl Storz |
| Intuitive Surgical |
| Stryker |
| B. Braun Melsungen AG |
| Richard Wolf |
| BD |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-Ahmedabad industrial corridor's freight cost dynamics compress margins for visualization equipment while amplifying price differentiation between premium German camera systems and standard-tier Chinese alternatives. CDSCO import licensing fees and BIS certification costs layer onto landed prices, forcing procurement committees to weigh upfront capital against total cost of ownership across replacement cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels in the Indian laparoscopy market. Premium tiers command position through CDSCO Class D registration and proprietary 4K-3D image processing chips, while economy segments compete on disposable trocar volumes and stripped-down electrosurgical units. Cost compression in the standard tier intensifies because of PLI scheme domestic assembly incentives and rupee volatility inflating landed costs for German optical components. Tier-2 multispecialty hospitals exhibit highest price sensitivity, deferring upgrades to extend legacy equipment life; corporate hospital chains in Maharashtra and Karnataka show lowest sensitivity, prioritating technology refresh cycles and bundled service contracts.
Supply Chain Analysis
High-definition CMOS sensors and fiber-optic light guides draw from German and Chinese manufacturing clusters, with domestic assembly of trocars and insufflation tubing expanding under PLI scheme fiscal incentives. Raw material dependencies center on optical glass from Schott AG facilities, polymer resins for disposable ports, and precision-machined metal alloys for reusable instrument shafts. Single-source vulnerability concentrates in camera sensor fabrication, where Taiwanese foundry capacity constraints ripple through delivery timelines for Indian equipment distributors. Distribution runs through authorized dealer networks serving corporate hospital chains, with direct procurement relationships emerging for high-volume surgical center consortia in Tamil Nadu and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indian laparoscopy market rewards service-attach strategies as consumable electrode and blade revenue streams expand faster than capital equipment sales. Per-procedure leasing models and bundled maintenance contracts now generate recurring income exceeding hardware margins for installed base holders.
For Market Incumbents: Entrench competitive position by deepening backward integration into trocar polymer molding and insufflation tubing extrusion within Gujarat special economic zones. Acquire CDSCO licensing expertise through local technical office expansion to compress registration timelines for Class C electrosurgical devices. Counter emerging domestic assemblers by locking tier-2 hospital chains into multi-year service contracts with guaranteed upgrade pathways. For New Entrants and Emerging Players: Tier-3 city surgical centers in Kerala and Madhya Pradesh represent the most penetrable entry point, with panchayat-level facilities underserved for advanced laparoscopy and lacking capital budgets for premium-tier systems. Mobile surgical unit leasing and equipment-as-a-service models bypass upfront purchase barriers. Partner with Tamil Nadu medical colleges for single-port access training certification to accelerate surgeon adoption and build installed base loyalty. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational parents divesting non-core visualization divisions amid CDSCO regulatory complexity and local content pressure. Mid-cap domestic assemblers with PLI scheme approvals and established BIS certification infrastructure offer viable acquisition profiles. Watch Ayushman Bharat reimbursement threshold expansion into bariatric and oncologic procedures as the inflection signal for premium technology tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Registration Acceleration | Streamlined licensing timelines enable faster market entry for electrosurgical platforms competing against established holders. |
| PLI Scheme Component Localization | Domestic trocar and tubing assembly reduces landed cost volatility and qualifies for government procurement preferences. |
| Medical College Training Partnership | Single-port certification programs with Chennai and Bengaluru institutions build surgeon loyalty and equipment lock-in. |
| Per-Procedure Leasing Model Expansion | Tamil Nadu surgical center preference for fee-based structures spreads technology access beyond capital-rich buyers. |
| 4K-3D Visualization Platform Retrofit | Maharashtra corporate hospital chains upgrade obsolete standard-definition stacks to support complex hepatobiliary workflows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laparoscopic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CDSCO device registration databases, Ayushman Bharat reimbursement schedules, PLI scheme beneficiary disclosures, and BIS certification records. Bottom-up procedure volume estimates across gynecology, general surgery, bariatrics, and urology segments were triangulated against top-down capital expenditure flows from corporate hospital chain annual disclosures.
Calibration against historical replacement cycles and technology refresh patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, end-user facility tier, application specialty, and technology platform maturity. CAGRs were derived from installed base growth projections and per-procedure consumable attachment rates. Industry-specific forecast inputs incorporated surgeon training pipeline expansion timelines and state-level public procurement policy evolution.
Macroeconomic conditions sit as an overlay; deviation in rupee exchange rates, optical component import tariffs, or PLI scheme incentive continuity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory streamlining and reimbursement expansion. Cross-checking against hospital capital budget disclosures and medical device import customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Urodynamic Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Global Otoscopes Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Global Glaucoma Surgery Devices Market