
 Disposable Bronchoscopes Market | 2026-2036
Disposable Bronchoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Bronchoscopes Market Intelligence
The EU Medical Device Regulation is rebalancing procurement criteria toward single-use bronchoscopes by elevating sterility assurance requirements above cost metrics. Olympus Corporation leverages its endoscopy manufacturing scale to sustain supply chain reliability across European hospital networks. AMBU A/S anchors its competitive position through dedicated single-use production lines that eliminate reusable device reprocessing entirely. Boston Scientific Corporation differentiates via integrated visualization platforms that pair disposable bronchoscopes with proprietary imaging systems.
A disposable bronchoscope is a single-use flexible endoscope, typically 2.0–5.8 mm in outer diameter with a working channel of 1.2–2.6 mm, manufactured from medical-grade polymers and fiber optic or digital imaging bundles for airway examination and intervention without sterilization cycles. The device serves pulmonologists and critical care physicians performing bedside bronchoscopy, bronchoalveolar lavage, and foreign body retrieval where cross-contamination risks outweigh economic considerations. Ultra-thin variants are capturing the fastest expansion as neonatal and pediatric intensive care units demand smaller outer diameters for fragile airways. Hospitals dominate procurement volume, though outpatient clinics are emerging as a concentrated margin pool where procedure economics favor disposables over capital-intensive reprocessing infrastructure.
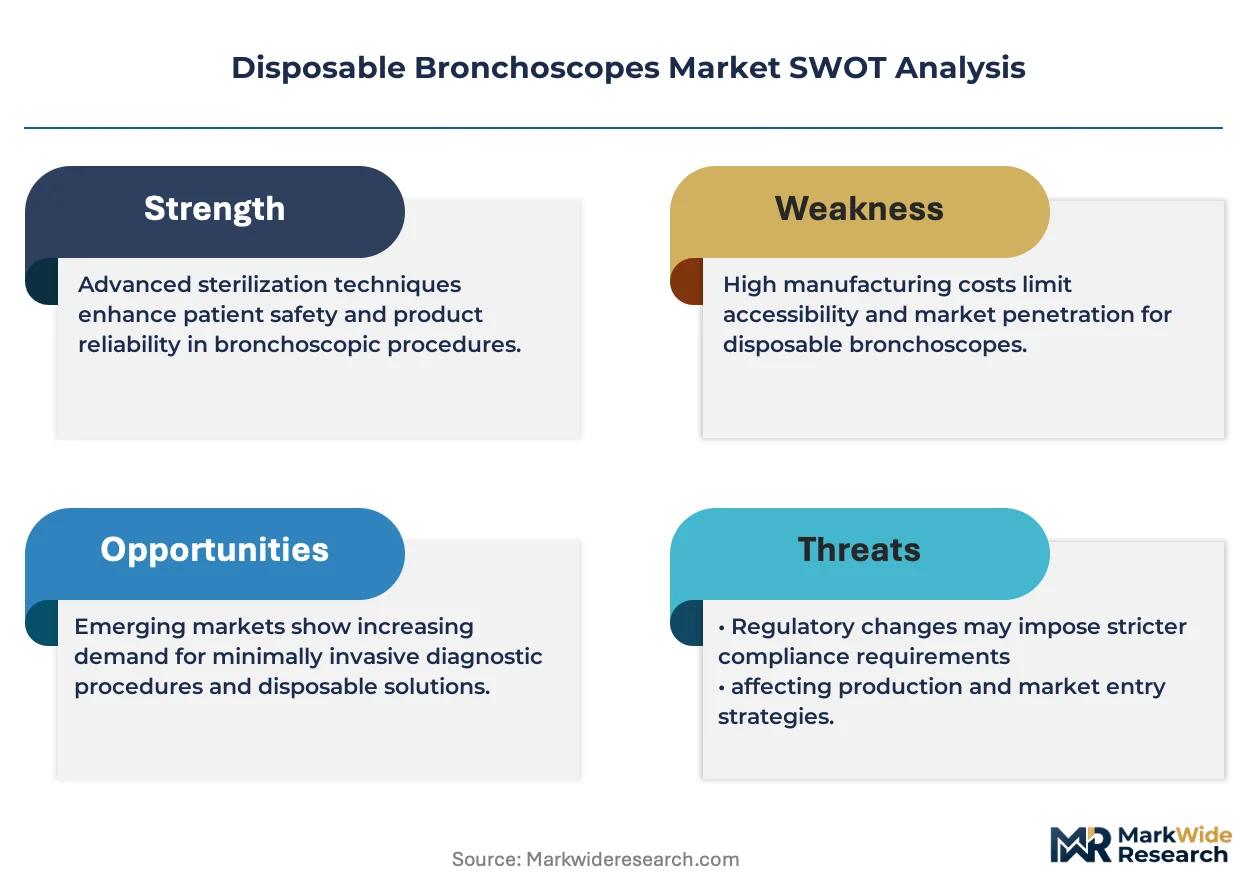
FDA reprocessing guidelines, EU MDR sterility benchmarks, and ISO 13485 quality management standards collectively determine market access thresholds and product validation requirements for disposable bronchoscope manufacturers. The FDA's safety communications on multidrug-resistant organism transmission via bronchoscopes have directly expanded hospital demand for single-use alternatives. Stakeholders must monitor how reimbursement parity between disposable and reusable bronchoscopy evolves across national health technology assessment frameworks.
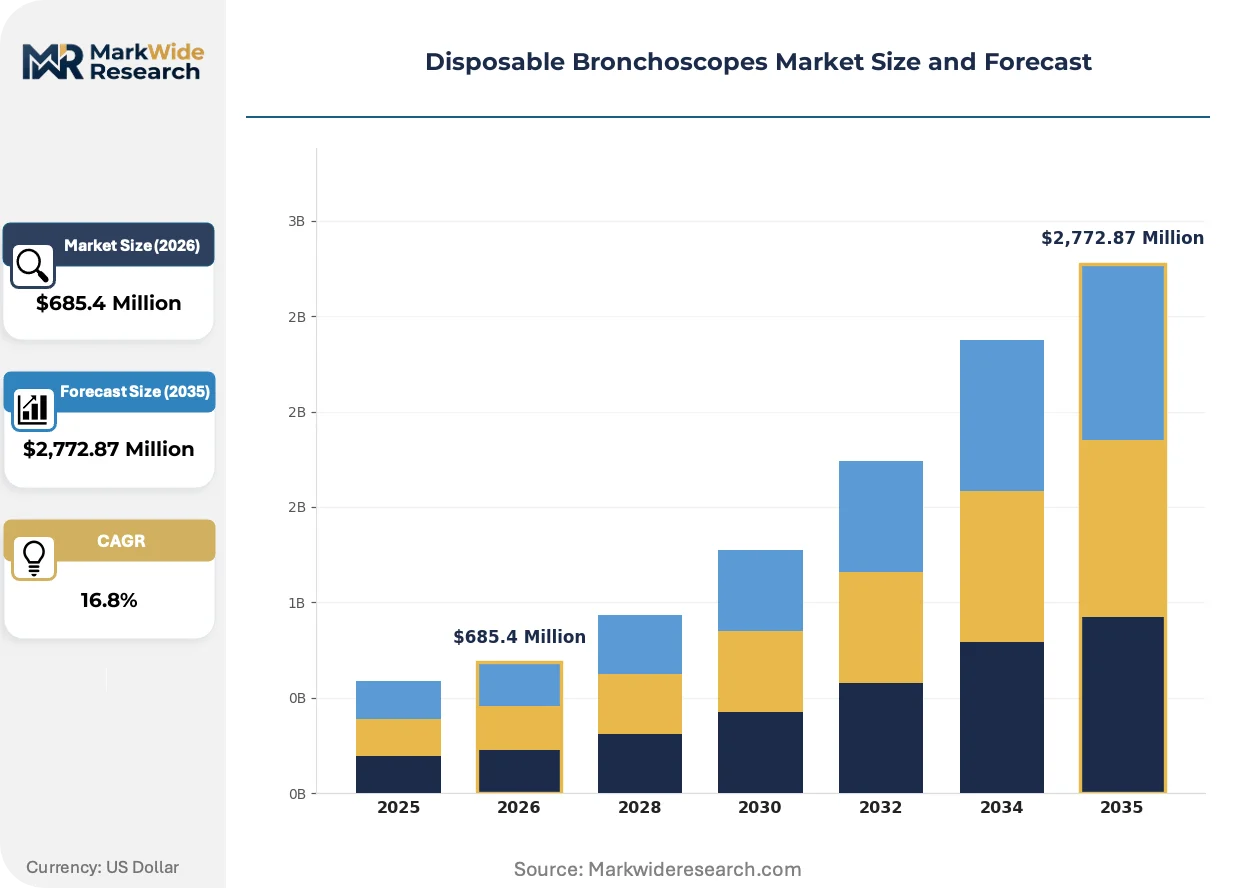
Market Dynamics
The FDA's updated reprocessing guidance for flexible endoscopes is eliminating the cost advantage of reusable bronchoscopes in US health systems, forcing procurement committees to recalculate total cost of ownership around infection risk rather than per-procedure device expense.
Growth Catalysts
- EU MDR sterility mandates:The EU Medical Device Regulation elevates sterility assurance requirements above cost metrics in procurement evaluations, rebalancing hospital purchasing criteria toward single-use platforms.
- Neonatal ICU demand:Ultra-thin bronchoscope variants are capturing fastest expansion as pediatric intensive care units require smaller outer diameters for fragile infant airways.
- Immunocompromised patient volumes:Tertiary hospital intensive care units are expanding single-use adoption to eliminate cross-contamination risks between vulnerable patient populations.
Market Restraints
- Polymer supply concentration:Medical-grade polymer feedstocks for bronchoscope manufacturing concentrate among specialty chemical suppliers, exposing production schedules to petrochemical volatility.
- Reimbursement parity gaps:National health technology assessment frameworks in Germany and France maintain payment differentials between disposable and reusable bronchoscopy procedures.
- Capital infrastructure lock-in:Health systems with recent investments in automated endoscope reprocessors face sunk-cost barriers to switching.
Strategic Opportunities
- Outpatient clinic channel:Ambulatory surgical centers represent concentrated margin pools where procedure economics favor disposables over capital-intensive reprocessing infrastructure.
- ISO 13485 quality certification:Manufacturers achieving quality management certification unlock preferential supplier status in European hospital procurement coalitions.
- Digital imaging convergence:Integration of disposable bronchoscopes with proprietary visualization platforms creates bundled service contracts that lock in recurring revenue streams.
Industry Challenges
- Pulmonology training adaptation:Residency programs must restructure bronchoscopy curricula around single-use device handling rather than reusable instrument maintenance protocols.
- Waste management compliance:Health systems face escalating costs for regulated medical waste disposal of polymer-based single-use devices under EPA guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Bronchoscopes Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,772.87 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Ultra-thin, Curved, Standard End User: Hospitals, Outpatient Clinics, Surgical Centers, Diagnostic Labs Application: Respiratory Procedures, Surgical Interventions, Diagnostics, Therapeutic Treatments Delivery Mode: Direct Sales, Online Channels, Distributors, Third-party Suppliers |
| Companies Covered | Olympus Corporation, AMBU A/S, Boston Scientific Corporation, FUJIFILM Holdings Corporation, Karl Storz GmbH & Co. KG, Smith & Nephew Inc., PENTAX Medical, NeoScope Inc., Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Bronchoscopes Market Strategic Shifts & Innovations
Disposable bronchoscope architecture is fragmenting into specialized form factors as manufacturers engineer diameter-specific devices for distinct anatomical applications rather than pursuing universal-platform designs.
Digital imaging bundles are modularizing bronchoscope production by separating the visualization core from the disposable insertion tube, enabling hospitals to retain capital-intensive camera systems while consuming only the polymer sheath. Pulmonology departments in tertiary centers are adopting this hybrid architecture fastest, compressing the replacement cycle for imaging electronics from five years to continuous upgrade paths. The structural consequence is unbundling what was previously integrated capital equipment into separable recurring consumables.
EU MDR implementation timelines are compressing market access windows for non-compliant manufacturers, with notified body bottlenecks extending certification timelines to eighteen months. European hospital procurement coalitions are responding by pre-qualifying only MDR-certified suppliers for tender participation, effectively freezing out legacy device portfolios. German infection control mandates are bundling single-use bronchoscopes into hospital accreditation requirements.
Hospital purchasing committees are consolidating vendor relationships around full-procedure bundles rather than discrete device procurement, demanding that disposable bronchoscope suppliers integrate suction, irrigation, and specimen collection accessories into single-SKU offerings. This unbundling of component sourcing is most visible in US health systems responding to FDA safety communications on multidrug-resistant organism transmission. Critical care departments are prioritizing suppliers with validated supply chain continuity over lowest unit cost.
Disposable Bronchoscopes Market Segmentation
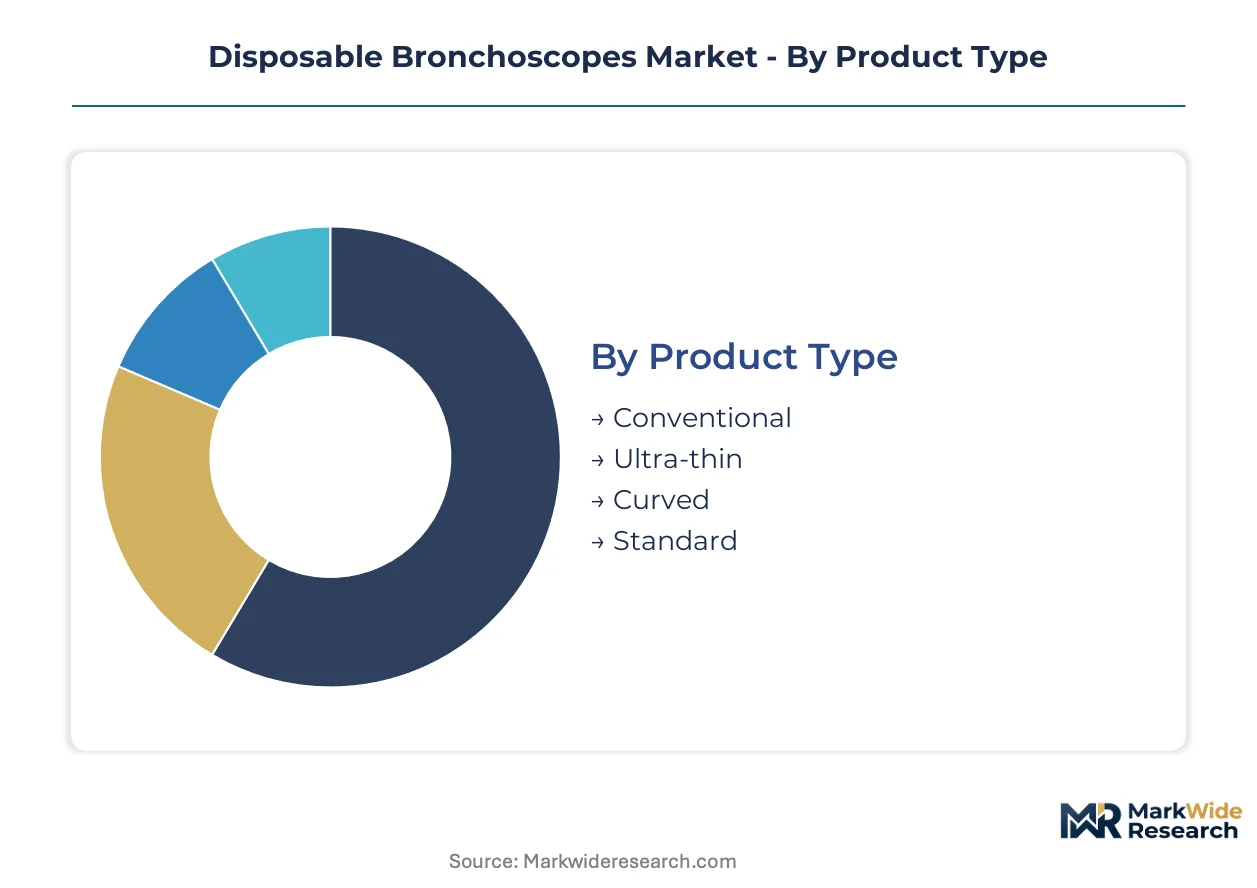
Disposable bronchoscope segmentation reveals how procurement criteria diverge across clinical settings, with infection control mandates reshaping product specifications and channel preferences. Manufacturers must align form factor engineering with distinct anatomical requirements while navigating fragmented purchasing authority between hospital supply chains and outpatient capital budgets.
Product Type:
Outer diameter and working channel dimensions differentiate clinical utility across patient populations and procedural complexity.
- Ultra-thin:These devices feature outer diameters below 2.8 mm with working channels of 1.0–1.2 mm, constructed from high-tensile polymers to navigate neonatal and pediatric airways without tissue trauma. Demand concentrates in tertiary pediatric intensive care units across Germany and France where fragile infant anatomy prohibits standard instrument insertion. EU MDR sterility mandates accelerate replacement of reusable pediatric bronchoscopes in these settings.
- Conventional:Specifications span 4.0–5.8 mm outer diameter with 2.0–2.6 mm working channels, serving adult pulmonology departments for bronchoalveolar lavage and foreign body retrieval. US health systems responding to FDA reprocessing guidance favor this segment for high-volume bedside procedures where cross-contamination risks outweigh per-procedure costs.
- Curved:Angled distal tips of 90–120 degrees enable navigation of anatomically distorted airways in oncology and post-surgical patients.
- Standard:General-purpose configurations balance visualization quality with suction capability for routine diagnostic bronchoscopy.
Volume sits with Conventional; growth tilts toward Ultra-thin.
End User:
Capital intensity and reprocessing infrastructure availability determine purchasing authority and contract structures.
- Hospitals:Tertiary medical centers command procurement volume through centralized supply chains, bundling disposable bronchoscopes into infection control accreditation requirements. German hospital procurement coalitions negotiate multi-year framework agreements that lock in supply continuity for intensive care units.
- Surgical Centers:Ambulatory settings lack automated endoscope reprocessors, making single-use devices economically rational despite higher per-unit costs. These facilities in the US Southeast and Midwest represent concentrated margin pools where procedure throughput justifies premium pricing.
- Outpatient Clinics:Pulmonology practices performing diagnostic bronchoscopy favor disposables to eliminate capital equipment investments.
- Diagnostic Labs:Specimen collection workflows drive demand for bronchoscopes with integrated suction and irrigation channels.
Hospitals dominate procurement tonnage; Surgical Centers expand most quickly.
Application:
Procedural reimbursement parity and clinical urgency shape device selection criteria.
- Respiratory Procedures:Bedside bronchoscopy for ventilator-associated pneumonia and acute respiratory failure demands immediate device availability without reprocessing delays. US critical care departments prioritize supply chain reliability over unit cost for these emergency applications.
- Surgical Interventions:Foreign body retrieval and airway stent placement require robust working channels and precise articulation control. Tertiary centers in France bundle these devices with interventional pulmonology service lines.
- Diagnostics:Elective tissue sampling and visual inspection follow scheduled workflows with lower urgency tolerance.
- Therapeutic Treatments:Laser ablation and cryotherapy applications demand specialized channel configurations.
Respiratory Procedures anchor current volume; Surgical Interventions gain share fastest.
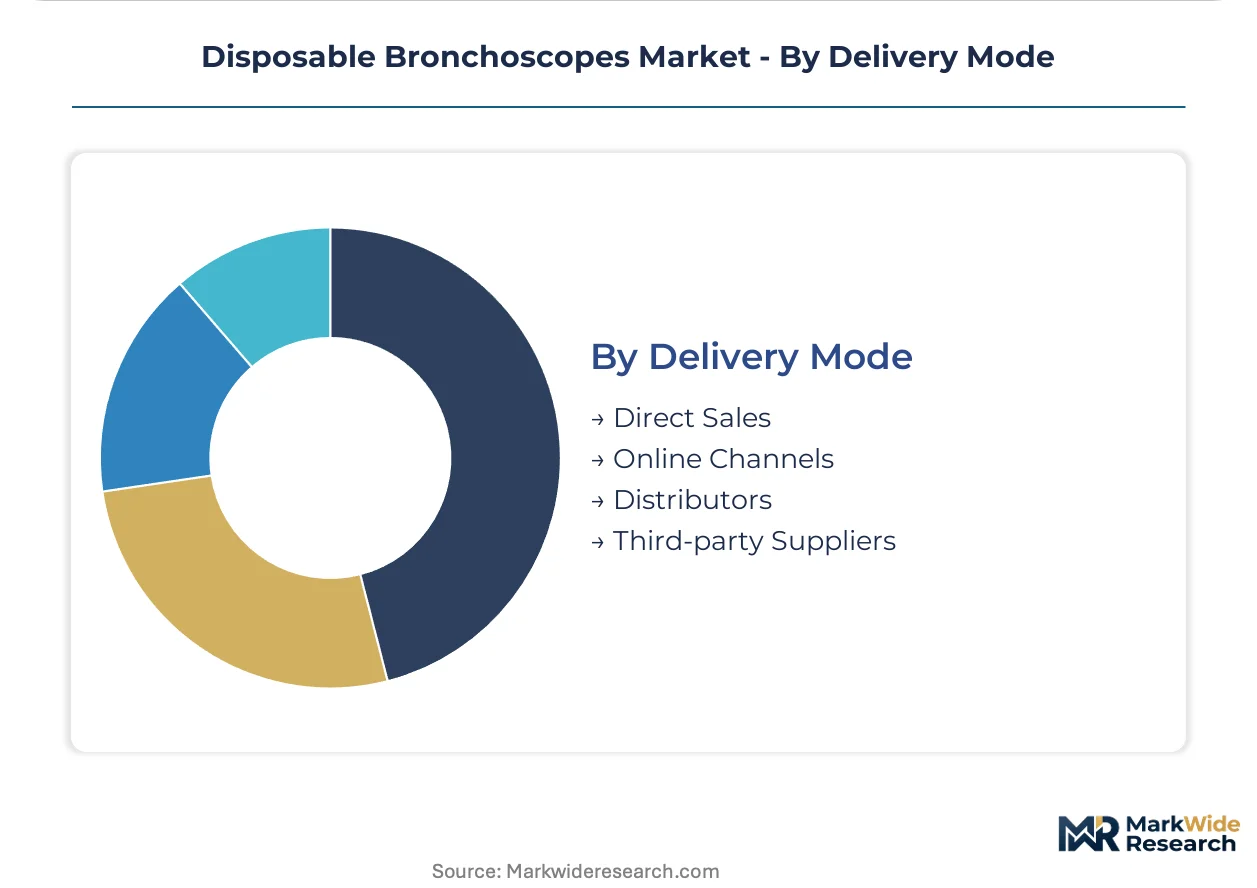
Delivery Mode:
Channel selection reflects contract complexity and geographic concentration of demand.
- Distributors:Regional medical supply distributors maintain inventory proximity to hospital clusters, compressing lead times for emergency replenishment. German and French procurement coalitions route volume through authorized distribution networks to enforce MDR compliance verification.
- Direct Sales:Manufacturers deploy field specialists for large health system negotiations, structuring multi-hospital agreements with price-volume tiers. US integrated delivery networks favor direct relationships to coordinate standardization across affiliated facilities.
- Online Channels:E-procurement platforms serve outpatient clinics with predictable demand patterns and lower contract complexity.
- Third-party Suppliers:Group purchasing organizations aggregate demand across independent facilities.
Distributors handle current volume concentration; Direct Sales capture expanding health system consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American single-use bronchoscope procurement as health system consolidation concentrates purchasing authority within integrated delivery networks. German hospital procurement coalitions in the Rhine-Ruhr corridor negotiate framework agreements that bundle infection control mandates with device supply contracts.
United States
FDA reprocessing guidance eliminates cost advantages for reusable bronchoscopes in tertiary intensive care units across Texas Medical Center and Mayo Clinic networks. The agency's safety communications on multidrug-resistant organism transmission accelerate hospital transitions to single-use platforms. Boston and Philadelphia health systems lead procurement volume for bedside bronchoscopy in immunocompromised patient populations.
Germany
Hospital procurement coalitions in Bavaria and North Rhine-Westphalia bundle single-use bronchoscopes into mandatory infection control accreditation requirements. EU MDR sterility benchmarks elevate procurement criteria above per-unit cost metrics, freezing out non-certified suppliers. The Frankfurt-Rhine-Main medical technology cluster concentrates distribution infrastructure for Central European hospital networks.
France
ANSM post-market surveillance requirements tighten sterility validation for flexible endoscopes in Paris and Lyon tertiary centers. EU MDR implementation extends certification timelines, compressing market access for manufacturers without notified body relationships. The Grenoble-Alps corridor hosts specialized production for ultra-thin pediatric bronchoscope variants.
Japan
PMDA quality management standards align with ISO 13485 certification requirements for manufacturers supplying Tokyo and Osaka university hospitals. METI medical device pricing regulations maintain reimbursement differentials between disposable and reusable bronchoscopy procedures. The Kobe biomedical cluster concentrates import distribution for single-use endoscopy platforms.
United Kingdom
NICE health technology assessments evaluate total cost of ownership for single-use bronchoscopes against reusable alternatives in London and Manchester hospital trusts. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements for EU-certified manufacturers. The Cambridge-Oxford-London golden triangle concentrates procurement innovation for NHS supply chain modernization.
Disposable Bronchoscopes Market Key Industry Players
Premium-margin players sit above commodity-margin players across sterility assurance and supply chain reliability dimensions in hospital procurement evaluations. The vendor base organizes into three tiers: diversified endoscopy conglomerates with reusable legacy portfolios, pure-play single-use specialists with dedicated polymer production lines, and integrated visualization platform vendors bundling disposable scopes with proprietary imaging systems. Dominant competitive moves include M&A to acquire MDR certification capabilities and capacity expansion into ultra-thin pediatric form factors.
Within the diversified conglomerate tier, Olympus Corporation and FUJIFILM Holdings Corporation occupy positions anchored by endoscopy manufacturing scale and hospital network relationships. AMBU A/S exemplifies the pure-play single-use specialist archetype with Danish-registered corporate structure. Boston Scientific Corporation sits within the integrated platform tier, representing US-based medical technology conglomerate positioning. Karl Storz GmbH & Co. KG anchors German precision instrument fabrication heritage.
| Leading Market Players |
|---|
| Olympus Corporation |
| AMBU A/S |
| Boston Scientific Corporation |
| FUJIFILM Holdings Corporation |
| Karl Storz GmbH & Co. KG |
| Smith & Nephew Inc. |
| PENTAX Medical |
| NeoScope Inc. |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned polymer specialists in Germany and Denmark anchor medical-grade resin supply, translating their captive feedstock control into pricing discipline that resists commoditization pressure from Asian contract manufacturers. This ownership concentration allows incumbent device producers to maintain margin structures even as hospital procurement coalitions consolidate purchasing volume.
Pricing Analysis
Value-based pricing anchored to infection-risk reduction outcomes dominates hospital procurement evaluations, with EU MDR certification tiers separating premium suppliers from economy entrants. Price differentiation rests on sterility assurance validation and supply chain continuity guarantees rather than unit cost alone. Cost compression in standard-diameter segments is intensifying as Chinese contract manufacturers achieve ISO 13485 certification. Outpatient clinics exhibit highest price sensitivity due to capital budget constraints, while tertiary ICU departments prioritize reliability over per-procedure expense.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical producers of medical-grade polycarbonates and fiber-optic imaging bundles. Raw material dependencies include high-purity polymer resins, CMOS sensor arrays, and precision-molded distal tip components. Regulatory restriction risk concentrates in EU MDR notified body bottlenecks that extend certification timelines. Distribution runs through regional medical supply distributors maintaining inventory proximity to hospital clusters, with direct sales capturing expanding integrated delivery network consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR sterility mandates erect barrier-to-entry moats that favor incumbent manufacturers with notified body relationships and quality management infrastructure already validated.
For Market Incumbents: Lock in multi-year framework agreements with German hospital procurement coalitions before MDR certification backlogs clear and new entrants achieve market access. Acquire ultra-thin pediatric production capabilities to defend against pure-play specialists capturing neonatal ICU demand. Prioritize backward integration into polymer resin supply to insulate margins from petrochemical volatility. For New Entrants and Emerging Players: E-procurement platforms serving US outpatient clinics represent the most penetrable channel, bypassing capital-intensive direct sales forces and GPO contract complexity. Target ambulatory surgical centers in the American Southeast and Midwest where reprocessing infrastructure absence creates natural single-use preference. Pursue ISO 13485 certification as the non-negotiable market access threshold before any commercial engagement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap device manufacturers with stalled MDR certification timelines in France and Italy, where notified body queue congestion has frozen revenue recognition. Long-term viability hinges on positioning for post-certification supply gaps as hospital procurement coalitions rebid framework agreements. Monitor FDA safety communication frequency as the inflection signal for accelerated US health system transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body relationships unlock tender participation in German hospital procurement coalitions. |
| Ultra-Thin Product Line Expansion | Pediatric ICU demand in France and Germany outstrips current supply capacity. |
| Hospital System Partnership | Integrated delivery networks in Texas and Minnesota consolidate standardization authority. |
| Backward Integration into Polymers | Captive resin supply insulates production schedules from petrochemical price swings. |
| Digital Imaging Platform Integration | Proprietary visualization systems lock in recurring consumable revenue streams. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and pulmonology department heads. FDA 510(k) databases, EU MDR notified body certification registries, CMS Medicare reimbursement schedules, and German hospital procurement coalition tender documents provided demand-side validation. Bottom-up device shipment estimates triangulated against top-down health system expenditure models.
Data-stream reconciliation across volume-based shipment tracking and value-based procurement contract analysis informed the projection framework. Segmentation dimensions modeled include outer diameter specifications, end-user facility type, procedural application category, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to hospital accreditation mandate implementation timelines and FDA safety communication issuance patterns. Reimbursement parity evolution and polymer feedstock price trajectories served as scenario-weighting inputs.
Inputs from notified body certification databases and hospital procurement coalition tender archives were available through the study window; gaps in real-time outpatient clinic transaction data introduce uncertainty bands around ambulatory segment estimates. Forecasts reflect documented assumptions regarding MDR implementation velocity and reimbursement framework stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Endoscopy Device Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Industrial Endoscope Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Endotherapy Devices Market