
 Gastroscopes Market | 2026-2036
Gastroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Gastroscopes Market Analysis
Capital-intensity divergence between players is bifurcating the competitive landscape. Olympus Corporation leverages in-house optical component manufacturing to sustain premium positioning across flexible gastroscope lines. Fujifilm Holdings Corporation anchors its portfolio through digital imaging R&D intensity, competing on sensor resolution rather than scope mechanics.
Gastroscopes are flexible or rigid endoscopic instruments incorporating fiber-optic or digital image sensor bundles, typically 8-12mm in diameter, designed for direct visualization and tissue sampling of the upper gastrointestinal tract. Video gastroscopes now dominate hospital procurement due to superior image quality and documentation compliance, while wireless technology segments attract outpatient surgery centers seeking procedure efficiency. Digital imaging platforms command margin concentration because software-integrated systems lock in recurring service contracts and consumable revenues.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers. ISO 13485 quality management standards and IEC 60601-1 electrical safety benchmarks further constrain design choices for wireless-enabled devices. Stakeholders must monitor reimbursement shifts toward outpatient endoscopy and reprocessing liability frameworks that could reshape capital-versus-disposable purchasing decisions.
Market Dynamics
Video gastroscope adoption is compressing fiber-optic scope margins while FDA and EU MDR reprocessing mandates reshape hospital procurement criteria toward single-use and disposable alternatives.
Growth Catalysts
- Aging demographics in Japan:Screening volumes for gastric cancer detection are expanding among patients over 65, driving hospital investment in high-definition imaging platforms.
- FDA 510(k) pathway streamlining:Predicate device clearances for wireless-enabled gastroscopes are accelerating time-to-market for digital imaging upgrades.
- Outpatient migration:Ambulatory surgery centers are procuring compact video systems to capture procedure volume shifting from inpatient settings.
Market Restraints
- Optical component supply concentration:Precision lens and sensor fabrication clusters in specific East Asian manufacturing zones create vulnerability to logistics disruptions.
- EU MDR technical documentation burden:Clinical evidence requirements for reusable device revalidation are extending certification timelines and inflating regulatory compliance costs.
- Single-use scope cost premium:Disposable gastroscope per-procedure economics remain prohibitive for budget-constrained public hospital systems in emerging markets.
Strategic Opportunities
- India's diagnostic infrastructure expansion:Government hospital modernization programs and private diagnostic chain rollouts are creating demand for mid-tier video systems.
- Artificial intelligence integration:Real-time polyp detection algorithms are converging with 4K imaging sensors to enable autonomous screening assistance.
- Reimbursement tailwinds in Germany:Outpatient endoscopy procedure codes are expanding coverage for advanced imaging modalities in statutory health insurance.
Industry Challenges
- Biomedical technician specialization gap:Complex video processor and sensor calibration requirements exceed training capacity at smaller healthcare facilities.
- Legacy system integration friction:Hospital IT departments face interoperability hurdles connecting new digital platforms to existing PACS and EMR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastroscopes Market |
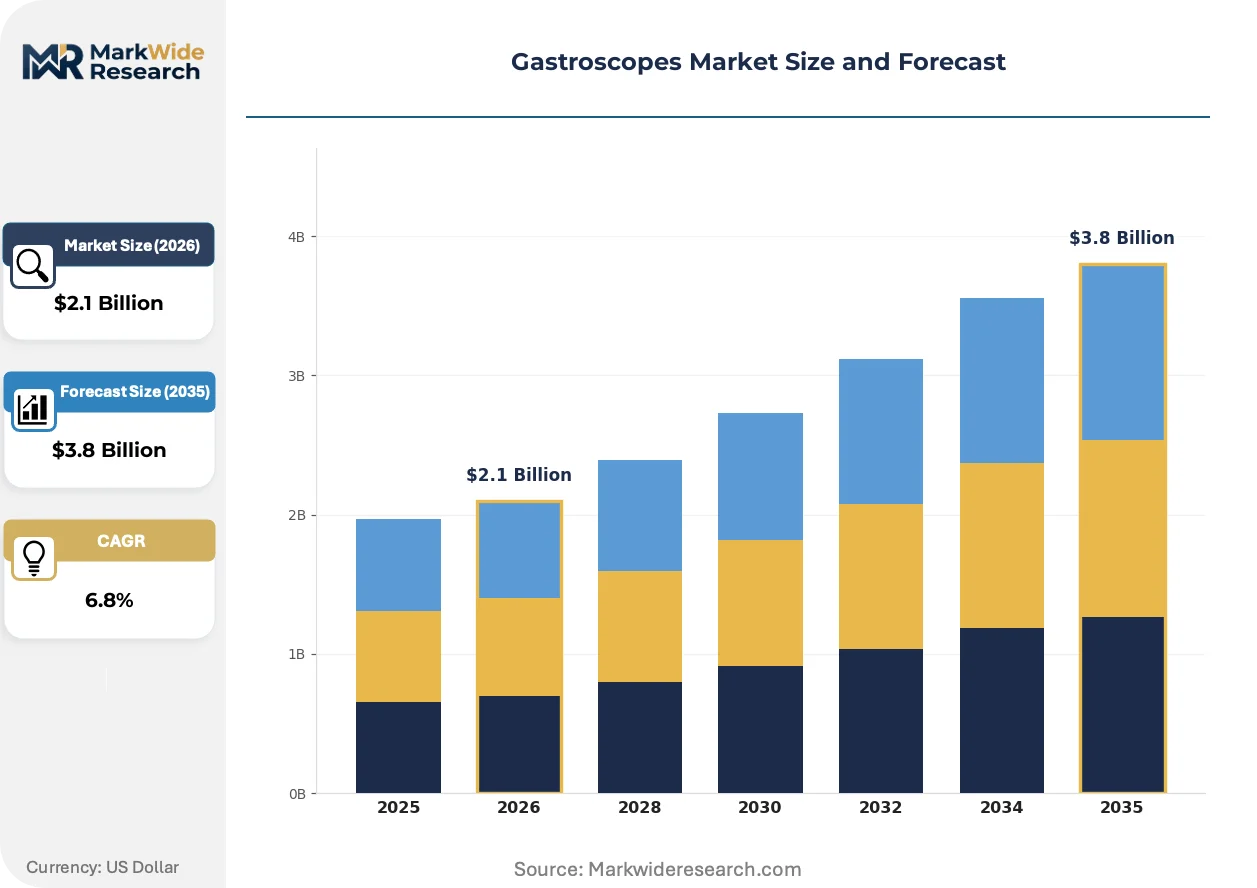
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Gastroscopes, Rigid Gastroscopes, Video Gastroscopes, Digital Gastroscopes End User: Hospitals, Clinics, Outpatient Surgery Centers, Diagnostic Centers Technology: Optical Imaging, Digital Imaging, Video Recording, Wireless Technology Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Olympus Corporation, Fujifilm Holdings Corporation, Karl Storz SE & Co. KG, Boston Scientific Corporation, Hoya Corporation (Pentax Medical), Medtronic plc, Richard Wolf GmbH, Stryker Corporation, Sonoscape Medical Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastroscopes Market Emerging Trajectories
Digital imaging architectures are supplanting legacy fiber-optic transmission while regulatory pressure on reprocessing safety accelerates single-use alternatives and AI-assisted diagnostics.
4K and 3D imaging sensor arrays are displacing standard-definition video processors in premium gastroscope lines. Tertiary care hospitals in the United States and Japan are adopting these platforms for early neoplasia detection. The shift is compressing margins for manufacturers without captive sensor supply or software development capabilities.
EU MDR Annex XVI requirements for reusable surgical instrument reprocessing validation are forcing manufacturers to submit enhanced clinical data packages. This regulatory friction is extending product lifecycle management costs and favoring incumbents with established notified body relationships. German and French hospital procurement offices are now mandating MDR-compliant documentation as a gate for tender participation.
Hospital buying committees are unbundling after-sales service contracts from capital equipment purchases. This behavioral shift is disrupting the traditional bundled pricing model that locked in multi-year maintenance revenues. The pattern is most pronounced in United States integrated delivery networks negotiating enterprise-wide endoscopy fleet replacements.
Gastroscopes Market Segmentation
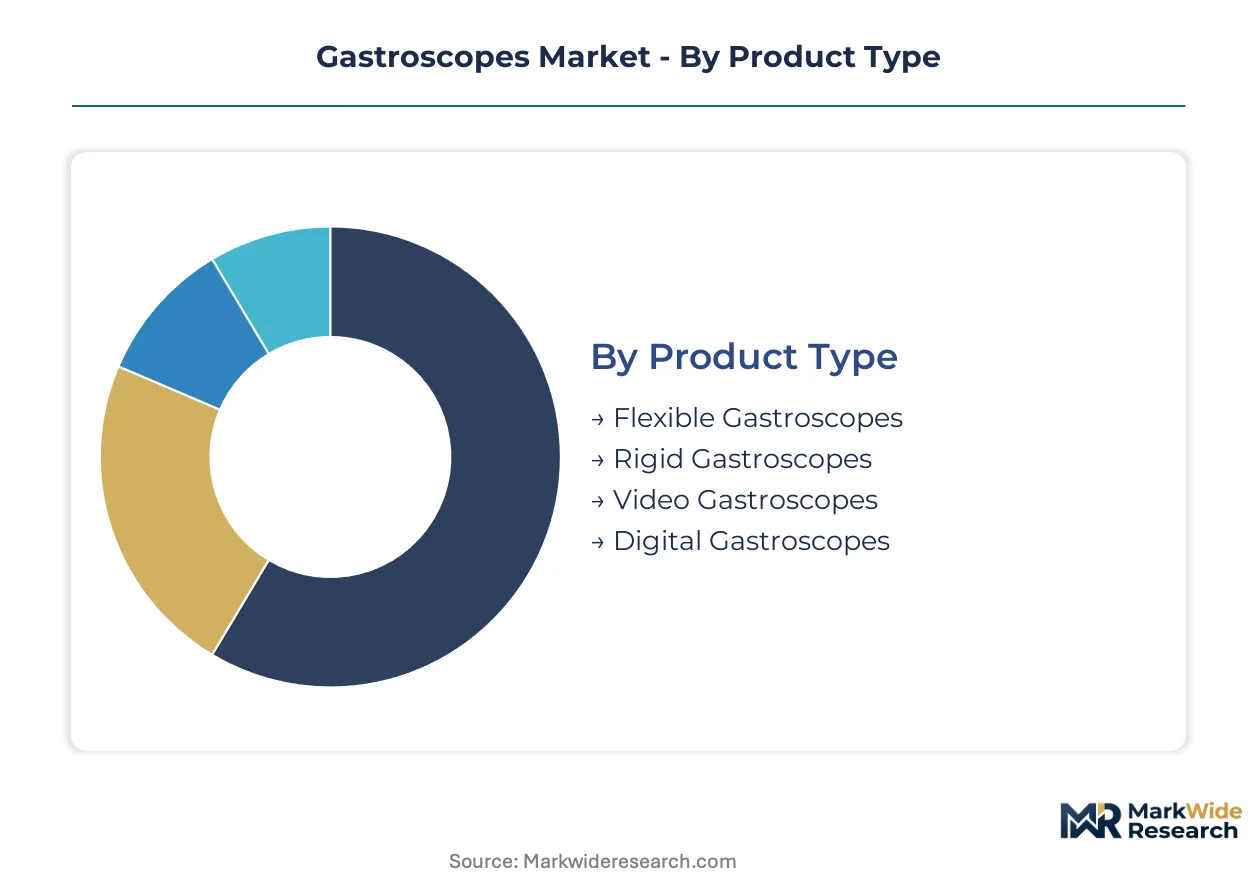
Gastroscope purchasing patterns diverge sharply across care settings and procurement channels. Product specifications, technology platforms, and distribution pathways must align with distinct clinical workflows and capital allocation constraints.
Product Type:
Channel mix varies by scope flexibility and imaging architecture. Video and digital platforms flow predominantly through direct sales with bundled service contracts, while flexible gastroscopes reach smaller facilities via distributor networks.
- Flexible Gastroscopes:Fiber-optic or sensor-based scopes with maneuverable insertion tubes enable navigation of the esophageal curvature and gastric folds. Demand concentrates in Japanese and German tertiary hospitals performing high-volume screening programs, constrained by EU MDR reprocessing validation costs.
- Video Gastroscopes:CCD or CMOS sensor arrays transmit high-definition images to external processors for documentation and AI-assisted detection. United States integrated delivery networks are consolidating procurement around these platforms to standardize fleet maintenance and training protocols.
- Rigid Gastroscopes:Stainless steel instruments for intraoperative or emergency applications where durability outweighs flexibility. Surgical suites in India and Brazil procure these through regional distributors serving price-sensitive public hospital tenders.
- Digital Gastroscopes:Fully integrated systems with on-board image processing and wireless data transmission. Outpatient surgery centers in Germany and the United States are adopting these for streamlined documentation workflows.
By volume, flexible gastroscopes lead due to legacy fleet replacement cycles. By growth pace, digital gastroscopes are expanding most quickly as ambulatory settings prioritize workflow integration.
End User:
Capital intensity and procedure volume shape facility-level purchasing behavior. High-throughput institutions negotiate enterprise pricing while smaller providers prioritize acquisition cost over feature depth.
- Hospitals:Acute care institutions with dedicated endoscopy suites require multi-scope fleets with 4K imaging and advanced therapeutic channels. Japanese public hospitals and United States academic medical centers dominate capital expenditure, though EU MDR compliance timelines are delaying replacement cycles.
- Outpatient Surgery Centers:Freestanding facilities performing routine diagnostic and screening procedures seek compact, single-procedure systems with rapid turnover capability. Growth in United States Medicare-certified ASCs is accelerating demand for wireless-enabled platforms.
- Clinics:Physician office laboratories and community gastroenterology practices prioritize cost-efficient flexible scopes for symptomatic patient evaluation. Indian urban diagnostic chains are expanding clinic-based endoscopy capacity.
- Diagnostic Centers:Specialized imaging facilities focused on cancer screening and surveillance programs. German statutory health insurance reimbursement expansions are driving investment in high-definition video systems.
Hospitals account for the largest installed base. Outpatient surgery centers are gaining share fastest as procedure migration accelerates.
Technology:
Margin concentration follows imaging sophistication. Basic optical systems face commoditization pressure while integrated digital platforms capture recurring software and service revenue.
- Digital Imaging:CMOS and CCD sensor arrays with 4K resolution and enhanced light sensitivity enable detection of subtle mucosal changes. Premium installations in Japan and the United States are standardizing on these platforms for early neoplasia programs.
- Wireless Technology:Bluetooth and proprietary radio protocols eliminate tethered connections between scope and processor. Ambulatory facilities in Germany value cable-free operation for rapid room turnover and infection control.
- Optical Imaging:Legacy fiber-optic bundles transmitting images through eyepiece or basic camera attachment. Budget-constrained public systems in emerging markets continue procurement where digital upgrade costs are prohibitive.
- Video Recording:Integrated capture and storage systems for documentation compliance and quality assurance. United States hospital systems require these capabilities for malpractice defense and accreditation standards.
Digital imaging commands the highest average selling prices. Wireless technology is climbing the fastest as outpatient migration demands workflow efficiency.
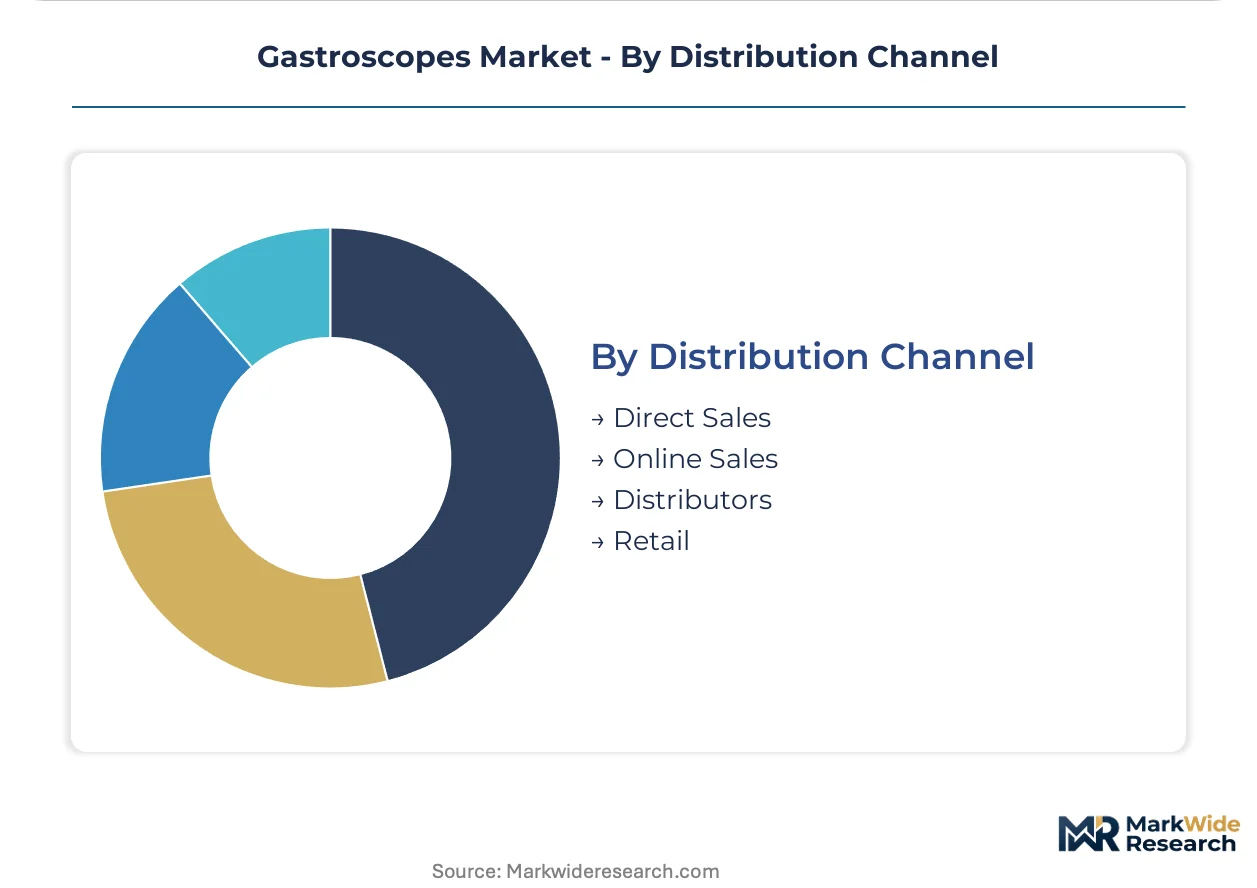
Distribution Channel:
Channel selection reflects transaction scale and technical support requirements. Direct relationships dominate complex system sales while distributors serve fragmented geographic markets.
- Direct Sales:Manufacturer field representatives negotiate enterprise contracts with integrated delivery networks and national hospital chains. United States and Japanese procurement offices favor direct relationships for fleet standardization and training coordination.
- Distributors:Regional medical device wholesalers with technical service capabilities serve mid-tier hospitals and independent clinics. Indian and Brazilian markets rely heavily on distributor networks for geographic coverage and local regulatory navigation.
- Online Sales:E-procurement platforms and manufacturer direct-to-customer portals for consumables and replacement components. Smaller German clinics are experimenting with online channels for standardized accessory purchasing.
- Retail:Limited to basic endoscopy accessories and training models through medical supply storefronts. Minimal scope sales occur through this channel due to capital equipment classification and service requirements.
Direct sales generate the highest revenue per transaction. Distributor channels are expanding fastest in emerging markets where manufacturer presence remains limited.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German procurement offices where aging demographics sustain premium imaging investments, while Indian public hospital systems face budget compression that limits digital platform adoption.
United States
Medicare-certified ambulatory surgery centers drive demand for wireless-enabled gastroscopes as outpatient procedure volumes migrate from inpatient settings. FDA 510(k) predicate pathways accelerate clearance timelines for digital imaging upgrades. Integrated delivery networks in Texas and California negotiate enterprise fleet contracts that standardize training protocols across multi-hospital systems.
Japan
Patients over 65 sustain high-volume gastric cancer screening programs that require high-definition video platforms. PMDA regulatory frameworks align with international standards while maintaining distinct domestic quality benchmarks. Tokyo and Osaka metropolitan hospital clusters anchor capital expenditure for 4K imaging sensor arrays in tertiary care facilities.
Germany
Statutory health insurance reimbursement expansions for outpatient endoscopy procedure codes enable investment in advanced imaging modalities. EU MDR technical documentation requirements extend certification timelines for reusable device revalidation. Bavarian and North Rhine-Westphalian hospital procurement offices now mandate MDR-compliant documentation as a tender participation gate.
India
Government hospital modernization programs and private diagnostic chain rollouts create demand for mid-tier video systems. CDSCO regulatory pathways for imported medical devices require local clinical trial data for novel imaging platforms. Maharashtra and Karnataka urban centers concentrate diagnostic infrastructure expansion as private equity funds regional clinic networks.
China
Domestic manufacturers capture public hospital procurement through cost-competitive digital imaging platforms. NMPA regulatory harmonization with international standards accelerates approval timelines for locally developed sensor technologies. Yangtze River Delta manufacturing clusters supply precision optical components to both domestic and export markets.
Gastroscopes Market Vendor Landscape
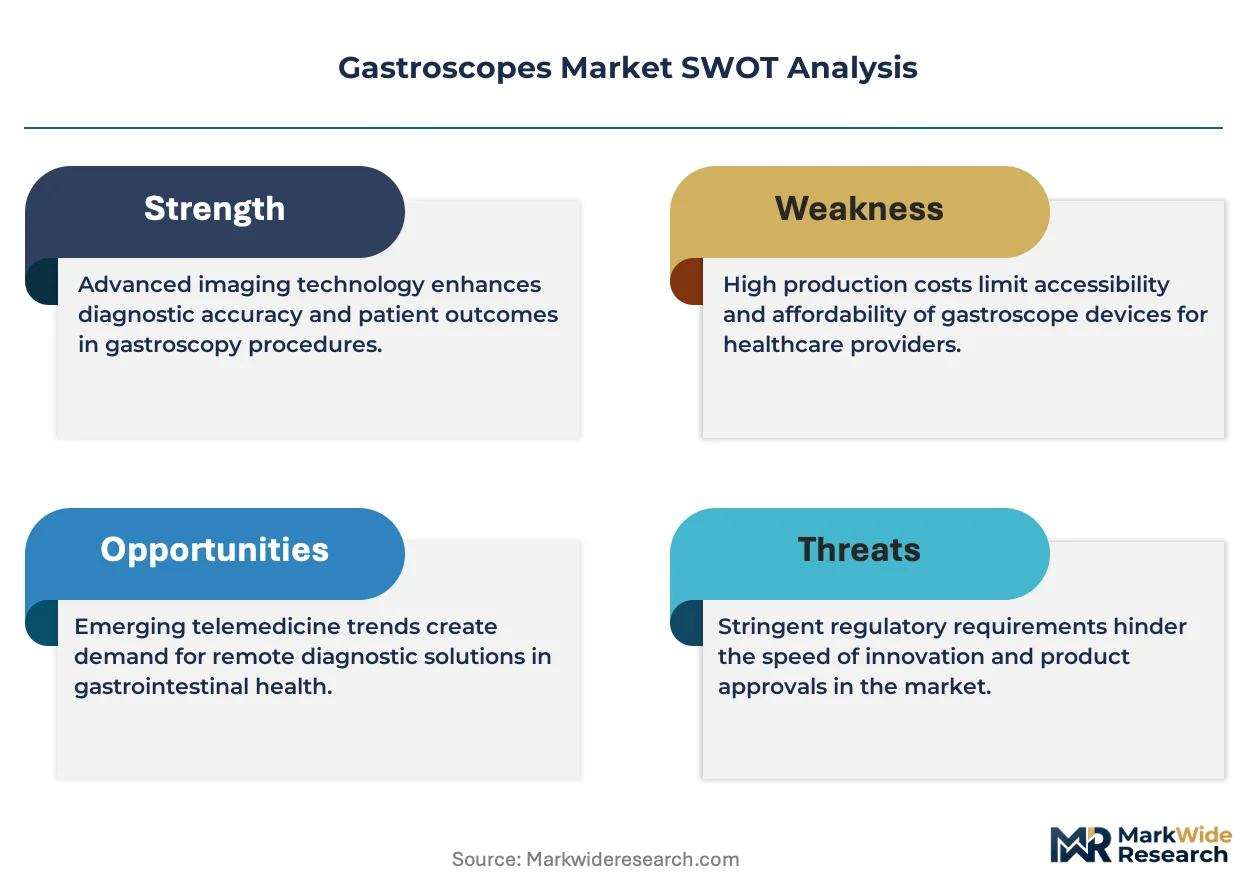
Concentration sits with diversified medical technology conglomerates that leverage captive optical component supply and established notified body relationships. The vendor base stratifies across three tiers: integrated imaging platform providers, specialized endoscope mechanics fabricators, and emerging wireless technology developers. Strategic moves center on unbundling after-sales service contracts from capital equipment purchases and deepening software integration to capture recurring revenue streams.
Among Japan-based diversified conglomerates, Olympus Corporation and Fujifilm Holdings Corporation exemplify the integrated imaging platform archetype through in-house optical manufacturing and digital sensor development capabilities. Karl Storz SE & Co. KG represents the specialized mechanics fabricator tier with German precision engineering heritage. Boston Scientific Corporation occupies a position within the therapeutic device integration segment, bridging diagnostic imaging with interventional capabilities.
| Leading Market Players |
|---|
| Olympus Corporation |
| Fujifilm Holdings Corporation |
| Karl Storz SE & Co. KG |
| Boston Scientific Corporation |
| Hoya Corporation (Pentax Medical) |
| Medtronic plc |
| Richard Wolf GmbH |
| Stryker Corporation |
| Sonoscape Medical Corp |
| Others |
Supply Flow & Price Mechanics
Long-term service bundling contracts between Japanese and German hospital systems and incumbent manufacturers lock in multi-year scope access while anchoring price visibility against volatile component costs. These arrangements tether procurement offices to predictable maintenance outlays even as CMOS sensor and precision lens markets fluctuate.
Pricing Analysis
Configured-to-order pricing for 4K imaging platforms with integrated AI detection modules commands substantial premiums over standard-definition fiber-optic configurations. Three-tier pricing structure across premium, standard, and economy levels separates Japanese tertiary hospitals seeking full software suites from Indian public systems constrained to basic video recording. Cost compression in mid-tier flexible scopes is intensifying because Chinese domestic manufacturers are capturing price-sensitive procurement with cost-competitive digital platforms. Ambulatory surgery centers in the United States exhibit the highest price sensitivity due to Medicare reimbursement compression, while German statutory insurance frameworks insulate academic medical centers from acute budget pressure.
Supply Chain Analysis
Inventory buffers for CMOS sensors and precision optical glass extend lead times when East Asian manufacturing clusters face logistics disruptions. Component fabrication concentrates in Japan, Germany, and China, where Yangtze River Delta facilities supply sensor arrays to both domestic and export markets. Raw material dependencies rest on rare-earth elements for sensor magnetics, specialized optical glass for lens grinding, and medical-grade polymers for insertion tube sheathing. Single-source vulnerability sits with precision lens grinding equipment manufacturers in southern Germany. Distribution runs through direct manufacturer field teams for enterprise hospital contracts and regional medical device wholesalers serving fragmented clinic networks in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastroscopes market represents high-growth disruption as AI-assisted diagnostics and EU MDR reprocessing mandates simultaneously elevate technology barriers and accelerate single-use alternatives. Regulatory friction and software integration are bifurcating competitive viability between integrated platform providers and component assemblers.
For Market Incumbents: Secure captive supply of CMOS sensor manufacturing to defend margin position against Chinese cost competitors while accelerating FDA 510(k) clearances for wireless-enabled platforms. Lock in multi-year service contracts with United States integrated delivery networks before procurement committees complete unbundling shifts. The threat of disposable scope economics becoming viable for outpatient volumes demands pre-emptive software ecosystem investments. For New Entrants and Emerging Players: Differentiate on AI algorithm integration for real-time polyp detection rather than competing on optical component specifications. Target India's diagnostic chain expansion with mid-tier video systems priced below Japanese premium platforms but above legacy fiber-optic alternatives. Pursue CDSCO regulatory pathways through local clinical trial partnerships to bypass import data requirements for novel imaging technologies. For Investors and Strategic Acquirers: Wireless technology developers with proprietary radio protocols and hospital IT integration capabilities represent the most defensible acquisition targets. Long-term viability hinges on recurring software revenue capture rather than capital equipment sales cyclicality. Watch for Medicare reimbursement code expansions for AI-assisted screening as the inflection signal for autonomous diagnostics market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended certification timelines favor incumbents with established notified body relationships in Germany and France. |
| AI Algorithm Regulatory Submission | FDA 510(k) predicate pathways for real-time detection software accelerate hospital procurement decisions in the United States. |
| Hospital System Partnership | Enterprise fleet standardization contracts with Japanese metropolitan clusters lock out competitor access for replacement cycles. |
| Software Companion Development | Integrated documentation platforms capture recurring service revenues as procurement committees unbundle maintenance contracts. |
| Reimbursement Strategy | German statutory health insurance code expansions for outpatient endoscopy enable premium imaging platform adoption. |
Methodological Framework
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and outpatient surgery center administrators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up installation base modeling and top-down market sizing triangulated volume estimates across flexible, video, rigid, and digital product categories.
Sensitivity analysis tested forecast outputs against alternative regulatory compliance timelines and reimbursement scenario variations across the projection horizon. Segmentation dimensions modeled include product flexibility architecture, imaging technology platform, end-user facility type, and geographic regulatory cluster. CAGRs were derived from fitted trend analysis of historical replacement cycles and projected procedure volume growth. Forecast inputs incorporated aging demographic screening penetration rates and outpatient migration velocity from inpatient settings.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway efficiency or accelerated EU MDR enforcement would require recalibration. Forecasts reflect documented assumptions regarding reimbursement stability and component supply chain continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Esophageal Stents Market
Endoscopy
Colonic Stents Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Global Colonoscopes Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Endoscopy Device Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Canada Endoscopy Devices Market