
 Global Endoscopy Ultrasound Market | 2026-2036
Global Endoscopy Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscopy Ultrasound Market Foresight
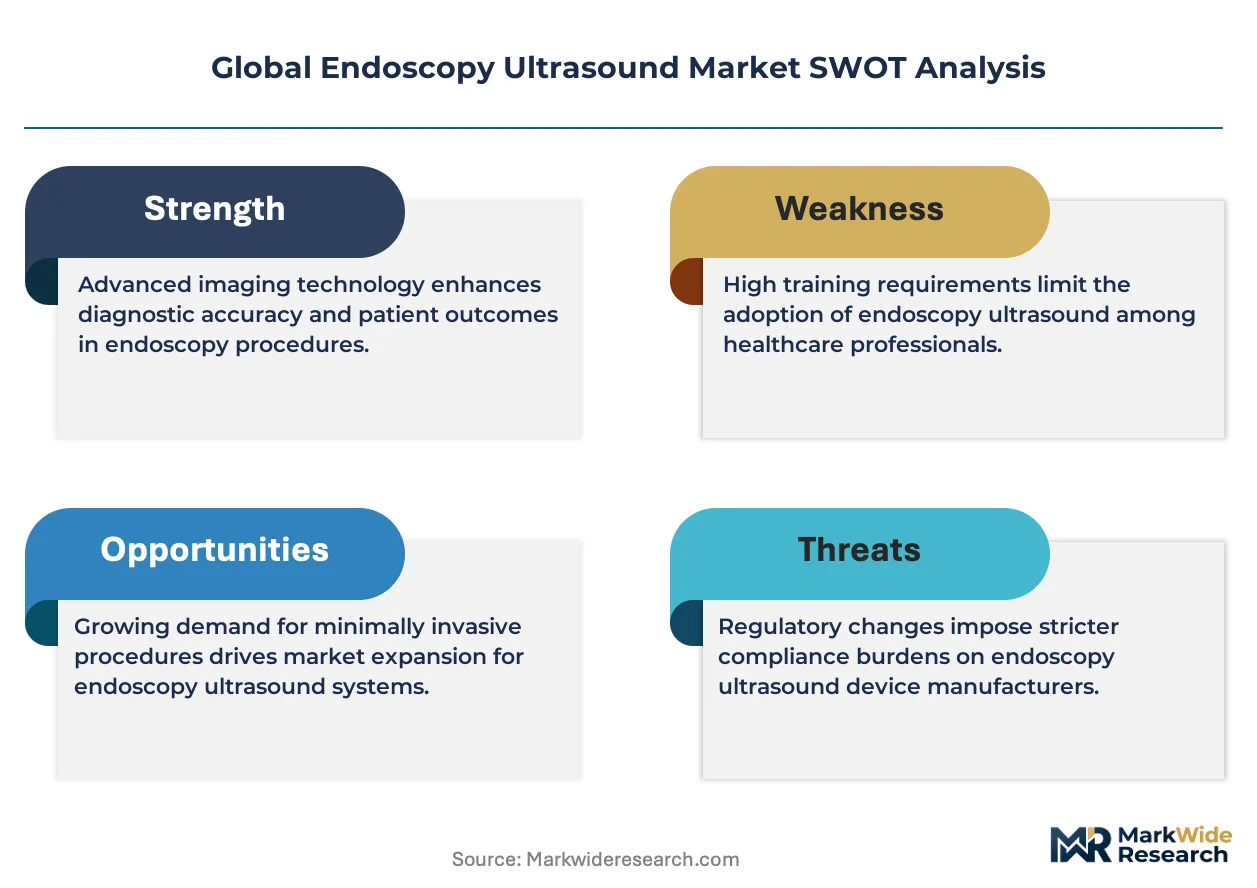
A shift from single-source to multi-source component procurement is expanding among endoscopy ultrasound manufacturers seeking supply chain resilience. Olympus Corporation leverages in-house transducer fabrication to control core imaging performance. Medtronic anchors its position through deep integration of needle aspiration devices with console platforms. FUJIFILM Holdings Corporation differentiates via advanced image processing algorithms embedded in its electronic scanning architectures.
Endoscopy ultrasound combines endoscopic visualization with high-frequency ultrasonic imaging through transducers mounted on flexible endoscope tips, typically operating at frequencies between 5 and 20 megahertz for tissue layer differentiation and submucosal lesion characterization. The primary purpose is to enable real-time diagnostic and therapeutic interventions within the gastrointestinal tract and adjacent organs without external incision. Linear scanning systems command the strongest margin pools due to their dominance in interventional procedures requiring needle guidance. Hospitals absorb the largest share of deployment value, though ambulatory surgery centers represent the fastest-growing end-user channel as same-day procedures expand. Console-based systems remain the revenue backbone, while portable configurations are gaining traction in outreach and emergency settings.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for market access across major jurisdictions. ISO 13485 quality management standards and IEC 60601 electrical safety specifications govern manufacturing compliance for devices sold in the United States, Europe, and Japan. Stakeholders must monitor evolving reimbursement codes for endoscopic ultrasound-guided procedures, as coverage decisions directly influence hospital capital allocation and system replacement cycles.
Market Dynamics
The FDA's updated guidance on reusable endoscope reprocessing is compressing product development cycles and forcing capital redeployment toward automated sterilization-compatible architectures across the installed base.
Growth Catalysts
- Fine-Needle Aspiration Expansion:Gastroenterology departments in tertiary hospitals are scaling linear scanning systems for tissue sampling procedures. This procedural pull sustains replacement demand for console platforms.
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements are accelerating consolidation among manufacturers with robust quality management systems. Compliant suppliers capture shelf space from lagging competitors.
- Ambulatory Surgery Center Channel:Same-day procedure expansion is driving portable configuration demand. These facilities prioritize footprint reduction and rapid room turnover over premium imaging specifications.
Market Restraints
- Transducer Supply Concentration:Piezoelectric crystal fabrication for high-frequency arrays concentrates in Japanese and German specialty suppliers. Disruption risks elevate working capital requirements for second-source qualification.
- Reprocessing Compliance Burden:The FDA's sterilization validation protocols extend validation timelines for reusable device submissions. Small manufacturers lack capital to absorb these fixed regulatory costs.
- Optical Coherence Tomography Substitution:OCT systems for superficial mucosal assessment offer comparable resolution without aspiration capability. Gastroenterology practices in cost-constrained environments substitute where interventional features remain unused.
Strategic Opportunities
- India Diagnostic Infrastructure:The country's national cancer screening program is expanding endoscopic capacity in tier-2 cities. CDSCO streamlined pathways for Class B device registration reduce market entry friction.
- Artificial Intelligence Integration:Real-time lesion classification algorithms are converging with electronic scanning architectures. Embedded AI differentiates premium tier offerings and supports procedure standardization.
- Leasing and Managed Service Models:Hospital capital budget constraints are shifting procurement toward utilization-based contracts. Equipment vendors capture recurring revenue streams while lowering customer acquisition barriers.
Industry Challenges
- Interventional Sonographer Training Pipeline:Fine-needle aspiration competence requires supervised case volume accumulation. Academic medical centers struggle to expand fellowship slots proportionally to device deployment growth.
- Legacy Console Integration Complexity:Hospital information system connectivity standards vary across vendor generations. Middleware development consumes engineering resources that would otherwise advance imaging performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscopy Ultrasound Market |
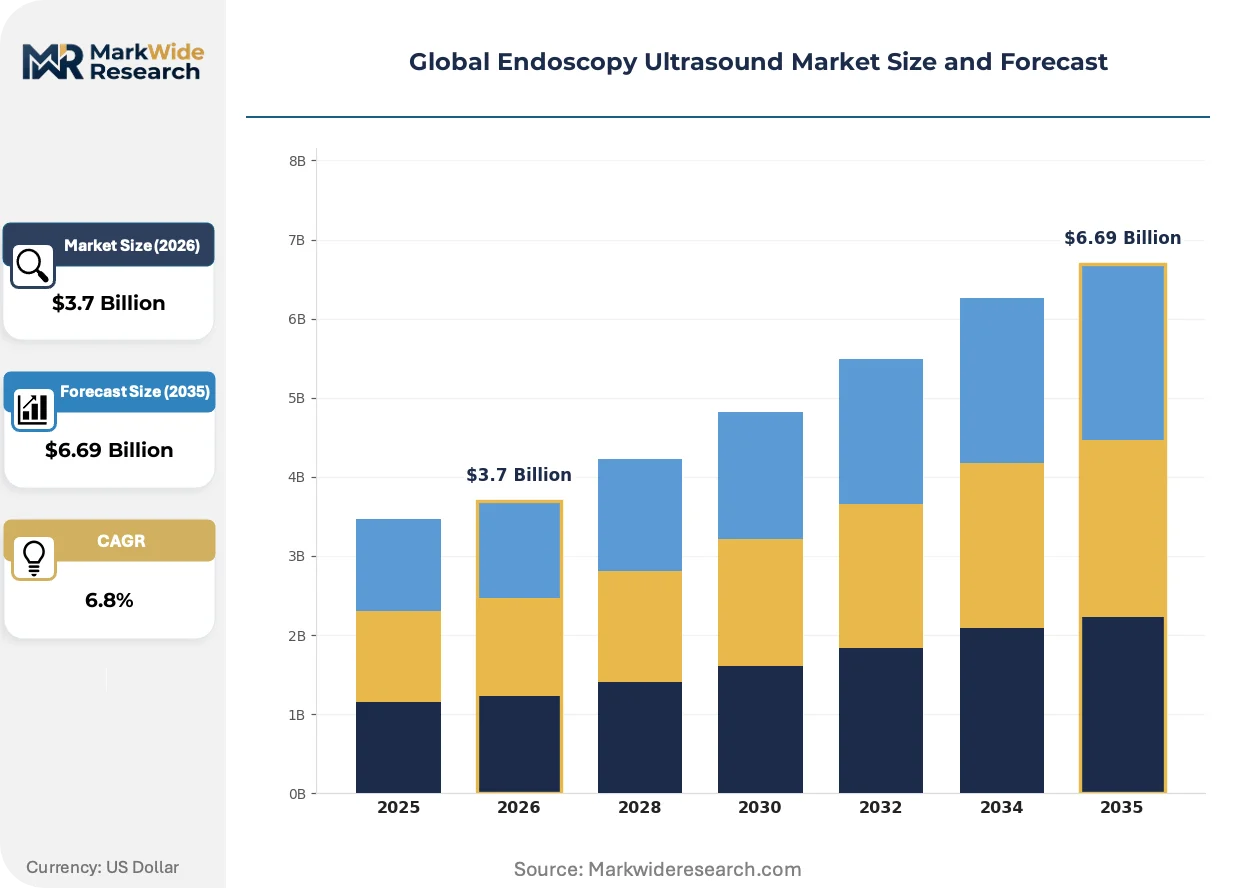
| Market Size in 2026 | $3.7 Billion |
| Market Size in 2035 | $6.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Scanning, Linear Scanning, Miniprobes, Convex Array, Electronic Scanning Application: Gastroenterology, Pulmonology, Urology, Gynecology, Thoracic Surgery End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Imaging Centers, Specialty Clinics, Academic Institutes Deployment: Portable Systems, Console-Based Systems, Integrated Systems, Cart-Based Systems, Handheld Devices |
| Companies Covered | Olympus Corporation, Medtronic, FUJIFILM Holdings Corporation, Boston Scientific Corporation, Pentax Medical, Conmed Corporation, Cook Medical, SonoScape Medical Corporation, Steris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscopy Ultrasound Market Shifts & Advancements
Electronic scanning architectures are displacing mechanical radial systems across diagnostic applications, while regulatory pressure on reprocessing safety compresses design cycles for sterilization-compatible transducer housings.
Single-use transducer sheaths with integrated balloon inflation channels are converging with high-frequency linear arrays. Community hospital systems in the United States are adopting these disposable interfaces to eliminate reprocessing liability and reduce turnover time between cases. This convergence is compressing the addressable market for capital-intensive automated sterilization equipment.
Japan's PMDA has tightened post-market surveillance requirements for reusable endoscopic accessories following adverse event clustering reports. Manufacturers must now submit periodic safety update reports with real-world performance data. Console-based system vendors with established Japanese subsidiaries are absorbing compliance costs more readily than entrants dependent on distributor relationships.
Hospital procurement committees are unbundling service contracts from capital equipment purchases and negotiating direct maintenance agreements with third-party technical service organizations. This disintermediation is most pronounced in Germany, where hospital purchasing cooperatives aggregate bargaining power across multi-site networks. Original equipment manufacturers are responding with certified partner programs that preserve brand control while conceding margin on aftermarket services.
Global Endoscopy Ultrasound Market Segmentation
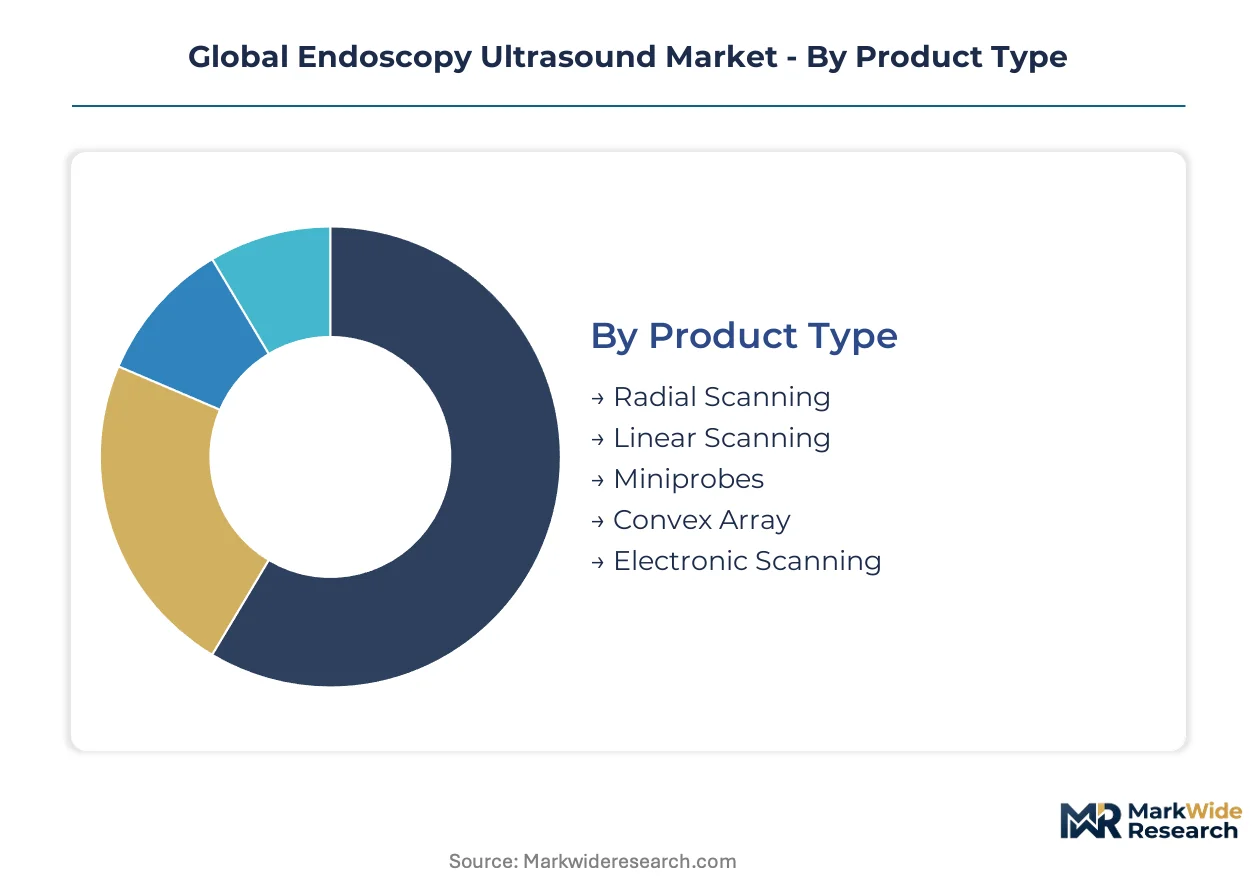
Endoscopy ultrasound manufacturers calibrate product portfolios across four intersecting dimensions: imaging architecture, clinical specialty, facility infrastructure, and mobility requirements. Each segmentation axis carries distinct regulatory pathways and capital intensity profiles that shape vendor go-to-market strategies.
Product Type:
FDA 510(k) clearance timelines stretch longest for electronic scanning architectures with embedded software components, while radial scanning systems with established predicates move through premarket notification faster. PMDA in Japan imposes additional electromagnetic compatibility testing on high-frequency linear arrays.
- Linear Scanning:Operating at 5-12 megahertz with parallel crystal arrays, these systems enable real-time needle guidance for fine-needle aspiration. Tertiary hospital gastroenterology departments in the United States and Germany concentrate procurement here, driven by interventional procedure volume and reimbursement coverage for tissue sampling.
- Electronic Scanning:Solid-state beam steering eliminates mechanical rotation, enabling faster frame rates and software-based image optimization. Academic medical centers in Japan and the United States lead adoption, prioritizing research applications and AI integration pathways over cost considerations.
- Radial Scanning:Mechanical 360-degree rotation remains the workhorse for diagnostic mucosal staging in community hospital settings.
- Miniprobes:Ultra-thin catheter-based designs access narrow luminal structures through standard endoscope channels.
- Convex Array:Curved crystal configurations optimize deep tissue penetration for hepatobiliary and pancreatic assessment.
Linear Scanning sits at the top of the volume ranking, with Electronic Scanning climbing the fastest.
Application:
Procedure reimbursement codes vary sharply across specialties, with gastroenterology carrying the most established coverage and thoracic surgery still negotiating category III code recognition.
- Gastroenterology:Esophageal, gastric, and colorectal lesion staging constitutes the procedural backbone. Screening program infrastructure in Japan and Germany sustains high utilization rates, while India's expanding national cancer detection initiative is opening new addressable volume.
- Pulmonology:Endobronchial ultrasound for mediastinal lymph node sampling requires dedicated bronchoscope compatibility. United States academic centers drive adoption here, constrained by interventional pulmonology fellowship capacity limitations.
- Urology:Transrectal applications for prostate and seminal vesicle assessment remain niche outside specialized centers.
- Gynecology:Transvaginal and transrectal approaches for pelvic pathology evaluation see sporadic deployment in European gynecologic oncology units.
- Thoracic Surgery:Preoperative staging and intraoperative localization applications are gaining procedural traction in German and Japanese thoracic surgery departments.
Gastroenterology commands the dominant revenue share, though Pulmonology demonstrates the steepest expansion trajectory.
End User:
Capital allocation authority and reprocessing liability exposure diverge materially across facility types, with hospitals absorbing full sterilization validation burdens that ambulatory surgery centers increasingly evade through disposable interfaces.
- Hospitals:Tertiary and academic medical centers deploy full console platforms with comprehensive service contracts. United States hospital purchasing cooperatives and German hospital networks exercise consolidated bargaining power, compressing equipment margins while expanding aftermarket attachment rates.
- Ambulatory Surgery Centers:Same-day procedure focus prioritizes portable configurations and rapid room turnover. These facilities in the United States are adopting single-use transducer sheaves to eliminate reprocessing overhead and liability exposure.
- Diagnostic Imaging Centers:Standalone facilities concentrate on outpatient diagnostic staging with lower interventional procedure mix.
- Specialty Clinics:Gastroenterology-focused practices in urban United States markets deploy compact systems for office-based procedures.
- Academic Institutes:Research and training missions justify premium electronic scanning platforms with embedded AI and extensive software customization capabilities.
Hospitals retain the largest installed base, with Ambulatory Surgery Centers gaining share fastest.
Deployment:
Footprint constraints and power infrastructure availability shape procurement decisions, with portable systems requiring less electrical safety validation than fixed console installations.
- Console-Based Systems:Fixed installations with dedicated processor units, high-resolution displays, and comprehensive transducer portfolios anchor revenue for major manufacturers. German and Japanese hospitals maintain the densest concentration of premium console deployments.
- Portable Systems:Battery-powered or cart-mounted configurations with reduced transducer compatibility serve outreach and emergency applications. India's tier-2 city diagnostic expansion and United States ambulatory surgery center growth are pulling portable demand.
- Integrated Systems:Direct hospital information system connectivity and PACS integration command premium positioning in academic medical centers.
- Cart-Based Systems:Modular mobility with plug-in processor units offers intermediate flexibility for mid-sized hospitals.
- Handheld Devices:Experimental ultra-compact form factors remain pre-commercial outside research settings.
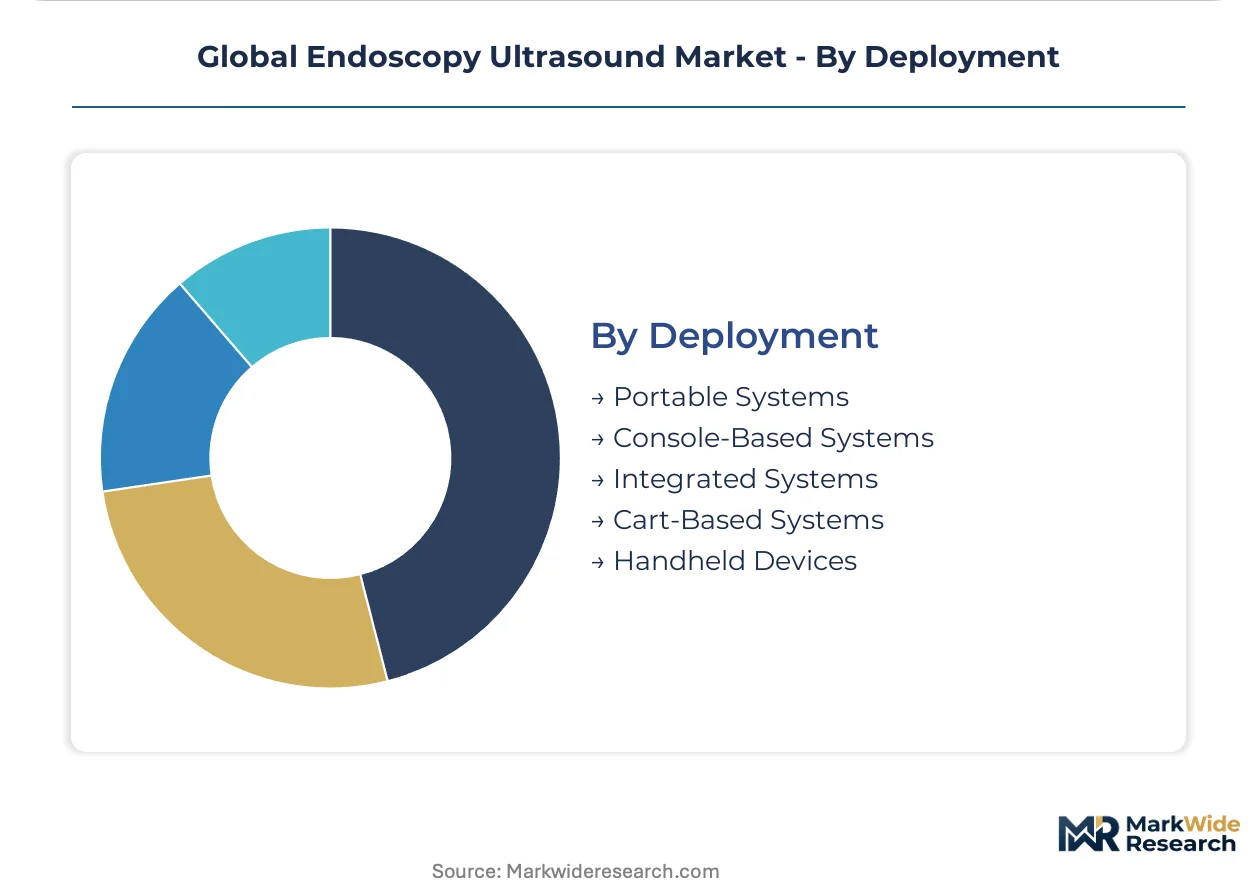
Console-Based Systems dominate current revenue, with Portable Systems expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Kanto industrial corridor anchors endoscopy ultrasound manufacturing concentration, with precision transducer fabrication clusters supplying tertiary hospital networks across Japan, Germany, and the United States.
United States
Gastroenterology departments in academic medical centers drive linear scanning system procurement for fine-needle aspiration procedures. FDA's updated reprocessing guidance compresses product development cycles toward automated sterilization-compatible designs. The Boston-Cambridge corridor concentrates AI-enabled electronic scanning research partnerships.
Germany
Hospital purchasing cooperatives aggregate bargaining power across multi-site networks, compressing equipment margins while expanding aftermarket attachment. EU Medical Device Regulation accelerates consolidation among manufacturers with robust quality management systems. The Baden-Württemberg region hosts precision engineering suppliers serving transducer array fabrication.
Japan
Aging demographics and established cancer screening programs sustain high procedure volumes in tertiary hospitals. PMDA tightened post-market surveillance requirements for reusable endoscopic accessories following adverse event clustering reports. Tokyo-based manufacturers leverage in-house piezoelectric crystal fabrication for high-frequency array production.
India
The national cancer screening program expands endoscopic capacity in tier-2 cities beyond metropolitan centers. CDSCO streamlined pathways for Class B device registration reduce market entry friction for console-based system vendors. Maharashtra and Karnataka states concentrate diagnostic infrastructure deployment.
United Kingdom
NHS procurement frameworks prioritize cost containment in endoscopy suite capital allocation. MHRA alignment with EU MDR transition timelines shapes compliance requirements for market access. London and Southeast England academic centers pilot AI-embedded electronic scanning platforms for lesion classification research.
Global Endoscopy Ultrasound Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue portable configurations and single-use disposable interfaces. The vendor base concentrates among diversified medical technology conglomerates with captive transducer fabrication capabilities and pure-play endoscopy specialists with deep interventional needle integration. Three archetypes dominate: integrated imaging-console manufacturers, component-specialized suppliers, and regional service-focused distributors. Competitive moves center on strategic partnerships for AI algorithm licensing and backward integration into piezoelectric crystal supply.
Within the integrated imaging tier, Olympus Corporation exemplifies the vertically consolidated archetype through captive transducer production. Medtronic occupies a position emphasizing deep needle aspiration device integration with console platforms. FUJIFILM Holdings Corporation anchors the advanced image processing differentiation vector through electronic scanning architectures. These three entities represent distinct strategic postures without implying specific market share claims or operational details beyond their evident corporate structures.
| Leading Market Players |
|---|
| Olympus Corporation |
| Medtronic |
| FUJIFILM Holdings Corporation |
| Boston Scientific Corporation |
| Pentax Medical |
| Conmed Corporation |
| Cook Medical |
| SonoScape Medical Corporation |
| Steris |
| Others |
Supply & Pricing Matrix
Tertiary hospital purchasing cooperatives in Germany and the United States anchor procurement volume, concentrating bargaining power that compresses equipment margins while expanding aftermarket service attachment as the dominant revenue model.
Pricing Analysis
Piezoelectric crystal and precision transducer array costs pass through directly to console system pricing, with Japanese and German specialty suppliers commanding premium positioning. Pricing stratifies across premium electronic scanning platforms, standard linear configurations, and economy radial systems based on imaging resolution tiers and FDA 510(k) predicate complexity. Cost compression in standard-tier consoles intensifies as ambulatory surgery centers prioritize portable configurations over premium specifications. Academic medical centers demonstrate lowest price sensitivity, while community hospitals in cost-constrained environments drive hardest bargain.
Supply Chain Analysis
Direct-to-hospital channels handle tier-one academic medical center demand, while distributor networks serve mid-tier hospital systems and ambulatory facilities. Precision transducer fabrication concentrates in Japan, Germany, and the United States, with piezoelectric crystal production, high-frequency array assembly, and sterilization-compatible housing manufacturing as critical inputs. Single-source vulnerability in Japanese specialty crystal suppliers elevates working capital requirements for second-source qualification. Distribution runs through certified service partner programs that preserve OEM brand control while conceding margin on technical maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable transducer sheath adoption is shifting margin pools from capital equipment toward consumable recurring revenue, creating expansion opportunity for vendors with captive manufacturing of single-use interfaces.
For Market Incumbents: Acquire captive piezoelectric crystal fabrication capacity to secure transducer supply continuity against Japanese supplier concentration risk. Consolidate position through backward integration into high-frequency array production, while embedding AI classification algorithms as software lock-in against emerging portable competitors.
For New Entrants and Emerging Players: Single-use disposable transducer interfaces represent the most penetrable wedge for capital-light market entry. Target United States ambulatory surgery centers with sterilization-liability elimination as primary value proposition, partnering with third-party technical service organizations to bypass OEM-certified maintenance networks.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates with existing endoscopy portfolios are the most active acquirer in this space, seeking needle aspiration device integration capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure for FDA sterilization validation and EU MDR quality management. Watch for CDSCO registration acceleration in India as inflection signal for emerging market volume shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Fabrication | Olympus Corporation secures piezoelectric crystal supply continuity against Japanese supplier concentration. |
| AI Algorithm Licensing Partnership | FUJIFILM Holdings Corporation embeds real-time lesion classification to differentiate electronic scanning platforms. |
| Disposable Transducer Sheath Launch | Single-use interfaces eliminate reprocessing liability for United States ambulatory surgery centers. |
| CDSCO Registration Pathway Execution | Streamlined Class B device access opens tier-2 city diagnostic infrastructure in Maharashtra and Karnataka. |
| Managed Service Contract Expansion | Utilization-based leasing lowers hospital capital acquisition barriers while capturing recurring revenue streams. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, gastroenterology department heads, and GPO contracts managers grounded qualitative findings, cross-referenced against FDA 510(k) filings, PMDA adverse event reports, hospital procurement databases, and EU MDR technical documentation. Secondary validation drew from CMS Medicare reimbursement data, Japanese Ministry of Health screening program statistics, and German hospital network purchasing cooperative disclosures. Bottom-up procedure volume estimates and top-down equipment replacement cycle analysis were triangulated to anchor market sizing.
Segment-level outputs across product architecture, clinical application, facility type, and mobility configuration were generated through the projection horizon. CAGRs were derived from fitted adoption curves incorporating reimbursement code expansion trajectories, interventional fellowship training pipeline capacity, and single-use disposable penetration assumptions. Forecast inputs included PMDA post-market surveillance tightening timelines and CDSCO registration pathway efficiency metrics.
The model holds under stable regulatory compliance cost assumptions; deviation in FDA sterilization validation protocol stringency or EU MDR enforcement intensity would shift equipment replacement cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
AI in Endoscopy Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Endoscopic Mucosal Resection Market