

Endoscopic Probe Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Probe Disinfection Market Insights
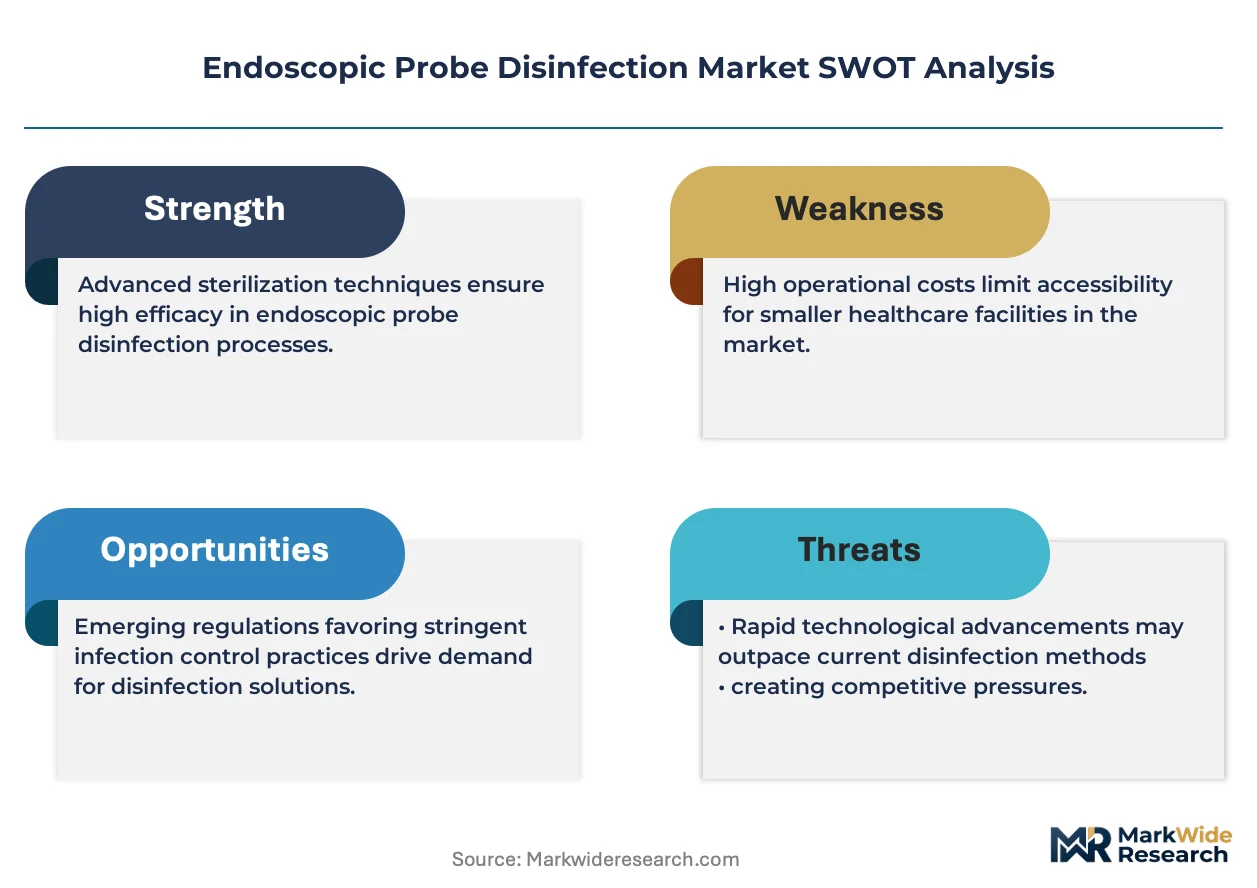
Peracetic acid is broadening its role as a replacement for glutaraldehyde in automated endoscope reprocessing, cutting cycle times and reducing ventilation burdens in sterile processing departments. STERIS leverages its installed base of automated endoscope processors to sustain recurring revenue from proprietary chemistries. Olympus Corporation anchors its disinfection portfolio through integrated washer-disinfectors tied to its endoscope ecosystem. Nanosonics competes via trophon technology specialized in ultrasound probe high-level disinfection, extending its clinical validation into endoscopic applications.
Endoscopic probe disinfection encompasses the chemical, thermal, and mechanical processes used to eliminate microbial contamination from flexible and rigid endoscopes between patient procedures, typically requiring exposure to high-level disinfectants at specific temperature and concentration parameters validated against mycobactericidal kill standards. The primary purpose is preventing healthcare-associated infections transmitted through inadequately reprocessed lumened instruments. Automated disinfectors command the largest share of product-type revenue due to capital-intensive hospital procurement cycles and liability-driven preference for validated, traceable reprocessing workflows. High-level disinfection dominates the method landscape because flexible gastrointestinal and bronchoscopes cannot withstand sterilization temperatures, though sterilization segments are gaining traction in urology and ENT where rigid instruments predominate.
FDA reprocessing guidance, EPA antimicrobial pesticide registration requirements, and MDR technical documentation obligations in Europe collectively shape product design, validation burden, and market access timelines for disinfection system manufacturers. The EPA's emerging scrutiny on peracetic acid emissions and the EU's F-Gas Regulation restricting certain sterilizing gases are forcing chemistry suppliers to reformulate and revalidate core disinfectant platforms. Stakeholders must monitor regulatory divergence between US and European validation protocols to avoid duplicative clinical testing costs and supply chain fragmentation.
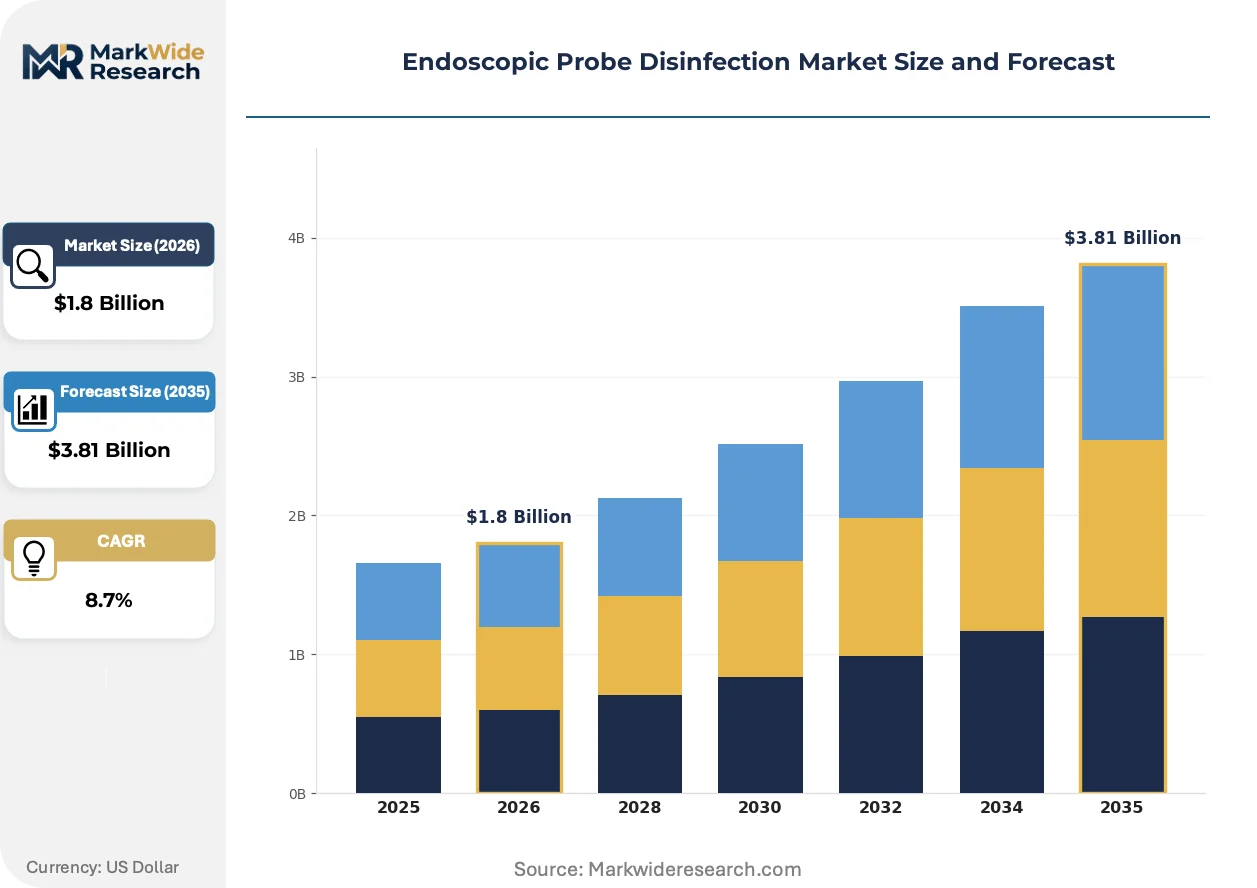
Market Dynamics
The FDA's updated reprocessing guidance for flexible endoscopes is compressing hospital procurement cycles toward validated automated systems, forcing capital allocation toward traceable high-level disinfection workflows and away from manual reprocessing stations.
Growth Catalysts
- MDR compliance deadlines:European facilities face mandatory technical documentation obligations for disinfection equipment, accelerating replacement of non-validated legacy systems in Germany and France.
- Ambulatory surgical center expansion:Outpatient facilities in the United States are installing compact automated disinfectors to manage rising endoscopy volumes without expanding sterile processing footprint.
- Peracetic acid chemistry advances:Reformulated low-temperature disinfectants are cutting cycle times below glutaraldehyde baselines while maintaining mycobactericidal efficacy.
Market Restraints
- EPA emission scrutiny:The Environmental Protection Agency's emerging peracetic acid ventilation requirements are forcing chemistry suppliers into costly reformulation and revalidation cycles.
- Capital intensity barriers:Automated endoscope processors require six-figure capital commitments that constrain independent ambulatory centers and rural hospital systems.
- EU F-Gas restrictions:The F-Gas Regulation is phasing out certain sterilizing gases used in rigid endoscope processing, eliminating established chemistry platforms without immediate substitutes.
Strategic Opportunities
- Ultrasound probe crossover:Trophon-style hydrogen peroxide mist systems validated for transesophageal echocardiogram probes are expanding into gastrointestinal endoscope niches.
- India outpatient growth:Private hospital chains in Mumbai and Delhi are building centralized reprocessing facilities to serve satellite clinics with shared automated infrastructure.
- CSRD traceability mandates:The EU Corporate Sustainability Reporting Directive is creating procurement preference for disinfectors with embedded cycle documentation and cloud-based audit trails.
Industry Challenges
- Sterile processing technician shortages:Hospital systems struggle to staff departments capable of operating complex automated disinfectors and interpreting chemical indicator failures.
- Legacy scope incompatibility:Older flexible endoscopes from non-integrated manufacturers lack RFID recognition required by newer washer-disinfector generations, forcing parallel manual workflows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Probe Disinfection Market Trends and Innovations
Reprocessing chemistry, equipment connectivity, and procurement accountability are converging to reshape how facilities validate and document disinfection outcomes across increasingly regulated environments.
Electrolyzed water systems are expanding into automated endoscope reprocessing as a cold sterilant alternative to peracetic acid and glutaraldehyde. Veterans Affairs hospitals in the United States are piloting these systems to eliminate chemical storage hazards and ventilation infrastructure costs. The technology is expanding into mid-tier community hospitals seeking to bypass chemistry supply chain dependencies entirely.
The EPA's antimicrobial pesticide registration requirements are tightening efficacy validation protocols for high-level disinfectants used in lumened instruments. Chemistry suppliers must now submit expanded mycobactericidal kill data and environmental fate studies before label approval. European manufacturers are responding by front-loading clinical testing budgets to maintain parallel US market access.
Hospital procurement departments are consolidating vendor relationships around single-source reprocessing ecosystems that bundle disinfectors, chemistry, and scope maintenance contracts. This consolidation displaces independent chemistry suppliers and third-party service providers. The pattern is most pronounced in integrated delivery networks across Texas and California seeking standardized protocols across multiple facilities.
Endoscopic Probe Disinfection Market Segmentation
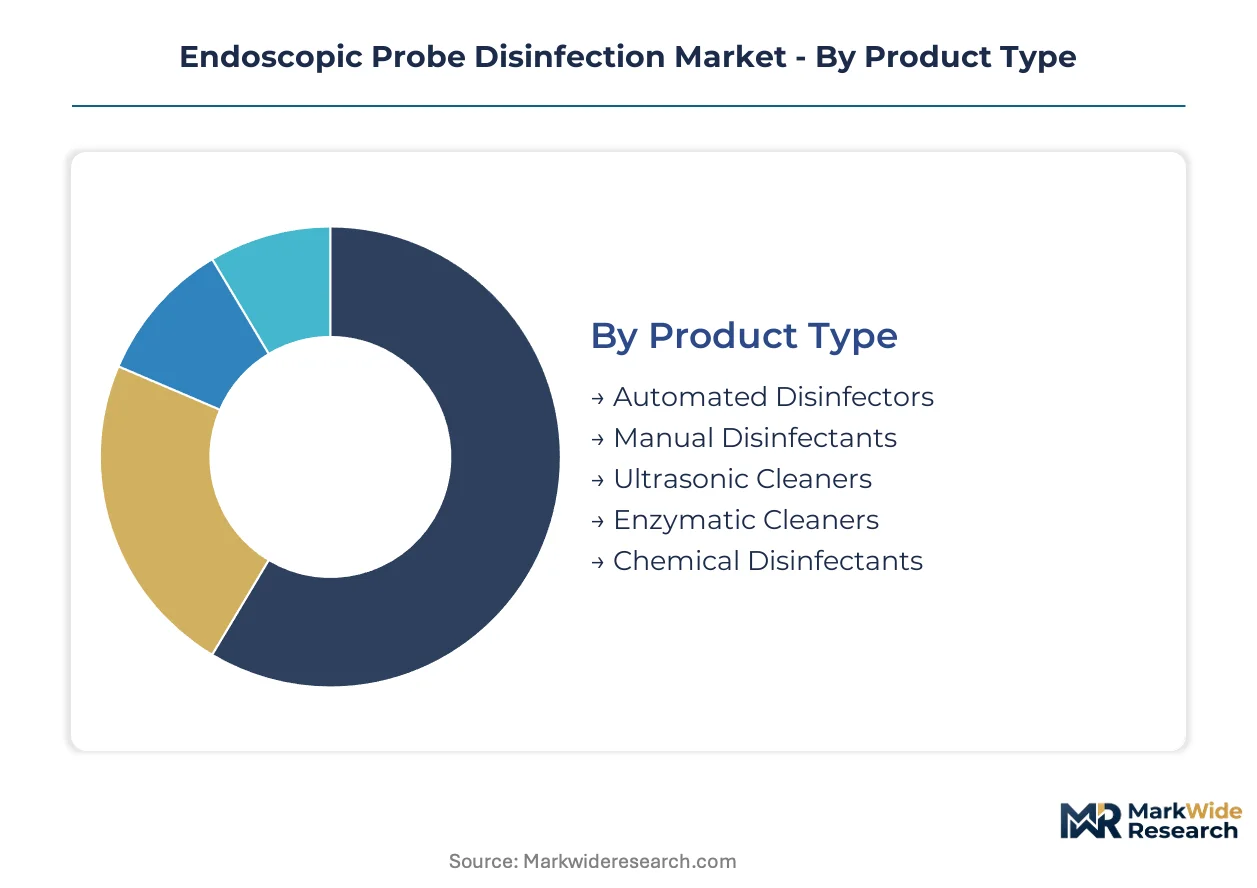
Segmentation in endoscopic probe disinfection reveals how capital intensity, clinical risk tolerance, and regulatory validation requirements fragment procurement patterns across facility types. Equipment manufacturers calibrate product portfolios against these divergent customer economics rather than pursuing uniform market penetration.
Product Type:
Volume concentration clusters around capital-intensive automated systems purchased by hospitals with dedicated sterile processing departments, while manual chemistries serve price-sensitive outpatient settings lacking infrastructure investment capacity.
- Automated Disinfectors:Washer-disinfector systems integrate mechanical cleaning, high-level disinfection, and drying cycles with automated chemical dosing and digital cycle documentation. Demand concentrates in Germany's university hospitals where MDR technical documentation mandates validate traceable reprocessing workflows against liability exposure.
- Manual Disinfectants:Pre-mixed or concentrate chemistries requiring immersion basins and manual brushing of lumened channels. Procurement in India's private clinic chains emphasizes cost-per-cycle minimization over capital expenditure, though technician training burdens limit adoption in high-throughput settings.
- Ultrasonic Cleaners:Cavitation-based pre-cleaning units for heavily soiled rigid endoscopes. Adoption clusters in urology suites processing resectoscopes and cystoscopes.
- Enzymatic Cleaners:Protease-lipase-amylase formulations for organic soil dissolution prior to disinfection. Standard pre-treatment in gastrointestinal endoscopy reprocessing protocols.
- Chemical Disinfectants:Peracetic acid, glutaraldehyde, and ortho-phthalaldehyde concentrates for manual or automated application. EPA registration status drives formulary decisions in US facilities.
Mature deployment sits with Automated Disinfectors. Newer deployment is concentrated in Manual Disinfectants serving expanding ambulatory networks.
Disinfection Method:
Clinical application dictates method selection, with thermal sensitivity of flexible endoscopes preserving chemical high-level disinfection as the dominant protocol despite sterilization's superior lethality assurance.
- High-Level Disinfection:Liquid chemical or vapor-phase processes eliminating all microbial life except high numbers of bacterial spores. Gastroenterology and pulmonology departments in US hospitals deploy automated peracetic acid systems to comply with FDA's updated flexible endoscope reprocessing guidance.
- Sterilization:Steam, ethylene oxide, or hydrogen peroxide plasma achieving sporicidal kill. Urology and ENT procedures utilizing rigid endoscopes drive adoption where instrument materials tolerate thermal or oxidative stress.
- Low-Level Disinfection:Intermediate-level germicidal activity for non-critical device surfaces. Environmental disinfection applications predominate over direct endoscope contact.
- Pasteurization:Hot water disinfection at sub-boiling temperatures for heat-tolerant instruments. Limited to specific rigid endoscope categories in European settings.
- Chemical Soaking:Extended immersion in high-level disinfectants without mechanical action. Declining utilization due to reprocessing time inefficiency and ventilation requirements.
High-Level Disinfection anchors current clinical practice. Sterilization protocols are climbing the fastest as materials science expands heat-tolerant instrument availability.
End User:
Facility scale and case volume determine whether procurement favors capital equipment with lifecycle service contracts or consumable-centric operating expense models.
- Ambulatory Surgical Centers:High-throughput outpatient facilities performing screening colonoscopy and diagnostic bronchoscopy. Texas and California integrated delivery networks install compact automated disinfectors to standardize protocols across multi-site operations without expanding sterile processing footprint.
- Diagnostic Laboratories:Pathology and microbiology settings utilizing endoscopes for specimen collection. Lower utilization rates favor manual reprocessing or third-party sterilization services.
- Specialized Clinics:Single-specialty gastroenterology or urology practices. India's Mumbai and Delhi private chains are building centralized reprocessing facilities to serve satellite clinics with shared automated infrastructure.
- Research Facilities:Academic medical centers with experimental endoscope protocols. Custom validation requirements complicate standard equipment procurement.
- Outpatient Care Units:Hospital-affiliated non-admitted patient services. Intermediate case volumes drive leasing arrangements for automated equipment.
Established procurement patterns characterize Ambulatory Surgical Centers. Specialized Clinics represent the steepest expansion trajectory as healthcare decentralization accelerates.
Application Area:
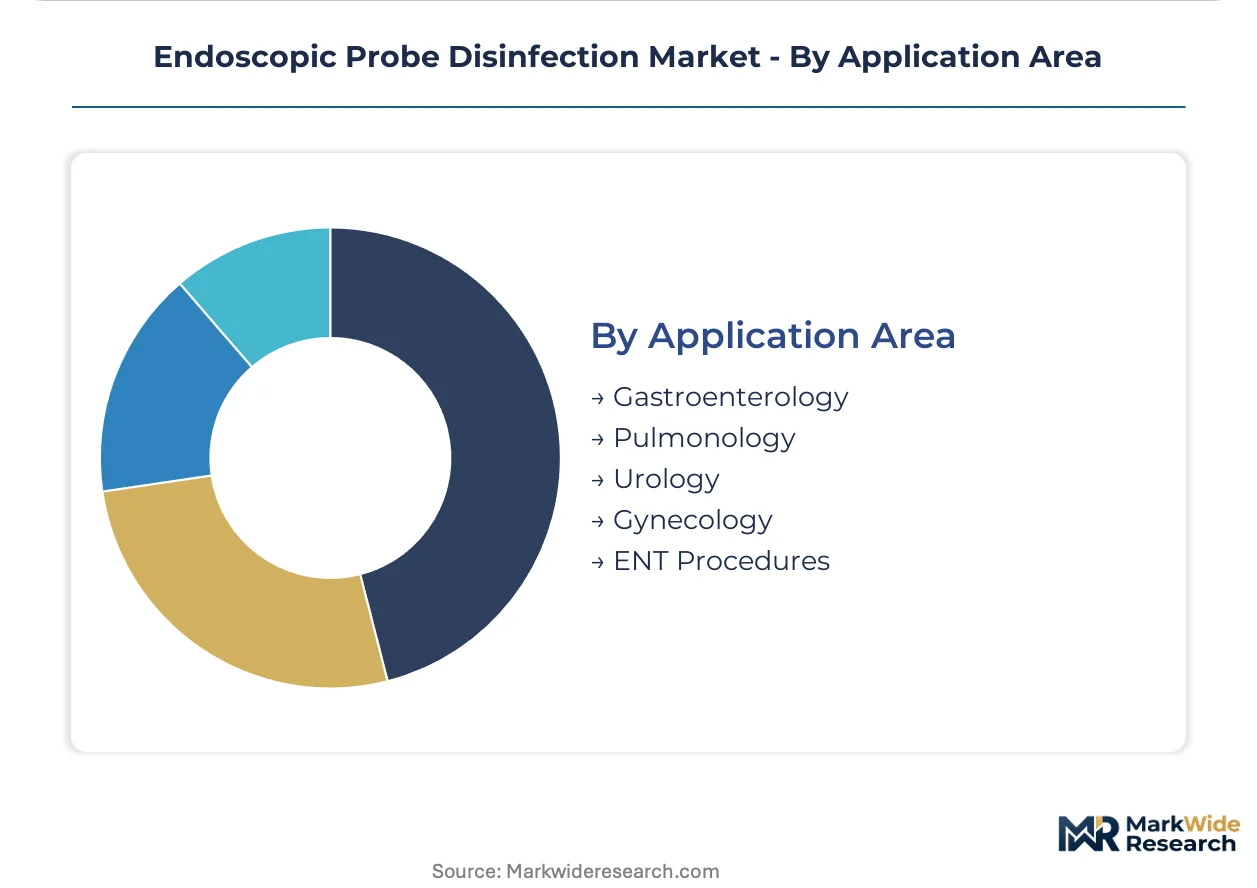
Procedure volume and infection consequence severity shape reprocessing rigor requirements, with gastrointestinal applications commanding the most stringent validation protocols due to bioburden exposure.
- Gastroenterology:Colonoscopy and upper endoscopy procedures involving high organic soil loads and mucosal contact. Automated high-level disinfection with peracetic acid dominates due to FDA guidance emphasizing validated, traceable workflows for flexible gastrointestinal endoscopes.
- Pulmonology:Bronchoscopy with lower bioburden but critical airway exposure. US Veterans Affairs hospitals pilot electrolyzed water systems to eliminate chemical storage hazards while maintaining mycobactericidal efficacy against tuberculosis transmission risks.
- Urology:Cystoscopy and resectoscopy utilizing rigid instruments. Steam sterilization compatibility permits higher lethality protocols than flexible endoscope applications.
- Gynecology:Hysteroscopy and laparoscopy with intermediate instrument complexity. Mixed rigid-flexible instrument portfolios complicate standardized reprocessing.
- ENT Procedures:Rigid rhinolaryngoscopy with sterilization-tolerant instruments. Smaller instrument diameter enables faster sterilization cycle completion.
Gastroenterology maintains the deepest installed base of validated automated systems. Pulmonology is gaining share fastest as bronchoscopy volumes expand and respiratory pathogen concerns intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endoscopic probe disinfection equipment concentrates in Germany, the United States, and India, where regulatory enforcement and procedural volume create procurement pull for validated automated systems.
Germany
University hospitals in Berlin and Munich drive replacement of legacy manual reprocessing stations with MDR-compliant automated washer-disinfectors. The EU Medical Device Regulation mandates technical documentation for all disinfection equipment, accelerating capital procurement cycles. Bavaria's medical technology cluster around Erlangen hosts multiple sterilization equipment manufacturers expanding production capacity for export markets.
United States
Veterans Affairs hospitals pilot electrolyzed water systems to eliminate chemical storage hazards while maintaining mycobactericidal efficacy. FDA's updated reprocessing guidance for flexible endoscopes compresses hospital procurement toward validated automated workflows. Texas integrated delivery networks standardize protocols across multi-site ambulatory surgical center operations with compact automated disinfector deployments.
India
Private hospital chains in Mumbai and Delhi build centralized reprocessing facilities to serve satellite gastroenterology clinics with shared automated infrastructure. The country's national pharmaceutical regulator enforces CDSCO medical device registration requirements for imported disinfection equipment. Karnataka's Bangalore medical device corridor attracts contract manufacturers assembling compact disinfectors for domestic outpatient networks.
Japan
Metropolitan Tokyo hospitals deploy hydrogen peroxide plasma systems for rigid endoscope sterilization in high-volume urology suites. PMDA pharmaceutical and medical device agency reviews require extended clinical validation timelines for novel disinfectant chemistries. Osaka's Kansai medical manufacturing belt supplies automated endoscope processors to Southeast Asian export markets.
United Kingdom
NHS trusts in London and Manchester consolidate vendor relationships around single-source reprocessing ecosystems bundling equipment and chemistry contracts. MHRA post-Brexit regulatory divergence from EU MDR creates parallel validation requirements for disinfection system suppliers. Cambridge's medical technology research cluster develops novel peracetic acid formulations with reduced ventilation burdens.
Endoscopic Probe Disinfection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated endoscope OEMs commanding hospital procurement through bundled reprocessing ecosystems while independent chemistry suppliers serve price-sensitive outpatient settings. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with disinfection divisions, pure-play sterilization equipment specialists, and regional contract manufacturers serving emerging markets. Consolidation pressures intensify as procurement departments demand single-source accountability spanning disinfectors, chemistries, and validation documentation.
Among diversified medical technology conglomerates, STERIS and Olympus Corporation anchor the premium equipment tier through integrated washer-disinfector portfolios tied to broader endoscope ecosystems. Nanosonics occupies a specialized position with hydrogen peroxide mist technology originally validated for ultrasound probe disinfection, now extending clinical evidence into gastrointestinal endoscope applications. These three companies exemplify divergent competitive vectors: chemistry-anchored recurring revenue models, hardware-ecosystem lock-in strategies, and technology crossover from adjacent diagnostic modalities.
| Leading Market Players |
|---|
| STERIS |
| Olympus Corporation |
| GE HealthCare |
| Philips Healthcare |
| Nanosonics |
| Tristel Plc |
| Germitec |
| CIVCO Medical Solutions |
| CS Medical LLC |
| Others |
Pricing and Supply Chain Analysis
Sterile processing technician concentrations in Germany's Bavaria region and India's Maharashtra state create labor-cost differentials that spread pricing tiers between premium MDR-validated automated systems and economy manual chemistry platforms.
Pricing Analysis
Volume concentration in automated disinfector procurement splits from margin capture in proprietary chemistry subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automated systems with full traceability from basic manual immersion setups. Cost compression in economy tiers intensifies because independent ambulatory centers negotiate aggressively on per-cycle consumables. Diagnostic laboratories and small outpatient clinics exhibit highest price sensitivity, while German university hospitals absorb premium pricing for liability protection.
Supply Chain Analysis
Direct-to-OEM channels handle hospital system demand for integrated washer-disinfector ecosystems, while independent distributors serve price-sensitive outpatient clinics. Manufacturing concentrates in Germany, Japan, and the United States for precision automated equipment, with India and China supplying manual chemistry components and contract assembly. Stainless steel enclosures, peracetic acid precursors, and microprocessor control systems constitute critical input dependencies. Single-source vulnerability in EPA-registered disinfectant formulations creates supply risk if emission regulations force reformulation cycles. Distribution runs through GPO contracts for hospital networks and direct sales for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA and MDR validation burdens force capital-constrained manual chemistry suppliers toward exit or acquisition by automated equipment platforms.
For Market Incumbents: Anchor recurring revenue through proprietary chemistry lock-in tied to automated processor installed bases. Deepen backward integration into peracetic acid manufacturing to neutralize EPA emission scrutiny. Defend against electrolyzed water substitution by accelerating clinical validation documentation for established chemistries. For New Entrants and Emerging Players: Hydrogen peroxide mist technology validated in ultrasound probe applications offers crossover entry into gastrointestinal endoscope niches with lower regulatory burden than novel chemistry development. Target India's centralized reprocessing facility buildout in Mumbai and Delhi satellite clinic networks. Pursue leasing-based go-to-market models that bypass capital intensity barriers constraining independent ambulatory centers. For Investors and Strategic Acquirers: Re-rating potential sits with automated equipment specialists possessing MDR technical documentation libraries given compliance deadline acceleration across European facilities. Long-term viability favors platforms combining hardware, chemistry, and cloud-based audit trail software. Monitor EPA peracetic acid emission rulemaking timelines as inflection indicator for chemistry supplier distress opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates market access for automated disinfectors in German and French hospital procurement cycles. |
| Proprietary Chemistry Platform Development | Creates recurring revenue streams that offset capital equipment margin pressure from consolidated GPO contracts. |
| Electrolyzed Water System Pilot Expansion | Eliminates chemical storage hazards for Veterans Affairs hospitals seeking ventilation infrastructure cost reduction. |
| Centralized Reprocessing Facility Partnership | Captures volume concentration in India's private hospital chain satellite clinic networks. |
| Cloud-Based Cycle Documentation Integration | Aligns disinfector portfolios with EU CSRD traceability mandates creating procurement preference. |
Research Methodology
Document review covered FDA 510(k) filings, EPA antimicrobial pesticide registrations, and EU MDR technical documentation databases, complemented by interviews with sterile processing department managers, biomedical engineers, hospital GPO contract specialists, and automated disinfector field service technicians. Secondary validation drew from hospital procurement database extracts, GPO contract award notices, and customs trade records for disinfection equipment imports. Bottom-up facility-level equipment counts triangulated against top-down manufacturer shipment disclosures.
Segment-level outputs across product type, disinfection method, end user, and application area dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from logistic diffusion curves fitted to automated system replacement cycles and ambulatory surgical center expansion trajectories. Model inputs incorporated MDR compliance deadline schedules, EPA emission rulemaking timelines, and outpatient procedure volume growth assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EPA chemistry restrictions or delayed MDR enforcement harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.