
 Global Colonoscopy Devices Market | 2026-2036
Global Colonoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colonoscopy Devices Market Foresight
Software-defined imaging analytics is repositioning what hospitals purchase during capital equipment cycles. Olympus Corporation leverages its installed base of endoscopy systems to sustain recurring revenue from proprietary image enhancement modules. FUJIFILM Holdings Corporation anchors its competitive stance through in-house sensor manufacturing that controls cost structures across video colonoscope lines. Medtronic plc differentiates by operating a parallel disposable endoscope portfolio that navigates reprocessing liability concerns in ambulatory settings.
Colonoscopy devices are flexible or rigid optical instruments, typically 130-160 cm in working length with distal tip angulation exceeding 180 degrees, designed for direct visualization and intervention within the lower gastrointestinal tract. Their primary commercial purpose centers on enabling tissue diagnosis, polypectomy, and cancer screening procedures that reduce mortality through early detection. Video colonoscopes command the dominant share of product-type revenue pools, while narrow band imaging technology expands fastest as clinicians prioritize vascular pattern recognition for dysplasia identification. Therapeutic applications now attract disproportionate capital allocation compared to screening, reflecting procedural reimbursement differentials across outpatient settings.
The FDA enforces reprocessing validation requirements under 21 CFR 820 quality system regulations, compelling manufacturers to invest in closed-loop drying and automated cleaning technologies. EMA's Medical Device Regulation mandates clinical evidence standards for colonoscope design modifications, lengthening approval timelines for next-generation platforms. ISO 13485 certification serves as a baseline market-access threshold across all major jurisdictions, filtering out suppliers lacking documented quality management systems. Stakeholders must weigh single-use economics against durable equipment lifecycle costs as sterilization standards tighten and liability frameworks evolve.
Market Dynamics
Reprocessing liability exposure is compressing capital equipment replacement cycles as ambulatory surgery centers abandon reusable flexible endoscopes for single-use alternatives. FDA enforcement actions against inadequate sterilization protocols have intensified since 2021, accelerating portfolio reconfiguration across outpatient networks.
Growth Catalysts
- Statutory screening mandates:Germany's statutory health insurance funds cover preventive colonoscopy starting at age 50, creating predictable procedure volume pipelines that stabilize equipment procurement forecasts for hospital outpatient departments.
- Image enhancement modules:Narrow band imaging technology enables real-time vascular pattern recognition, reducing biopsy sampling error rates and justifying premium pricing for video colonoscope upgrades.
- Ambulatory expansion:United States hospital outpatient departments are expanding dedicated endoscopy suites to accommodate colorectal cancer screening backlogs accumulated during 2020-2021 service disruptions.
Market Restraints
- Reprocessing validation costs:FDA 21 CFR 820 quality system regulations mandate closed-loop drying and automated cleaning technology investments that inflate per-unit manufacturing costs for reusable platforms.
- Sensor supply concentration:CMOS image sensor fabrication concentrates in East Asian foundries, exposing colonoscope manufacturers to geopolitical supply interruptions and input cost volatility.
- Single-use economics:Disposable endoscope per-procedure costs exceed reusable equipment lifecycle amortization by 3-4x in high-volume settings, limiting penetration to liability-sensitive ambulatory environments.
Strategic Opportunities
- Underpenetrated screening pools:India's national cancer screening program targets 100 million adults for colorectal examination by 2030, creating demand for cost-optimized video colonoscope platforms suited to district hospital budgets.
- AI-assisted polyp detection:Convolutional neural networks integrated into endoscopy video processors reduce adenoma miss rates, enabling premium positioning for next-generation visualization systems.
- Disposable component hybrids:Modular designs separating reusable control bodies from single-use insertion tubes navigate reprocessing liability while preserving capital equipment margins.
Industry Challenges
- Technician certification bottlenecks:Competency validation for automated endoscope reprocessors extends deployment timelines by 6-12 months in multi-site health systems.
- Legacy system integration:Proprietary video processor architectures from incumbent manufacturers lock ambulatory centers into incompatible upgrade paths, fragmenting purchasing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colonoscopy Devices Market |
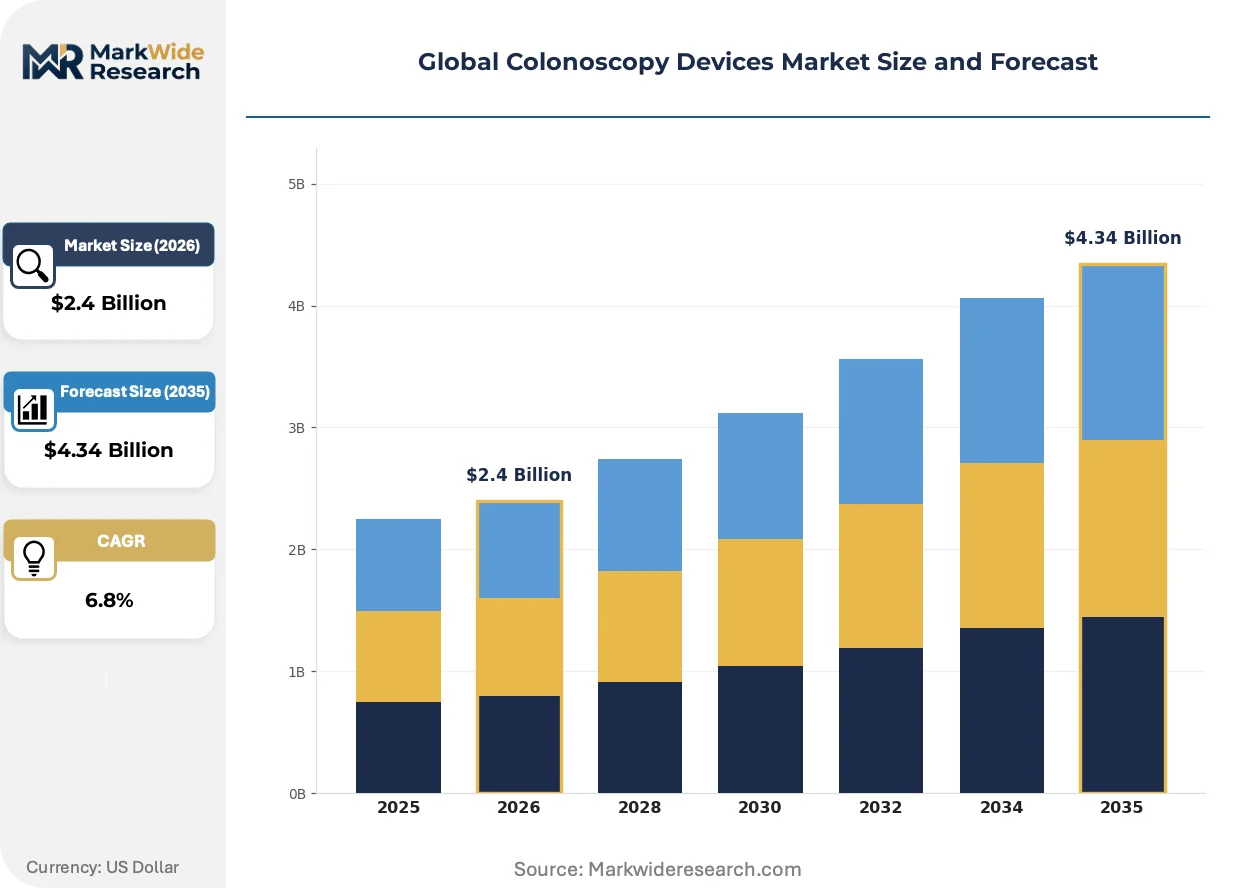
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Colonoscopes, Rigid Colonoscopes, Pediatric Colonoscopes, Video Colonoscopes Technology: Optical Imaging, Narrow Band Imaging, Chromoendoscopy, Autofluorescence Imaging Application: Screening, Detection, Therapeutic Procedures, Biopsy Collection End User: Ambulatory Surgery Centers, Diagnostic Labs, Specialty Clinics, Research Institutes |
| Companies Covered | Olympus Corporation, FUJIFILM Holdings Corporation, Medtronic plc, HOYA Corporation, KARL STORZ SE & Co. KG, Boston Scientific Corporation, Avantis Medical Systems, Endomed Systems GmbH, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colonoscopy Devices Market Shifts & Advancements
Software-defined functionality is displacing hardware-centric product architectures across the colonoscopy device value chain. Image processing, diagnostic assistance, and procedural documentation increasingly reside in upgradeable software layers rather than fixed optical or mechanical systems.
Capacitive micromachined ultrasonic transducer arrays are electrifying endoscopic ultrasound guidance for submucosal lesion characterization. Gastroenterology departments at tertiary referral hospitals in Germany and Japan are adopting these platforms for pancreaticobiliary staging. The technology is electrifying competitive positioning by collapsing the distinction between diagnostic colonoscopy and interventional endosonography, forcing equipment suppliers to bundle ultrasound capability into base video colonoscope configurations.
EMA's Medical Device Regulation mandates clinical evidence standards for design modifications, extending approval timelines for next-generation platforms. Manufacturers must submit prospective data for tip angulation improvements or insertion tube flexibility enhancements previously cleared through predicate equivalence. European notified bodies are prioritizing submissions from suppliers with established quality management systems, advantaging ISO 13485-certified incumbents over emerging competitors.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, compressing vendor margins on installation and maintenance. Group purchasing organizations in the United States are negotiating multi-year service agreements separately from device acquisition, transferring technical training and repair liability to third-party clinical engineering firms. This disintermediation is most visible in integrated delivery networks consolidating endoscopy service lines across 10+ ambulatory sites.
Global Colonoscopy Devices Market Segmentation
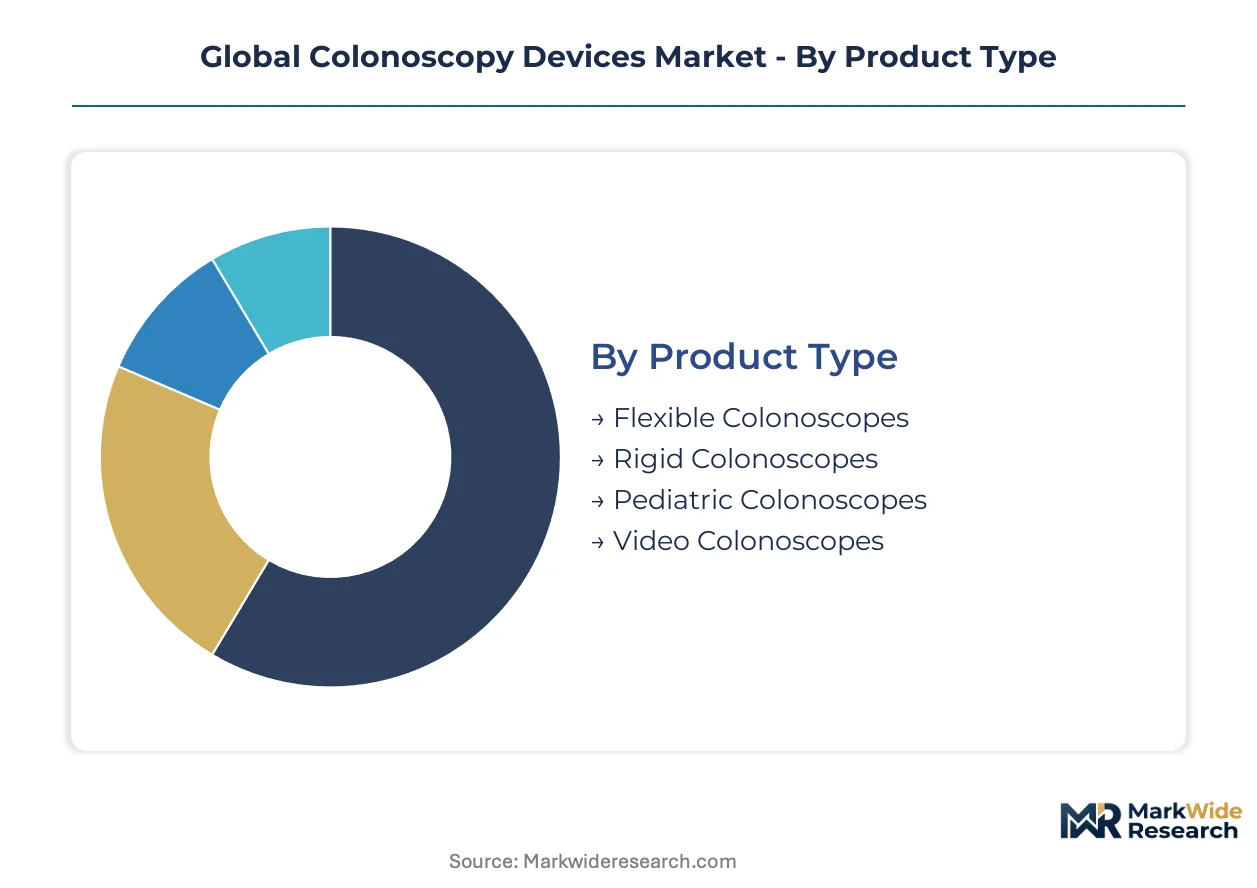
Segmentation in colonoscopy devices tracks how capital equipment cycles, liability pressures, and reimbursement differentials reshape purchasing patterns across hospital systems and outpatient networks. Understanding these divides clarifies where manufacturers must defend installed bases versus where single-use alternatives can penetrate.
Product Type:
Upgrade and replacement cycles in this category hinge on reprocessing liability exposure and the amortization economics of reusable platforms against disposable alternatives.
- Flexible Colonoscopes:These instruments employ fiberoptic or video transmission through a steerable insertion tube with distal tip angulation exceeding 180 degrees. Demand concentrates in United States hospital outpatient departments expanding endoscopy suites to clear colorectal cancer screening backlogs accumulated during 2020-2021 service disruptions.
- Video Colonoscopes:CMOS or CCD sensor-based systems deliver high-definition visualization through proprietary processor architectures that lock ambulatory centers into vendor-specific upgrade paths. Germany's statutory health insurance funds covering preventive colonoscopy from age 50 stabilize procurement forecasts for these capital-intensive platforms in European hospital systems.
- Rigid Colonoscopes:Stainless steel instruments with fixed optical pathways serve limited diagnostic niches in anorectal examination where flexible navigation is unnecessary.
- Pediatric Colonoscopes:Reduced-diameter insertion tubes accommodate neonatal through adolescent anatomy, with procurement concentrated in tertiary children's hospitals.
Video colonoscopes sit at the top of the volume ranking, with flexible colonoscopes climbing the fastest as facilities balance reprocessing investments against single-use migration.
Technology:
Cost tier differentiation in imaging modalities separates premium vascular-pattern recognition systems from standard white-light platforms, with reimbursement for advanced detection driving capital allocation.
- Narrow Band Imaging:Spectral filtering at 415nm and 540nm wavelengths enhances mucosal vascular contrast, enabling real-time dysplasia identification without dye spraying. United States ambulatory surgery centers prioritize this technology to reduce adenoma miss rates and justify premium procedural reimbursement.
- Optical Imaging:Conventional white-light systems remain the baseline configuration across cost-sensitive procurement in India's district hospital networks targeted by national cancer screening expansion.
- Chromoendoscopy:Topical dye application techniques require minimal capital investment but extend procedure duration, limiting adoption to academic medical centers with research mandates.
- Autofluorescence Imaging:Tissue autofluorescence detection of metabolic shifts in neoplastic mucosa offers alternative contrast mechanisms, with clinical validation concentrated in Japanese tertiary referral hospitals.
Optical imaging retains the largest installed base, though narrow band imaging gains share fastest where detection accuracy drives reimbursement differentiation.
Application:
Volume concentration across procedural categories reflects reimbursement spreads between screening and interventional codes, with therapeutic margins attracting disproportionate capital deployment.
- Screening:Asymptomatic colorectal cancer prevention procedures generate the highest annual case volumes but face compressed reimbursement rates that extend equipment replacement cycles. Germany's population-wide coverage mandate from age 50 creates predictable demand pipelines stabilizing procurement planning.
- Therapeutic Procedures:Polypectomy, endoscopic mucosal resection, and hemostasis interventions command premium reimbursement differentials that accelerate capital refresh cycles in United States outpatient settings.
- Detection:Diagnostic examination with biopsy sampling occupies an intermediate reimbursement tier, with AI-assisted polyp detection systems repositioning equipment specifications toward software-defined capability.
- Biopsy Collection:Forceps-based tissue acquisition represents a procedural subcomponent rather than standalone application, with instrument demand tied to broader examination volumes.
Screening dominates procedure counts, while therapeutic applications expand most quickly where reimbursement premiums justify technology investment.
End User:
Customer type segmentation tracks how liability frameworks and economies of scale fragment purchasing authority across integrated delivery networks versus independent ambulatory sites.
- Ambulatory Surgery Centers:Freestanding outpatient facilities face acute reprocessing liability exposure under FDA enforcement intensification since 2021, accelerating abandonment of reusable flexible endoscopes for single-use alternatives despite 3-4x per-procedure cost premiums.
- Specialty Clinics:Gastroenterology-focused practices concentrate procedure volume sufficient to amortize automated endoscope reprocessor investments across high utilization rates.
- Diagnostic Labs:Pathology-focused facilities with limited procedural capability represent peripheral demand concentrated in specimen handling accessories rather than capital equipment.
- Research Institutes:Academic medical centers drive early adoption of CMUT array endoscopic ultrasound platforms for pancreaticobiliary staging, with procurement cycles tied to grant funding rather than clinical reimbursement.
Ambulatory surgery centers lead capital reconfiguration, with specialty clinics maintaining the steepest expansion trajectory as group purchasing organizations consolidate procurement across multi-site networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as reprocessing compliance costs diverge sharply across jurisdictions. Single-use device producers are migrating assembly toward regions with streamlined medical device quality system requirements, while reusable platform manufacturers concentrate in established regulatory clusters where predicate device pathways accelerate iterative approvals.
United States
Hospital outpatient departments in Texas and Florida are expanding endoscopy suite capacity to clear screening backlogs accumulated during 2020-2021 service disruptions. FDA enforcement actions under 21 CFR 820 since 2021 have intensified reprocessing validation requirements, accelerating ambulatory surgery center migration toward disposable alternatives. The Minneapolis-St. Paul corridor hosts concentrated automated endoscope reprocessor manufacturing as third-party clinical engineering firms consolidate multi-site service contracts.
Germany
Statutory health insurance funds covering preventive colonoscopy from age 50 generate predictable procedure volume pipelines stabilizing procurement forecasts for hospital systems. EMA Medical Device Regulation mandates clinical evidence standards for design modifications, extending approval timelines for next-generation platforms through notified bodies in Berlin and Munich. The Tuttlingen surgical instrument cluster anchors reusable flexible endoscope production, with manufacturers integrating closed-loop drying technologies to satisfy tightened sterilization standards.
Japan
Tertiary referral hospitals in Tokyo and Osaka are adopting capacitive micromachined ultrasonic transducer arrays for pancreaticobiliary staging, collapsing the distinction between diagnostic colonoscopy and interventional endosonography. PMDA quality system regulations align with international harmonization initiatives, though domestic clinical trial requirements persist for novel imaging modalities. The Nagoya medical device manufacturing corridor supplies precision optical components for video colonoscope sensor assemblies serving Asia-Pacific demand.
India
The national cancer screening program targeting 100 million adults for colorectal examination by 2030 creates demand for cost-optimized video colonoscope platforms suited to district hospital budgets. CDSCO medical device rules classify endoscopes by risk category, with streamlined pathways for established predicate devices accelerating market entry for Korean and Japanese exporters. The Hyderabad-Visakhapatnam corridor is emerging as a contract manufacturing hub for disposable insertion tube components serving global OEMs.
China
Domestic manufacturers are capturing share in standard-definition video colonoscope segments as NMPA quality system regulations mature toward international convergence. The Yangtze River Delta medical device cluster in Jiangsu and Zhejiang provinces concentrates CMOS image sensor packaging capacity, though advanced sensor fabrication remains import-dependent. Shanghai-based hospital procurement groups are negotiating bundled service contracts that separate capital equipment acquisition from maintenance, compressing vendor margins on installation and technical training.
Global Colonoscopy Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated endoscopy system vendors defending installed bases through proprietary processor architectures while disposable device assemblers compete on unit economics and liability mitigation. The market structure concentrates around three strategic archetypes: diversified medical technology conglomerates with parallel reusable and single-use portfolios; pure-play endoscopy specialists leveraging image enhancement software for recurring revenue; and regional contract manufacturers supplying insertion tube components and sterilization accessories. Dominant competitive moves include portfolio diversification into disposable alternatives and strategic partnerships with automated reprocessor vendors to bundle compliance solutions.
Within the diversified conglomerate tier, Olympus Corporation and FUJIFILM Holdings Corporation occupy positions defined by vertical control over critical supply chain segments—Olympus through its installed base of endoscopy systems sustaining proprietary image enhancement module revenue, FUJIFILM through in-house sensor manufacturing governing cost structures across video colonoscope lines. Medtronic plc exemplifies the parallel-portfolio approach, with its disposable endoscope range addressing reprocessing liability concerns in ambulatory settings while maintaining reusable platform relationships with hospital outpatient departments. These three Tokyo- and Dublin-based entities anchor competitive dynamics through divergent responses to regulatory pressure on sterilization protocols.
| Leading Market Players |
|---|
| Olympus Corporation |
| FUJIFILM Holdings Corporation |
| Medtronic plc |
| HOYA Corporation |
| KARL STORZ SE & Co. KG |
| Boston Scientific Corporation |
| Avantis Medical Systems |
| Endomed Systems GmbH |
| Getinge AB |
| Others |
Supply & Pricing Matrix
Captive CMOS sensor fabrication by Japanese and Korean conglomerates anchors both supply security and premium pricing power for video colonoscope platforms. This upstream control insulates tier-one manufacturers from input cost volatility while forcing smaller competitors toward spot-market sensor procurement that compresses their margin structures.
Pricing Analysis
Distributor margins on reusable flexible colonoscopes typically absorb 15-25% of end-user price before hospital procurement committees negotiate direct-OEM contracts. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced visualization systems from conventional white-light platforms and refurbished legacy equipment. Cost compression in the economy tier is intensifying because Indian district hospitals and Southeast Asian clinics prioritize acquisition cost over software functionality. Ambulatory surgery centers exhibit highest price sensitivity due to per-procedure margin pressures, while German hospital systems demonstrate lowest sensitivity given statutory reimbursement stability.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital purchasing committees mandate qualified suppliers for both CMOS image sensors and flexible insertion tube materials across at least two distinct geographies. Component fabrication concentrates in Japan, South Korea, and Germany, with precision optical assemblies drawing from Nagoya-area manufacturers and polymer extrusion feeding from Tuttlingen surgical instrument clusters. Supply chain risk centers on single-source vulnerability for advanced CMOS sensors fabricated at East Asian foundries. Distribution runs through specialized medical device distributors serving integrated delivery networks, with direct-to-hospital contracts gaining share among systems operating 10+ endoscopy suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colonoscopy devices market functions as a stable compounder anchored by statutory screening mandates that generate predictable procedure volume pipelines across aging populations.
For Market Incumbents: To counter single-use disposable migration in ambulatory settings, deepen software-defined imaging analytics capabilities that lock hospital systems into proprietary upgrade cycles. Prioritize backward integration into automated endoscope reprocessor partnerships that bundle compliance solutions with capital equipment sales, converting liability-driven replacement demand into recurring service revenue. For New Entrants and Emerging Players: Begin with cost-optimized video colonoscope platforms targeting India's national cancer screening program expansion into district hospital networks. White-space concentration exists in pediatric colonoscope segments where reduced-diameter instrument demand outpaces incumbent supply capacity. Pursue regulatory fast-track pathways via CDSCO predicate device equivalence for established Japanese and Korean platform designs. For Investors and Strategic Acquirers: Roll-up economics work for disposable insertion tube component manufacturers because reprocessing liability compression accelerates modular hybrid adoption across ambulatory networks. Platform-rollup viability extends through a 5-10 year window as facilities navigate the transition from reusable to single-use architectures. Monitor FDA enforcement action frequency as the primary inflection indicator for disposable penetration rates versus reusable platform defense.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance accelerates European hospital system procurement approvals for next-generation platforms. |
| Hospital System Partnership | Multi-site service agreements with integrated delivery networks consolidate installed base defense against single-use entrants. |
| Software Companion Development | AI-assisted polyp detection modules justify premium pricing through measurable adenoma miss rate reduction. |
| Reimbursement Strategy | CMS coding alignment for narrow band imaging procedures secures favorable outpatient payment differentials. |
| FDA Submission | 510(k) predicate pathways for disposable component hybrids navigate reprocessing liability while preserving capital margins. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and emerging markets, with primary inputs from each region combined with secondary validation. Interviews engaged hospital purchasing committee directors, gastroenterology department heads, biomedical engineering managers, and GPO contracts specialists. Secondary sources included FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates.
Granularity-level modeling deployed product-type, technology modality, application category, and end-user archetype dimensions across the projection horizon. CAGRs derived from procedure volume growth trajectories weighted by equipment replacement cycle assumptions. Forecast inputs incorporated statutory screening mandate expansion timelines, reprocessing regulatory enforcement intensity, and sensor supply concentration risk assessments.
Several conditions sit outside the modeled scope, including unforeseen pandemic-related service disruptions, abrupt tariff regime shifts affecting East Asian sensor imports, and breakthrough non-colonoscopic screening technology adoption. Deviation in FDA reprocessing enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Endoscopy Device Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Gastroscopes Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Global Endoscopes Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Global Endoscopy Ultrasound Market